
 Enterprise Network Infrastructure Market | 2026-2036
Enterprise Network Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Network Infrastructure Market Intelligence
Software-defined subscription layers is broadening what enterprises purchase as capital equipment gives way to recurring network-as-a-service arrangements. Cisco Systems leverages its installed base to anchor multi-year SaaS contracts across campus and data center environments. Arista Networks specializes in high-density 400G switching for cloud-scale data centers, sustaining R&D intensity that outpaces legacy hardware competitors.
Enterprise network infrastructure comprises the physical and virtual systems—routers, switches, firewalls, access points, and their control planes—that transport, secure, and manage data traffic across organizational boundaries, typically operating at Layer 2 through Layer 4 with throughput specifications ranging from 1 Gbps edge ports to 51.2 Tbps chassis-based core switches. Its primary commercial purpose is to guarantee application availability, enforce security segmentation, and enable workforce mobility across distributed sites. Switches occupy the deepest margin pools as refresh cycles compress to three-year intervals under bandwidth pressure from AI workloads. SD-WAN within the technology dimension is displacing MPLS in mid-market deployments, though Ethernet retains dominance in campus aggregation due to IEEE 802.3bt power delivery requirements for IoT endpoints.
The FCC governs unlicensed spectrum access and equipment authorization, while the ETSI NFV framework shapes European procurement specifications for virtualized network functions, and NIST cybersecurity guidelines mandate zero-trust architecture reviews for federal contractors. These frameworks collectively elevate compliance costs for entrants while privileging vendors with pre-certified product portfolios and in-house regulatory affairs teams. Stakeholders must monitor how spectrum auction outcomes and encryption export controls reshape hardware sourcing strategies before their next platform refresh cycle.
Market Dynamics
AI workload density is compressing campus refresh cycles from five years to three, forcing enterprises to absorb upfront capital outlays for 400G-capable switching fabric before depreciation schedules mature.
Growth Catalysts
- Wi-Fi 6E spectrum allocation:The FCC's 6 GHz band reallocation enables 1,200 MHz of contiguous unlicensed spectrum, triggering access point replacement waves across healthcare and education campuses.
- Industrial automation clusters:German smart factory deployments require deterministic Ethernet backbones with sub-millisecond latency guarantees for robotic coordination.
- Zero-trust architecture mandates:NIST cybersecurity guidelines for federal contractors compel segmentation upgrades that retrofit microperimeters into legacy three-tier designs.
Market Restraints
- Silicon supply concentration:Advanced switching ASIC fabrication concentrates at TSMC's leading-edge nodes, exposing procurement timelines to geopolitical foundry access risks.
- Copper and optical transceiver cost volatility:800G pluggable module prices fluctuate with rare earth element availability and laser diode yield rates.
- MPLS substitution friction:SD-WAN underlay performance gaps persist for jitter-sensitive financial trading applications, delaying full retirement of leased-line contracts.
Strategic Opportunities
- Network-as-a-service penetration:Subscription consumption models open mid-market segments previously priced out of enterprise-grade security and analytics stacks.
- Private 5G campus integration:CBRS spectrum licenses in the United States allow manufacturing facilities to bypass carrier dependency for mobile robotics control.
- ETSI NFV procurement specifications:European virtualized network function mandates create certified vendor lists that advantage pre-integrated hardware-software portfolios.
Industry Challenges
- Intent-based networking skill scarcity:NetDevOps automation requires Python and YANG modeling competencies absent from traditional CLI-trained engineering cohorts.
- Multi-vendor orchestration complexity:API fragmentation between switching, wireless, and security domains extends integration timelines and elevates professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Network Infrastructure Market |
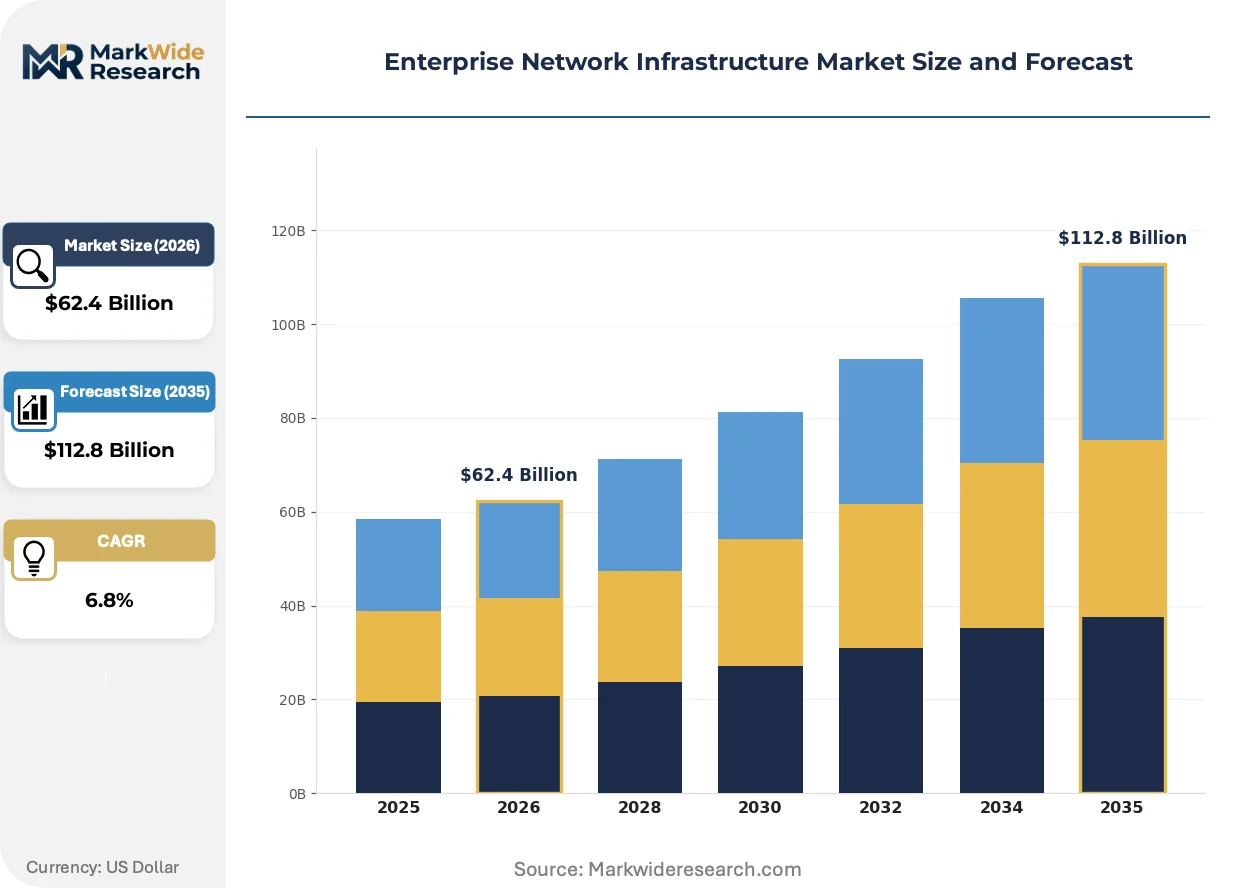
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Switches, Firewalls, Access Points Delivery Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Enterprises, SMBs, Government, Educational Institutions Technology: Ethernet, Wi-Fi, MPLS, SD-WAN |
| Companies Covered | Extreme Networks, Lumen Technologies, Hewlett Packard Enterprise, Alkira, Meter, Cisco Systems, Arista Networks, Megaport, Juniper Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Network Infrastructure Market Strategic Shifts & Innovations
Operational technology and information technology network boundaries are dissolving as manufacturing floors demand IP-native connectivity for sensor-to-cloud telemetry pipelines.
Silicon photonics is converging with co-packaged optics to collapse power-per-bit metrics in data center interconnects. Hyperscale operators are deploying 51.2 Tbps chassis with embedded optical engines to eliminate discrete transceiver modules. This convergence is compressing physical layer component counts while extending reach beyond copper's thermal limitations.
The EU AI Act's risk-based classification system imposes documentation and audit obligations on network infrastructure supporting high-risk automated decision systems. Equipment vendors must now provide model cards for embedded machine learning functions in security appliances. European financial services and healthcare verticals are prioritizing vendors with pre-submitted conformity assessments to accelerate procurement timelines.
Capital equipment purchasing is fragmenting into hybrid ownership models where enterprises retain physical layer assets while outsourcing control plane operations. Managed SD-WAN providers are absorbing policy orchestration and threat intelligence functions previously staffed internally. This unbundling is most pronounced in North American retail and distributed logistics networks where IT headcount constraints outpace bandwidth requirements.
Enterprise Network Infrastructure Market Segmentation
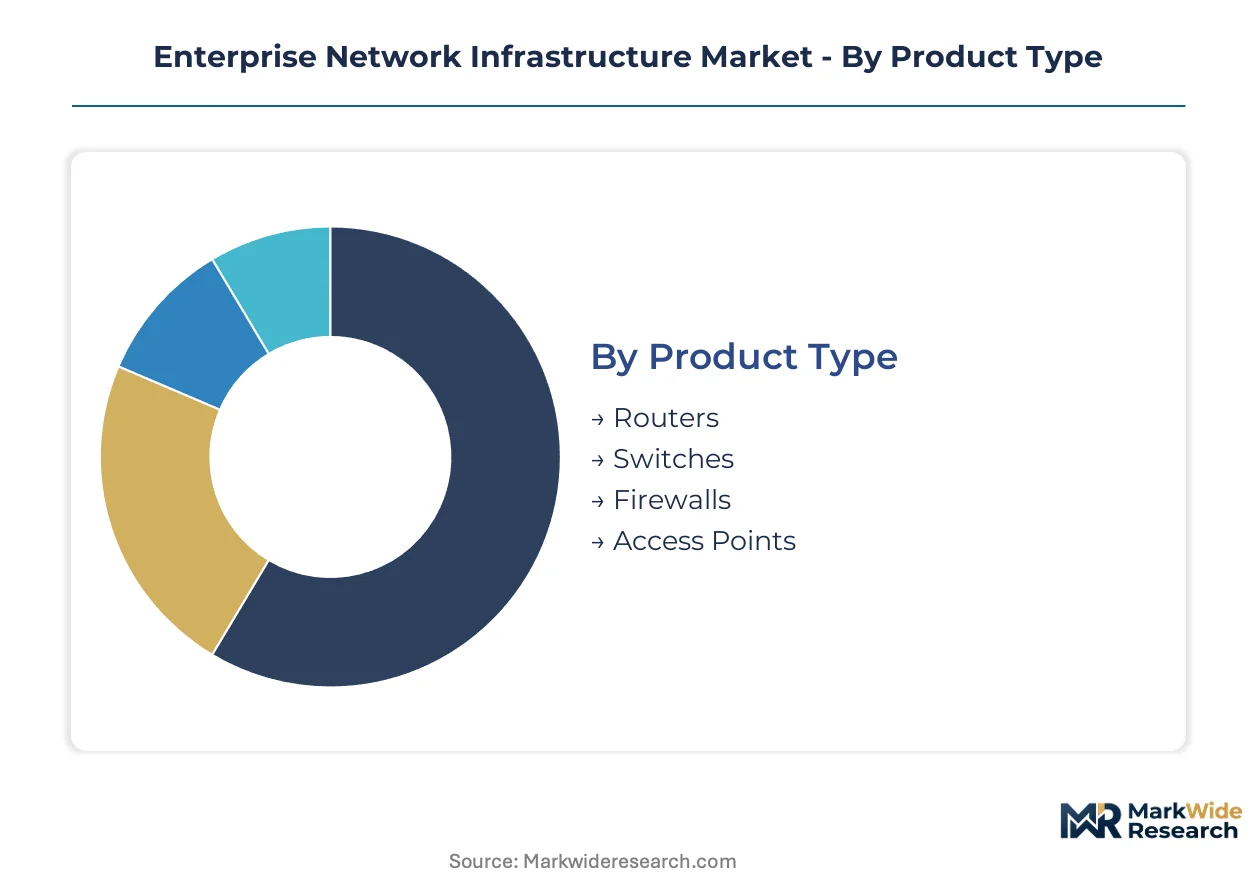
Segmentation in enterprise network infrastructure reveals how procurement priorities diverge across deployment scales and operational models. Understanding these divides exposes where vendor margins concentrate and which technology transitions face adoption friction.
Product Type:
Supply concentration in merchant silicon foundries favors vendors with direct TSMC allocation for advanced switching ASICs.
- Switches:Layer 2 through Layer 4 chassis and fixed-configuration units process traffic from 1 Gbps edge ports to 51.2 Tbps core fabrics. Financial services firms in New York and London compress refresh cycles to three years under AI workload pressure, prioritizing 400G-capable backplane density.
- Routers:Border and core routing platforms execute path selection across autonomous systems using BGP, OSPF, and segment routing protocols. Telecom operators in Germany require deterministic latency guarantees for industrial automation backbones, driving demand for time-sensitive networking extensions.
- Firewalls:Stateful inspection and next-generation platforms enforce segmentation policies with application-layer visibility.
- Access Points:Wi-Fi 6, 6E, and 7 radios deliver campus coverage with OFDMA and MU-MIMO efficiency gains.
Today's leader: Switches. Tomorrow's challenger: Access Points.
Delivery Model:
Cost tier stratification separates capital-intensive ownership from operating-expense flexibility across enterprise IT budgets.
- Managed Services:Third-party providers assume responsibility for monitoring, patching, and policy orchestration through SLAs. Mid-market retailers in the United States bypass internal NetDevOps hiring constraints by outsourcing control plane operations to specialized providers.
- Cloud-Based:Controller and analytics functions run from hyperscale infrastructure while physical edge devices remain on-site. Healthcare systems in Singapore centralize policy management across distributed clinics without maintaining regional data center footprints.
- On-Premises:Full hardware and software ownership with internal operational responsibility.
- Hybrid:Split architectures retaining sensitive control functions locally while leveraging cloud analytics.
Managed Services commands current procurement volume. Cloud-Based delivery gains fastest among regulated verticals seeking audit trail centralization.
End User:
Application intensity varies sharply between latency-sensitive trading floors and bandwidth-elastic remote work deployments.
- Enterprises:Large organizations with multi-site footprints require 99.999% availability architectures and microsegmentation for zero-trust compliance. Federal contractors in the United States face NIST-mandated architecture reviews that accelerate segmentation upgrade timelines.
- Government:National and local agencies mandate FIPS 140-2 encryption and continuous monitoring under binding operational directives.
- SMBs:Resource-constrained organizations prioritize simplified management interfaces and subscription consumption models.
- Educational Institutions:Universities and K-12 districts manage extreme density swings between semester schedules and residential coverage.
Enterprises dominate current infrastructure spend. Government verticals show steepest expansion trajectory under cybersecurity mandate acceleration.
Technology:
Customer type fragmentation separates campus aggregation standards from WAN transformation priorities.
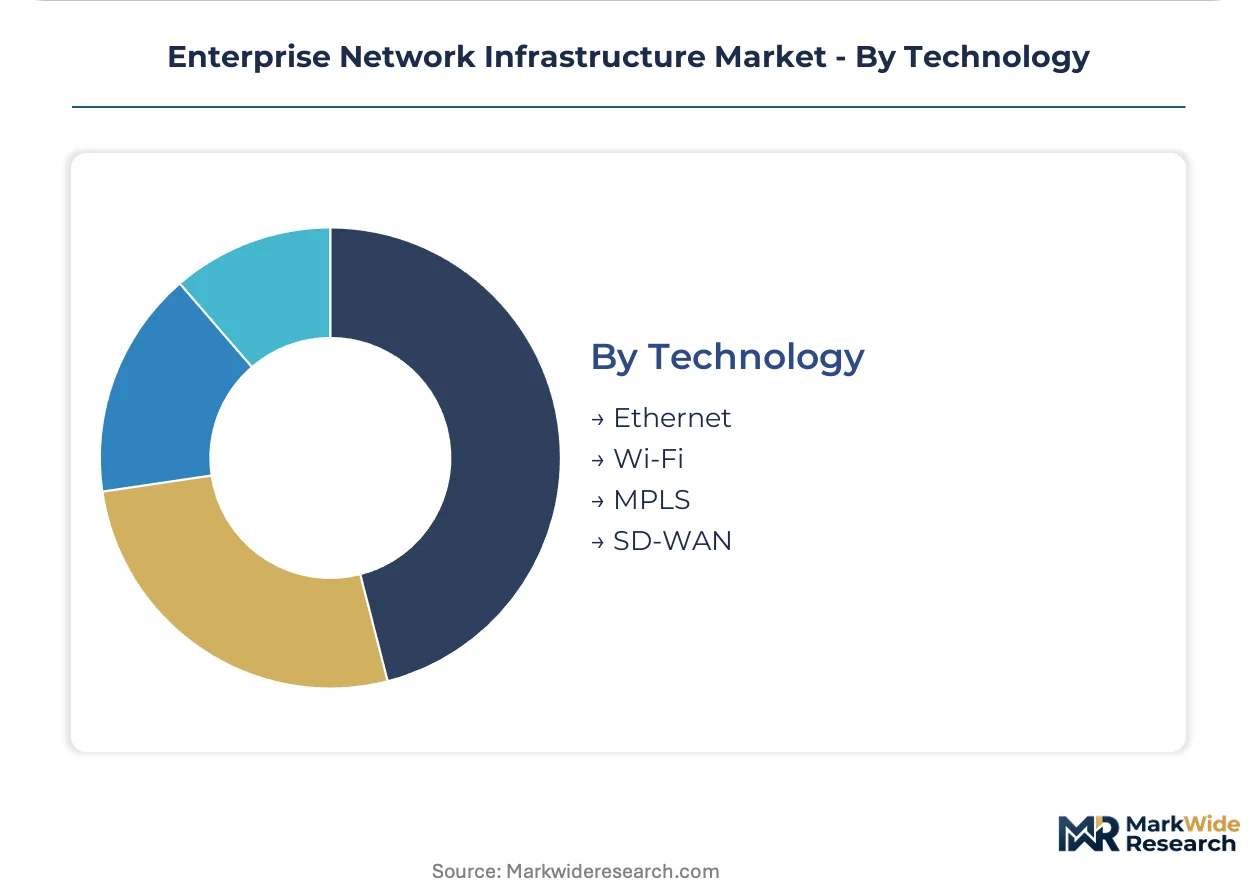
- SD-WAN:Software-defined overlays abstract transport independence across broadband, LTE, and MPLS underlays. Mid-market manufacturers in the United States deploy CBRS-integrated private backhaul to bypass carrier dependency for mobile robotics control.
- Ethernet:IEEE 802.3 standards dominate campus aggregation with Power over Ethernet Plus (PoE++) delivering 90W for IoT endpoints. Smart factory deployments in Stuttgart require IEEE 802.1Qbv time-aware scheduling for robotic coordination.
- Wi-Fi:Unlicensed spectrum access enables workforce mobility and guest connectivity across enterprise campuses.
- MPLS:Leased-line private routing persists in financial trading applications where jitter tolerance measures below one millisecond.
Ethernet anchors campus infrastructure today. SD-WAN represents the fastest-climbing challenger as MPLS contract retirements accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting procurement flows toward jurisdictions with streamlined equipment authorization pathways. Vendors pre-certify portfolios in the United States to accelerate European market entry under mutual recognition agreements.
United States
Federal contractors drive segmentation upgrades under NIST zero-trust mandates. The FCC's 6 GHz spectrum reallocation triggers access point replacement waves across healthcare and education campuses. New York financial services firms compress refresh cycles to three years for AI workload support.
Germany
Industrial automation clusters demand deterministic Ethernet backbones with sub-millisecond latency guarantees. ETSI NFV procurement specifications create certified vendor lists favoring pre-integrated hardware-software portfolios. Stuttgart smart factory deployments require IEEE 802.1Qbv time-aware scheduling for robotic coordination.
China
Domestic cloud operators deploy 51.2 Tbps chassis with embedded optical engines to eliminate discrete transceiver modules. MIIT standards govern equipment authorization timelines for campus and data center infrastructure. Yangtze River Delta manufacturing hubs prioritize captive silicon supply chains for switching ASICs.
Japan
Enterprise IT budgets concentrate in Tokyo-Osaka corridor for 400G-capable core switching fabric. METI industrial policy shapes procurement specifications for virtualized network functions. Kanto region financial institutions maintain MPLS underlays for jitter-sensitive trading applications.
Singapore
Healthcare systems centralize policy management across distributed clinics without regional data center footprints. TRAI-equivalent regulations govern cross-border data flows for cloud-based network controllers. Marina Bay financial district demands 99.999% availability architectures with microsegmentation compliance.
Enterprise Network Infrastructure Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments. Campus aggregation tilts toward integrated hardware-software portfolios with recurring revenue attachments. Data center switching favors high-density specialists with direct foundry allocation. Two strategic archetypes dominate: installed-base incumbents anchoring multi-year SaaS contracts, and cloud-scale pure-plays sustaining R&D intensity above legacy competitors. Competitive moves concentrate on subscription model migration and silicon photonics integration.
Within the installed-base tier, Cisco Systems and Hewlett Packard Enterprise exemplify vendors leveraging campus and data center footprints to anchor recurring revenue arrangements. Arista Networks occupies a position among cloud-scale specialists prioritizing high-density switching fabric for hyperscale environments. These three represent divergent strategic postures: one emphasizing subscription conversion, another hardware-software integration, the third pure-play density optimization.
| Leading Market Players |
|---|
| Extreme Networks |
| Lumen Technologies |
| Hewlett Packard Enterprise |
| Alkira |
| Meter |
| Cisco Systems |
| Arista Networks |
| Megaport |
| Juniper Networks |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud operators and federal contractors anchor procurement volume, locking in multi-year SaaS contracts that compress transactional pricing for legacy hardware tiers.
Pricing Analysis
Capacity additions in Taiwan are reshaping price floors for advanced switching ASICs as TSMC's leading-edge nodes expand allocation to merchant silicon vendors. Three-tier pricing structure across premium chassis-based systems, standard fixed-configuration switches, and economy edge ports differentiates on throughput density and power efficiency. Cost compression in mid-market SD-WAN appliances is intensifying because subscription consumption models displace perpetual licensing. Federal contractors show least price sensitivity under NIST mandate deadlines, while educational institutions face acute budget constraints extending refresh cycles.
Supply Chain Analysis
Engineering talent scarcity in Shenzhen and Penang constrains optical transceiver assembly capacity just as 800G module demand accelerates. Merchant silicon fabrication centers on Taiwan, South Korea, and the United States, drawing from rare earth element feedstocks and laser diode components. Single-source vulnerability at TSMC's 3nm node exposes procurement timelines to geopolitical foundry access restrictions. Distribution runs through authorized value-added resellers and direct hyperscale contracts, bypassing traditional distributor tiers for high-density data center fabrics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription conversion and silicon photonics integration expand margin pools as recurring revenue displaces transactional hardware sales and embedded optics eliminate discrete transceiver costs.
For Market Incumbents: Lock in multi-year SaaS contracts across installed campus footprints before Arista Networks and cloud-scale specialists capture data center refresh cycles. Prioritize backward integration into merchant silicon allocation through direct TSMC partnerships to secure leading-edge node access. Certification investment in ETSI NFV pre-integration creates vendor-list advantages in European procurement. For New Entrants and Emerging Players: Launch via managed service provider channels targeting mid-market retailers with IT headcount constraints and compliance-driven segmentation needs. White-space concentrates in private 5G campus integration for manufacturing facilities seeking CBRS-based mobile robotics control. Go-to-market should emphasize NetDevOps automation bundles that bridge skill scarcity in traditional CLI-trained engineering cohorts. For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirers in this space, seeking vertical control over switching fabric and embedded optical engine technology. Long-term viability hinges on subscription revenue mix and direct foundry allocation securing leading-edge silicon access. Monitor FCC spectrum auction outcomes and encryption export control adjustments as inflection indicators for hardware sourcing strategy shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Embedded optical engines in 51.2 Tbps chassis eliminate discrete transceiver modules and collapse power-per-bit metrics. |
| Subscription Model Migration | Network-as-a-service arrangements convert capital equipment purchases into recurring revenue streams across mid-market segments. |
| ETSI NFV Pre-Certification | Pre-integrated hardware-software portfolios secure placement on European certified vendor lists for virtualized network functions. |
| Private 5G Campus Deployment | CBRS spectrum licenses enable manufacturing facilities to bypass carrier dependency for deterministic mobile robotics control. |
| Zero-Trust Architecture Retrofit | Microperimeter segmentation upgrades address NIST cybersecurity mandates for federal contractors under binding operational directives. |
Research Approach
Multiple input streams — structured interviews with network infrastructure procurement officers, technical validation with NetDevOps engineering leads, and financial analysis of hyperscaler capex disclosures — were reconciled against secondary sources including FCC equipment authorization databases, ETSI NFV certification registries, and SEC filings from publicly traded networking vendors. Bottom-up estimates of access point and switching unit deployments were cross-referenced with top-down market sizing derived from carrier and enterprise IT budget allocations.
Historical shipment trajectories were cross-referenced against panel input from distribution channel partners and value-added reseller principals to anchor projection assumptions. Segmentation modeling spanned product type, delivery model, end-user vertical, and technology protocol dimensions across the analysis window. CAGR derivation incorporated AI workload density impacts on refresh cycle compression, Wi-Fi 6E spectrum reallocation timing, and industrial automation cluster expansion in German manufacturing hubs.
Several conditions sit outside the modeled scope, including unannounced foundry capacity expansions, geopolitical restrictions on semiconductor manufacturing equipment exports, and abrupt shifts in federal cybersecurity procurement mandates. Forecasts reflect documented assumptions regarding subscription conversion rates and silicon photonics yield improvements. Material deviation in TSMC node allocation priorities or FCC spectrum auction outcomes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Middle East Data Center Networking Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market