
 Thailand Data Center Networking Market | 2026-2036
Thailand Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Data Center Networking Market Insights
Thailand's Personal Data Protection Act is rebalancing the cost-of-entry calculus for data center operators by mandating localized data governance infrastructure. Cisco Systems Inc. leverages its established channel partnerships to sustain dominance in enterprise switching deployments across Bangkok metro facilities. Huawei Technologies Co. Ltd. competes aggressively on total cost of ownership for state-backed digital economy projects. Arista Networks differentiates through cloud-optimized Ethernet architectures that anchor hyperscale customer relationships in the Eastern Economic Corridor.
Data center networking encompasses the interconnected switching, routing, and security infrastructure that enables compute and storage resource communication within and between facilities, typically operating at speeds from 10 Gbps to 800 Gbps with sub-microsecond latency requirements. Its primary purpose is to maintain deterministic throughput for virtualized workloads, real-time analytics, and distributed cloud services. Switches capture the dominant share of hardware expenditure as spine-leaf architectures displace traditional three-tier designs in Thai facilities. Cloud Providers represent the fastest-growing end-user category as hyperscalers expand local availability zones to satisfy data residency requirements under national law. Ethernet technology leads deployment volumes, though InfiniBand gains traction in AI training clusters emerging near Bangkok.
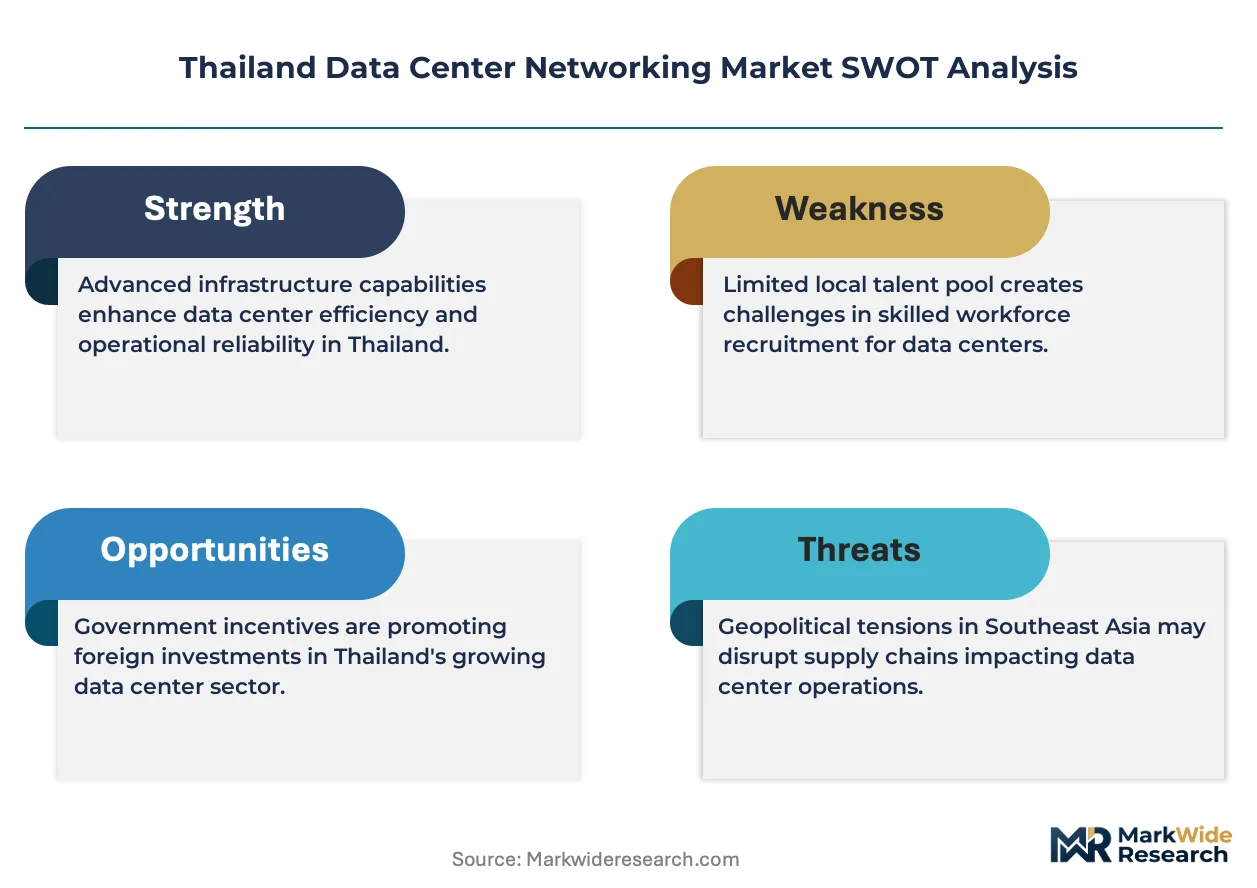
The National Broadcasting and Telecommunications Commission shapes spectrum allocation for wireless data center interconnects, while the Electronic Transactions Development Agency certifies cryptographic standards for network security appliances. BIS-aligned product certification requirements from Thailand's industrial standards body constrain import timelines for non-compliant networking equipment. Stakeholders must monitor evolving localization mandates and decide whether to establish domestic assembly partnerships or absorb extended certification cycles.
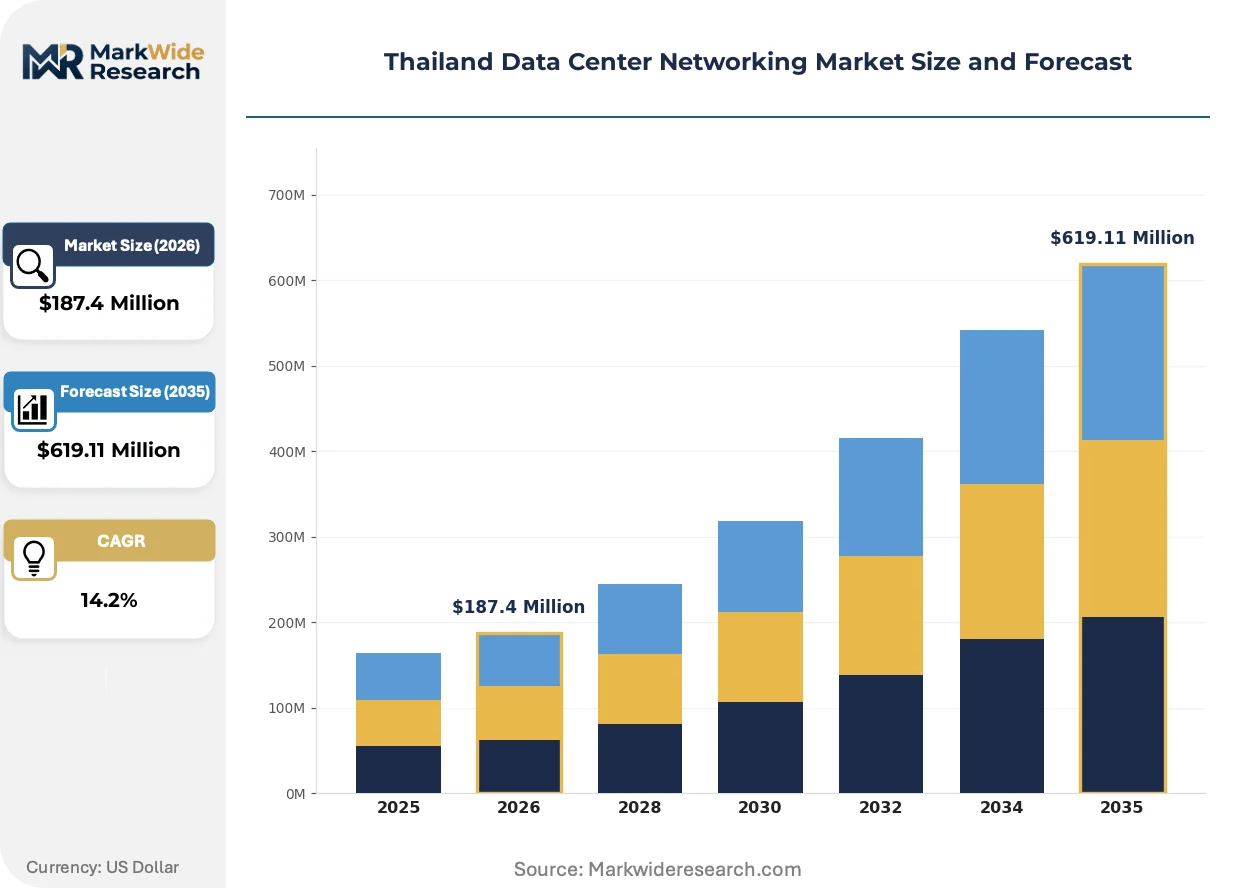
Market Dynamics
Thailand's data center networking sector is experiencing structural compression from the Personal Data Protection Act, which mandates localized data residency infrastructure and forces operators to rebuild switching architectures for domestic sovereignty compliance rather than regional hub efficiency.
Growth Catalysts
- Eastern Economic Corridor incentives:Board of Investment tax holidays for digital infrastructure investments are pulling hyperscale builds into Chonburi and Rayong provinces, creating clustered demand for high-density spine-leaf fabrics.
- PDPA compliance mandates:Thailand's data localization requirements under the Personal Data Protection Act are compelling financial services and e-commerce platforms to establish dedicated on-premise networking stacks rather than regional cloud extensions.
- AI training cluster emergence:GPU-intensive workloads near Bangkok are driving InfiniBand adoption for east-west traffic patterns that traditional Ethernet cannot satisfy at sub-microsecond latency thresholds.
Market Restraints
- BIS-aligned certification delays:Thailand's industrial standards body enforces extended testing protocols for imported switching equipment, stretching deployment timelines for non-domestic vendors by 8-14 weeks.
- Copper and optical component volatility:Spine-leaf architectures consume 3-4x more fiber cabling than legacy three-tier designs, exposing operators to spot price swings in 400G/800G transceiver modules sourced from concentrated East Asian suppliers.
- Power density constraints:Bangkok metro facilities face 30-50 MW substation limits that prevent full-scale AI cluster networking without grid infrastructure upgrades that remain 24-36 months from completion.
Strategic Opportunities
- Chiang Mai secondary market:Cooler ambient temperatures and lower land costs in northern Thailand support natural cooling for edge networking nodes serving latency-sensitive gaming and content delivery applications.
- 5G private network convergence:Integration of Open RAN fronthaul with data center switching fabrics enables unified management planes for manufacturing and logistics campuses in the Eastern Economic Corridor.
- Green data center directives:Thailand's energy efficiency regulations for digital infrastructure are creating preferential procurement lanes for vendors offering liquid-cooled switching and power-optimized SerDes architectures.
Industry Challenges
- Spine-leaf engineering scarcity:Local system integrators lack depth in Clos topology design and BGP-EVPN deployment, forcing operators to import Malaysian or Singaporean network architects at 40-60% cost premiums.
- Multi-vendor interoperability testing:Thai facilities running mixed switching stacks from different vendors face extended validation cycles for firmware compatibility that compress maintenance windows and elevate outage risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Data Center Networking Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Load Balancers End User: Colocation Providers, Enterprises, Managed Service Providers, Cloud Providers Technology: Ethernet, InfiniBand, Fiber Channel, Wireless Service Type: Installation, Maintenance, Consulting, Support |
| Companies Covered | Cisco Systems Inc., Huawei Technologies Co. Ltd., Juniper Networks Inc., Dell Technologies Inc., Hewlett Packard Enterprise, Arista Networks, Fujitsu, IBM, Inspur, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Data Center Networking Market Trends and Innovations
Switching architectures in Thai data centers are pivoting from hierarchical designs to flattened fabrics optimized for machine-to-machine traffic, while regulatory pressure and procurement model evolution reshape how networking infrastructure is specified and acquired.
Spine-leaf architectures are overtaking traditional three-tier designs in Bangkok and Eastern Economic Corridor facilities. Financial services and hyperscale colocation operators are adopting 400G spine switches with 25.6 Tbps aggregate capacity to support east-west virtualization traffic. This topology compression is collapsing aggregation layers and forcing vendors to compete on single-chip switch density rather than chassis modularity.
Thailand's Personal Data Protection Act is tightening cryptographic requirements for cross-border data flows through the Electronic Transactions Development Agency certification framework. Network security appliances must now implement hardware-rooted encryption that satisfies domestic standards before deployment in regulated verticals. Banking and insurance sectors are responding by pre-qualifying vendors with existing ETA certifications, narrowing the supplier pool for new facility builds.
Consumption-based switching procurement is displacing traditional capital purchase models among mid-size colocation operators in Thailand. Leasing arrangements for white-box switches with bundled software subscriptions allow facilities to match port capacity to actual tenant uptake rather than overbuilding for speculative demand. This shift is most visible in the Eastern Economic Corridor, where speculative builds outpace signed commitments and operators seek to preserve balance sheet flexibility.
Thailand Data Center Networking Market Segmentation
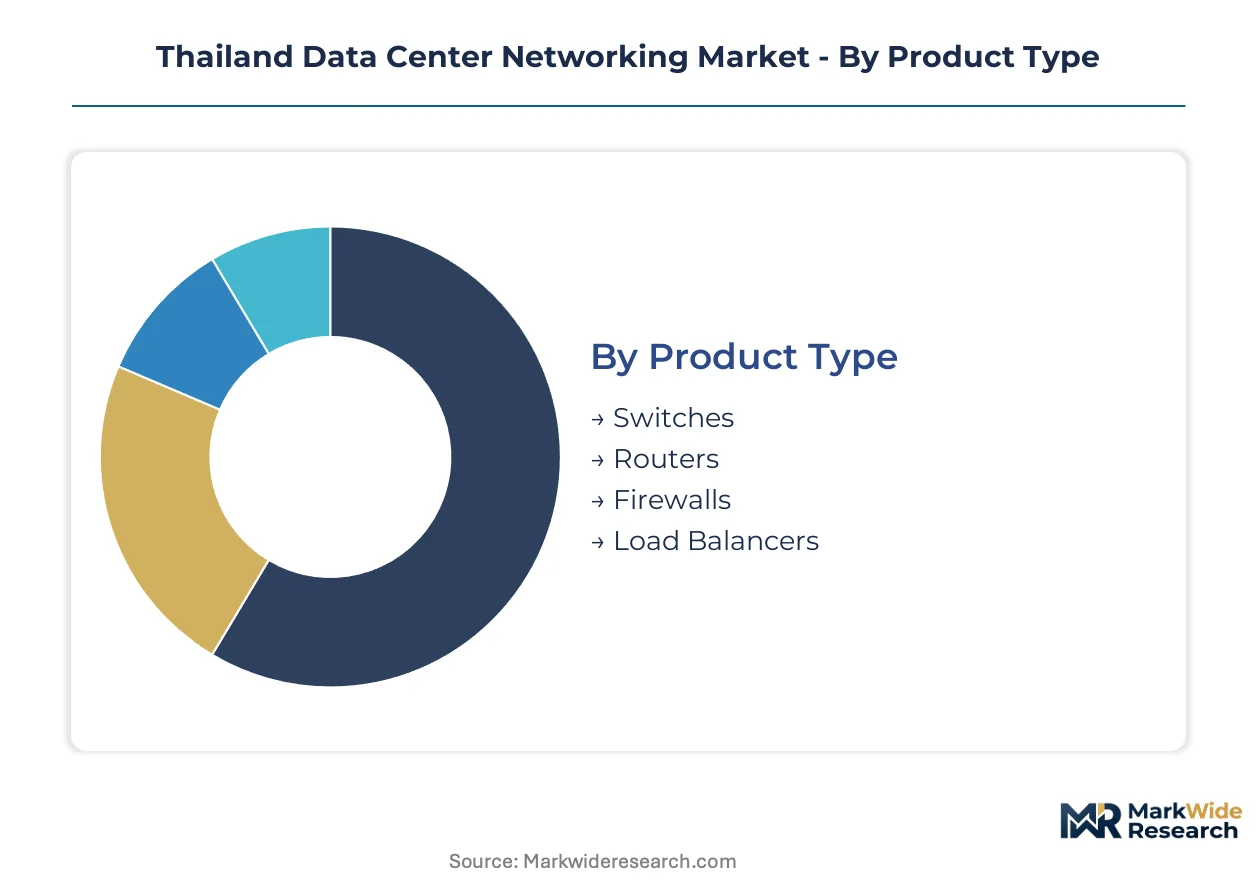
Thailand's data center networking market fragments across equipment categories, buyer types, and technology layers that each carry distinct procurement rhythms and margin profiles. Understanding these divisions reveals where infrastructure investment concentrates and which segments are reshaping under PDPA localization mandates and AI workload pressures.
Product Type:
Capital allocation intensity varies sharply across hardware categories, with port density and throughput specifications driving replacement cycles more than brand loyalty.
- Switches:Spine-leaf fabric deployments dominate Bangkok and Eastern Economic Corridor builds, with 400G aggregation switches capturing the largest share of hardware expenditure as three-tier architectures retire. Financial services and hyperscale colocation operators in Chonburi prioritize single-chip 25.6 Tbps spine switches to collapse network layers and cut latency.
- Routers:Border gateway and WAN aggregation platforms face extended procurement timelines under BIS-aligned certification requirements, stretching deployment windows by 8-14 weeks for imported chassis. Enterprise facilities in Bangkok metro lean toward domestic integrators with pre-certified inventory to bypass testing bottlenecks.
- Firewalls:Hardware-rooted encryption modules certified by the Electronic Transactions Development Agency are narrowing supplier pools for banking and insurance verticals.
- Load Balancers:Application delivery controllers see rising attach rates in e-commerce platforms handling flash traffic during regional shopping events.
Volume sits with Switches; growth tilts toward Firewalls as PDPA compliance hardens cryptographic requirements.
End User:
Facility ownership models determine procurement authority and vendor relationship depth, with outsourced infrastructure operators wielding greater negotiating leverage than captive enterprise IT.
- Cloud Providers:Hyperscale availability zone expansions in Bangkok and Rayong are driving the steepest expansion trajectory for spine-leaf fabrics, with these buyers specifying white-box switches and disaggregated software stacks to optimize total cost of ownership. Their procurement templates are reshaping vendor roadmaps across Southeast Asia.
- Colocation Providers:Multi-tenant facilities in the Eastern Economic Corridor face speculative build pressure, pushing consumption-based leasing models for switching hardware to preserve balance sheet flexibility until tenant commitments materialize.
- Enterprises:Banking and retail conglomerates are rebuilding on-premise networking stacks for PDPA data residency rather than extending regional cloud footprints.
- Managed Service Providers:Regional operators are consolidating network operations centers to serve mid-market Thai enterprises lacking internal spine-leaf engineering depth.
Revenue concentrates with Colocation Providers; margin expansion favors Cloud Providers through volume commitment leverage.
Technology:
Physical layer choices are splitting between established Ethernet dominance and emerging InfiniBand incursion as AI training clusters reshape traffic patterns.
- Ethernet:10 Gbps to 800 Gbps copper and optical implementations anchor the installed base, with 400G SR8 and DR4 transceivers seeing strongest uptake in Bangkok metro facilities upgrading from 100G leaf tiers. Supply concentration in East Asian optical component vendors exposes operators to spot price volatility.
- InfiniBand:GPU-intensive AI clusters near Bangkok are adopting HDR and NDR implementations for east-west traffic demanding sub-microsecond latency that Ethernet cannot satisfy, creating a new technology pocket with distinct vendor ecosystems.
- Fiber Channel:Storage area networking persists in legacy financial services data centers with sunk investments in FC-NVMe fabrics.
- Wireless:60 GHz and Wi-Fi 6E are penetrating edge networking nodes for temporary staging and maintenance access in hard-to-cable zones.
Deployment volume remains with Ethernet; technology transition momentum clusters around InfiniBand.
Service Type:
Post-sale revenue streams are gaining prominence as hardware margins compress and local engineering scarcity elevates professional services premiums.
- Installation:Spine-leaf topology deployment requires imported Malaysian and Singaporean network architects commanding 40-60% cost premiums over local integrators, making this the highest-margin service tier for vendors with regional deployment capabilities.
- Maintenance:Multi-vendor interoperability testing demands are extending firmware validation cycles, compressing maintenance windows and elevating outage risk that drives premium support contract attachment.
- Consulting:PDPA compliance architecture reviews are emerging as a discrete service line for legal-technical hybrid advisory.
- Support:24x7 Thai-language network operations center coverage is becoming a competitive differentiator for regional MSPs.
Recurring revenue pools deepest in Maintenance; consulting is climbing fastest as regulatory complexity mounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center networking investment concentrates in Bangkok's metropolitan core and the Eastern Economic Corridor, where hyperscale cloud builds and financial services compliance are restructuring infrastructure demand.
Bangkok Metropolitan Region
Financial services and e-commerce platforms are rebuilding on-premise networking stacks for PDPA data residency requirements. The Electronic Transactions Development Agency certifies cryptographic standards for security appliances deployed in banking facilities. Lat Phrao and Ratchada districts host the densest concentration of Tier III facilities upgrading to 400G spine-leaf fabrics.
Eastern Economic Corridor
Board of Investment tax holidays are pulling hyperscale builds into Chonburi and Rayong provinces. The National Broadcasting and Telecommunications Commission allocates spectrum for wireless interconnects serving manufacturing campuses. Chonburi's industrial zones anchor clustered demand for high-density switching fabrics from cloud providers expanding local availability zones.
Chiang Mai and Northern Thailand
Cooler ambient temperatures and lower land costs support natural cooling for edge networking nodes. The country's energy efficiency regulations for digital infrastructure create preferential procurement lanes for power-optimized equipment. Chiang Mai's emerging data center cluster serves latency-sensitive gaming and content delivery applications for Southeast Asian markets.
Phuket and Southern Economic Zone
Tourism and hospitality technology infrastructure drives demand for resilient networking in disaster-prone coastal areas. The industrial standards body enforces BIS-aligned certification requirements that constrain import timelines. Phuket's submarine cable landing stations position the island as a secondary connectivity hub for international traffic.
Khon Kaen and Northeastern Region
Government digital economy initiatives are stimulating public sector data center construction in secondary cities. Local system integrators lack depth in Clos topology design, forcing operators to import regional network architects. Khon Kaen's university and research institutions anchor modest AI training cluster development with InfiniBand networking requirements.
Thailand Data Center Networking Market Competitive Landscape
American producers anchor the premium switching tier; Chinese specialists hold cost-optimized positions for state-backed digital economy projects. The vendor base stratifies across three tiers: global incumbents with established channel partnerships, aggressive challengers competing on total cost of ownership, and cloud-optimized specialists capturing hyperscale relationships. Strategic moves concentrate on consumption-based procurement models and domestic assembly partnerships to bypass certification delays.
Within the established incumbent tier, Cisco Systems Inc. and Juniper Networks Inc. represent the channel-anchored archetype with pre-certified inventory advantages. Huawei Technologies Co. Ltd. exemplifies the state-project specialist competing aggressively on total cost of ownership. Arista Networks occupies the cloud-optimized position serving hyperscale relationships in the Eastern Economic Corridor. These three anchors illustrate how geographic origin and partnership depth determine competitive positioning under Thailand's regulatory framework.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Huawei Technologies Co. Ltd. |
| Juniper Networks Inc. |
| Dell Technologies Inc. |
| Hewlett Packard Enterprise |
| Arista Networks |
| Fujitsu |
| IBM |
| Inspur |
| Others |
Pricing and Supply Chain Analysis
400G/800G optical transceiver spot prices in East Asian commodity markets cascade through Thai data center networking supply chains, compressing margins on spine-leaf deployments while amplifying cost premiums for PDPA-compliant hardware-rooted encryption modules. Buyers stratify across three tiers: hyperscale cloud providers leveraging volume commitments for white-box switches, financial services accepting certification-driven premiums for ETA-approved appliances, and mid-market colocation operators deferring capital through consumption-based leasing.
Pricing Analysis
Volume concentrates with hyperscale cloud providers commanding 400G spine switch procurement at scale, while margin expansion favors vendors bundling PDPA compliance architecture with hardware-rooted encryption certified by the Electronic Transactions Development Agency. Price differentiation separates ETA-certified premium tiers from standard enterprise switching, with banking and insurance verticals absorbing 15-25% premiums for pre-qualified inventory. Cost compression in mid-market colocation is intensifying as speculative builds outpace tenant commitments, forcing operators toward subscription-based white-box models. Cloud providers exhibit lowest price sensitivity due to TCO optimization frameworks; mid-market colocation operators face highest sensitivity as balance sheet flexibility erodes.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for spine-leaf fabrics, while tiered distribution through Thai system integrators serves enterprise and colocation segments facing BIS-aligned certification bottlenecks. Component supply concentrates in Taiwan, South Korea, and China for 25.6 Tbps switch ASICs, 400G/800G optical transceivers, and precision copper cabling. Raw material dependencies span silicon wafers, rare-earth-doped fiber for amplifiers, and high-purity copper for backplane interconnects. Single-source vulnerability in East Asian optical component vendors exposes operators to spot price volatility and extended lead times. Distribution runs through Bangkok-based value-added distributors with pre-certified inventory for rapid deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race into domestic assembly partnerships, as vendors bypass BIS-aligned certification delays by establishing local manufacturing footprints that compress deployment timelines for switching equipment.
For Market Incumbents: Extend pre-certified inventory advantages by deepening channel partnerships with Bangkok metro system integrators holding ETA-approved security appliance stockpiles. Threats from Huawei's aggressive TCO positioning in state-backed Eastern Economic Corridor projects demand defensive certification investments in hardware-rooted encryption modules. Priority lever rests on backward integration into domestic switch assembly to neutralize 8-14 week import testing bottlenecks. For New Entrants and Emerging Players: Mid-market colocation operators in Chonburi and Rayong represent the most penetrable buyer archetype, as speculative builds create demand for consumption-based switching procurement without incumbent channel lock-in. White-space targets include PDPA compliance consulting services and 24x7 Thai-language network operations center coverage. Go-to-market angle centers on spine-leaf deployment partnerships with Malaysian and Singaporean network architects to overcome local Clos topology engineering scarcity. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional managed service providers consolidating network operations centers to serve Thai mid-market enterprises lacking internal spine-leaf engineering depth. Long-term viability hinges on recurring maintenance revenue pools deepening as multi-vendor interoperability testing extends firmware validation cycles. Signal to watch is Board of Investment tax holiday expiration timelines in the Eastern Economic Corridor, which will reshape hyperscale build economics and vendor procurement templates.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Partnership | Neutralizes BIS-aligned certification delays for imported switching equipment in Thai facilities. |
| PDPA Compliance Certification | Unlocks banking and insurance verticals requiring ETA-approved hardware-rooted encryption modules. |
| Spine-Leaf Engineering Acquisition | Addresses scarcity of Clos topology expertise forcing 40-60% premiums on imported architects. |
| Consumption-Based Procurement Platform | Matches port capacity to actual tenant uptake in speculative Eastern Economic Corridor builds. |
| InfiniBand Ecosystem Development | Captures GPU-intensive AI cluster demand near Bangkok demanding sub-microsecond latency. |
Research Methodology
Document review covered National Broadcasting and Telecommunications Commission spectrum allocation filings, Electronic Transactions Development Agency cryptographic certification registers, and Board of Investment tax incentive disclosures, complemented by interviews with data center facility directors, network operations managers at hyperscale cloud providers, procurement leads at Thai financial institutions, spine-leaf deployment architects, and system integrators in Bangkok and Chonburi. Secondary validation drew from BIS-aligned product certification databases, industrial standards body testing protocols, and hyperscaler capex expenditure disclosures. Bottom-up equipment shipment analysis triangulated against top-down infrastructure investment tracking.
Historical spending patterns were cross-referenced against panel input from network architects and procurement officers to anchor projection assumptions across the modeling period. Segmentation dimensions modeled include product type, end-user ownership model, physical layer technology, and service delivery mechanism, with geographic deployment patterns across Bangkok metropolitan, Eastern Economic Corridor, and secondary northern markets. CAGRs were derived from equipment replacement cycle analysis, regulatory compliance-driven refresh mandates, and AI workload penetration curves. Forecast inputs encompass PDPA enforcement trajectory, Board of Investment incentive renewal probability, and grid infrastructure upgrade timelines affecting power density constraints.
Revisions become necessary when PDPA regulatory amendments, Board of Investment policy shifts, or optical component supply disruptions materialize beyond baseline assumptions. Forecasts reflect documented assumptions about hyperscale availability zone expansion commitments, domestic certification timeline stability, and spine-leaf architecture adoption velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Mobile Data Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Global Data Management Platform Market