
 China Cross-Border E-Commerce Logistics Market | 2026-2036
China Cross-Border E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
China Cross-Border E-Commerce Logistics Market Insights
China's dual carbon goals is expanding compliance requirements across cross-border supply chains, compelling logistics providers to adopt cleaner fleet technologies and energy-efficient warehouse operations. SF Express leverages its integrated air-and-ground network to control premium express corridors into Southeast Asia and Europe. JD Logistics anchors cold-chain and high-value electronics fulfillment through proprietary warehouse robotics and last-mile density in tier-one cities.
China cross-border e-commerce logistics encompasses the end-to-end movement of goods from Chinese sellers to overseas buyers, spanning first-mile collection, customs brokerage, international line-haul, and last-mile handoff, typically operating within delivery windows of three to fifteen days depending on mode and destination. The sector functions as commercial infrastructure enabling direct-to-consumer export trade, with Freight Forwarding and Customs Clearance representing mature, margin-compressed service layers where scale operators extract efficiency through automated documentation and bonded zone consolidation. AI Routing and Automated Sorting within the Technology dimension are capturing disproportionate investment as labor costs rise and peak-season volume surges strain manual processing capacity.
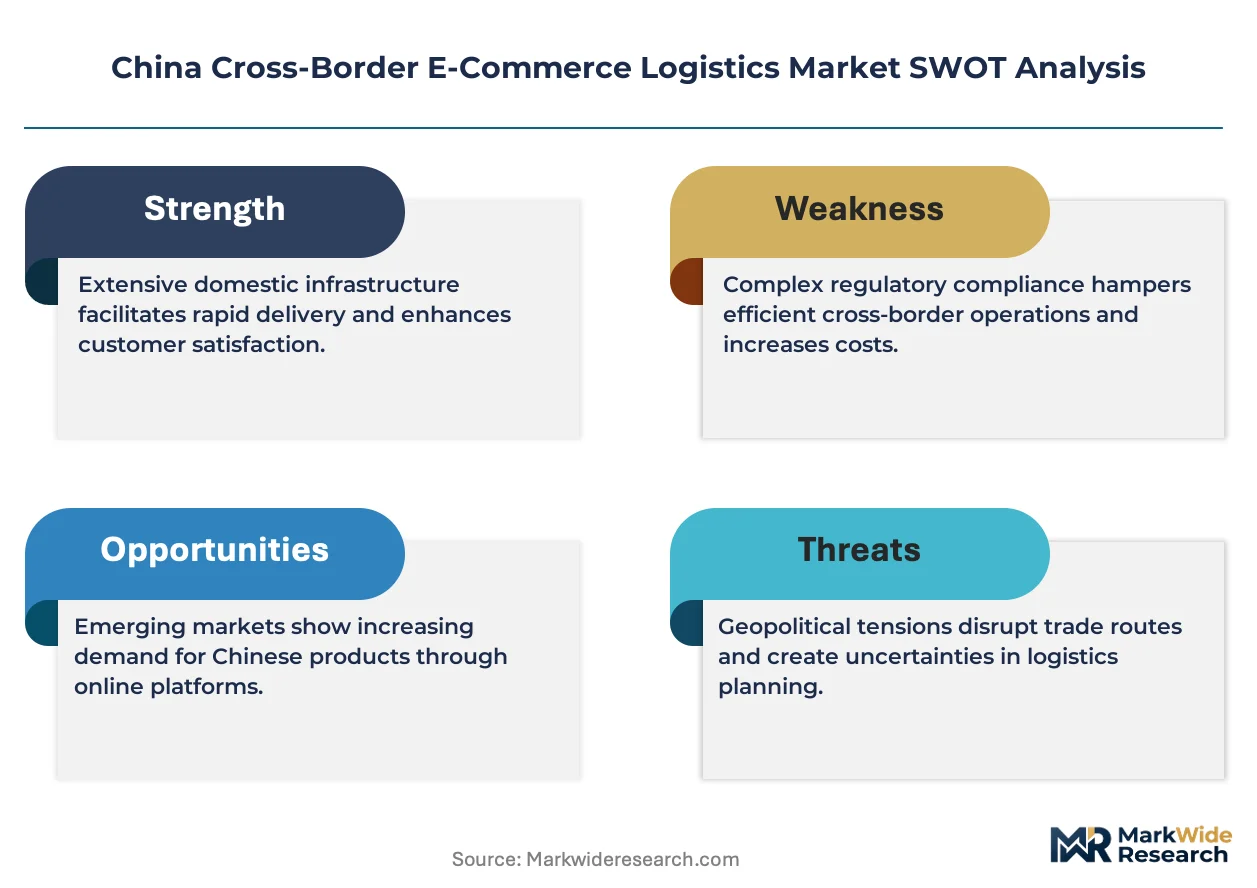
SAMR enforces product quality and platform accountability standards that shape seller eligibility and logistics partner certification requirements, while GB standards and NMPA regulations govern hazardous materials labeling and consumer product safety documentation for cross-border parcels. MIIT coordinates data localization and cross-border transmission protocols that affect IoT tracking systems and blockchain traceability deployments. Stakeholders must weigh regulatory compliance investments against automation dividends as enforcement intensity escalates.
Market Dynamics
China's dual carbon goals are forcing logistics providers to restructure energy consumption across bonded warehouses and line-haul fleets, compressing operating margins while accelerating capital deployment into electrification.
Growth Catalysts
- GB Standards Compliance:NMPA and SAMR certification requirements for consumer electronics exports are professionalizing seller documentation, reducing customs detention rates and accelerating clearance velocity at Shanghai and Hangzhou hubs.
- AI Routing:Automated sorting and predictive load-balancing systems are absorbing peak-season volume surges that previously required seasonal labor expansion, protecting margin structure during Singles' Day and Golden Week cycles.
- Yangtze River Delta Concentration:Shanghai Pudong and Hangzhou Xiaoshan airports anchor dedicated freighter networks into Southeast Asia and Europe, compressing line-haul transit times for high-value electronics shipments.
Market Restraints
- Aviation Fuel Cost Volatility:Jet fuel represents 35-45% of air freight operating costs, and price spikes transmit directly into express corridor pricing, constraining adoption among price-sensitive cross-border sellers.
- Customs Brokerage Margin Compression:Automated documentation platforms and bonded zone consolidation have commoditized traditional freight forwarding, squeezing service provider profitability in mature trade lanes.
- Data Localization Requirements:MIIT cross-border transmission protocols restrict IoT tracking data flows, complicating real-time visibility deployments for blockchain traceability systems.
Strategic Opportunities
- Cold-Chain Expansion:JD Logistics proprietary warehouse robotics and temperature-controlled infrastructure create defensible positioning in pharmaceutical and fresh-food exports, segments with 3-5x standard parcel yields.
- Dual Carbon Incentives:MEE green logistics subsidies and carbon-trading mechanisms reward fleet electrification and solar warehouse installations, lowering total cost of ownership for compliant operators.
- Last-Mile Density in Tier-Two Cities:Ningbo, Suzhou, and Wuxi fulfillment nodes remain underpenetrated relative to Shanghai and Hangzhou, offering first-mover advantages in collection network coverage.
Industry Challenges
- Automation Engineering Talent Scarcity:Warehouse robotics deployment and AI routing optimization require specialized skill sets that outpace domestic university pipeline output, inflating recruitment costs.
- SAMR Certification Timelines:Product safety documentation reviews for cross-border electronics now average 14-21 days, creating inventory staging requirements that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cross-Border E-Commerce Logistics Market |
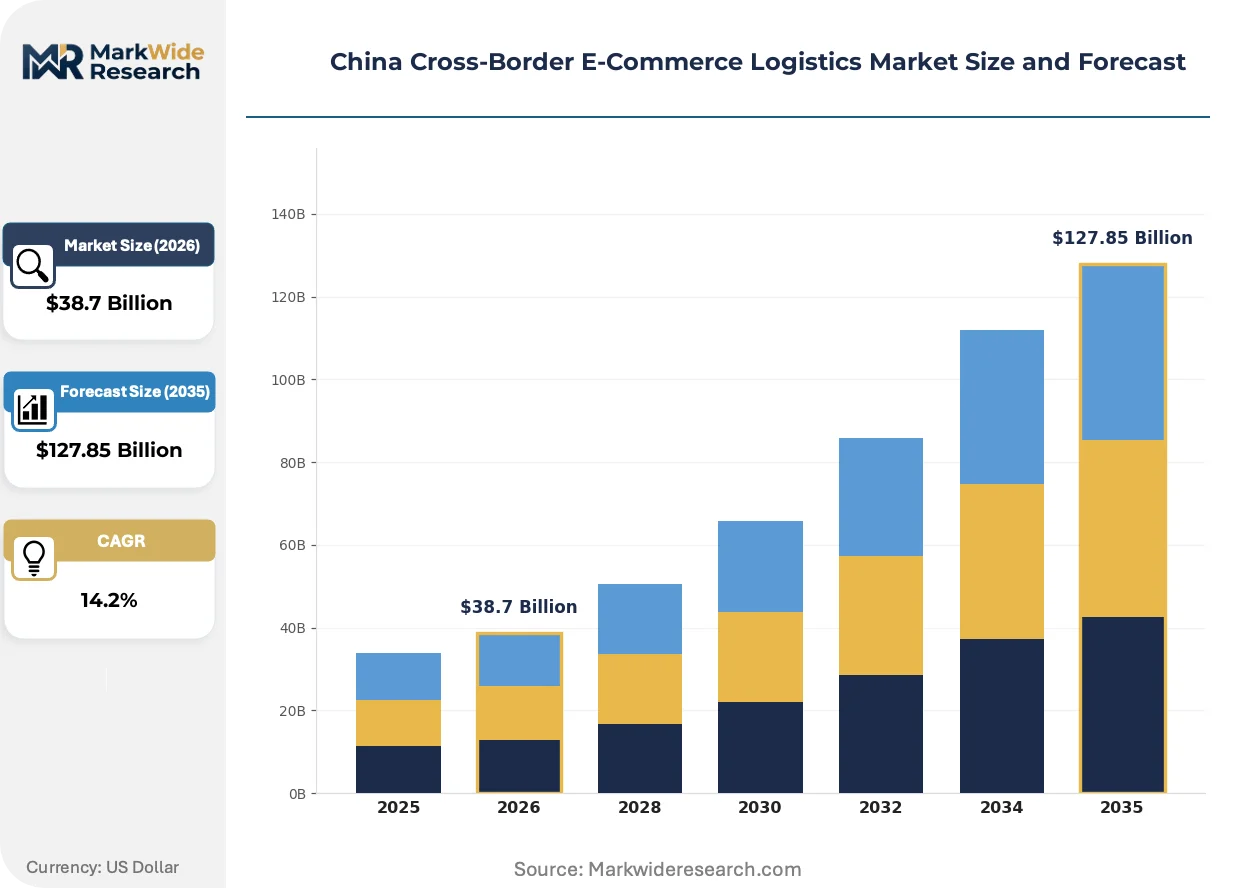
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last Mile Delivery, Freight Forwarding, Customs Clearance, Warehousing Technology: Blockchain, IoT Tracking, AI Routing, Automated Sorting Customer Type: B2B, B2C, Marketplace Sellers, Individual Consumers Delivery Mode: Air Freight, Ocean Freight, Rail Transport, Road Transport |
| Companies Covered | SF Express, STO Express, YTO Express, ZTO Express, J&T Express, JD Logistics, Cainiao Network, Sinotrans, COSCO Shipping, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cross-Border E-Commerce Logistics Market Trends and Innovations
Technology convergence and regulatory tightening are compressing delivery windows while fragmenting service tiers, forcing logistics providers to differentiate through data infrastructure rather than asset scale alone.
Automated sorting systems integrating computer vision and dynamic weight-dimensioning are rewriting fulfillment economics in Shanghai and Hangzhou bonded zones. Third-party logistics operators and dedicated brand channels alike are deploying these systems at 40% annual capacity expansion rates. The technology is rewriting labor deployment models, shifting workforce composition from manual sorters to robotics technicians and exception-handling specialists.
SAMR platform accountability standards and NMPA hazardous materials labeling requirements are tightening documentation intensity for cross-border parcels. Sellers now face suspension from marketplace eligibility for incomplete certification, elevating logistics partner selection criteria. Electronics and cosmetics categories are responding by consolidating shipment volumes through certified 3PLs with pre-cleared documentation templates.
Direct-to-consumer export sellers are unbundling express, standard, and economy service tiers based on delivery-certainty requirements rather than speed alone. Southeast Asian and European buyers are selecting logistics modes by customs pre-clearance reliability and returns-handling capability, not headline transit time. This preference shift concentrates volume with operators offering end-to-end liability coverage and destination-country last-mile integration.
China Cross-Border E-Commerce Logistics Market Segmentation
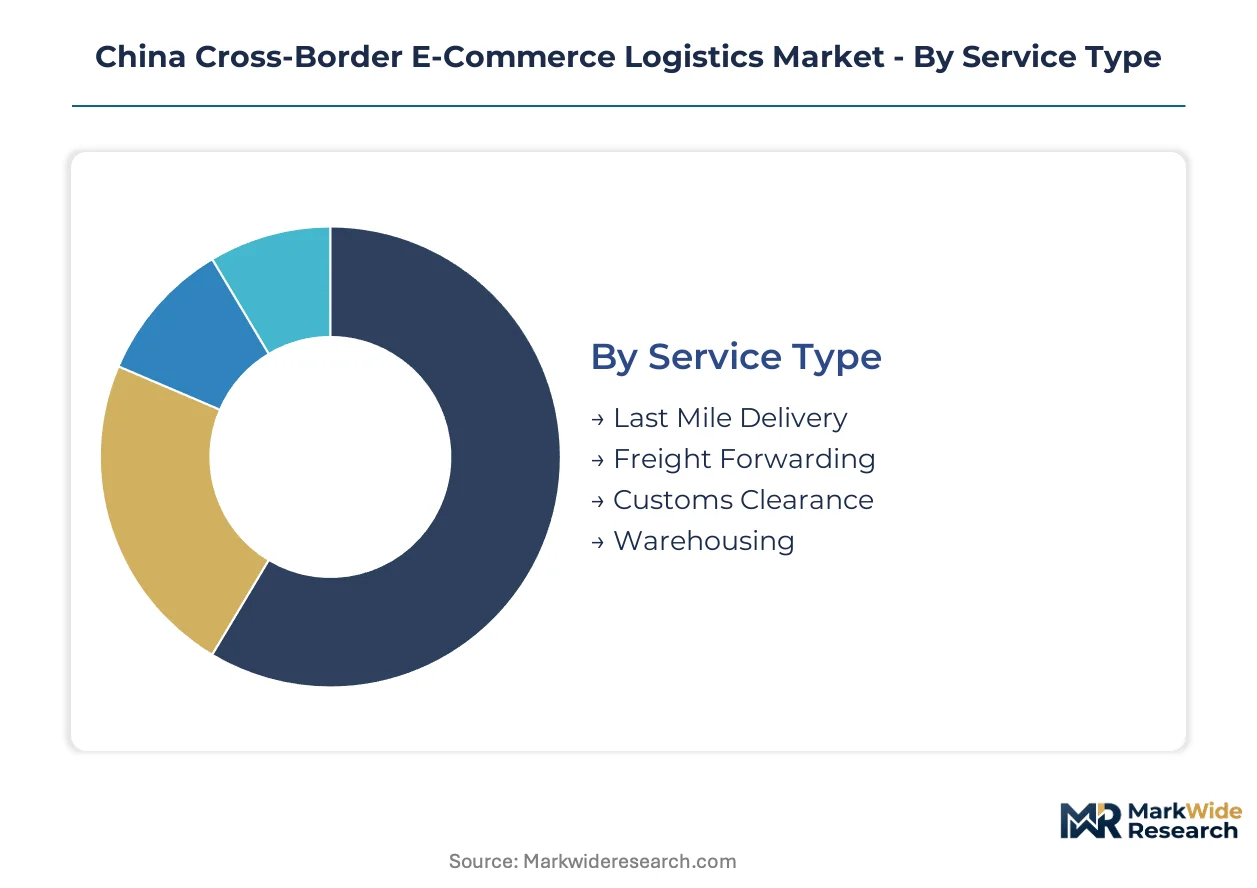
Segmentation in China cross-border e-commerce logistics reveals how service tiers, technology adoption, and delivery modes concentrate margin capture. Supply chain configuration varies sharply across customer types and transport modes, with bonded zone proximity and customs automation determining competitive position.
Service Type:
Supply concentration in the Yangtze River Delta shapes which service layers capture premium pricing versus commoditized volume.
- Last Mile Delivery:Final-mile handoff to overseas buyers demands destination-country partner networks and returns-handling infrastructure. Demand clusters around Shanghai and Hangzhou hub operations serving Southeast Asian and European corridors, with SF Express and JD Logistics controlling proprietary density in tier-one Chinese cities that feed international express lanes.
- Freight Forwarding:Traditional documentation and carrier booking functions face margin compression from automated platforms and bonded zone consolidation. Mature trade lanes into Europe and North America see price pressure, though Ningbo and Suzhou collection nodes offer first-mover expansion opportunities for operators building density outside Shanghai-Hangzhou concentration.
- Customs Clearance:NMPA and SAMR certification requirements professionalize documentation intensity, elevating certified broker status as a competitive filter.
- Warehousing:Bonded zone positioning in Shanghai Pudong and Hangzhou Xiaoshan determines inventory staging economics for peak-season electronics volumes.
Today's leader: Freight Forwarding. Tomorrow's challenger: Last Mile Delivery.
Technology:
Cost tier separation between labor-intensive and automated processing drives technology investment allocation across fulfillment networks.
- AI Routing:Predictive load-balancing algorithms absorb Singles' Day and Golden Week volume surges without proportional labor expansion. Deployment concentrates in Shanghai and Hangzhou bonded zones where 40% annual capacity expansion rates rewrite workforce composition toward robotics technicians.
- Automated Sorting:Computer vision and dynamic weight-dimensioning systems integrate with warehouse robotics to compress unit economics. JD Logistics anchors proprietary deployments for cold-chain and high-value electronics, creating defensible yield premiums in pharmaceutical and fresh-food exports.
- Blockchain:MIIT data localization protocols complicate cross-border transmission for traceability systems, restricting real-time visibility deployments.
- IoT Tracking:Regulatory constraints on cross-border data flows limit sensor network integration for end-to-end shipment monitoring.
Today's leader: Automated Sorting. Tomorrow's challenger: AI Routing.
Customer Type:
Volume concentration among platform-integrated sellers versus fragmented individual shapers determines service tier packaging and liability structures.
- Marketplace Sellers:Platform-integrated merchants face SAMR suspension risk for incomplete NMPA certification, consolidating volume through certified 3PLs with pre-cleared documentation templates. Electronics and cosmetics categories drive this professionalization.
- B2C:Direct-to-consumer export brands unbundle express, standard, and economy tiers based on delivery-certainty requirements rather than speed alone, with customs pre-clearance reliability and returns-handling capability determining logistics mode selection.
- B2B:Wholesale export shipments operate on contracted lane pricing with longer planning horizons and lower documentation intensity per unit.
- Individual Consumers:Fragmented sender base relies on postal consolidators and economy line-haul with extended delivery windows.
Today's leader: Marketplace Sellers. Tomorrow's challenger: B2C.
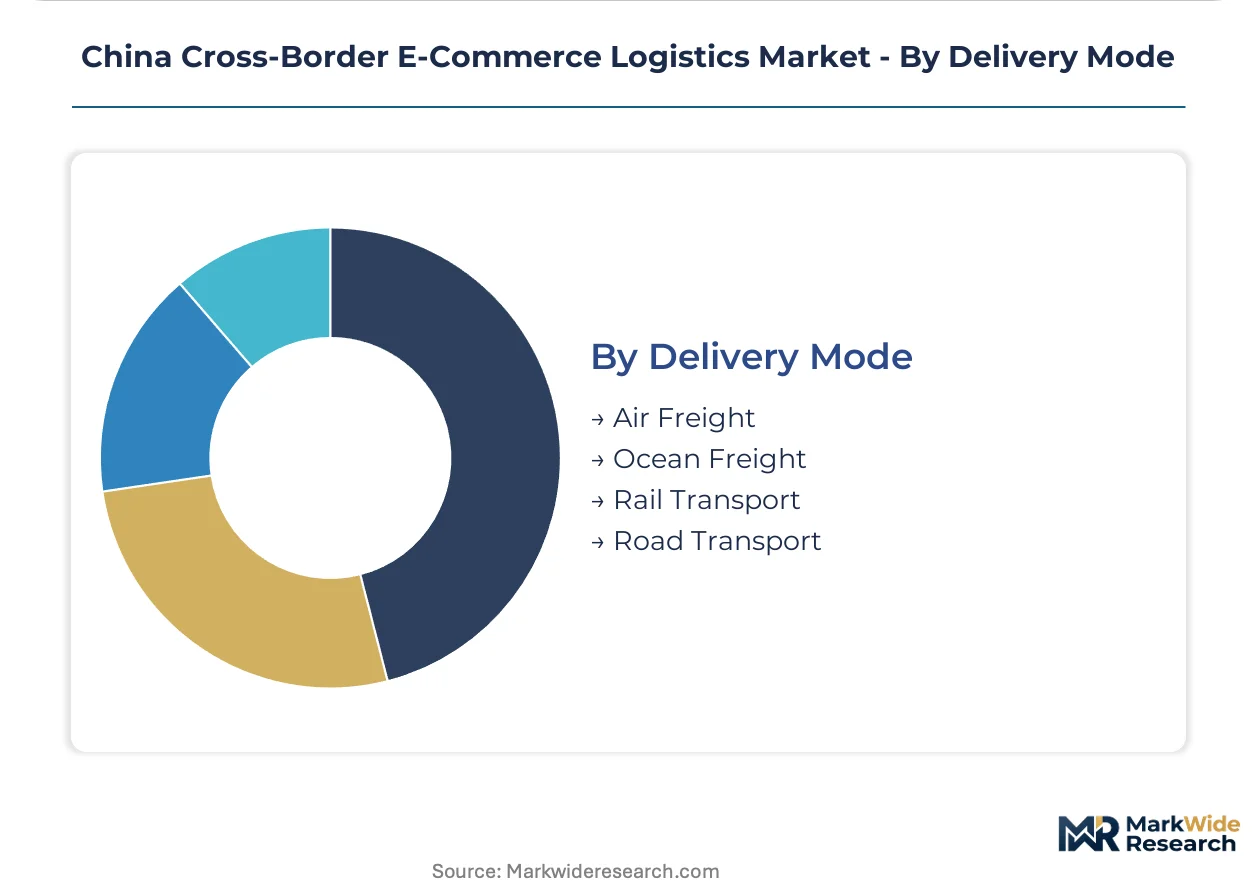
Delivery Mode:
Margin structure varies sharply across transport modes, with fuel cost exposure and infrastructure access determining competitive positioning.
- Air Freight:Dedicated freighter networks from Shanghai Pudong and Hangzhou Xiaoshan anchor premium express corridors into Southeast Asia and Europe. Jet fuel representing 35-45% of operating costs transmits price volatility directly into express pricing, constraining adoption among price-sensitive cross-border sellers.
- Rail Transport:China-Europe block train services offer intermediate transit times and lower fuel exposure than air, expanding most quickly for mid-value electronics and automotive parts shipments through Xinjiang corridor gateways.
- Ocean Freight:Containerized line-haul serves bulk inventory replenishment with 15-30 day windows, operating on thin margins in mature lanes.
- Road Transport:Cross-border trucking through ASEAN corridors provides flexible capacity for regional e-commerce volumes with shorter haul distances.
Today's leader: Air Freight. Tomorrow's challenger: Rail Transport.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border e-commerce logistics emerged from China's export manufacturing clusters in the Yangtze River Delta, where bonded zone infrastructure first consolidated international parcel flows during the early 2010s platform economy expansion.
Yangtze River Delta
Shanghai Pudong and Hangzhou Xiaoshan airports anchor dedicated freighter networks into Southeast Asia and Europe. MEE green logistics subsidies reward warehouse solar installations and fleet electrification in this corridor. Ningbo and Suzhou fulfillment nodes remain underpenetrated relative to Shanghai-Hangzhou concentration, offering first-mover advantages in collection network coverage.
Pearl River Delta
Shenzhen electronics manufacturers drive direct-to-consumer export volumes through dedicated logistics channels. GB standards compliance requirements from SAMR professionalize seller documentation, reducing customs detention rates at Guangzhou Baiyun cargo terminals. Dongguan bonded warehouses process peak-season consumer electronics volumes with automated sorting systems.
Beijing-Tianjin-Hebei
Tianjin Port serves as the northern gateway for rail-sea intermodal shipments into Europe via Xinjiang corridor gateways. MIIT data localization protocols restrict IoT tracking data flows, complicating real-time visibility deployments for blockchain traceability systems in this cluster. Beijing-based platform operators consolidate cross-border seller volumes through certified 3PL partnerships.
Sichuan-Chongqing
Western China manufacturing relocation drives demand for rail transport connections to Europe through the Chongqing-Duisburg block train service. Dual carbon goals compel logistics providers to adopt cleaner fleet technologies across bonded warehouses in this inland hub. Chengdu Shuangliu International Airport expands cargo capacity for high-value electronics exports.
Shandong Peninsula
Qingdao Port anchors ocean freight consolidation for bulk inventory replenishment to North American markets. NMPA certification timelines for cross-border electronics create inventory staging requirements that strain working capital for sellers operating through this corridor. Yantai and Weihai processing zones specialize in cold-chain exports for agricultural products.
China Cross-Border E-Commerce Logistics Market Competitive Landscape
Capital-heavy asset operators compete with platform-integrated network orchestrators across China's cross-border logistics sector. The market structures around three tiers: integrated express carriers with proprietary air fleets, platform-affiliated logistics networks with bonded zone density, and specialized freight forwarders with customs brokerage expertise. Consolidation pressures favor operators combining warehouse robotics deployment with destination-country last-mile partnerships. Strategic moves center on cold-chain infrastructure expansion and dual carbon compliance certification.
Within the integrated express tier, SF Express and JD Logistics exemplify divergent asset strategies. SF Express leverages its air-and-ground network to control premium express corridors, while JD Logistics anchors positioning through proprietary warehouse robotics and cold-chain infrastructure. STO Express, YTO Express, and ZTO Express occupy the volume-driven standard delivery segment. J&T Express represents the Southeast Asia-specialized challenger archetype. Cainiao Network functions as the platform-orchestrated network layer, coordinating fragmented logistics capacity through data integration rather than captive asset ownership.
| Leading Market Players |
|---|
| SF Express |
| STO Express |
| YTO Express |
| ZTO Express |
| J&T Express |
| JD Logistics |
| Cainiao Network |
| Sinotrans |
| COSCO Shipping |
| Others |
Pricing and Supply Chain Analysis
Automated sorting deployment across Shanghai and Hangzhou bonded zones compresses unit economics while concentrating volume with operators achieving scale in warehouse robotics. This technology shift simultaneously reduces labor cost exposure and elevates capital barriers, reshaping margin capture toward integrated carriers with proprietary infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by delivery-certainty requirements rather than speed alone. Certification grade under SAMR and NMPA standards and volume scale differentiate price bands, with customs pre-clearance reliability commanding premiums. Pricing pressure stems from automated documentation platforms commoditizing freight forwarding in mature Europe and North America lanes. Individual consumers and fragmented postal consolidators exhibit highest price sensitivity, while marketplace sellers prioritize certification compliance over cost minimization.
Supply Chain Analysis
Certification gating through NMPA and SAMR documentation requirements professionalizes supplier eligibility, elevating certified 3PL status as a competitive filter. Supply concentrates in China, with Shanghai and Hangzhou anchoring bonded zone infrastructure and Vietnam and Thailand serving as Southeast Asian corridor extensions. The network draws from jet fuel for air freight, warehouse robotics components, and cold-chain refrigeration systems. Single-source vulnerability runs through concentrated freighter networks at Shanghai Pudong and Hangzhou Xiaoshan. Distribution runs through platform-orchestrated networks and proprietary carrier channels to destination-country last-mile partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds on regulatory tightening, with SAMR platform accountability standards and NMPA hazardous materials labeling driving seller consolidation toward certified logistics partners.
For Market Incumbents: To counter margin compression in automated documentation and bonded zone consolidation, deepen proprietary warehouse robotics deployment in tier-two collection nodes and secure exclusive cold-chain certification for pharmaceutical exports. Channel control through destination-country last-mile partnerships protects express corridor pricing power against Southeast Asian challengers. For New Entrants and Emerging Players: Launch via underpenetrated Ningbo and Suzhou fulfillment nodes where collection network density lags Shanghai-Hangzhou concentration. Target certified 3PL partnerships for electronics and cosmetics marketplace sellers facing SAMR suspension risk. White space exists in temperature-controlled agricultural exports through Shandong Peninsula cold-chain infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap freight forwarders lacking warehouse robotics integration but holding customs brokerage certification. Long-term viability over the next decade hinges on dual carbon compliance certification and MIIT data localization adaptation. The signal to watch is MEE green logistics subsidy allocation intensity as fleet electrification capital deployment accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | JD Logistics proprietary robotics create defensible yield premiums in pharmaceutical exports. |
| Dual Carbon Certification Program | MEE subsidies reward solar warehouse installations and electric fleet conversion. |
| Platform Integration Partnership | Cainiao Network orchestration consolidates fragmented capacity through data layer control. |
| Geographic Expansion | Ningbo and Suzhou nodes offer first-mover collection density outside Yangtze River Delta concentration. |
| Acquisition of Specialist Firm | Certified 3PLs with pre-cleared NMPA documentation templates capture marketplace seller volume consolidation. |
Research Methodology
Coverage spans China's Yangtze River Delta, Pearl River Delta, Beijing-Tianjin-Hebei, Sichuan-Chongqing, and Shandong Peninsula, with primary inputs from each logistics cluster. The analysis combines interviews with bonded zone operations directors, customs brokerage managers, platform seller compliance officers, and cold-chain infrastructure engineers with secondary validation from MIIT data transmission filings, SAMR certification databases, MEE green logistics subsidy records, and customs trade statistics. Bottom-up volume triangulation across service types and top-down macroeconomic anchoring ensure consistency.
Granularity-level modeling captures service type, technology adoption, customer segment, and delivery mode dimensions at the corridor level between Chinese origin hubs and destination countries. CAGRs derive from volume trajectory analysis across the projection horizon, incorporating Singles' Day and Golden Week peak seasonality patterns, aviation fuel cost sensitivity, and regulatory enforcement intensity assumptions. Industry-specific inputs include freighter network capacity schedules and bonded zone automation deployment rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt SAMR certification timeline extensions or MIIT data localization protocol revisions. Forecasts reflect documented assumptions regarding dual carbon policy implementation pace and Southeast Asian destination market customs modernization. A model refresh is warranted upon material change in MEE subsidy allocation or aviation fuel price volatility regime.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
Retail E-Commerce Market
E-Commerce Solutions
E-Commerce Ecosystem Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
E-Commerce in Nigeria Market
E-Commerce Solutions
United Arab Emirates E-Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
Estonia E-Commerce Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
UAE Ecommerce Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
Asia Pacific Same Day Delivery Market
E-Commerce Solutions
E-Commerce in Luxembourg Market