
 Europe Subscriber Data Management Market | 2026-2036
Europe Subscriber Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Subscriber Data Management Market Analytics
Telecom systems engineering talent scarcity is reorganizing competitive dynamics across the Europe Subscriber Data Management Market, forcing vendors to restructure delivery models around remote implementation pods and partner ecosystems. Nokia Corporation sustains its position through deep radio access network integration that binds subscriber data to core infrastructure roadmaps. Enea AB specializes in cloud-native signaling and data layer software, giving it outsized presence in Nordic operator upgrade cycles. Cisco Systems, Inc. leverages its enterprise security footprint to cross-sell subscriber identity and access management into converged telecom-enterprise accounts.
Europe Subscriber Data Management encompasses the software systems, databases, and policy engines that consolidate subscriber identity, service entitlement, usage records, and consent preferences into unified profiles accessible across network functions and business support systems. These platforms typically operate at sub-50 millisecond latency thresholds for authentication queries and employ distributed ledger or in-memory architectures to maintain consistency across georedundant installations. Cloud-based deployment now leads in new installations, driven by mobile operators seeking elastic capacity for 5G network slicing and IoT onboarding spikes. AI and Machine Learning segments within the technology dimension are expanding fastest, as operators deploy predictive churn models and real-time tariff personalization engines atop unified subscriber data lakes. Data Governance solutions command premium pricing due to the compliance burden imposed by cross-border data residency requirements within the European Economic Area.
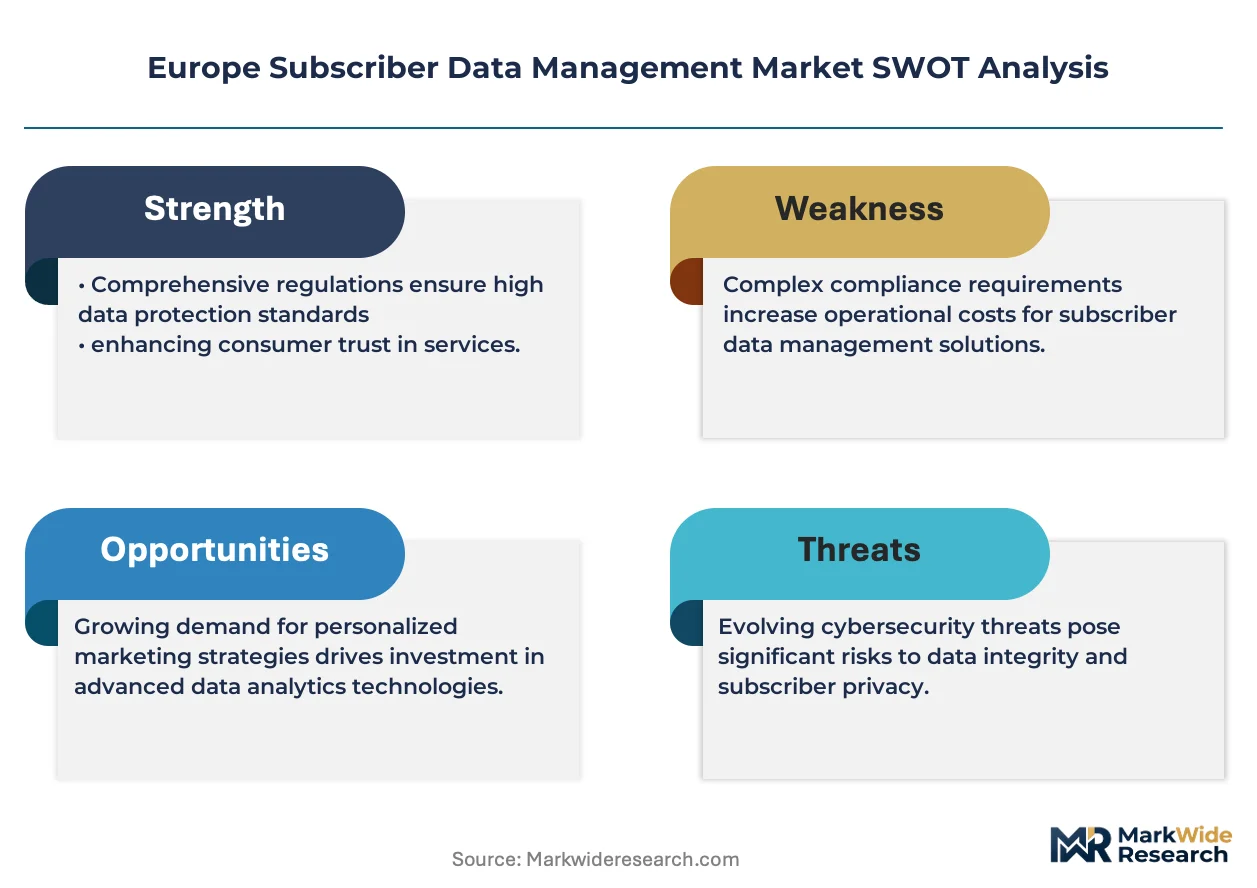
The EU's General Data Protection Regulation and the Digital Services Act impose strict data minimization, portability, and audit obligations that directly shape subscriber data platform procurement criteria and vendor qualification timelines. EMA guidance on clinical data interoperability and national telecom regulators in Germany, France, and Italy enforce additional sector-specific retention and anonymization standards that layer onto baseline GDPR requirements. Stakeholders must monitor the interplay between the EU AI Act's risk classification framework and automated decision-making features embedded in subscriber analytics modules, as this intersection will determine which platform capabilities remain permissible without human-in-the-loop architectures.
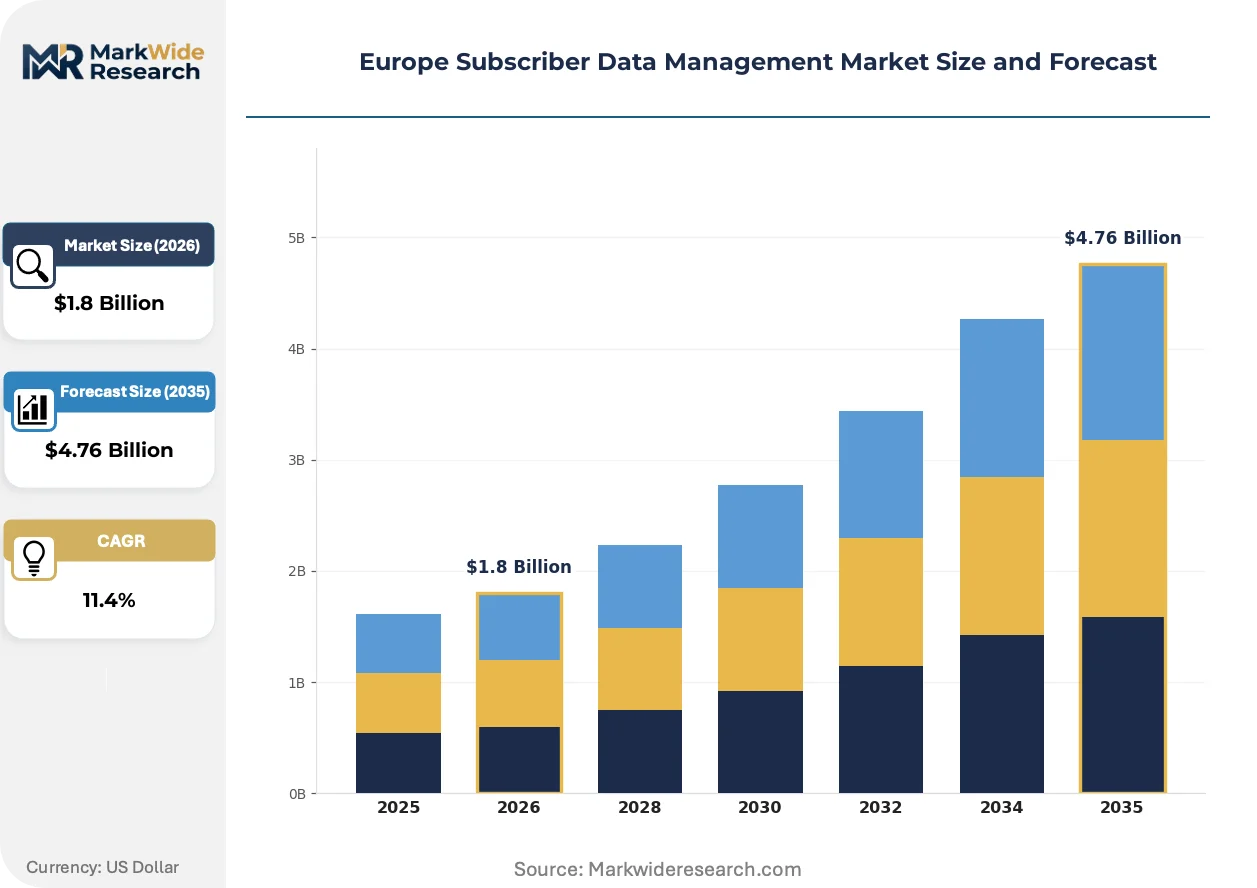
Market Dynamics
The EU AI Act's risk classification framework is forcing telecom operators to re-architect subscriber analytics modules with human-in-the-loop safeguards, compressing vendor qualification timelines and reshaping platform procurement criteria across Germany, France, and the United Kingdom.
Growth Catalysts
- GDPR Data Portability Mandates:Telecom operators must replace legacy data silos with unified subscriber profiles, accelerating replacement cycles for consent management and audit trail capabilities.
- 5G Network Slicing:Mobile operators require elastic subscriber data capacity to provision dynamic quality-of-service tiers for enterprise IoT and industrial automation verticals.
- France and Germany:National telecom regulators in these markets enforce sector-specific retention standards that layer onto baseline GDPR, driving demand for georedundant data governance solutions.
Market Restraints
- Specialized Engineering Talent:Scarcity of telecom systems architects with cloud-native signaling expertise limits vendor delivery capacity and extends implementation timelines.
- Cross-Border Data Residency:European Economic Area requirements fragment cloud deployment architectures, increasing operational complexity for pan-European operator groups.
- Legacy Infrastructure Interdependence:Decades-old policy engines and charging systems create technical debt that constrains migration velocity to modern subscriber data platforms.
Strategic Opportunities
- Italy and Spain:These markets show underpenetrated demand for AI-driven churn prediction engines, with tier-two mobile operators lagging Nordic and German peers in analytics maturity.
- Digital Services Act Compliance:Transparency and audit obligations for algorithmic content recommendation create adjacent demand for subscriber consent orchestration platforms.
- Edge Computing Convergence:Integration of subscriber data functions with multi-access edge computing nodes enables sub-10 millisecond authentication for autonomous vehicle and industrial control use cases.
Industry Challenges
- Certification Timeline Compression:Vendor qualification periods for GDPR and EU AI Act compliance now extend 18-24 months, delaying revenue recognition for platform deployments.
- Multi-Vendor Integration Complexity:Operators must synchronize subscriber data across radio access, core network, and business support systems from disparate suppliers, multiplying test and validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Subscriber Data Management Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Solution: Data Governance, Customer Data Platform, Data Analytics, Consent Management End User: Telecom Operators, ISPs, Media Companies, Enterprises Technology: AI & Machine Learning, Big Data Analytics, Blockchain, API Integration |
| Companies Covered | Hewlett Packard Enterprise Company, Huawei Technologies Co., Ltd., Nokia Corporation, Oracle Corporation, Cisco Systems, Inc., Telefonaktiebolaget LM Ericsson, Enea AB, Amdocs Limited, Optiva, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Subscriber Data Management Market Evolving Landscape
Three forces are actively reshaping how subscriber data platforms are architected and monetized: cloud-native signaling stacks, regulatory automation requirements, and evolving procurement models for analytics capabilities.
In-memory distributed ledger architectures for subscriber identity management are displacing traditional relational database deployments in tier-one European mobile operators. Deutsche Telekom and Vodafone Group units are migrating authentication and policy functions to Kubernetes-orchestrated containers, achieving sub-50 millisecond query latency while reducing hardware footprint. This displacement is compressing pricing for legacy appliance-based solutions and elevating software-centric vendors in competitive evaluations.
The EU AI Act's automated decision-making provisions now require human oversight interfaces for subscriber-facing analytics modules. Platform vendors must embed explainability dashboards and audit logging that satisfy both GDPR accountability requirements and emerging AI risk classification standards. German operators are responding fastest, with BNetzA guidance pushing tier-one carriers to pilot human-in-the-loop architectures before full enforcement deadlines.
Outcome-based contracts for subscriber data platform procurement are replacing traditional perpetual license models across Nordic operator groups. Telia Company and Telenor now negotiate pricing tied to measurable improvements in customer lifetime value and churn reduction, shifting vendor risk onto performance guarantees. This behavioral shift is most visible in Sweden and Norway, where operator procurement teams have consolidated analytics vendor panels to three preferred suppliers.
Europe Subscriber Data Management Market Segmentation
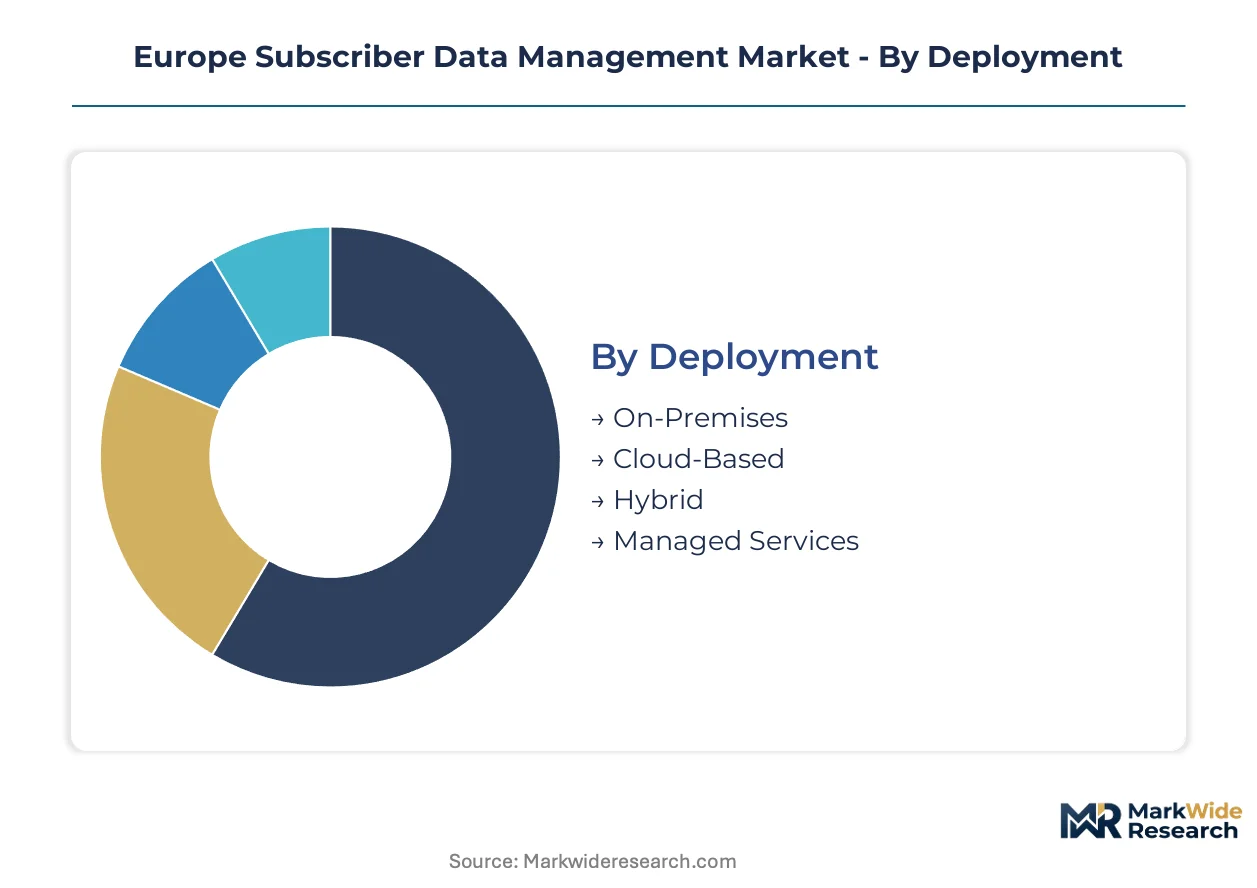
Segmentation in the Europe Subscriber Data Management Market reveals how GDPR enforcement and 5G rollout priorities reshape procurement patterns across deployment models, solution types, and underlying technologies. Understanding these divides clarifies where vendor investments concentrate and where compliance burdens create pricing premiums.
Deployment:
GDPR data residency mandates fragment procurement criteria across deployment architectures, with German and French regulators enforcing stricter geolocation requirements than southern European counterparts.
- Cloud-Based:Kubernetes-orchestrated containers host authentication and policy functions at sub-50 millisecond latency. Deutsche Telekom and Vodafone units across Germany and the United Kingdom favor elastic capacity for 5G network slicing and IoT onboarding spikes.
- Hybrid:Split architectures maintain sensitive subscriber identity on-premises while pushing analytics workloads to cloud regions. Nordic operator groups deploy this model most aggressively to balance latency requirements against cross-border data fragmentation.
- On-Premises:Legacy appliance-based installations persist in Italian and Spanish tier-two operators with extended depreciation cycles.
- Managed Services:Outsourced platform operations appeal to ISPs and smaller media companies lacking internal telecom systems engineering capacity.
Established volume favors On-Premises; emerging adoption favors Cloud-Based.
Solution:
Compliance layering drives solution prioritization, with Data Governance commanding premium pricing due to EEA cross-border residency requirements and audit trail mandates.
- Data Governance:Distributed ledger architectures maintain consistency across georedundant installations while satisfying GDPR minimization and anonymization standards. German BNetzA guidance accelerates replacement cycles for legacy consent management systems.
- Customer Data Platform:Unified profile systems consolidate identity, entitlement, and preference data across network functions and business support systems. France and the United Kingdom show concentrated demand from converged telecom-media operators.
- Data Analytics:Predictive churn models and real-time tariff personalization engines climb the fastest in Nordic markets with advanced analytics maturity.
- Consent Management:Audit trail capabilities and portability interfaces face compressed vendor qualification timelines under EU Digital Services Act transparency obligations.
Mature deployments concentrate in Customer Data Platform; steepest expansion trajectory appears in Data Governance.
End User:
Procurement authority and technical sophistication separate end-user tiers, with Telecom Operators driving platform roadmaps while Enterprises follow standardized integration patterns.
- Telecom Operators:Tier-one mobile network operators across Germany, France, and the United Kingdom define performance specifications and latency thresholds. 5G monetization requirements push these buyers toward AI-driven personalization and network slicing enablement.
- Enterprises:Industrial automation and autonomous vehicle verticals in Germany demand sub-10 millisecond authentication through edge-integrated subscriber data functions.
- ISPs:Fixed-line broadband providers in Spain and Italy lag mobile peers in cloud-native migration velocity.
- Media Companies:Algorithmic content recommendation engines create adjacent demand for consent orchestration platforms under Digital Services Act compliance pressure.
Revenue concentration sits with Telecom Operators; capability gap widest among Media Companies.
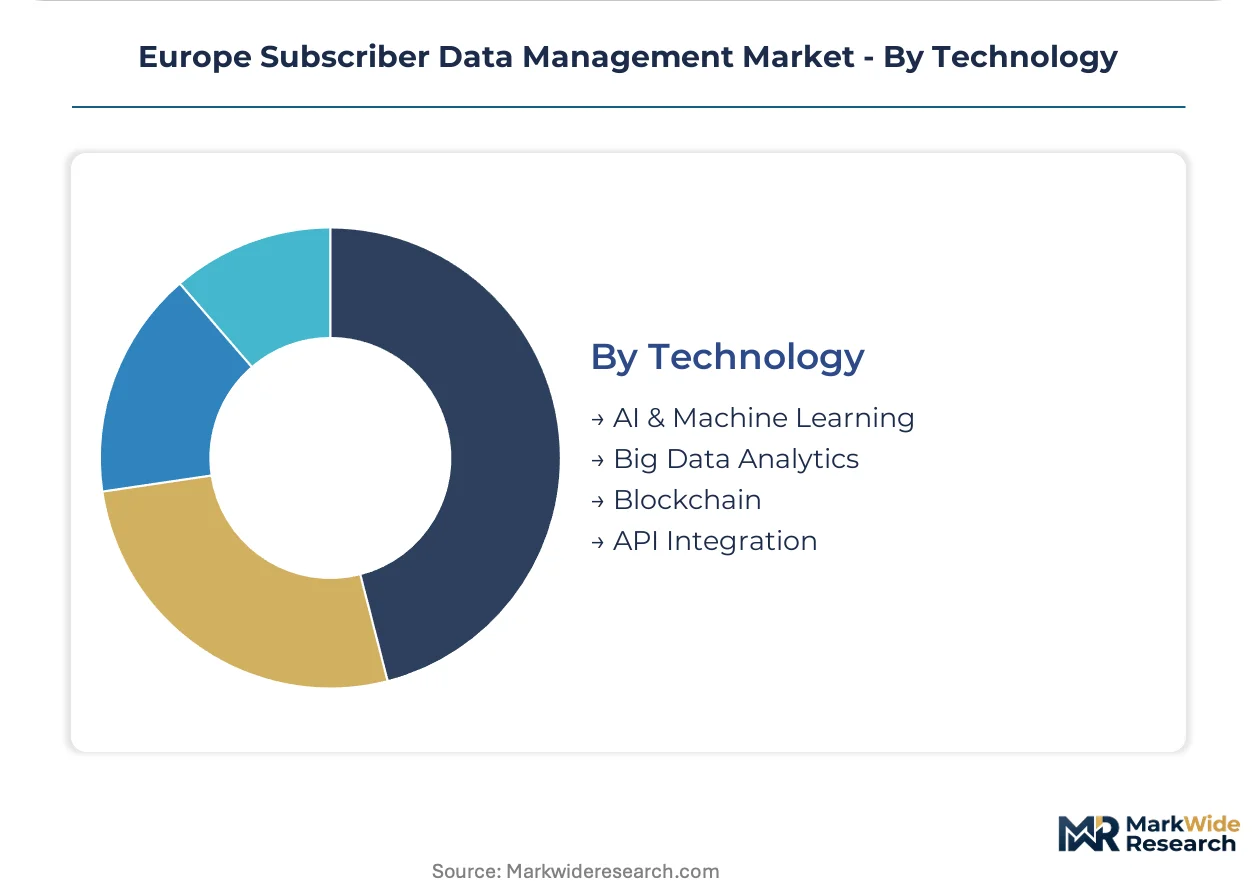
Technology:
AI risk classification under the EU AI Act now determines which automated decision-making features remain permissible without human-in-the-loop architectures.
- AI & Machine Learning:Explainability dashboards and audit logging satisfy both GDPR accountability and emerging AI Act standards. German operators pilot human-in-the-loop architectures fastest following BNetzA guidance.
- Big Data Analytics:Unified subscriber data lakes enable predictive models atop consolidated usage records and entitlement histories. France and the United Kingdom show concentrated deployment among converged operator groups.
- API Integration:Standardized interfaces synchronize subscriber data across radio access, core network, and business support systems from disparate suppliers.
- Blockchain:Distributed ledger approaches to identity verification gain traction in pilot deployments for cross-operator roaming authentication.
Current investment prioritizes Big Data Analytics; regulatory uncertainty clouds Blockchain deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BNetzA guidance from Germany anchors procurement velocity across the region, with GDPR enforcement and 5G rollout timelines creating divergent national patterns. Operators in northern markets accelerate cloud-native migrations while southern peers navigate extended legacy depreciation cycles.
Germany
Deutsche Telekom and Vodafone Deutschland drive demand for elastic subscriber data capacity supporting industrial IoT verticals. BNetzA enforces sector-specific retention standards that layer onto baseline GDPR requirements, compressing vendor qualification timelines. Munich and Frankfurt clusters host the densest concentration of multi-access edge computing pilots integrating sub-10 millisecond authentication functions.
United Kingdom
Converged telecom-media operators in London and the Southeast prioritize unified customer data platforms for personalized service delivery. Ofcom guidelines on data portability accelerate replacement cycles for legacy consent management architectures. The M4 corridor hosts the region's most active deployments of AI-driven churn prediction engines atop subscriber data lakes.
France
Orange and Bouygues Telecom expand investments in georedundant data governance solutions to satisfy CNIL audit trail mandates. ANSM guidance on clinical data interoperability creates adjacent demand for subscriber identity platforms in healthcare-adjacent IoT verticals. The Paris-Saclay cluster concentrates the highest density of human-in-the-loop architecture pilots responding to EU AI Act risk classifications.
Sweden
Telia Company and Telenor negotiate outcome-based contracts tied to measurable customer lifetime value improvements, shifting vendor risk onto performance guarantees. PTS oversight of cross-border data flows shapes hybrid deployment preferences balancing latency against residency requirements. Stockholm anchors the Nordic region's most mature analytics vendor consolidation, with operator procurement panels now limited to three preferred suppliers.
Italy
TIM and WindTre maintain on-premises subscriber data installations with extended depreciation cycles constraining cloud-native migration velocity. AGCOM enforcement of Digital Services Act transparency obligations creates emerging demand for consent orchestration platforms. Milan hosts the country's primary concentration of tier-two mobile operators lagging Nordic peers in AI-driven personalization maturity.
Europe Subscriber Data Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure consolidating around radio access network integration capabilities and cloud-native signaling expertise. The upper tier binds subscriber data functions to core infrastructure roadmaps, while specialists concentrate on policy engines and data layer software. Two strategic archetypes dominate: full-stack telecom infrastructure vendors and pure-play signaling software houses. Competitive moves center on strategic partnerships with mobile network operators and portfolio diversification into edge-integrated authentication functions.
Within the integrated infrastructure tier, Nokia Corporation and Cisco Systems, Inc. occupy positions that leverage existing radio access and enterprise security footprints respectively. Enea AB exemplifies the specialist archetype, anchoring cloud-native signaling presence in Nordic operator upgrade cycles. Huawei Technologies Co., Ltd. represents the scale-driven multinational vendor segment, though its positioning varies by national procurement restrictions across European markets.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise Company |
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| Oracle Corporation |
| Cisco Systems, Inc. |
| Telefonaktiebolaget LM Ericsson |
| Enea AB |
| Amdocs Limited |
| Optiva, Inc. |
| Others |
Value Network & Pricing Analysis
Kubernetes container orchestration at scale compresses per-subscriber data management costs below legacy appliance thresholds, concentrating procurement power among tier-one German and French operators while elevating software-centric vendors in competitive evaluations. This scale dynamic tightens price floors for on-premises deployments and expands margin capture for cloud-native signaling specialists serving Nordic upgrade cycles.
Pricing Analysis
Geographic price spreads between Nordic outcome-based contracts and southern European perpetual licenses reflect divergent analytics maturity levels across the region. Three-tier pricing structure across premium, standard, and economy levels segments by GDPR certification grade and edge-computing integration depth. Cost compression in standard tiers intensifies because Kubernetes-orchestrated alternatives displace relational database appliances. Tier-two mobile operators in Italy and Spain exhibit highest price sensitivity; converged telecom-media operators in the United Kingdom show lowest sensitivity due to churn reduction ROI visibility.
Supply Chain Analysis
Specialized telecom systems engineering talent in Germany, Sweden, and Finland anchors cloud-native signaling software development, creating chokepoints for vendor delivery capacity. Component dependencies draw from in-memory database engines, distributed ledger identity modules, and Kubernetes orchestration layers. Single-source vulnerability concentrates in Nordic engineering pods with cloud-native expertise. Distribution runs through direct vendor-operator partnerships for tier-one deployments, supplemented by systems integrator channels for tier-two and enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of architects fluent in both 3GPP signaling protocols and Kubernetes-native deployment patterns constrains platform delivery velocity across the region, forcing buyers into extended vendor qualification cycles and consolidating procurement panels.
For Market Incumbents: Consolidate delivery capacity through acquisition of Nordic cloud-native signaling specialists to offset engineering talent scarcity. Deepen radio access network integration roadmaps to bind subscriber data functions to core infrastructure refresh cycles, defending against pure-play software vendors. Prioritize GDPR and EU AI Act certification investments to compress 18-24 month qualification timelines. For New Entrants and Emerging Players: BNetzA fast-track compliance pathways for human-in-the-loop architectures open immediate traction in German tier-one operator pilots. White-space concentration sits in Italian and Spanish tier-two mobile operators lagging Nordic peers in AI-driven personalization maturity. Target edge-integrated authentication functions for industrial IoT verticals through multi-access edge computing partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native signaling software houses with proven Kubernetes deployments over legacy appliance vendors. Long-term viability hinges on regulatory automation capabilities spanning GDPR, EU AI Act, and sector-specific telecom retention mandates. Acquisition target archetype: specialists with distributed ledger identity management and existing BNetzA or CNIL audit trail validation. Monitor BNetzA enforcement timelines for EU AI Act risk classifications as inflection indicator for human-in-the-loop architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Kubernetes-orchestrated deployments at Deutsche Telekom and Vodafone achieve sub-50 millisecond latency thresholds. |
| Regulatory Compliance Certification | GDPR and EU AI Act validation compresses vendor qualification timelines across German and French operator procurement. |
| Edge Computing Integration | Multi-access edge computing nodes in Munich and Frankfurt enable sub-10 millisecond authentication for industrial IoT. |
| Outcome-Based Contracting | Telia Company and Telenor shift vendor risk onto customer lifetime value performance guarantees in Nordic markets. |
| Specialist Talent Acquisition | Cloud-native signaling expertise scarcity forces restructuring around remote implementation pods and partner ecosystems. |
Research Methodology
Cross-validation between primary interviews with network architecture directors, BSS transformation leads, regulatory compliance officers, and procurement executives at tier-one operators anchors the qualitative findings. Secondary validation draws from BNetzA guidance documents, CNIL audit trail mandates, ETSI standards filings, and hyperscaler capex disclosures for telecom cloud infrastructure. Bottom-up deployment tracking across German, French, and Nordic operator groups triangulates against top-down vendor revenue segmentation.
Sensitivity analysis across deployment model, operator tier, technology architecture, and national regulatory cluster dimensions shapes the analytical framework. CAGRs derive from elasticity modeling of 5G network slicing capacity requirements and GDPR-driven replacement cycle compression. Industry-specific inputs include BNetzA sector-specific retention standards and PTS cross-border data flow oversight patterns.
Decision-makers should treat outputs as directional under sustained GDPR enforcement and EU AI Act implementation timelines; material deviation in regulatory pacing or 5G monetization velocity would warrant model refresh. Practitioners should keep alternative scenarios live as BNetzA and CNIL guidance on automated decision-making oversight evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
5G Edge Cloud Network and Services Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Managed Network Services Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Japan Data Center Server Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market