
 Hong Kong Data Center Networking Market | 2026-2036
Hong Kong Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Data Center Networking Market Insights
Multi-source procurement of optical switching gear is realigning how Hong Kong facility operators build redundancy into their backbone networks. Cisco Systems leverages its merchant silicon partnerships to sustain supply continuity across Greater Bay Area deployments. Arista Networks anchors its position through cloud-optimized 400G platforms purpose-built for hyperscale colocation environments. Huawei Technologies competes aggressively on price-performance ratios for spine-leaf architectures serving local telecom providers.
Hong Kong Data Center Networking encompasses the switching, routing, security, and traffic management infrastructure that interconnects servers, storage arrays, and external networks within a controlled facility environment, typically operating at 10G to 400G port speeds with sub-microsecond latency requirements for high-frequency trading and real-time analytics workloads. The primary commercial purpose centers on enabling reliable, low-latency data exchange between distributed computing resources while enforcing segmentation policies that isolate tenant traffic in multi-client facilities. Switches command the largest product type revenue pool as leaf-spine deployments proliferate, though firewalls are capturing disproportionate growth from zero-trust security mandates. Hybrid deployment models are expanding fastest among end users seeking to bridge on-premises latency advantages with burst capacity from cloud interconnection points.
The Office of the Communications Authority enforces facility licensing and spectrum coordination rules that directly shape data center construction timelines and interconnection density limits across Hong Kong's constrained land base. BIS certification requirements for imported networking equipment, combined with OFCA's cybersecurity resilience guidelines for critical infrastructure operators, elevate compliance costs for non-domestic vendors while creating specification advantages for pre-certified suppliers. Stakeholders must monitor how proposed amendments to Hong Kong's Personal Data (Privacy) Ordinance cross-border transfer provisions reshape customer requirements for data sovereignty-compliant network architectures.
Market Dynamics
The OFCA licensing framework is compressing facility certification timelines while simultaneously mandating higher cybersecurity resilience standards, forcing operators to rearchitect spine-leaf backbones under tighter compliance windows.
Growth Catalysts
- Financial services colocation expansion:Asset managers and trading firms are densifying rack deployments in Tseung Kwan O to exploit sub-microsecond latency for high-frequency execution platforms.
- Submarine cable convergence:The Asia-Pacific Gateway and Southeast Asia-Japan Cable 2 landings at Tsuen Wan are attracting hyperscale interconnection demand from cloud providers seeking direct fiber access to mainland China and Southeast Asian markets.
- 400G port speed migration:Leaf-spine fabric upgrades are accelerating as AI training clusters and real-time analytics workloads saturate existing 100G backplanes.
Market Restraints
- BIS certification delays:Imported optical switching equipment faces extended customs inspection protocols that stretch deployment schedules by 8-12 weeks.
- Land supply scarcity:Industrial plot availability in Tseung Kwan O has tightened to sub-5% vacancy, constraining greenfield expansion for Tier III+ facilities.
- Power density limitations:Substation capacity constraints in Tsuen Wan cap rack power density at 15kW per cabinet, forcing liquid cooling retrofits that inflate capex by 40%.
Strategic Opportunities
- Greater Bay Area edge node deployment:Shenzhen and Guangzhou manufacturing corridors present untapped demand for sub-10ms latency interconnection to Hong Kong financial exchanges.
- Zero-trust security fabric integration:Microsegmentation mandates under OFCA's critical infrastructure guidelines are creating pull for converged switching-firewall appliances.
- Submarine cable landing station diversification:New cable systems landing at Chung Hom Kok offer alternative fiber paths that reduce single-point-of-failure risk for multi-homed facilities.
Industry Challenges
- Optical engineering talent scarcity:The territory's universities produce fewer than 200 photonics specialists annually, forcing operators to recruit from Singapore and Taiwan at 35% salary premiums.
- Legacy MPLS migration complexity:Financial institutions with decade-old core networks face 18-24 month transition timelines to EVPN-VXLAN fabrics, delaying 400G refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Data Center Networking Market |
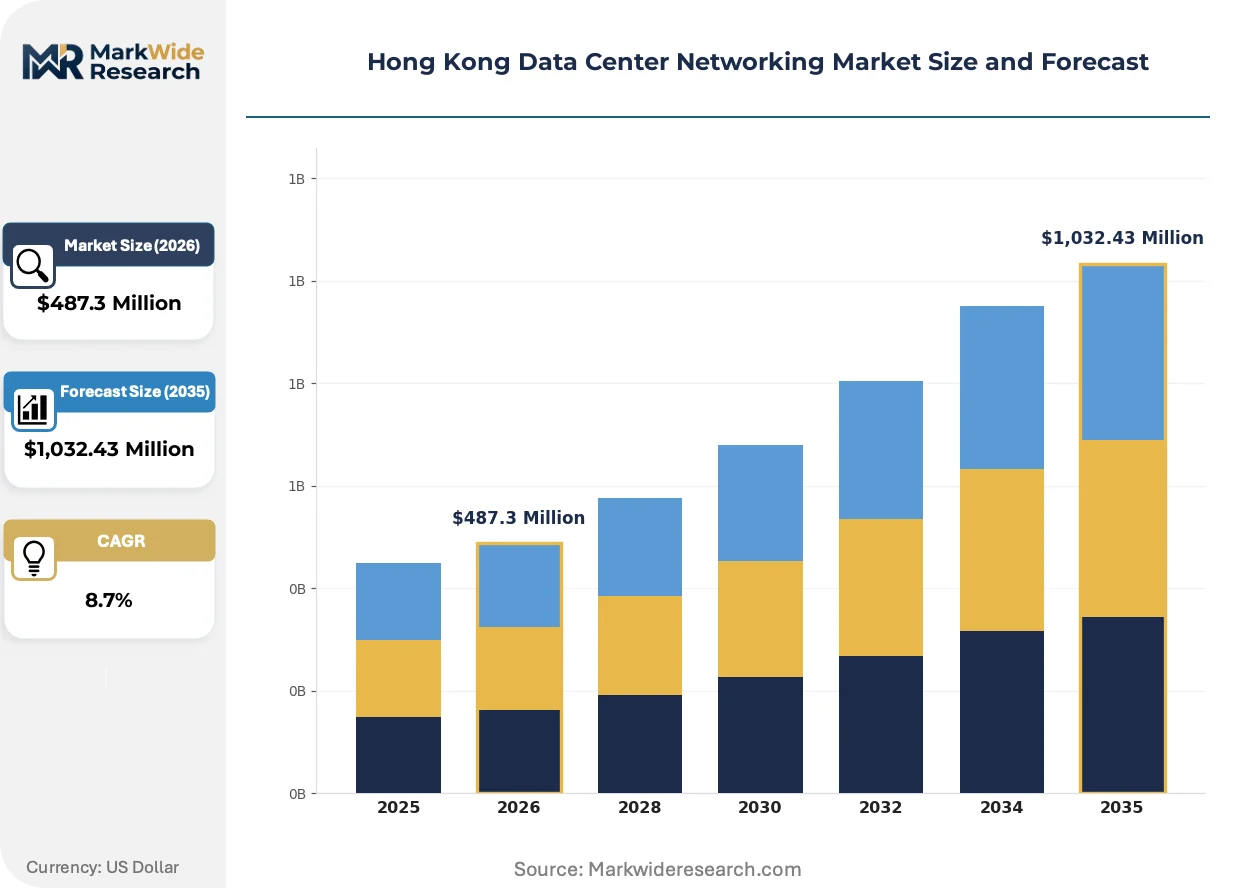
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Load Balancers Deployment Model: On-Premises, Cloud-Based, Hybrid, Colocation End User: Telecom Providers, Enterprises, Cloud Service Providers, Government Solution Type: Network Security, Data Management, Monitoring, Virtualization |
| Companies Covered | Cisco Systems, Arista Networks, Huawei Technologies, Juniper Networks, Dell Technologies, Hewlett Packard Enterprise, NVIDIA, Broadcom, IBM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Data Center Networking Market Trends and Innovations
Disaggregated white-box switching is eroding incumbent hardware lock-in across Hong Kong colocation facilities, while regulatory pressure on data sovereignty is reshaping interconnection architecture requirements.
Software-defined networking fabrics are decentralizing control plane intelligence from proprietary chassis to merchant silicon-based white-box switches. Hyperscale tenants at iAdvantage and SUNeVision facilities are deploying SONiC-based operating systems across 32-port 400G leaf switches, compressing procurement cycles from 16 weeks to 6 weeks and enabling multi-vendor interoperability that slashes switching capex by 30%.
OFCA's proposed amendments to the Personal Data (Privacy) Ordinance cross-border transfer provisions are mandating traffic localization for financial and healthcare workloads. Facility operators must now deploy in-territory encryption gateways and audit-ready logging infrastructure, with Tier III+ certified data centers in Tseung Kwan O capturing disproportionate leasing interest from compliance-sensitive tenants.
Consumption-based interconnection pricing is displacing traditional cross-connect fee structures. Wholesale buyers at Hong Kong Internet Exchange points are migrating from flat-rate 10G port contracts to metered 95th-percentile billing aligned with actual traffic volumes, with this model penetrating fastest among cryptocurrency exchanges and cloud gaming platforms seeking burst capacity without committed spend.
Hong Kong Data Center Networking Market Segmentation
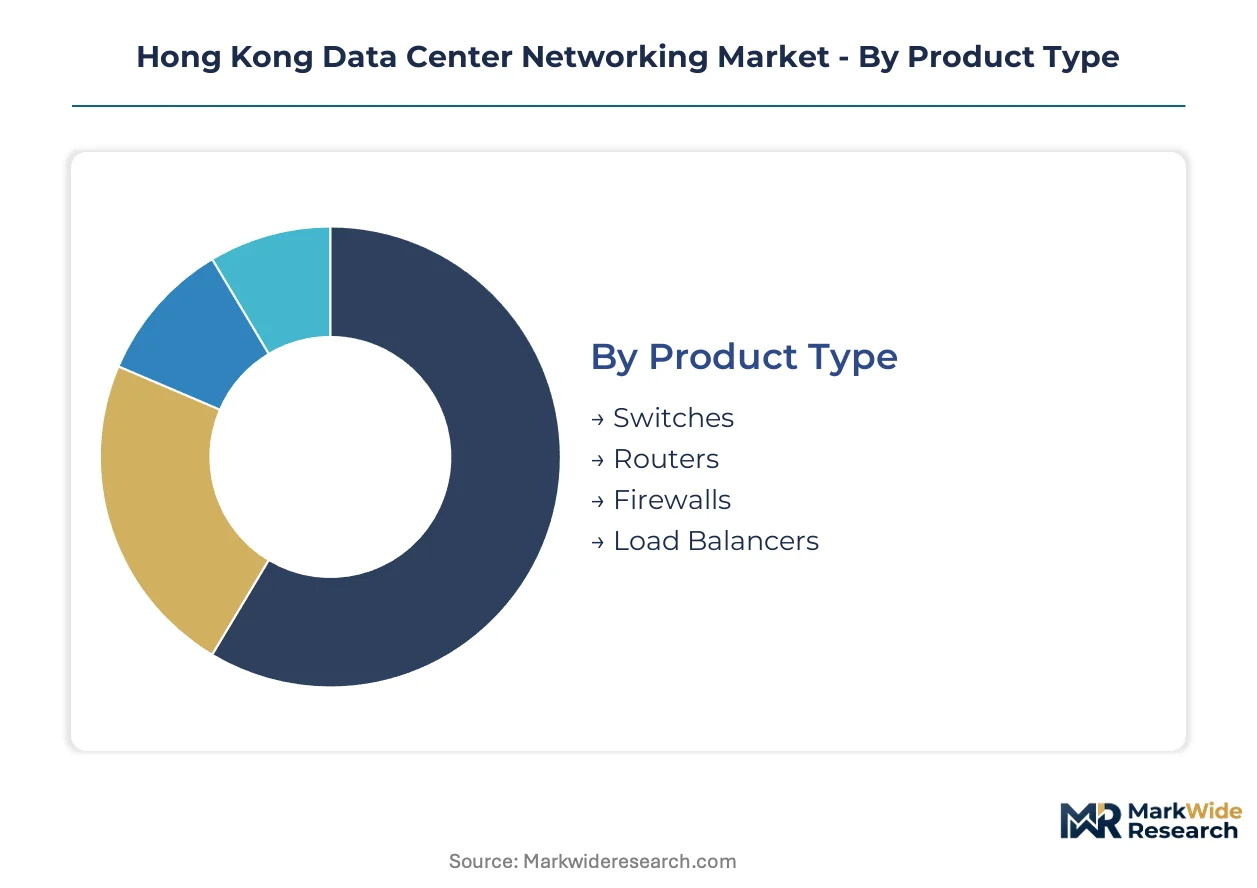
Segmentation reveals how Hong Kong facility operators allocate capital across switching fabrics, deployment architectures, and compliance-sensitive customer tiers. Supply concentration in optical component sourcing directly shapes which product categories capture disproportionate procurement spend.
Product Type:
Supply concentration among merchant silicon vendors is compressing differentiation in switching hardware while elevating margin capture for security appliances with embedded compliance features.
- Switches:Leaf-spine architectures dominate new builds, with 400G port densities now standard for AI training clusters in Tseung Kwan O facilities. Financial services tenants at iAdvantage and SUNeVision drive demand for sub-microsecond latency switching fabrics that support high-frequency trading co-location.
- Routers:Border gateway platforms handling submarine cable handoffs at Tsuen Wan landing stations require carrier-grade redundancy. OFCA's cybersecurity resilience guidelines are forcing router refresh cycles that embed hardware-based encryption and telemetry export capabilities.
- Firewalls:Converged switching-firewall appliances are gaining traction under zero-trust mandates.
- Load Balancers:Application delivery controllers see steady replacement demand from cloud service providers.
Today's leader: Switches. Tomorrow's challenger: Firewalls.
Deployment Model:
Cost tier stratification is separating capex-intensive on-premises builds from opex-flexible hybrid arrangements that appeal to compliance-constrained financial institutions.
- On-Premises:Sovereign data requirements at Hong Kong Monetary Authority-regulated institutions sustain dedicated switching infrastructure. Tier III+ certified facilities in Tseung Kwan O command 20-30% leasing premiums for tenants mandating physical control over encryption key management.
- Hybrid:Burst capacity interconnection to Alibaba Cloud and Tencent Cloud regions is climbing fastest among asset managers seeking mainland China market access without full data localization. Network fabrics must bridge EVPN-VXLAN on-premises segments with cloud-native VPC architectures.
- Cloud-Based:Software-defined WAN overlays are displacing MPLS for regional branch consolidation.
- Colocation:Cross-connect density at Hong Kong Internet Exchange points attracts cryptocurrency exchanges and gaming platforms.
On-premises retains the revenue base. Hybrid deployments are expanding most quickly.
End User:
Customer type determines procurement sophistication, with cloud service providers driving merchant silicon adoption while government buyers prioritize pre-certified vendor relationships.
- Cloud Service Providers:Hyperscale tenants at MEGA-i and HKCOLO facilities deploy disaggregated white-box switching at 400G densities, compressing hardware procurement cycles through direct merchant silicon relationships. Their engineering teams custom-compile SONiC distributions that bypass traditional vendor support contracts.
- Telecom Providers:HKT, PCCW, and China Mobile Hong Kong anchor spine-leaf demand for 5G core network virtualization and submarine cable landing station interconnection. Their procurement specifications favor redundant supervisor modules and hitless software upgrade capabilities.
- Enterprises:Insurance and asset management firms prioritize compliance-ready network segmentation.
- Government:OFCA critical infrastructure designation restricts vendor selection to pre-approved suppliers.
Cloud service providers dominate volume. Enterprises represent the steepest expansion trajectory.
Solution Type:
Application maturity separates established network security spending from emerging monitoring and virtualization categories that require operational technology integration.
- Network Security:Microsegmentation fabrics with distributed firewalling are becoming mandatory for multi-tenant facilities serving cross-border financial data flows. OFCA's proposed Personal Data (Privacy) Ordinance amendments are accelerating encryption gateway deployments at rack edge.
- Monitoring:Real-time telemetry pipelines for AI workload optimization are displacing legacy SNMP polling. Facilities serving quantitative trading firms require nanosecond-precision latency monitoring that correlates network events with execution performance.
- Data Management:Software-defined storage networking protocols are standardizing on NVMe-oF for high-performance analytics clusters.
- Virtualization:Container network interface plugins for Kubernetes are gaining adoption among fintech startups.
Network security commands current budgets. Monitoring solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tseung Kwan O anchors Hong Kong's data center networking demand through its concentration of submarine cable landings and Tier III+ certified facilities serving financial services colocation.
Tseung Kwan O Industrial Cluster
Asset managers and high-frequency trading firms densify rack deployments to exploit sub-microsecond latency execution platforms. The Office of the Communications Authority mandates cybersecurity resilience standards that compress facility certification timelines. Spine-leaf fabric upgrades to 400G port densities dominate new construction as AI training clusters saturate existing backplanes.
Tsuen Wan Industrial Zone
Hyperscale cloud providers seek direct fiber access through Asia-Pacific Gateway and Southeast Asia-Japan Cable 2 landings for mainland China and Southeast Asian market interconnection. BIS certification requirements for imported optical switching equipment stretch deployment schedules through extended customs inspection protocols. Power density limitations cap rack capacity at 15kW per cabinet, forcing liquid cooling retrofits.
Chung Hom Kok
New submarine cable systems offer alternative fiber paths that reduce single-point-of-failure risk for multi-homed facilities. OFCA's proposed Personal Data (Privacy) Ordinance amendments mandate traffic localization for financial workloads. Tier III+ certified data centers capture disproportionate leasing interest from compliance-sensitive tenants requiring in-territory encryption gateways.
Greater Bay Area Corridor
Shenzhen and Guangzhou manufacturing corridors generate untapped demand for sub-10ms latency interconnection to Hong Kong financial exchanges. Cross-border data transfer regulations under mainland China's cybersecurity law create architectural complexity for hybrid cloud deployments. Network fabrics bridge EVPN-VXLAN on-premises segments with cloud-native VPC architectures at Alibaba Cloud and Tencent Cloud regions.
Hong Kong Data Center Networking Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue disaggregated white-box switching and merchant silicon partnerships. The vendor landscape concentrates around three strategic archetypes: integrated systems vendors with end-to-end portfolios, cloud-optimized specialists delivering hyperscale-focused platforms, and price-competitive challengers serving regional telecom providers. Competitive moves center on supply continuity assurance through multi-source procurement and compliance pre-certification to accelerate OFCA licensing timelines.
Within the integrated systems tier, Cisco Systems and Dell Technologies represent the incumbent anchor position, while Arista Networks exemplifies the cloud-optimized specialist archetype. Huawei Technologies occupies a position as the price-competitive challenger serving local infrastructure requirements.
| Leading Market Players |
|---|
| Cisco Systems |
| Arista Networks |
| Huawei Technologies |
| Juniper Networks |
| Dell Technologies |
| Hewlett Packard Enterprise |
| NVIDIA |
| Broadcom |
| IBM |
| Others |
Pricing and Supply Chain Analysis
Merchant silicon costs cascade through three distinct pricing tiers as 400G switch fabrics migrate from proprietary ASICs to Broadcom and NVIDIA-based white-box platforms. OFCA certification requirements for critical infrastructure operators create specification premiums that separate Tier III+ qualified vendors from uncertified alternatives.
Pricing Analysis
Input-cost pass-through from optical component shortages is compressing margins on 100G legacy platforms while 400G leaf-spine bundles retain pricing power. Pricing stratifies across OFCA-certified premium tiers, standard enterprise grades, and uncertified economy alternatives. Cost compression in the economy tier is intensifying because hyperscale tenants are bypassing traditional vendor support contracts through SONiC custom compilations. Cloud service providers exhibit the highest price sensitivity, while financial institutions regulated by the Hong Kong Monetary Authority accept substantial premiums for sovereign-compliant encryption gateways.
Supply Chain Analysis
BIS certification and OFCA cybersecurity resilience guidelines are gating supplier qualification, stretching vendor onboarding timelines and elevating procurement risk for non-pre-certified equipment. Optical switching hardware draws from Taiwan for merchant silicon fabrication, the United States for specialized PHY components, and mainland China for passive optical assemblies. Single-source vulnerability concentrates in 400G DSP supply where Broadcom and Marvell dominate programmable chip architectures. Distribution runs through direct hyperscale procurement channels, systems integrator partnerships, and telecom provider framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong Data Center Networking operates as a stable compounder anchored by irreversible financial services digitization and submarine cable infrastructure expansion. Regulatory tightening on cross-border data flows sustains premium pricing for compliance-ready network fabrics.
For Market Incumbents: Deepen merchant silicon partnerships to secure allocation priority during supply crunches, while accelerating OFCA pre-certification investments to compress competitor licensing timelines. Disaggregated white-box switching from cloud-optimized specialists poses substitution risk in hyperscale colocation segments. Vertical integration into optical component sourcing insulates against BIS inspection delays that stretch deployment schedules.
For New Entrants and Emerging Players: Capture edge node deployment opportunities across the Greater Bay Area corridor where Shenzhen and Guangzhou manufacturing corridors generate untapped demand for sub-10ms latency interconnection. Zero-trust security fabric integration represents the most penetrable white-space, with microsegmentation mandates creating pull for converged switching-firewall appliances. A compliance-first go-to-market angle targeting Tier III+ certification from launch accelerates facility operator adoption.
For Investors and Strategic Acquirers: Roll-up economics work for regional colocation platform consolidation because land scarcity in Tseung Kwan O and Tsuen Wan prevents greenfield competition and sustains pricing power for incumbent facilities. The 5-10 year viability window favors assets with existing submarine cable landing proximity and OFCA critical infrastructure designation. Monitor OFCA amendments to the Personal Data (Privacy) Ordinance as the signal to watch for demand inflection toward data sovereignty-compliant network architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Partnership Deepening | Direct relationships with Broadcom and NVIDIA secure 400G switch allocation priority during supply crunches. |
| OFCA Pre-Certification Investment | Early compliance with cybersecurity resilience guidelines compresses facility licensing timelines against competitors. |
| Zero-Trust Security Fabric Development | Converged switching-firewall appliances capture microsegmentation mandates under critical infrastructure guidelines. |
| Greater Bay Area Edge Expansion | Sub-10ms latency nodes in Shenzhen and Guangzhou bridge on-premises segments with cloud-native VPC architectures. |
| Submarine Cable Landing Diversification | Chung Hom Kok fiber paths reduce single-point-of-failure risk for multi-homed financial services facilities. |
Research Methodology
Coverage spans Hong Kong SAR, Greater Bay Area corridor cities, and submarine cable landing zones across the Asia-Pacific, with primary inputs from each. Data synthesis combined structured interviews with data center facility operators, network engineering leads at financial services firms, procurement officers at cloud service providers, and OFCA regulatory affairs specialists. Secondary validation drew from OFCA licensing databases, submarine cable landing station records, BIS certification registries, and hyperscaler capex disclosures. Bottom-up port shipment analysis and top-down facility capacity modeling were triangulated against vendor revenue segmentation.
Granularity-level modeling deployed product type, deployment architecture, end user category, and solution type as core segmentation dimensions, with submarine cable landing proximity and OFCA certification tier as industry-specific overlay variables. CAGRs were derived from weighted capacity expansion schedules and port speed migration curves across the projection horizon. AI training cluster density requirements and real-time analytics workload growth served as demand-side forecast inputs.
Regulatory amendment timing, merchant silicon supply allocation shifts, and cross-border data transfer policy changes are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding continued financial services colocation expansion and submarine cable landing convergence. A model refresh is warranted upon material change in OFCA licensing framework stringency or Personal Data (Privacy) Ordinance cross-border transfer provisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Mobile Data Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Global Virtual Private Server Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Cache Server Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Graph Database Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Netherlands Data Center Networking Market