
 Global Dental Surgical Instruments Market | 2026-2036
Global Dental Surgical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Surgical Instruments Market Analysis
Equipment leasing and pay-per-use financing is rewriting competitive dynamics for mid-sized dental practices seeking advanced surgical capabilities. Dentsply Sirona leverages its direct sales infrastructure to bundle instrument financing with digital workflow packages. Straumann Group anchors its position through captive leasing subsidiaries that reduce upfront barriers for clinic customers. KaVo competes via regional distributor credit programs that preserve cash flow for smaller practices.
Dental surgical instruments comprise precision-engineered handpieces, cutting tools, grasping devices, and aspiration systems fabricated from medical-grade stainless steel and titanium alloys to tolerances of 0.01 mm for safe intraoral manipulation. Their primary purpose is to enable controlled tissue modification, tooth extraction, and implant site preparation with minimal trauma. Powered instruments command the widest margin pools as motor systems integrate torque feedback and irrigation management that command premium positioning. Stainless steel retains dominant volume share across forceps and elevators, though titanium variants capture preference in implantology where weight reduction and biocompatibility justify higher unit economics. Digital imaging systems represent the fastest-expanding technology segment as cone-beam computed tomography and intraoral scanning merge preoperative planning with guided surgery workflows.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements impose multi-year validation timelines that filter out undercapitalized entrants. ISO 13485 quality management systems and IEC 60601 electrical safety standards further condition market access for powered and laser-based devices. Stakeholders must monitor convergence between surgical instrument connectivity and cybersecurity frameworks as networked devices proliferate in clinic environments.
Market Dynamics
EU MDR technical documentation requirements and FDA 510(k) validation timelines are compressing the competitive set by filtering out undercapitalized instrument manufacturers. Powered surgical systems with integrated torque feedback and irrigation management are capturing disproportionate margin pools as clinics prioritize precision outcomes over basic handpiece procurement.
Growth Catalysts
- EU MDR compliance mandates:Stricter technical documentation requirements for Class IIa and IIb surgical instruments are accelerating consolidation among manufacturers with established quality management systems.
- Titanium alloy adoption:Implantology practices in Germany and Japan are driving preference for lightweight, biocompatible instrument variants that reduce operator fatigue during extended procedures.
- Outpatient procedure volumes:Dental clinics across the United States are expanding surgical service lines as reimbursement shifts favor same-day implant and periodontal interventions.
Market Restraints
- Medical-grade stainless steel price volatility:Input cost fluctuations for surgical-grade alloys are compressing margins on standard forceps and elevator product lines.
- Validation timeline concentration:Multi-year FDA and EU MDR approval processes create capital lockup that disadvantages mid-tier manufacturers without captive regulatory affairs teams.
- Laser-based cutting systems:Erbium and diode laser platforms for soft tissue modification are substituting mechanical instruments in select periodontal applications.
Strategic Opportunities
- Brazil and Mexico:Underpenetrated private dental clinic networks in Latin America present expansion vectors for premium instrument portfolios with localized financing structures.
- Cone-beam CT integration:Convergence of intraoral scanning and 3D imaging is creating demand for guided surgery instrument kits with proprietary drill guides.
- Japan's aging demographic:METI-backed healthcare infrastructure investments are expanding implantology access for elderly populations requiring complex surgical interventions.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified quality management system assessors are concentrated in Western Europe and the United States, extending certification timelines for Asia-Pacific manufacturers.
- Powered instrument cybersecurity:IEC 60601 electrical safety standards now require networked device hardening that exceeds legacy motor system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Surgical Instruments Market |
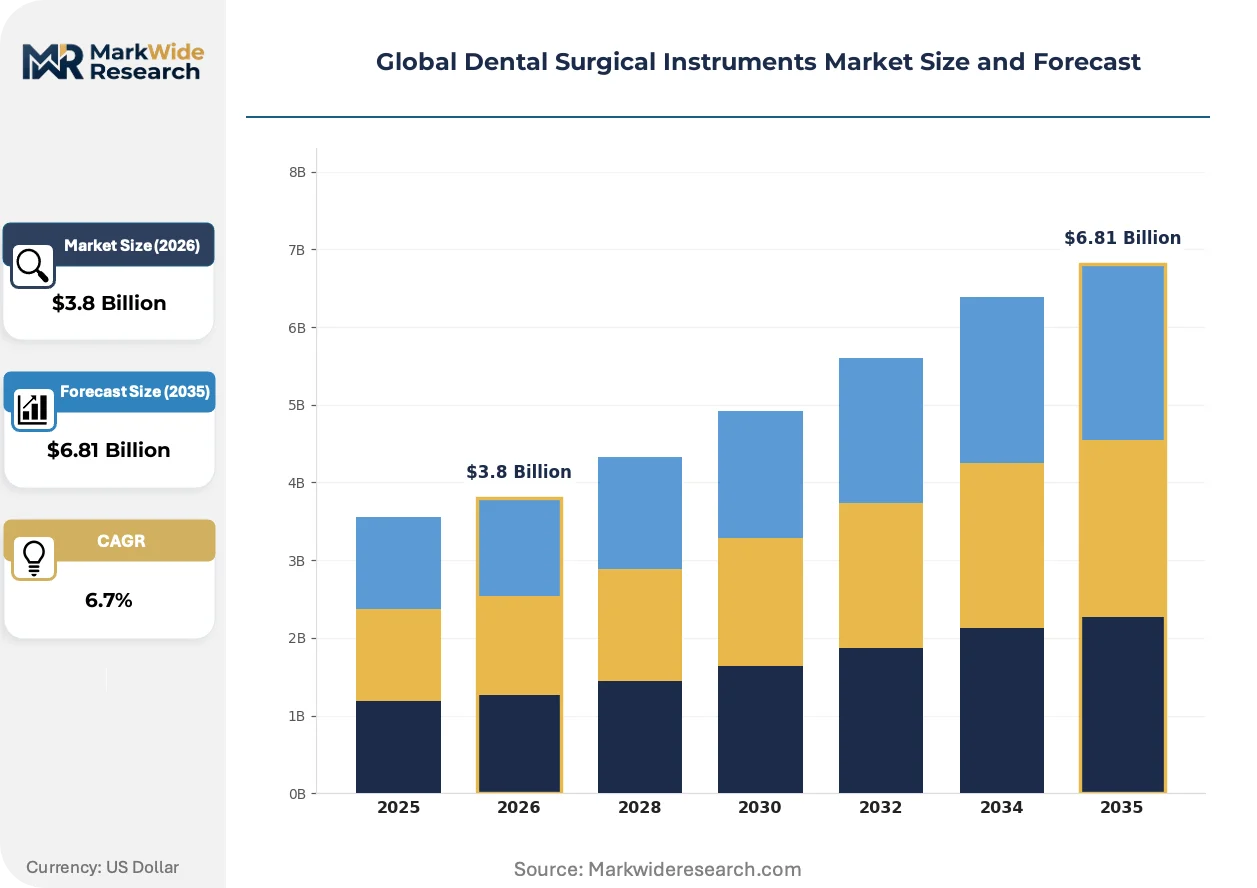
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Scissors, Forceps, Root Elevators, Curettes End User: Dental Clinics, Hospitals, Research Laboratories, Academic Institutions Material: Stainless Steel, Titanium, Plastic, Advanced Composites Technology: Handheld Instruments, Powered Instruments, Laser Devices, Digital Imaging Systems |
| Companies Covered | Planmeca Oy, KaVo, Dentsply Sirona, W&H, Bien-Air, Straumann Group, A-dec, GerDentUSA, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Surgical Instruments Market Emerging Trajectories
Digital workflow integration is redefining instrument value propositions by merging preoperative planning with intraoperative execution. Manufacturers are embedding connectivity modules and sensor feedback into previously mechanical device categories.
Robotic-assisted implant placement systems are migrating from research protocols to commercial deployment in high-volume German and Swiss clinics. Straumann and Dentsply Sirona are field-testing autonomous drilling units with real-time bone density compensation. This technology is migrating from academic medical centers to premium private practices, compressing the traditional learning curve for complex surgical interventions.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIb surgical instruments. Manufacturers must now maintain active implant registries and adverse event reporting infrastructure that exceeds previous vigilance obligations. Powered handpiece and laser system suppliers face the steepest compliance cost escalation as electrical safety and software validation documentation expand.
Clinic procurement committees are consolidating vendor relationships around full-arch workflow providers rather than discrete instrument suppliers. Group purchasing organizations in the United States are negotiating enterprise contracts that bundle surgical instruments with digital imaging and laboratory services. This concentration is most visible in dental service organization networks across Texas, Florida, and California, where standardized instrument protocols reduce training overhead across multi-site operations.
Global Dental Surgical Instruments Market Segmentation
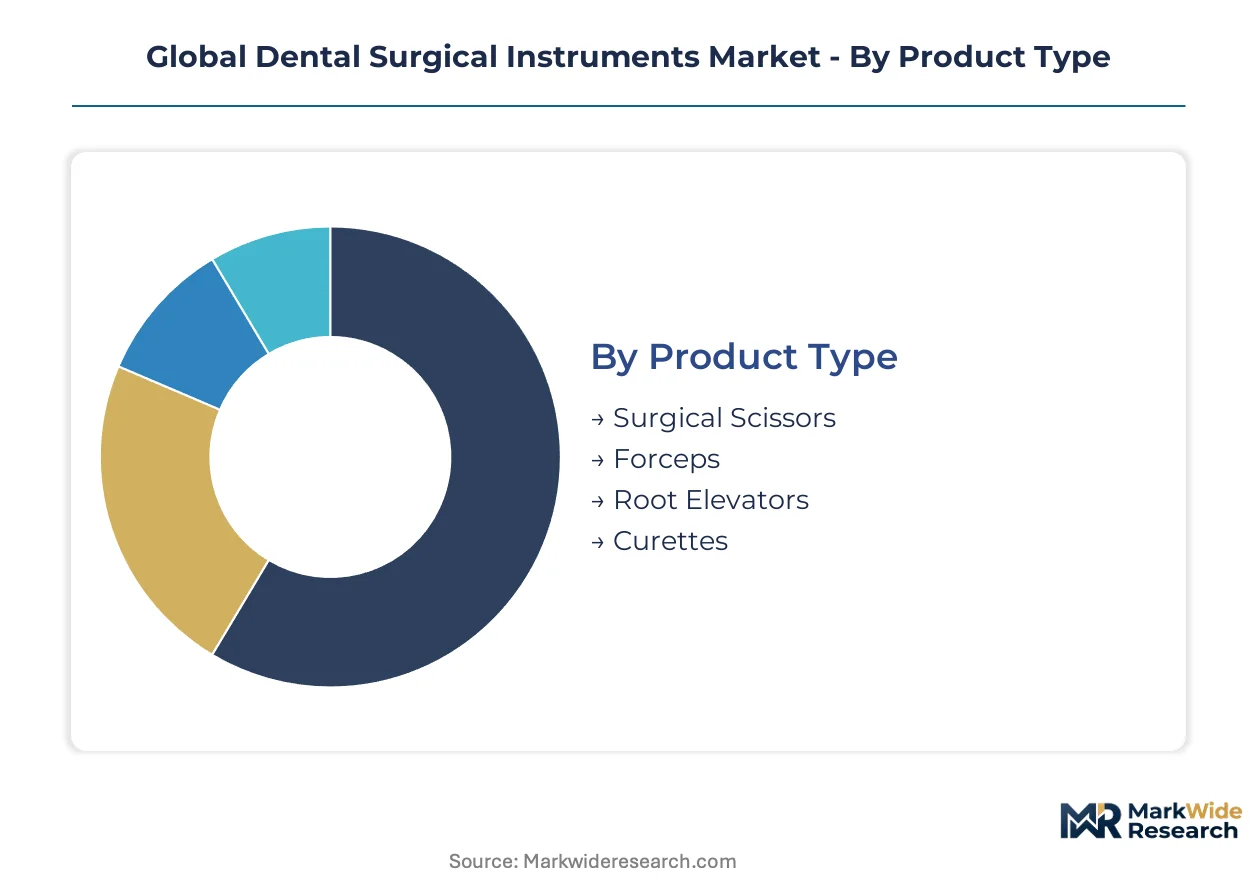
Dental surgical instruments fragment across four intersecting dimensions that determine procurement priorities and margin architecture. Product type and technology capture the largest share of manufacturer R&D investment, while material selection and end-user channel dictate pricing power and service requirements.
Product Type:
Application-specific design requirements shape procurement patterns across oral surgery suites, with instrument geometry and cutting edge geometry calibrated to tissue resistance and access constraints.
- Surgical Scissors:Precision-ground tungsten carbide inserts maintain edge integrity through thousands of cutting cycles. German implantology clinics specify beveled-tip configurations for periosteal elevation in flap procedures.
- Forceps:Beak geometry varies by tooth morphology and root configuration, with pediatric and surgical extraction variants commanding distinct SKU portfolios. US dental service organizations standardize on universal designs to reduce inventory complexity across multi-site networks.
- Root Elevators:Lever-action instruments with ergonomic handle profiles reduce wrist strain during luxation.
- Curettes:Gracey and universal patterns serve periodontal debridement with cutting edge angulation matched to root surface topography.
Surgical scissors hold installed capacity. Forceps are rotating up the share rankings.
End User:
Customer type determines purchasing authority structures, with institutional procurement committees imposing vendor consolidation that independent practitioners resist.
- Dental Clinics:Private practices and group practices drive volume through direct distributor relationships, with financing terms often outweighing unit price in vendor selection. Japanese metropolitan clinics prioritize instrument sterilization compatibility with existing autoclave infrastructure.
- Hospitals:Ambulatory surgery centers and integrated delivery networks negotiate enterprise contracts bundling surgical instruments with implant systems. FDA 510(k) documentation requirements extend procurement validation timelines for hospital materials management departments.
- Research Laboratories:Academic and commercial research facilities source specialized instruments for biomechanical testing and prototype validation.
- Academic Institutions:Dental schools require didactic instrument sets with standardized configurations for preclinical training programs.
Dental clinics hold installed capacity. Hospitals are climbing the fastest.
Material:
Cost tier and performance specifications diverge sharply across metallic and non-metallic substrates, with biocompatibility certification and sterilization durability filtering supplier qualification.
- Stainless Steel:Medical-grade 440A and 17-4 PH alloys dominate standard instrument production, with passivation treatments ensuring corrosion resistance through repeated sterilization cycles. Indian manufacturers leverage domestic stainless capacity to serve price-sensitive Asian and African markets.
- Titanium:Grade 5 titanium alloys reduce instrument weight by 40% versus steel equivalents, justifying premium positioning in implantology and microsurgical applications. Swiss and German manufacturers control precision forging capabilities for complex titanium geometries.
- Plastic:Single-use polymer instruments serve infection control protocols in resource-constrained settings.
- Advanced Composites:Carbon fiber reinforced polymers enable radiolucent instrument designs for intraoperative imaging compatibility.
Stainless steel holds installed capacity. Titanium is gaining share fastest.
Technology:
Maturity gradients separate mechanical instruments from digitally integrated systems, with connectivity and sensor feedback redefining value capture in premium tiers.
- Handheld Instruments:Manual cutting, grasping, and retraction devices fabricated to ISO 13485 tolerances remain the volume foundation, with ergonomic handle designs reducing operator fatigue in extended procedures. Brazilian private clinics prioritize cost-efficient handheld portfolios amid reimbursement compression.
- Powered Instruments:Electric and pneumatic motor systems with torque feedback and irrigation integration command the widest margin pools, with brushless motor technology extending service intervals. EU MDR electrical safety documentation requirements filter out undercapitalized motor system entrants.
- Laser Devices:Erbium and diode platforms enable soft tissue modification with reduced mechanical trauma.
- Digital Imaging Systems:Cone-beam CT and intraoral scanning convergence is expanding fastest, with surgical navigation requiring instrument tracking integration.
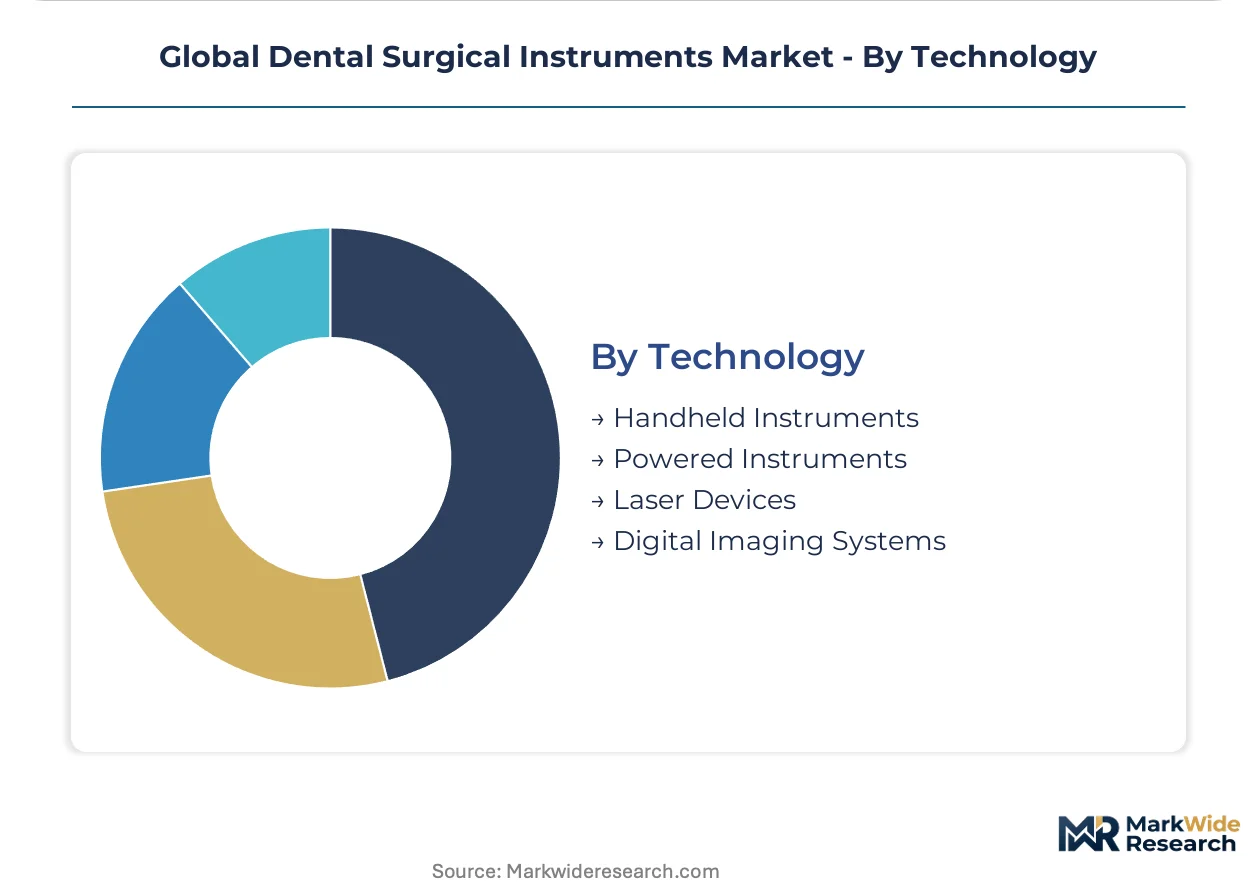
Handheld instruments hold installed capacity. Digital imaging systems are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a substantial trade surplus in precision dental surgical instruments, while the United States and Japan balance significant import flows against specialized export niches. Emerging manufacturing clusters in India and Brazil are reshaping regional supply patterns for standard instrument categories.
United States
Outpatient implant procedure volumes at ambulatory surgery centers in Texas and Florida are accelerating procurement of powered surgical systems. FDA 510(k) clearance pathways for Class II surgical devices impose multi-year validation timelines that favor established manufacturers with captive regulatory affairs teams. The dental service organization network concentrated in California and the Sun Belt is consolidating vendor relationships around bundled instrument and digital imaging contracts.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia sustain elevated periodontal and implant surgery volumes across private clinic networks. EU MDR technical documentation requirements for Class IIa and IIb instruments filter market access toward manufacturers with ISO 13485 quality management systems and established notified body relationships. The precision engineering cluster around Stuttgart and Tuttlingen anchors global production of titanium alloy surgical handpieces and torque-controlled motor systems.
Japan
METI-backed healthcare infrastructure investments are expanding geriatric implantology access in Tokyo and Osaka metropolitan corridors. PMDA consultation procedures for powered surgical devices align with international harmonization frameworks while preserving distinct documentation requirements. The Chubu region around Nagoya hosts specialized forging capabilities for medical-grade titanium instrument geometries serving domestic and export markets.
Brazil
Private dental clinic expansion in São Paulo and Rio de Janeiro is driving demand for cost-efficient handheld instrument portfolios amid reimbursement compression. ANVISA registration pathways for imported surgical devices create working capital intensity that disadvantages distributors without established local technical representation. Southeastern state manufacturing zones are developing domestic stainless steel instrument fabrication to substitute select import categories.
India
Corporate dental chain growth in Maharashtra and Karnataka is standardizing procurement around sterilization-compatible instrument sets. CDSCO medical device rules for Class B and C surgical instruments are transitioning toward risk-based classification alignment with international norms. The Gujarat industrial corridor is attracting contract manufacturers serving export markets with price-competitive stainless steel forceps and elevator production.
Global Dental Surgical Instruments Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and precision forging. The competitive set concentrates around five to seven full-arch workflow providers with direct sales infrastructure spanning major clinic networks. Three strategic archetypes dominate: diversified dental conglomerates with captive financing arms, precision engineering houses with metallurgical specialization, and regional distributors with localized regulatory navigation capabilities. M&A activity targets digital imaging convergence capabilities, while capacity expansion concentrates in ISO 13485-certified forging and finishing facilities.
Among diversified platform providers, Dentsply Sirona and Straumann Group occupy positions defined by bundled instrument financing and guided surgery workflow integration. KaVo represents the precision-engineering archetype with regional distributor credit programs. These three entities exemplify the competitive tension between full-system integration and specialized component supply across premium and mid-market tiers.
| Leading Market Players |
|---|
| Planmeca Oy |
| KaVo |
| Dentsply Sirona |
| W&H |
| Bien-Air |
| Straumann Group |
| A-dec |
| GerDentUSA |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in precision titanium forging around Stuttgart and Tuttlingen drives supplier pricing power for powered surgical handpieces while forcing mid-tier manufacturers toward stainless steel alternatives or extended payment negotiations with distributors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Price differentiation hinges on ISO 13485 certification grade and after-sales service bundling, with premium tiers commanding substantial markups for torque-feedback motor systems. Pricing pressure stems from medical-grade stainless steel cost volatility compressing margins on standard forceps and elevator lines. Group purchasing organizations exhibit lowest price sensitivity, while independent Brazilian and Indian clinics drive hardest bargain negotiations.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate supplier-financing arrangements for distributor networks serving mid-sized dental practices. Manufacturing concentrates in Germany, Switzerland, and Japan for precision titanium components, while India and China supply volume stainless steel fabrication. Raw material dependencies center on medical-grade 440A and 17-4 PH stainless alloys, Grade 5 titanium billet, and tungsten carbide cutting inserts. Single-source vulnerability in EU-notified body certification capacity creates regulatory chokepoint risk. Distribution runs through authorized dealer networks with regional technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across financing structures and digital workflow maturity creates niche opportunities for specialists targeting mid-market clinics underserved by bundled enterprise contracts.
For Market Incumbents: Insulate margin pools by deepening captive leasing capabilities that reduce customer churn, while accelerating ISO 13485 certification investments to exploit auditor scarcity delaying Asia-Pacific competitor timelines. Laser-based soft tissue systems and robotic-assisted platforms represent substitution threats requiring pre-emptive R&D positioning. For New Entrants and Emerging Players: Mid-market dental clinics in São Paulo and Mexico City lacking access to Straumann or Dentsply Sirona financing represent the most penetrable entry point for cost-efficient handheld instrument portfolios paired with localized distributor credit programs. ANVISA registration navigation capabilities separate viable entrants from capital-trapped aspirants. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among powered instrument manufacturers with service-contract attachment above fifty percent of unit sales. Long-term viability favors targets with established EU MDR technical documentation and PMDA alignment for Japanese market access. Watch cone-beam CT integration velocity as inflection signal for guided surgery instrument kit demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Filters competition toward ISO 13485-certified manufacturers with notified body relationships. |
| Cone-Beam CT Integration Partnership | Positions instrument suppliers within full-arch digital workflow capture at high-volume clinics. |
| Captive Leasing Subsidiary Formation | Reduces upfront barriers for clinic customers while locking in multi-year service revenue. |
| Titanium Forging Capacity Expansion | Secures supply of lightweight implantology instruments amid German capacity constraints. |
| ANVISA Registration Pathway Navigation | Unlocks Brazilian private clinic network expansion before domestic manufacturing substitutes imports. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dental clinic procurement managers, biomedical equipment engineers, GPO contracts administrators, and regional distributor principals. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, PMDA consultation records, and hospital procurement contract disclosures. Bottom-up instrument shipment analysis triangulated against top-down dental service line revenue modeling.
Calibration against historical validation timelines and procedural volume correlations anchored projections across the analysis window. Segmentation dimensions encompassed product type, material grade, technology tier, and end-user channel with regional regulatory cluster overlays. CAGRs derived from installed base replacement cycles and outpatient procedure growth trajectories, with powered system penetration and digital imaging adoption serving as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in stainless steel alloy pricing, reimbursement policy shifts, or EU MDR implementation enforcement would shift the trajectory. Forecasts reflect documented assumptions about procedural volume growth and regulatory harmonization progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Global Hernia Repair Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Equine Surgical Equipment Market
Surgical Instruments
Italy General Surgical Devices Market