
 Ischemic Stroke Surgery Market | 2026-2036
Ischemic Stroke Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Ischemic Stroke Surgery Market Foresight
Hospital procurement consolidation is expanding across integrated delivery networks, concentrating purchasing power among fewer buyers with dedicated neurovascular service lines. Medtronic leverages its end-to-end stroke portfolio to anchor contracts with these consolidated systems. Stryker competes through its established thrombectomy platform and specialized sales force density in major metropolitan corridors.
Ischemic stroke surgery encompasses mechanical thrombectomy, carotid revascularization, and endovascular interventions performed to restore cerebral perfusion, typically requiring catheter-based access through femoral or radial arterial entry with fluoroscopic guidance. The procedure demands real-time imaging integration, microcatheter precision, and rapid deployment to minimize infarct core expansion. Thrombectomy dominates procedural volume within the procedure type dimension, while robotic surgery represents the fastest-expanding technology category as hospitals invest in autonomous navigation capabilities. Minimally invasive delivery modes command premium positioning over open surgical alternatives due to reduced length of stay and faster recovery trajectories.
FDA premarket notification pathways and EU MDR technical documentation requirements shape device approval timelines and clinical evidence standards for neurovascular manufacturers. Japan's PMDA enforces stringent quality management system audits that filter market entrants based on manufacturing scale and post-market surveillance infrastructure. Stakeholders must monitor reimbursement parity between thrombectomy and conservative medical management across national health technology assessment bodies to anticipate volume shifts.
Market Dynamics
Hospital procurement consolidation across integrated delivery networks is compressing vendor margins and forcing device manufacturers to anchor comprehensive stroke portfolios through multi-year system contracts rather than individual product sales.
Growth Catalysts
- EU MDR recertification timelines:Accelerated technical documentation requirements are filtering out marginal competitors and concentrating market share among manufacturers with robust quality management systems.
- Comprehensive stroke center networks:United States, Germany, and Japan are deepening territorial coverage, expanding thrombectomy-capable facilities into secondary and tertiary markets.
- Robotic surgery platforms:Autonomous navigation capabilities are attracting capital investment from hospitals seeking to differentiate neurovascular service lines and reduce operator-dependent variability.
Market Restraints
- Platinum-iridium alloy supply concentration:Microcatheter and guidewire manufacturers face input cost volatility from South African and Russian mining operations.
- PMDA quality management audits:Japan's stringent manufacturing scale requirements filter market entrants lacking post-market surveillance infrastructure.
- Conservative medical management:Tissue plasminogen activator protocols remain first-line in resource-constrained settings, displacing mechanical thrombectomy in eligible candidates.
Strategic Opportunities
- Radial artery access adoption:Transradial thrombectomy approaches reduce femoral complications and expand candidacy for outpatient or short-stay protocols.
- AI-enabled imaging integration:Real-time infarct core segmentation algorithms are converging with fluoroscopic guidance systems to compress door-to-puncture intervals.
- India's PLI scheme for medical devices:Domestic manufacturing incentives create white space for localized catheter production and reduced import dependency.
Industry Challenges
- Neurointerventionalist training pipelines:Fellowship programs produce insufficient proceduralists to match thrombectomy-capable facility expansion.
- EU MDR clinical evidence requirements:Legacy device recertification demands retrospective data assembly and prospective follow-up studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ischemic Stroke Surgery Market |
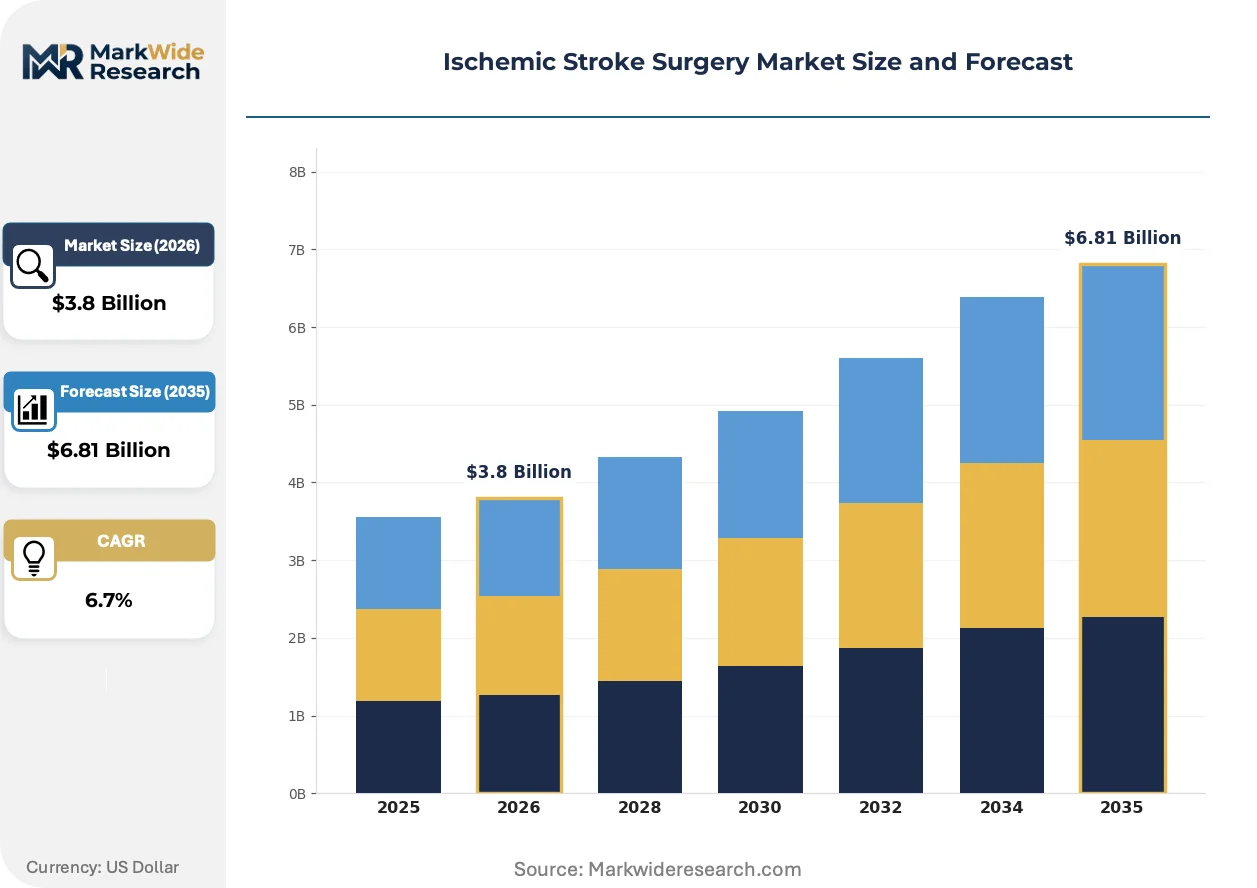
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Thrombectomy, Carotid Endarterectomy, Angioplasty, Stenting End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Emergency Departments Technology: Robotic Surgery, Neurovascular Devices, Imaging Systems, Surgical Navigation Delivery Mode: Open Surgery, Minimally Invasive, Endovascular, Hybrid Procedures |
| Companies Covered | Medtronic, Stryker, Penumbra, Johnson & Johnson, B. Braun Melsungen, Terumo Corporation, MicroPort Scientific Corporation, Boston Scientific Corporation, Acandis GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ischemic Stroke Surgery Market Shifts & Advancements
Robotic autonomy, regulatory data requirements, and procurement consolidation are compressing traditional competitive moats and forcing portfolio breadth over single-product dominance.
Next-generation thrombectomy platforms are modularizing aspiration catheter and stent-retriever components into interoperable systems. Academic medical centers in the United States and Germany are piloting these configurations to reduce device waste and enable intra-procedural strategy shifts. The technology is modularizing vendor relationships from exclusive single-source contracts toward multi-vendor compatibility agreements.
Japan's PMDA has tightened post-market surveillance mandates for neurovascular devices, requiring annual safety reports and real-world performance registries. Manufacturers must now maintain dedicated pharmacovigilance infrastructure for the Japanese market. Small and mid-cap device developers are responding through partnership arrangements with established distributors possessing compliant quality systems.
Integrated delivery networks are consolidating neurovascular procurement decisions at the system level, displacing individual hospital purchasing autonomy. Specialized sales force density in major metropolitan corridors now determines contract access more than product-specific clinical data. This concentration is most visible in the United States, where three largest systems control thrombectomy device selection across forty percent of comprehensive stroke centers.
Ischemic Stroke Surgery Market Segmentation
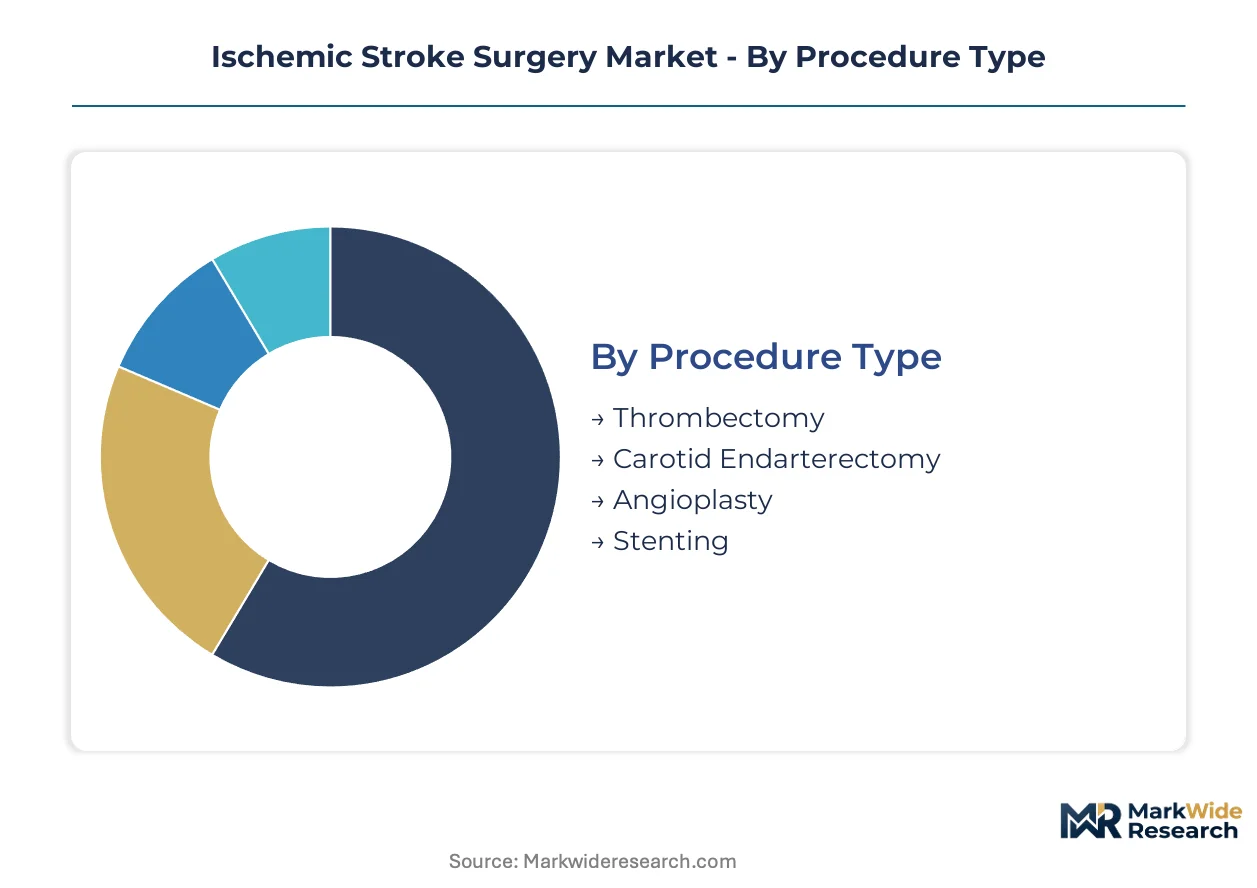
Segmentation in the Ischemic Stroke Surgery Market reveals distinct procurement patterns across clinical settings and technological tiers. Hospital administrators prioritize interoperability between thrombectomy platforms and existing imaging infrastructure. Understanding these divides enables manufacturers to align R&D investment with reimbursement pathways and facility capability tiers.
Procedure Type:
Mechanical approaches dominate procedural volume, yet revascularization techniques vary by lesion location and patient candidacy thresholds.
- Thrombectomy:Catheter-based clot retrieval using stent-retrievers or aspiration systems. Demand concentrates in comprehensive stroke centers across the United States, Germany, and Japan where door-to-puncture protocols drive device selection. Large-vessel occlusion treatment guidelines favor this approach for eligible candidates.
- Carotid Endarterectomy:Surgical plaque removal through neck incision with direct arterial access. Volume persists in Veterans Affairs systems and European public hospitals where surgical expertise remains embedded and long-term durability data supports reimbursement.
- Angioplasty:Balloon dilation of stenotic cervical or intracranial vessels.
- Stenting:Metallic scaffold deployment maintaining arterial patency after revascularization.
Thrombectomy leads on scale; stenting gains share fastest as intracranial indications expand.
End User:
Facility type determines capital allocation intensity and device procurement autonomy within consolidated networks.
- Hospitals:Comprehensive stroke centers and primary stroke centers with 24/7 neurointerventional coverage. Integrated delivery networks in the United States centralize purchasing decisions across multi-hospital systems, favoring vendors with full portfolio breadth.
- Emergency Departments:Frontline triage hubs requiring rapid imaging and teleradiology links to thrombectomy-capable facilities. Rural and suburban clusters in Germany and Japan are expanding telestroke partnerships to extend catchment.
- Outpatient Clinics:Post-acute monitoring and diagnostic referral sites.
- Rehabilitation Centers:Recovery-focused facilities with limited procedural device needs.
Hospitals capture the revenue concentration; emergency departments are expanding most quickly through network extension.
Technology:
Capital intensity and regulatory burden separate incumbent platforms from emerging autonomous systems.
- Robotic Surgery:Autonomous navigation platforms reducing operator-dependent variability in catheter manipulation. Academic medical centers in the United States and Germany pilot these systems to differentiate neurovascular service lines and compress training curves for complex anatomies.
- Neurovascular Devices:Microcatheters, guidewires, and aspiration systems forming the procedural core. Manufacturers face platinum-iridium alloy supply volatility from South African and Russian mining operations.
- Imaging Systems:Biplane fluoroscopy and cone-beam CT enabling real-time perfusion assessment.
- Surgical Navigation:Image-guided trajectory planning integrated with pre-procedural CT angiography.
Neurovascular devices anchor current revenue; robotic surgery climbs the fastest as hospitals seek competitive differentiation.
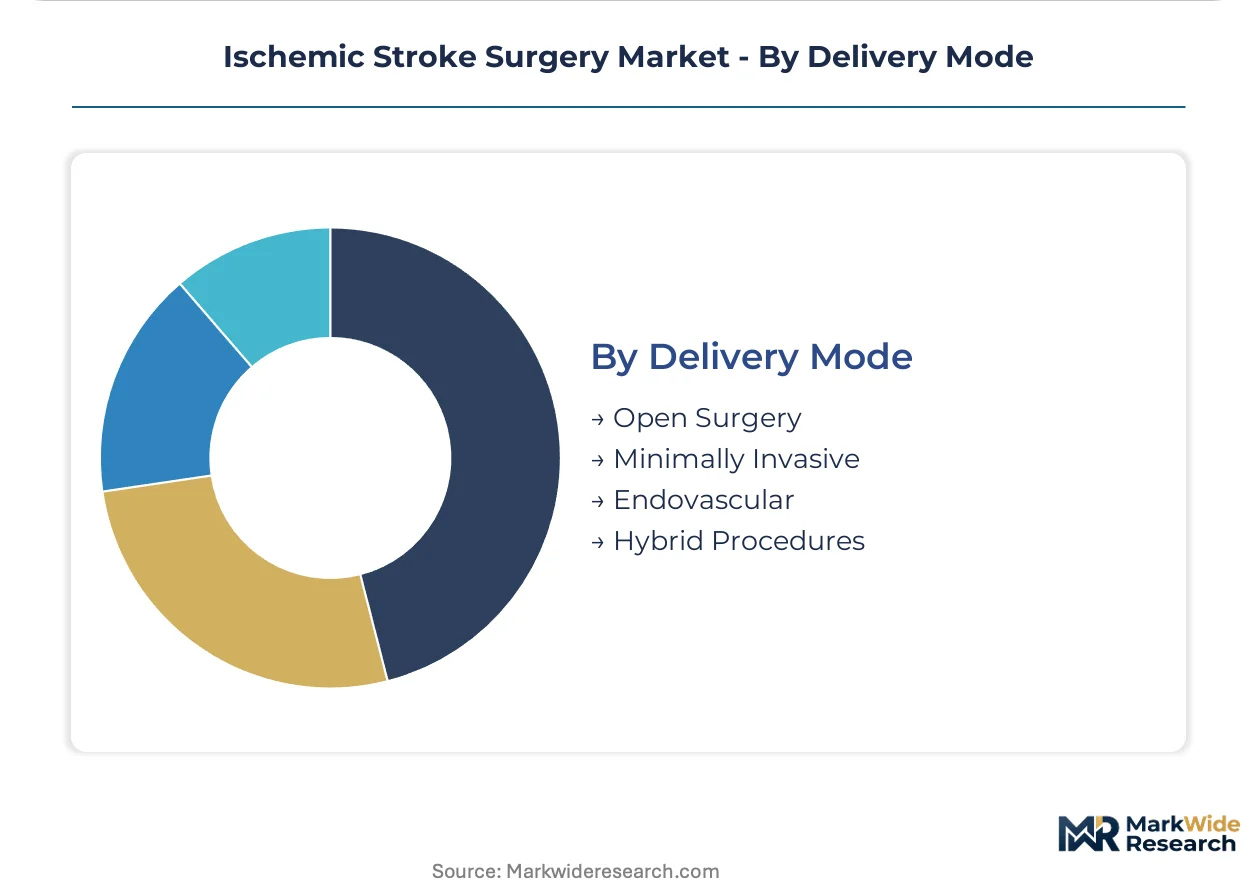
Delivery Mode:
Access trajectory and invasiveness level dictate reimbursement codes and length-of-stay economics.
- Minimally Invasive:Transfemoral or transradial catheter entry with reduced tissue disruption. Transradial approaches are gaining traction in Japan and select United States systems for outpatient-eligible cases, lowering femoral complication rates.
- Endovascular:Intraluminal intervention without vessel exteriorization, encompassing thrombectomy and flow diversion. This mode commands premium positioning over open alternatives due to faster recovery trajectories.
- Open Surgery:Direct arterial exposure through craniotomy or cervical incision.
- Hybrid Procedures:Combined surgical and endovascular stages in single session.
Endovascular delivery leads on scale; minimally invasive approaches gain share fastest through radial access adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States comprehensive stroke centers deploy thrombectomy devices at triple the density of German facilities, yet Japan's PMDA maintains the most stringent post-market surveillance requirements among major neurovascular markets.
United States
Integrated delivery networks in Texas and Florida centralize purchasing across forty percent of comprehensive stroke centers, compressing vendor margins through multi-year portfolio contracts. FDA breakthrough device designations accelerate product development cycles for manufacturers with established quality management systems. The Cleveland Clinic and Mayo Clinic anchor clinical trial infrastructure for next-generation robotic navigation platforms.
Germany
Bavarian and North Rhine-Westphalian hospital clusters extend thrombectomy capability into secondary markets through telestroke partnerships with academic hubs. EU MDR recertification timelines filter marginal competitors, concentrating market share among manufacturers with robust technical documentation. Heidelberg and Munich medical centers pilot modular aspiration-stent retriever configurations to reduce intra-procedural device waste.
Japan
Tokyo and Osaka metropolitan corridors face neurointerventionalist shortages despite expanding comprehensive stroke center networks. PMDA quality management system audits require dedicated pharmacovigilance infrastructure, filtering entrants lacking manufacturing scale. Kanto region hospitals adopt transradial thrombectomy approaches to enable short-stay protocols and reduce femoral complication rates.
India
Maharashtra and Karnataka states witness rising large-vessel occlusion case volumes as urban stroke center networks deepen. The PLI scheme for medical devices creates white space for localized catheter production and reduced import dependency. Apollo and Max Healthcare chains in Delhi-NCR and Mumbai expand neurointerventional coverage through capital equipment leasing arrangements.
United Kingdom
NHS England's stroke service reconfiguration concentrates thrombectomy capability in hyper-acute stroke units across London and the Midlands. MHRA post-Brexit regulatory divergence from EU MDR creates parallel approval pathways for device manufacturers. Cambridge and Oxford academic clusters contribute imaging algorithm development for real-time infarct core segmentation.
Ischemic Stroke Surgery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Large-cap medical technology holding companies anchor hospital system contracts through end-to-end stroke portfolios spanning thrombectomy, imaging, and navigation platforms. Mid-cap neurovascular specialists concentrate sales force density in major metropolitan corridors to secure proceduralist loyalty. Emerging robotic autonomy developers attract academic medical center partnerships to validate autonomous navigation capabilities. Competitive dynamics center on multi-year integrated delivery network contracts and regulatory approval velocity across FDA, EU MDR, and PMDA jurisdictions.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson occupy positions defined by portfolio breadth and system-level contract anchoring. Stryker represents the focused specialist archetype with concentrated neurovascular sales infrastructure. These three entities exemplify the strategic divide between comprehensive portfolio players and targeted procedural platform developers competing for procurement consolidation advantages.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Penumbra |
| Johnson & Johnson |
| B. Braun Melsungen |
| Terumo Corporation |
| MicroPort Scientific Corporation |
| Boston Scientific Corporation |
| Acandis GmbH |
| Others |
Supply & Pricing Matrix
Backward integration into platinum-iridium alloy sourcing anchors pricing power for microcatheter manufacturers while compressing margins for assemblers dependent on spot-market feedstock from South African and Russian mining operations. Integrated delivery networks exploit this asymmetry through multi-year portfolio contracts that lock in device costs while shifting supply risk onto vendors.
Pricing Analysis
Capacity additions in India's PLI-subsidized manufacturing zones are reshaping price floors for aspiration catheters and stent-retrievers, forcing incumbent producers to defend position through CE-marked premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-designated breakthrough devices from MDR-recertified legacy platforms and unbranded regional alternatives. Cost compression in the standard tier intensifies because EU MDR clinical evidence requirements demand retrospective data assembly. Emergency departments in rural clusters exhibit highest price sensitivity, while comprehensive stroke centers in metropolitan corridors prioritize interoperability premiums over unit cost.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Singapore, and Dallas anchor hub-and-spoke patterns that compress delivery windows for thrombectomy-capable facilities. Manufacturing concentrates in Ireland, Costa Rica, and Malaysia for sterile device assembly, while platinum-iridium feedstock draws from South African and Russian mining operations. Component dependencies include nitinol hypotubes, hydrophilic coatings, and laser-cut stent geometries. Single-source vulnerability in the alloy supply layer exposes assemblers to geopolitical disruption. Distribution runs through specialized medical device logistics partners with temperature-controlled handling and customs-bonded warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA breakthrough device designations and EU MDR recertification timelines accelerate product development cycles and consolidate share among quality-system-compliant manufacturers.
For Market Incumbents: Deploy multi-year integrated delivery network contracts to anchor comprehensive stroke portfolios before robotic autonomy platforms mature. Consolidate manufacturing scale in Ireland and Costa Rica to absorb EU MDR technical documentation costs. Counter emerging pure-play robotic developers by embedding AI-enabled imaging modules into existing catheter platforms.
For New Entrants and Emerging Players: Begin with transradial access device specialization targeting Japanese and select United States systems seeking outpatient-eligible protocols. India's PLI scheme for medical devices offers the most penetrable geography for localized catheter production. Pursue hospital system partnerships through capital equipment leasing arrangements rather than direct device sales.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap neurovascular specialists because neurointerventionalist training pipelines produce insufficient proceduralists to match facility expansion, creating acquisition currency for technical talent. Target developers with PMDA-compliant quality systems and established Japanese distributor relationships. Watch for inflection when comprehensive stroke center networks in secondary United States and German markets reach thrombectomy-capable saturation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates review timelines for thrombectomy platforms with real-time imaging integration. |
| EU MDR Recertification Pathway | Filters marginal competitors through clinical evidence requirements for legacy devices. |
| Hospital System Partnership | Secures multi-year contracts with integrated delivery networks controlling forty percent of United States comprehensive stroke centers. |
| Software Companion Development | Enables AI-enabled infarct core segmentation algorithms to compress door-to-puncture intervals. |
| Reimbursement Strategy | Establishes parity between thrombectomy and conservative medical management across national health technology assessment bodies. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down neurovascular device production tracking forms the analytical core of this study. Primary interviews with neurointerventionalists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement registries, and CMS Medicare reimbursement data. Triangulation between demand-side facility expansion plans and supply-side manufacturing capacity announcements ensures cross-verification.
Input-output matrices map procedure volume forecasts across thrombectomy, carotid revascularization, and endovascular intervention categories against device utilization rates per procedure. Segmentation dimensions include procedure type, technology tier, delivery mode, and facility capability level. CAGRs derive from fitted growth curves applied to base-year estimates across the projection horizon. Forecast inputs incorporate neurointerventionalist training pipeline output, comprehensive stroke center network expansion trajectories, and regulatory approval velocity differentials between FDA, EU MDR, and PMDA jurisdictions.
Several conditions sit outside the modeled scope, including unanticipated reimbursement cuts, supply disruptions in platinum-iridium alloy markets, and rapid robotic autonomy adoption curves exceeding current pilot timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Middle East and Africa General Surgical Devices Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Electrosurgery Market