
 Disposable Spinal Instruments Market | 2026-2036
Disposable Spinal Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Spinal Instruments Market Analysis
Aftermarket sterilization and reprocessing revenue is reconfiguring toward single-use origination as OEMs capture margin pools previously held by third-party reprocessors. ECA Medical anchors its position through vertically integrated polymer molding capabilities in California. Xenco Medical differentiates via glass-reinforced polymer engineering that eliminates metal-on-metal wear debris. Intelligent Implant Systems competes through bundled disposable instrument-and-implant systems that reduce OR setup complexity.
Disposable spinal instruments are single-patient-use surgical tools manufactured from medical-grade polymers, glass-fiber composites, or bioabsorbable materials, designed to perform retraction, access creation, fixation delivery, or tissue manipulation during spine procedures without postoperative reprocessing. These devices incorporate torque-limiting features, radiolucent properties, and anatomically pre-contoured geometries to match specific spinal levels and surgical approaches. Retractors and access systems dominate current revenue as hospitals convert from metal table-mounted frames to lightweight polymer alternatives that reduce setup time and eliminate sterilization queue bottlenecks. Disc replacement applications represent the fastest-expanding segment as motion-preserving procedures gain preference over fusion in cervical cases, driving demand for precision-milled disposable trials and insertion instruments. The distribution channel structure concentrates margin capture with direct sales forces serving integrated delivery networks, while medical distributors retain importance in mid-tier surgical centers lacking capital equipment procurement committees.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence thresholds for polymer-based spinal instruments. ISO 13485 quality management systems and ASTM F2077 testing standards govern material biocompatibility and mechanical performance validation across manufacturing sites. Stakeholders must monitor evolving CMS reimbursement codes for outpatient spine procedures and hospital-acquired infection penalty frameworks, as these payment mechanisms determine whether disposable instrument premiums receive cost pass-through approval or face utilization review scrutiny.
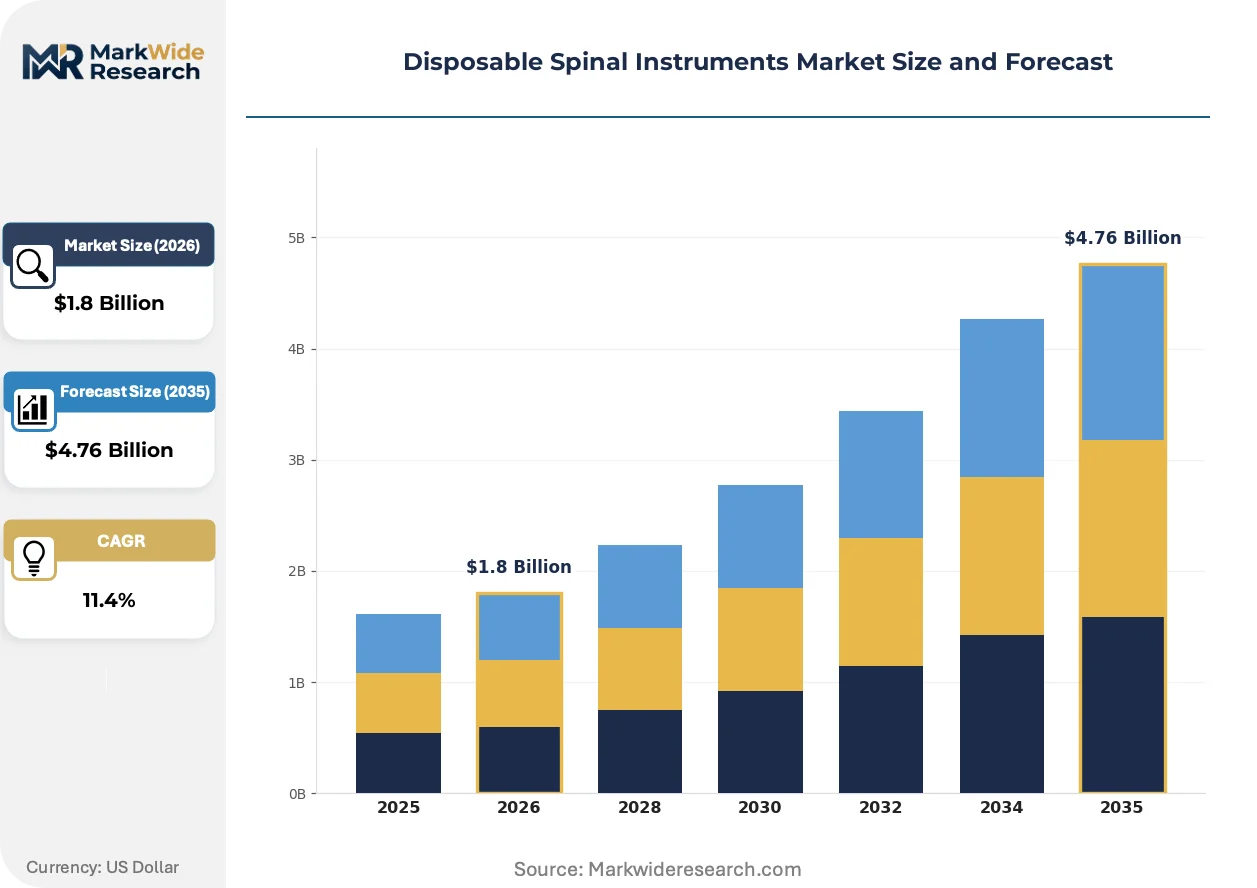
Market Dynamics
Hospital infection control budgets and ambulatory surgical center expansion are compressing instrument reprocessing infrastructure, redirecting capital toward single-use polymer platforms that eliminate sterilization queue bottlenecks and cross-contamination liability.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined pathways for polymer-based spinal instruments reduce time-to-market for manufacturers with established biocompatibility data, expanding product pipelines.
- Ambulatory surgical center volume surge:Outpatient spine procedures in United States facilities lacking on-site sterilization departments drive kit-based disposable adoption.
- EU MDR traceability mandates:Device serialization requirements increase compliance costs for reusable metal instruments, tilting procurement toward single-use alternatives with embedded lot tracking.
Market Restraints
- Medical-grade polymer supply concentration:PEEK and glass-reinforced resin production clusters in Germany and Japan create input vulnerability for North American manufacturers.
- Reimbursement compression:CMS outpatient procedure codes impose utilization review on instrument premiums, limiting cost pass-through in Medicare-dependent hospitals.
- Mechanical performance ceiling:Torque-limiting polymer constructs fail to match stainless steel fatigue resistance in multi-level thoracic fixation, restricting application scope.
Strategic Opportunities
- Japan's aging spine surgery population:Cervical disc replacement volume expansion creates demand for precision-milled disposable trials in a market with stringent reprocessing regulations.
- Bundled instrument-implant systems:OR setup complexity reduction through pre-configured kits opens margin capture in integrated delivery networks consolidating vendor relationships.
- Glass-reinforced composite convergence:Radiolucent mechanical properties combined with metal-equivalent strength enable intraoperative imaging clarity without instrument removal.
Industry Challenges
- Polymer molding talent scarcity:Medical device-grade injection molding expertise concentrates in Southern California and Bavaria, constraining geographic manufacturing diversification.
- ISO 13485 certification timeline:Quality management system audits for multi-site polymer production extend product launch schedules by 8-14 months.
- Legacy sterilization department integration:Hospital capital equipment committees resist write-downs of existing autoclave infrastructure, slowing disposable conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Spinal Instruments Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractors, Trocar, Cannula, Staplers Application: Spinal Fusion, Disc Replacement, Decompression, Trauma Surgery End User: Hospitals, Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Distribution Channel: Direct Sales, Online Channels, Medical Distributors, Wholesalers |
| Companies Covered | ECA Medical, Xenco Medical, Intelligent Implant Systems, TeDan Surgical Innovations, Providence Medical Technology, Paradigm Spine, Safe Orthopaedics, Joimax GmbH, AxioMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Spinal Instruments Market Emerging Trajectories
Material science advances and regulatory traceability requirements are reconfiguring instrument design priorities, shifting competitive advantage from metallurgical expertise to polymer engineering and supply chain transparency.
Glass-reinforced polymer composites are virtualizing traditional stainless steel retractor sets. Ambulatory surgical centers in Texas and Florida adopt these platforms within 18-month procurement cycles. The technology is virtualizing metal-on-metal wear debris concerns while compressing OR setup time from 45 minutes to 12 minutes.
EU MDR technical documentation requirements now mandate clinical performance data for all Class IIa spinal instruments. Manufacturers face 40% expansion in regulatory affairs staffing to manage notified body interactions. German and Swiss OEMs respond by consolidating product families to reduce documentation burden per SKU.
Direct-to-facility consignment models displace distributor-held inventory in United States integrated delivery networks. Hospital materials management departments negotiate vendor-managed stock agreements that transfer carrying cost to manufacturers. This pattern concentrates in California and Illinois health systems with centralized procurement committees.
Disposable Spinal Instruments Market Segmentation
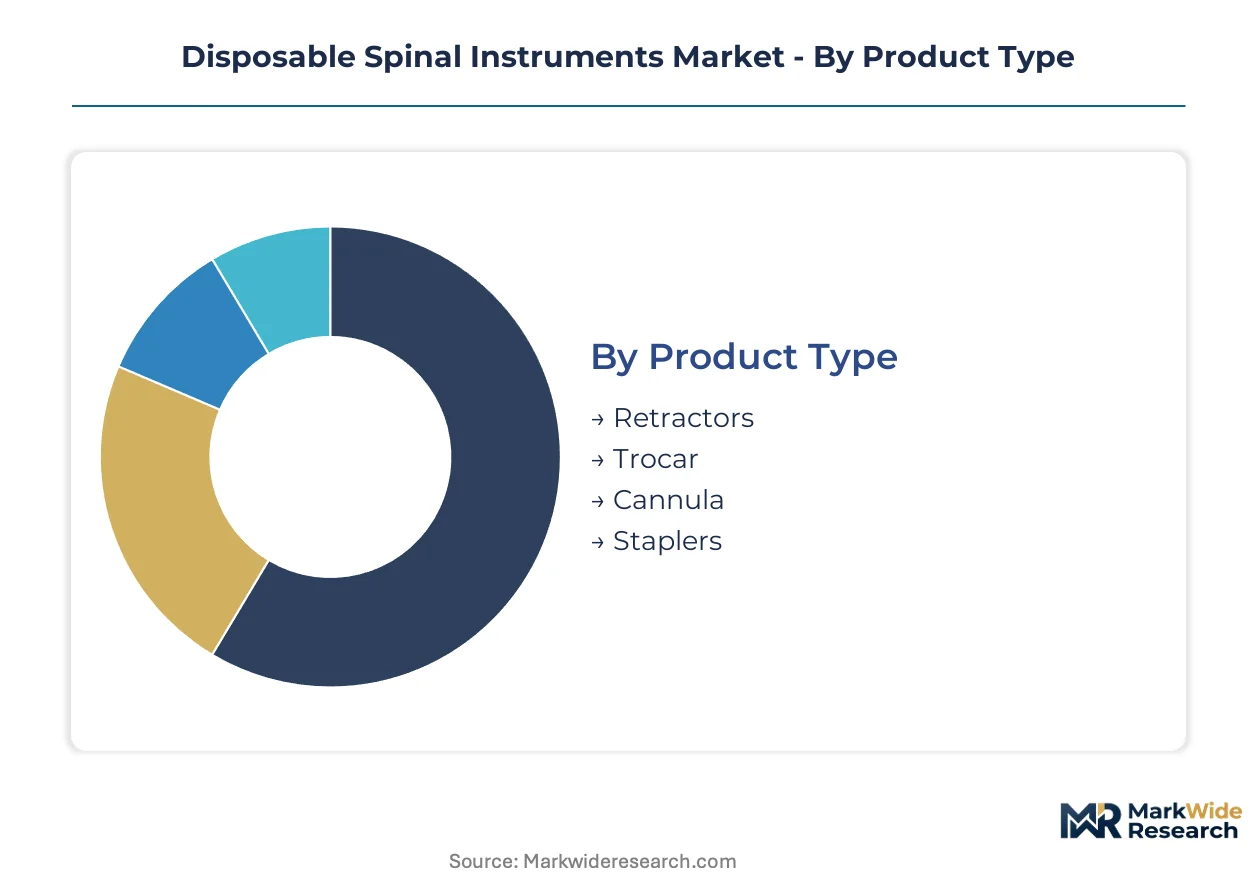
Segmentation in the disposable spinal instruments market reveals distinct procurement velocities across product categories. Cycle times vary dramatically from high-turnover retractor kits to slower-moving specialized fixation systems. Understanding these turnover patterns enables manufacturers to align inventory positioning with facility sterilization constraints and surgical volume profiles.
Product Type:
Retractors turn over fastest in ambulatory settings where polymer-based access systems replace metal frames between cases. Trocar and cannula systems move more slowly due to procedure-specific sizing requirements. Staplers exhibit the longest replacement cycles as their deployment ties to complex multi-level fixation cases.
- Retractors:Polymer table-mounted and handheld retractor systems manufactured from medical-grade PEEK or glass-reinforced composites. Demand concentrates in United States ambulatory surgical centers in Texas and Florida where 12-minute OR setup targets eliminate metal frame sterilization queues.
- Trocar:Percutaneous access devices with blunt-tip or cutting-edge configurations for minimally invasive posterior approaches. Adoption clusters in German spine clinics facing stringent EU MDR traceability mandates that favor single-use serialization over reusable instrument tracking.
- Cannula:Tubular access conduits for endoscopic and microscopic decompression procedures.
- Staplers:Single-use fixation deployment systems for anterior lumbar interbody fusion.
Retractors dominate installed base. Staplers represent where expansion concentrates.
Application:
Cost tiers separate high-complexity fusion procedures from streamlined decompression cases. Disc replacement commands premium pricing due to precision-milled trial instrument requirements. Trauma surgery sits at the economy tier with standardized emergency kits.
- Spinal Fusion:Instrument sets for posterior and interbody fusion incorporating distractors, trials, and insertion tools. United States integrated delivery networks in California and Illinois drive volume through bundled instrument-implant procurement agreements that reduce vendor count.
- Disc Replacement:Motion-preserving cervical and lumbar procedures requiring anatomically pre-contoured trials and specialized insertion instrumentation. Japanese surgical centers generate fastest uptake amid aging demographics and strict reprocessing regulations that disadvantage reusable metal alternatives.
- Decompression:Laminectomy and discectomy instrument kits for nerve root and spinal cord decompression.
- Trauma Surgery:Emergency stabilization systems for fracture reduction and temporary fixation.
Spinal fusion captures the highest procedure volume. Disc replacement is climbing the fastest.
End User:
Customer type determines kit complexity and delivery model. Surgical centers demand streamlined pre-configured sets while hospitals require modular systems across service lines. Orthopedic clinics and rehabilitation centers occupy niche positions with limited sterilization infrastructure.
- Hospitals:Multi-service-line institutions requiring comprehensive instrument platforms across neurosurgery and orthopedic departments. Procurement committees in United States academic medical centers resist autoclave infrastructure write-downs, slowing disposable conversion despite infection control priorities.
- Surgical Centers:Ambulatory facilities lacking on-site sterilization departments drive fastest adoption of complete disposable kits. Texas and Florida ASCs complete procurement cycles within 18 months as outpatient spine volumes surge.
- Orthopedic Clinics:Specialized musculoskeletal practices performing limited-scope spine procedures.
- Rehabilitation Centers:Post-acute facilities with minimal surgical instrumentation requirements.
Hospitals retain the largest installed base. Surgical centers represent the steepest expansion trajectory.
Distribution Channel:
Margin capture shifts toward direct engagement as integrated delivery networks consolidate vendor relationships. Online channels and wholesalers serve price-sensitive mid-tier facilities with limited procurement sophistication.
- Direct Sales:Manufacturer-employed representatives negotiating vendor-managed inventory agreements with United States health systems. California and Illinois IDNs transfer carrying costs to suppliers through consignment models that displace distributor-held stock.
- Medical Distributors:Regional and national intermediaries serving mid-tier surgical centers lacking capital equipment committees. German and Swiss OEMs reduce SKU complexity to manage EU MDR documentation burdens, consolidating distributor relationships.
- Online Channels:E-commerce platforms for standardized consumable replenishment.
- Wholesalers:Bulk procurement intermediaries for price-sensitive institutional buyers.
Direct sales commands margin concentration. Medical distributors retain volume significance in mid-market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. United States buyers absorb premium pricing for infection control benefits, while emerging markets prioritize cost containment over single-use conversion.
United States
Ambulatory surgical centers in Texas and Florida drive fastest kit adoption as outpatient spine volumes surge. FDA 510(k) clearance pathways streamline polymer instrument approvals for manufacturers with established biocompatibility data. Southern California hosts concentrated medical-grade injection molding expertise that supplies domestic OEMs.
Germany
Stringent EU MDR traceability mandates tilt procurement toward single-use alternatives with embedded lot tracking. EMA technical documentation requirements expand regulatory affairs staffing by 40 percent across notified body interactions. Bavaria anchors glass-reinforced resin production clusters serving North American manufacturers.
Japan
Aging demographics accelerate cervical disc replacement volumes, creating demand for precision-milled disposable trials. PMDA sterilization validation requirements disadvantage reusable metal alternatives in hospital procurement. Tokyo and Osaka surgical centers lead conversion amid strict domestic reprocessing regulations.
Switzerland
Swissmedic oversight of Class IIa spinal instruments consolidates product families among domestic OEMs to reduce documentation burden per SKU. Precision polymer engineering capabilities concentrate in Basel and Zurich industrial corridors. Bundled instrument-implant systems gain traction in adjacent EU markets through Swiss distribution networks.
United Kingdom
NHS infection control budgets face utilization review pressure on instrument premiums, slowing disposable conversion despite clinical preference. MHRA post-Brexit regulatory alignment with EU MDR maintains documentation complexity for market entry. London and Southeast England academic medical centers resist autoclave infrastructure write-downs.
Disposable Spinal Instruments Market Vendor Landscape
Capability concentration sits with polymer engineering specialists; scale advantage sits with diversified orthopedic platforms. The market structure tiers between vertically integrated molders and instrument-implant bundlers. Three archetypes dominate: California-based polymer compounders, glass-reinforced composite engineers, and European notified-body navigators. Competitive moves center on backward integration into resin supply and vendor-managed inventory agreements with integrated delivery networks.
Within the polymer engineering tier, ECA Medical exemplifies vertically integrated molding capabilities through its California operations. Xenco Medical occupies a position as a glass-reinforced polymer specialist. Intelligent Implant Systems represents the bundled system approach, reducing OR setup complexity through pre-configured disposable kits.
| Leading Market Players |
|---|
| ECA Medical |
| Xenco Medical |
| Intelligent Implant Systems |
| TeDan Surgical Innovations |
| Providence Medical Technology |
| Paradigm Spine |
| Safe Orthopaedics |
| Joimax GmbH |
| AxioMed |
| Others |
Supply Flow & Price Mechanics
Undercapacity in medical-grade polymer injection molding across Southern California and Bavaria is compressing supplier availability and hardening pricing posture for disposable spinal instrument OEMs. This utilization squeeze transfers negotiating leverage toward compounders with captive resin supply, while buyers face extended lead times for precision-molded retractor and access system components.
Pricing Analysis
Long-term offtake agreements dominate procurement between tier-one OEMs and German PEEK resin suppliers, insulating volume buyers from spot-market volatility in glass-reinforced composites. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared instrument systems from CE-marked alternatives and unvalidated economy imports. Cost compression in the standard tier is intensifying because mid-tier surgical centers demand kit-based solutions without brand premiums. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity, while Japanese academic medical centers absorb premium positioning for PMDA-validated systems.
Supply Chain Analysis
Medical-grade PEEK and glass-reinforced resin feedstock production clusters in Germany, Japan, and the United States, creating geographic concentration for polymer spinal instrument manufacturing. North American OEMs draw from Bavarian resin suppliers and Southern California compounding facilities, with secondary sourcing from Japanese engineering polymer producers. Single-source vulnerability runs through German notified-body-certified resin grades required for EU MDR compliance. Distribution runs through direct sales forces serving integrated delivery networks in California and Illinois, with medical distributors retaining mid-tier surgical center access in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable spinal instruments market is entering cyclical recovery as ambulatory surgical center construction absorbs sterilization infrastructure write-downs and drives kit-based procurement. This capital expenditure cycle favors polymer-platform OEMs with vendor-managed inventory capabilities.
For Market Incumbents: Build regulatory moat through accelerated FDA 510(k) pathway utilization and EU MDR technical documentation consolidation. Incumbents should secure backward integration into medical-grade polymer compounding to defend margin position against resin price volatility, while expanding consignment inventory agreements with California and Illinois integrated delivery networks to lock out distributor-based competitors. For New Entrants and Emerging Players: Pursue white-space capture in cervical disc replacement disposable trials for Japanese surgical centers, where PMDA sterilization validation requirements disadvantage reusable metal incumbents. New entrants should target Texas and Florida ambulatory surgical centers with pre-configured retractor kits that compress OR setup time, leveraging direct-to-facility sales models that bypass established distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across glass-reinforced composite manufacturing as cleanroom molding capacity tightens in Southern California. Long-term viability over the next decade rests on acquiring vertically integrated polymer compounders with ISO 13485 certification and existing FDA master files. The signal to monitor is CMS outpatient procedure code expansion for spine surgeries, which would validate disposable instrument premium pass-through.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Consolidation | Reduces notified body audit burden per SKU for German and Swiss OEMs. |
| Vendor-Managed Inventory Agreements | Transfers carrying cost to manufacturers while securing California IDN shelf position. |
| Glass-Reinforced Composite Platform Expansion | Enables radiolucent mechanical performance matching stainless steel fatigue resistance. |
| FDA 510(k) Clearance Acceleration | Streamlines market entry for polymer instruments with established biocompatibility data. |
| Backward Integration into PEEK Compounding | Captures resin margin pool and insulates against German supply concentration risk. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, EU MDR notified body documentation, CMS outpatient procedure coding, and hospital procurement database extracts. The analysis combines structured interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with validation across ASTM F2077 testing standards and ISO 13485 quality management system audits. Bottom-up facility-level demand modeling triangulates against top-down OEM revenue segmentation across product type, application, and end-user categories.
Forecast inputs span ambulatory surgical center construction permits, spine surgery volume projections, sterilization department capital expenditure cycles, and regulatory approval timelines for polymer-based platforms. Segmentation dimensions modeled include product type, application, end-user facility type, and distribution channel across the analysis window. CAGRs derive from procedure volume elasticity to outpatient migration, infection control budget allocation patterns, and instrument kit penetration curves by facility sterilization infrastructure status. Specific inputs include EU MDR implementation compliance costs and PMDA sterilization validation requirements.
Sensitivities concentrate around CMS reimbursement code revisions for outpatient spine procedures, medical-grade polymer supply disruptions from German or Japanese production clusters, and hospital capital committee resistance to autoclave infrastructure write-downs. Forecasts reflect documented assumptions regarding ambulatory surgical center expansion velocity and regulatory clearance pathway efficiency. Cross-checking against hospital infection control expenditure surveys and spine surgeon preference studies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Ultrasonic Scalpel Market