
 Global Urethral Dilator Market | 2026-2036
Global Urethral Dilator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urethral Dilator Market Foresight
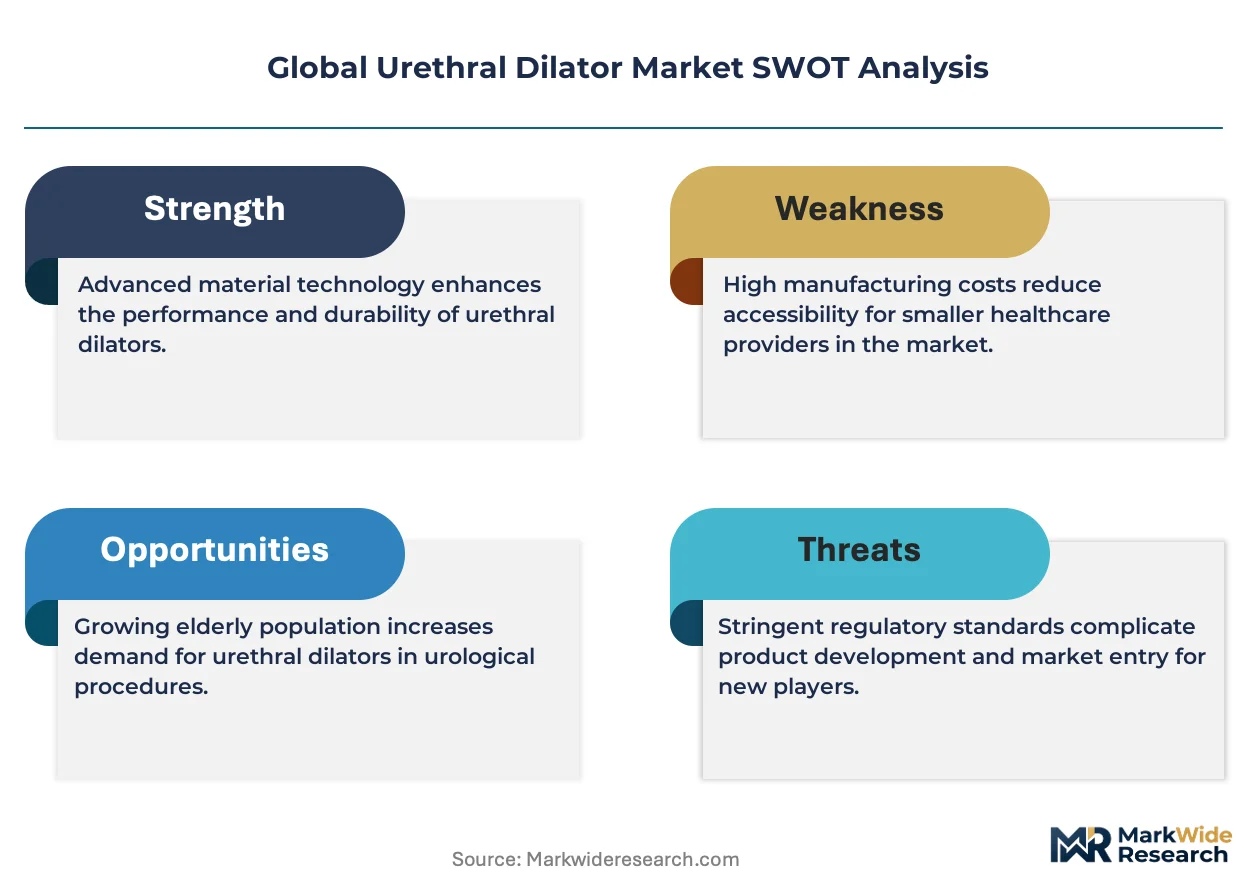
Single-use sterile specification tiers is bifurcating the competitive landscape between premium polymer platforms and conventional reusable metal sets. Boston Scientific Corporation leverages balloon expansion technology across urology clinics worldwide. B. Braun Melsungen AG anchors European procurement networks through its sterilization-ready dilator portfolios. Coloplast differentiates via hydroactive polymer formulations that reduce mucosal trauma during repeated dilation sessions.
A urethral dilator is a graduated medical instrument, typically manufactured from surgical stainless steel, medical-grade polymers, or hydrophilic-coated elastomers, designed to progressively enlarge the urethral lumen in patients with strictures, stenoses, or post-traumatic narrowing. The device functions by mechanical radial force application or balloon-mediated expansion to restore urinary patency without open surgical reconstruction. Balloon dilators command premium positioning due to controlled pressure delivery and reduced perforation risk in delicate stricture segments. Plastic dilators compete on cost efficiency and single-use sterility assurance in high-volume ambulatory settings. Electronic dilators represent an emerging technology segment where powered feedback mechanisms enable real-time resistance monitoring during procedural advancement.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape polymer biocompatibility testing burdens and clinical evidence thresholds for market entry. Japan's PMDA enforces JIS-standard dimensional tolerances that influence Japanese manufacturers' export compatibility. ISO 13485 quality management compliance has become a baseline procurement filter for hospital system tenders across North America and Western Europe. Stakeholders must monitor regulatory divergence between FDA's streamlined predicate-device routes and EMA's intensified post-market surveillance obligations as these frameworks determine speed-to-market and compliance cost structures.
Market Dynamics
Balloon-mediated expansion technology is compressing procedural timeframes and displacing graduated metal dilators in tertiary care settings, while EU MDR biocompatibility mandates are reshaping polymer formulation requirements across manufacturing footprints.
Growth Catalysts
- Ambulatory surgery center expansion:Outpatient urological procedure volumes in Germany and the United States are pulling single-use sterile dilator procurement into high-throughput clinic networks.
- EU MDR Class IIa certification pathways:Intensified post-market surveillance obligations are filtering out marginal suppliers and consolidating procurement around ISO 13485-compliant manufacturers.
- Hydroactive polymer formulations:Mucosal trauma reduction during repeated dilation sessions is expanding addressable patient populations in Japan's aging demographic cohorts.
Market Restraints
- Medical-grade polymer feedstock concentration:Specialty elastomer supply chains cluster among German and Japanese chemical producers, exposing device manufacturers to input cost volatility.
- FDA 510(k) predicate-device dependencies:Streamlined clearance routes require substantial equivalence demonstrations that constrain novel balloon pressure-sensor architectures.
- Reusable metal dilator substitution persistence:Stainless steel instrument sets retain cost advantages in budget-constrained public hospital systems across Southern Europe.
Strategic Opportunities
- Electronic dilator technology convergence:Powered feedback mechanisms integrating real-time resistance monitoring with digital urodynamic systems represent unclaimed premium positioning.
- India's CDSCO regulatory harmonization:Alignment with ISO standards is accelerating import substitution opportunities for domestic polymer device manufacturers.
- Direct-to-ambulatory distribution channels:Bypassing traditional hospital supply chain intermediaries captures margin in United States outpatient surgery networks.
Industry Challenges
- Polymer biocompatibility testing capacity constraints:EU MDR cytotoxicity and sensitization study backlogs are extending certification timelines for new hydrophilic coating formulations.
- Cross-border regulatory divergence management:Simultaneous FDA 510(k) and PMDA JIS-standard compliance requires parallel quality system documentation that strains mid-tier quality assurance functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urethral Dilator Market |
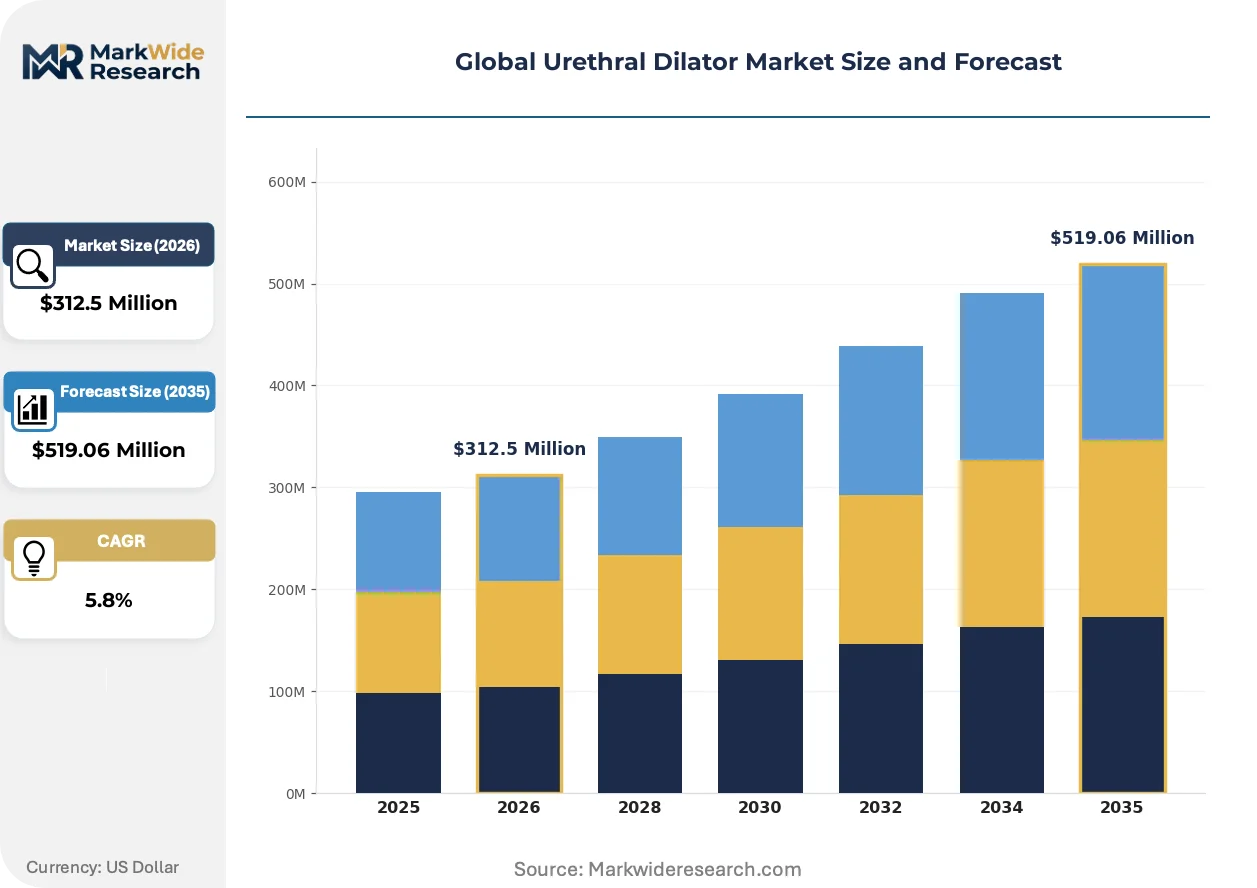
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Dilators, Plastic Dilators, Balloon Dilators, Hydrogel Dilators Application: Urethral Stricture Treatment, Post-Surgical Therapy, Trauma Management, Diagnostic Procedures End User: Urology Clinics, Ambulatory Surgery Centers, Diagnostic Labs, Rehabilitation Centers Technology: Manual Dilators, Balloon Expansion, Electronic Dilators, Hydroactive Dilators |
| Companies Covered | Boston Scientific Corporation, B. Braun Melsungen AG, Teleflex Inc., Cook Medical, BD, Coloplast, MED pro Medical BV, UROMED Kurt Drews KG, Medi Globe Technologies GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urethral Dilator Market Shifts & Advancements
Digital feedback integration and single-use polymer platforms are actively restructuring competitive differentiation, while regulatory frameworks on both sides of the Atlantic are accelerating formulation chemistry investments.
Balloon dilators with integrated pressure transducers are supplanting tactile-dependent metal bougies in delicate bulbar stricture segments. Tertiary urology departments in the United States and Germany are adopting these systems at accelerating pace. The technology is compressing perforation rates and enabling same-day discharge protocols that reshape ambulatory reimbursement structures.
EMA's intensified post-market surveillance obligations under EU MDR are forcing polymer suppliers to maintain batch-level biocompatibility traceability. Manufacturers serving European hospital systems must now document cytotoxicity test results across multi-year retention periods. German and French procurement networks are filtering tenders exclusively toward ISO 13485-certified suppliers with established vigilance reporting infrastructure.
Hospital system buying consortiums in the United States are consolidating dilator procurement around sterilization-ready single-use platforms. Traditional reusable instrument reprocessing contracts are losing share to disposable polymer sets that eliminate central sterilization department burden. This pattern concentrates most visibly in multi-site ambulatory surgery networks across Texas and Florida where throughput metrics dominate vendor selection criteria.
Global Urethral Dilator Market Segmentation
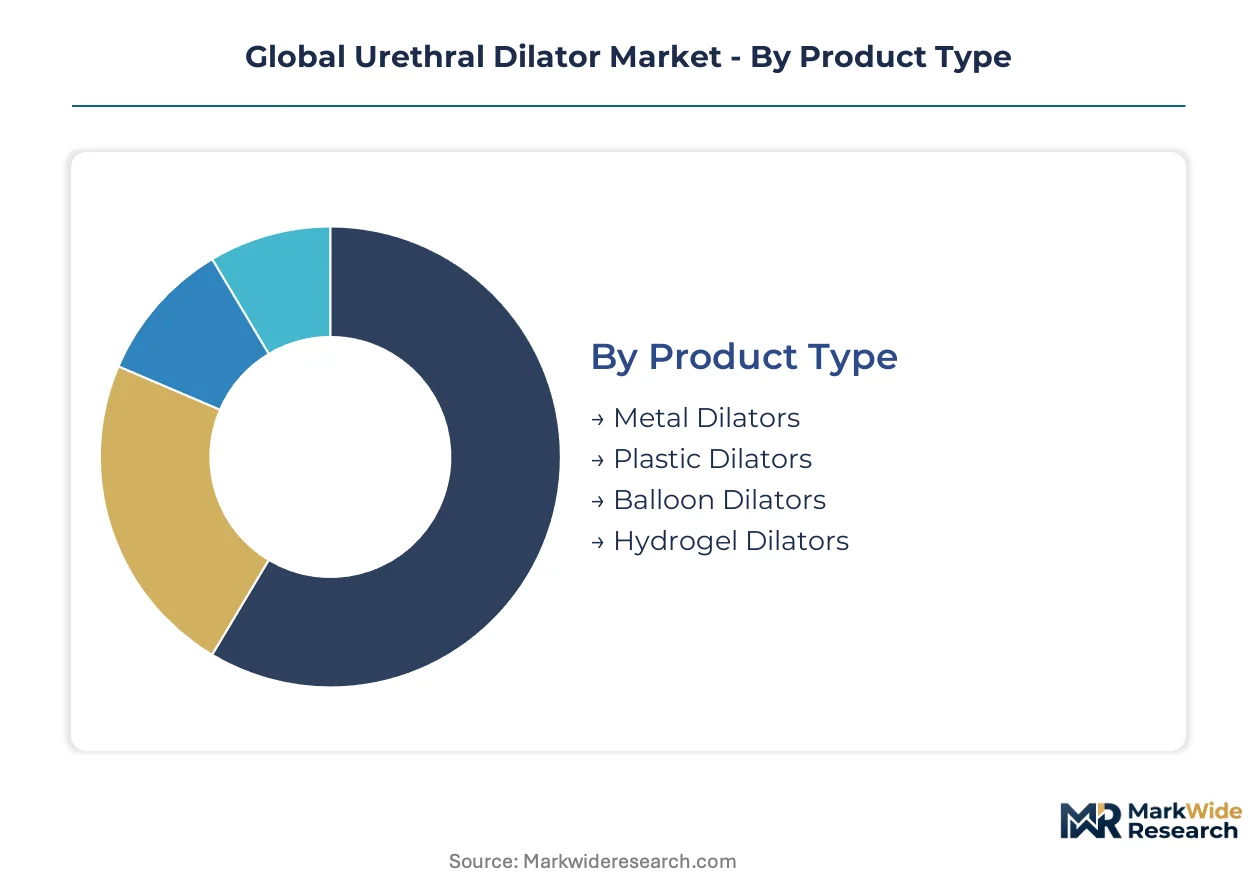
Urethral dilator purchasing decisions split across material durability, procedural setting sterility requirements, and real-time feedback capabilities. Manufacturers must align platform investments with the specific substitution pressures each segment faces from adjacent technologies.
Product Type:
Balloon dilators exert the strongest substitution pressure on conventional metal sets, compressing their addressable volume in tertiary care while plastic variants defend ambulatory cost positions.
- Balloon Dilators:Polymer balloons with integrated pressure transducers deliver controlled radial expansion for delicate bulbar strictures. Demand concentrates in German and United States tertiary urology departments where same-day discharge protocols reduce hospitalization costs.
- Metal Dilators:Surgical stainless steel bougies with graduated diameters persist in budget-constrained procurement networks. Southern European public hospital systems retain these instruments due to multi-decade amortization schedules and central sterilization infrastructure.
- Plastic Dilators:Single-use polymer sets eliminate reprocessing burden in high-throughput clinics.
- Hydrogel Dilators:Hydrophilic-coated elastomers reduce mucosal trauma during repeated sessions.
Metal dilators retain volume leadership; balloon dilators hold the steepest expansion curve.
Application:
Procedure reimbursement tiers stratify demand, with stricture interventions commanding premium device specifications and diagnostic applications prioritizing cost efficiency.
- Urethral Stricture Treatment:Progressive lumen restoration for fibrotic narrowing drives the highest-value device procurement. Japanese aging demographics expand addressable populations for recurrent dilation protocols.
- Post-Surgical Therapy:Scheduled dilation prevents anastomotic contracture following urethroplasty. United States ambulatory surgery networks favor single-use platforms that eliminate central sterilization bottlenecks.
- Trauma Management:Emergency patency restoration requires rapid deployment capability.
- Diagnostic Procedures:Cystoscopy-assisted calibration uses lower-specification instruments.
Stricture treatment commands the dominant revenue share; post-surgical therapy is climbing the fastest.
End User:
Site-of-care migration toward outpatient settings reconfigures procurement authority away from hospital materials management toward clinic-level purchasing.
- Ambulatory Surgery Centers:High-throughput Texas and Florida networks prioritize sterilization-ready single-use sets that maximize room turnover. Throughput metrics dominate vendor selection over per-unit cost minimization.
- Urology Clinics:Office-based dilation services require compact instrument portfolios with minimal reprocessing footprint. German clinic chains consolidate purchasing through regional procurement cooperatives.
- Diagnostic Labs:Cystoscopy suites demand calibration-grade dilators.
- Rehabilitation Centers:Long-term stricture management uses patient-tolerable platforms.
Ambulatory surgery centers capture the fastest volume gains; urology clinics maintain the deepest installed base.
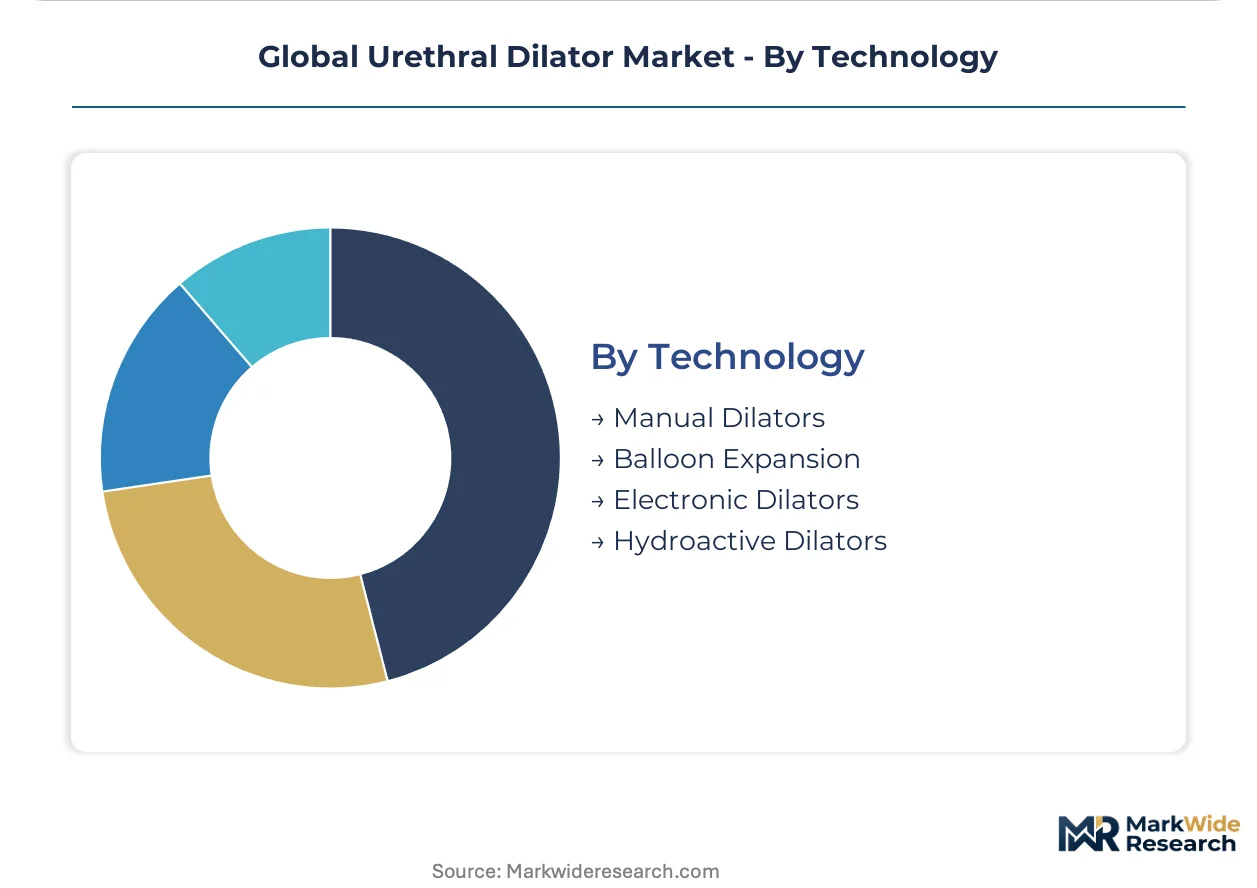
Technology:
Digital feedback integration separates premium positioning from commodity competition, with electronic architectures creating defensible technology moats.
- Electronic Dilators:Powered advancement with real-time resistance monitoring enables precision control in complex strictures. Unclaimed premium positioning exists for platforms integrating with digital urodynamic systems.
- Balloon Expansion:Pressure-mediated dilation supersedes tactile-dependent metal bougies in delicate segments. United States academic medical centers adopt these systems for perforation rate reduction.
- Manual Dilators:Operator-dependent graduated advancement persists in cost-sensitive procurement.
- Hydroactive Dilators:Polymer formulations activate upon fluid contact to reduce insertion trauma.
Balloon expansion retains procedural dominance; electronic dilators represent the steepest technology trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese chemical producers dominate specialty elastomer feedstocks for polymer dilators, while United States ambulatory networks and Japanese aging demographics pull demand toward divergent product specifications.
United States
Texas and Florida ambulatory surgery networks prioritize throughput-optimized single-use sets that eliminate central sterilization bottlenecks. FDA 510(k) clearance pathways constrain novel balloon pressure-sensor architectures through substantial equivalence requirements. Boston Scientific Corporation anchors balloon expansion technology deployment across tertiary urology departments nationwide.
Germany
Regional procurement cooperatives consolidate clinic chain purchasing for sterilization-ready dilator portfolios. EU MDR Class IIa certification mandates filter tenders toward ISO 13485-certified suppliers with established vigilance reporting infrastructure. B. Braun Melsungen AG leverages sterilization-ready dilator portfolios across European hospital networks.
Japan
Aging demographic cohorts expand addressable populations for recurrent dilation protocols requiring mucosal trauma reduction. PMDA enforces JIS-standard dimensional tolerances that influence domestic manufacturers' export compatibility. Tokyo and Osaka medical device clusters specialize in hydrophilic-coated elastomer formulations for stricture intervention.
India
CDSCO regulatory harmonization with ISO standards accelerates import substitution opportunities for domestic polymer device manufacturers. Cost-sensitive public hospital systems retain reusable metal instrument sets due to multi-decade amortization schedules. Mumbai and Bangalore medical device corridors attract contract manufacturing for European and North American brands.
United Kingdom
NHS procurement frameworks favor sterilization-ready single-use platforms that reduce central sterilization department burden. MHRA alignment with EU MDR post-market surveillance obligations maintains biocompatibility testing standards post-Brexit. London and Cambridge medical technology clusters concentrate on digital feedback integration for electronic dilator architectures.
Global Urethral Dilator Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates possessing established regulatory navigation capabilities and hospital system procurement relationships. The competitive structure tiers between premium balloon platforms with integrated pressure monitoring and cost-optimized single-use polymer sets. Strategic archetypes include diversified urology device majors, specialized urological instrument fabricators, and emerging electronic feedback technology developers. Dominant competitive moves encompass geographic expansion through regional procurement cooperative penetration and technology licensing partnerships for pressure-sensor architectures.
Among diversified urology device majors, Boston Scientific Corporation exemplifies balloon expansion technology deployment across global clinic networks. B. Braun Melsungen AG occupies a position within European sterilization-ready dilator supply chains through its Melsungen-based manufacturing footprint. Coloplast represents hydroactive polymer formulation specialization targeting mucosal trauma reduction in repeated dilation protocols.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Teleflex Inc. |
| Cook Medical |
| BD |
| Coloplast |
| MED pro Medical BV |
| UROMED Kurt Drews KG |
| Medi Globe Technologies GmbH |
| Others |
Supply & Pricing Matrix
Balloon-mediated expansion technology displacing graduated metal bougies simultaneously concentrates procurement authority in German and Japanese polymer feedstock corridors while compressing per-procedure reimbursement bands across United States ambulatory networks. This substitution dynamic reshapes supplier pricing power toward elastomer formulation specialists and away from stainless steel instrument fabricators.
Pricing Analysis
FDA 510(k) predicate-device requirements dictate the pricing tier structure across premium balloon platforms, standard single-use polymer sets, and economy reusable metal instruments. Price differentiation rests on ISO 13485 certification grade and sterilization-ready packaging for high-throughput clinic procurement. Pricing pressure stems from EU MDR biocompatibility testing cost absorption squeezing mid-tier manufacturers. Ambulatory surgery centers in Texas and Florida exhibit highest price sensitivity; tertiary urology departments in Germany and the United States demonstrate lowest sensitivity due to outcome-based procurement criteria.
Supply Chain Analysis
Specialty elastomer feedstock concentration in German and Japanese chemical production corridors creates upstream chokepoints for hydrophilic-coated balloon dilator manufacturing. Medical-grade polymer supply draws from BASF and Mitsui Chemicals production footprints, with silicone elastomer and polyurethane resin dependencies amplifying input cost volatility. Single-source vulnerability runs through Japanese JIS-standard dimensional tolerance enforcement affecting export compatibility. Distribution runs through regional procurement cooperatives in Germany and GPO contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital system buying consortium consolidation across United States ambulatory networks and European clinic chains has shifted procurement leverage toward volume-aggregated purchasers and away from fragmented vendor bases.
For Market Incumbents: Shield balloon platform margins through backward integration into polymer formulation capabilities in Germany or Japan to secure feedstock cost stability against specialty elastomer price volatility. Accelerate pressure-sensor architecture R&D to defend premium positioning against emerging electronic dilator entrants targeting digital urodynamic integration. For New Entrants and Emerging Players: CDSCO regulatory harmonization with ISO standards offers the fastest certification fast-track for penetrating India's cost-sensitive public hospital systems with single-use polymer platforms. Target Southern European budget-constrained procurement networks where reusable metal substitution persistence creates white-space for sterilization-ready disposables at 15-20% cost advantage. Pursue direct-to-ambulatory distribution channel partnerships to bypass traditional hospital supply intermediaries and capture margin. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier polymer device manufacturers possessing ISO 13485 infrastructure but lacking balloon pressure-sensor technology portfolios. Five-to-ten year viability hinges on regulatory navigation capabilities rather than manufacturing scale alone. Monitor FDA 510(k) clearance velocity for novel electronic dilator architectures as inflection indicator for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Investment | EMA post-market surveillance obligations filter tenders toward compliant manufacturers with vigilance infrastructure. |
| Balloon Pressure-Sensor R&D Partnership | United States academic medical centers adopt integrated transducer systems for perforation rate reduction. |
| Direct-to-Ambulatory Distribution Buildout | Texas and Florida surgery networks prioritize throughput-optimized single-use sets eliminating sterilization bottlenecks. |
| Hydrophilic Polymer Formulation Licensing | Japanese aging demographics expand addressable populations for mucosal trauma-reducing repeated dilation protocols. |
| CDSCO Regulatory Harmonization Pathway | India's ISO alignment accelerates import substitution opportunities for domestic polymer device manufacturers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures across the analysis window. Interviews with urology department heads, ambulatory surgery center purchasing managers, biomedical engineers, and polymer formulation specialists combined with bottom-up and top-down triangulation validate volume and value estimates.
Segmentation dimensions modeled encompass product type (balloon, metal, plastic, hydrogel), application (stricture treatment, post-surgical therapy, trauma management, diagnostic), end user (ambulatory surgery centers, urology clinics, diagnostic labs), and technology (electronic, balloon expansion, manual, hydroactive) across the projection horizon. CAGRs derive from procedure volume elasticity to aging demographic penetration, regulatory clearance velocity differentials, and substitution rate trajectories between reusable and single-use platforms.
Decision-makers should treat outputs as directional under base assumptions of sustained EU MDR enforcement intensity and United States ambulatory surgery center expansion; material deviation in either regulatory stringency or reimbursement policy would warrant model refresh. Practitioners should keep alternative scenarios live as polymer biocompatibility testing capacity constraints and cross-border regulatory divergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Korea Respiratory Devices Market
Medical Devices
External Defibrillator Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
US C-Arms Market
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Global Nebuliser Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Europe Medical Devices Market
Medical Devices
Global Artificial Organs and Bionics Market