
 Dental Surgical Microscopes Market | 2026-2036
Dental Surgical Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Surgical Microscopes Market Insights
Equipment leasing and pay-per-use financing is reshaping competitive access in the dental surgical microscopes landscape. Carl Zeiss AG leverages its vertically integrated optical manufacturing to sustain premium positioning across university hospitals and private clinics. Leica Microsystems anchors European demand through its specialized fluorescence-filter configurations for endodontic procedures. Zumax Medical Co., Ltd. competes aggressively on modular upgrade paths that reduce total cost of ownership for mid-tier dental practices.
Dental surgical microscopes are precision optical instruments combining apochromatic lens systems with coaxial LED illumination, typically offering magnification ranges from 2.5x to 25x and working distances of 200-400 millimeters for real-time visualization during microsurgical dental procedures. These systems integrate stereoscopic eyepieces with binocular or trinocular heads to enable direct operator viewing while supporting assistant observation or documentation capture. High-definition video integration and digital documentation segments are expanding fastest as malpractice documentation requirements intensify and teledentistry protocols mature. Compact and portable configurations occupy growing share among mobile dental units and field clinic deployments where space constraints dominate purchasing criteria. Optical technology with LED illumination leads installed base volumes, though fiber optic variants retain niche positions in legacy retrofit environments.
FDA 510(k) clearance pathways govern commercial entry in the United States, while CE marking under the EU MDR and ISO 10993 biocompatibility standards shape product development cycles for European-bound manufacturers. Japan's PMDA enforces stringent optical performance verification that extends approval timelines but reinforces quality differentiation for systems serving its aging demographic base. Stakeholders must monitor evolving reimbursement codes for microsurgical dental procedures across national health systems, as coverage expansion or restriction will directly influence upgrade cycles and new equipment placement decisions.
Market Dynamics
Equipment leasing structures and pay-per-use financing are compressing capital barriers for mid-tier dental practices, forcing manufacturers to restructure revenue models around recurring service streams rather than upfront hardware sales.
Growth Catalysts
- MDR compliance mandates:CE marking requirements under the EU Medical Device Regulation are accelerating replacement cycles for legacy systems across German and French dental hospitals.
- Teledentistry documentation protocols:High-definition video integration is becoming standard as malpractice insurers require procedural recording for microsurgical claims defense.
- Aging demographic concentration:Japan's over-65 population is driving demand for precision endodontic procedures that require magnification beyond loupes capability.
Market Restraints
- Apochromatic lens supply concentration:German and Japanese optical glass manufacturers control critical raw material inputs, creating vulnerability to export restriction shocks.
- PMDA optical verification timelines:Japan's pharmaceutical and medical device agency extends approval cycles by 8-14 months compared to FDA 510(k) pathways.
- Loupe substitution in general dentistry:Magnification eyewear at 2.5x-4.5x range satisfies 70% of routine procedures, capping microscope penetration in price-sensitive segments.
Strategic Opportunities
- Mobile dental unit deployment:Compact portable configurations are capturing field clinic demand in rural United States markets where fixed infrastructure is absent.
- Fluorescence-filter convergence:Integration of caries detection fluorescence with surgical visualization is hybridizing diagnostic and operative workflows in specialized endodontic practices.
- IRA equipment depreciation incentives:United States tax code provisions for medical technology investment are improving net present value calculations for private practice upgrades.
Industry Challenges
- Microsurgical technique certification gaps:Dental schools lack standardized curricula for microscope-assisted procedures, constraining operator pool expansion.
- Legacy fiber optic retrofit complexity:Practices with installed halogen systems face incompatible mounting hardware and illumination coupling when upgrading to LED platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Surgical Microscopes Market |
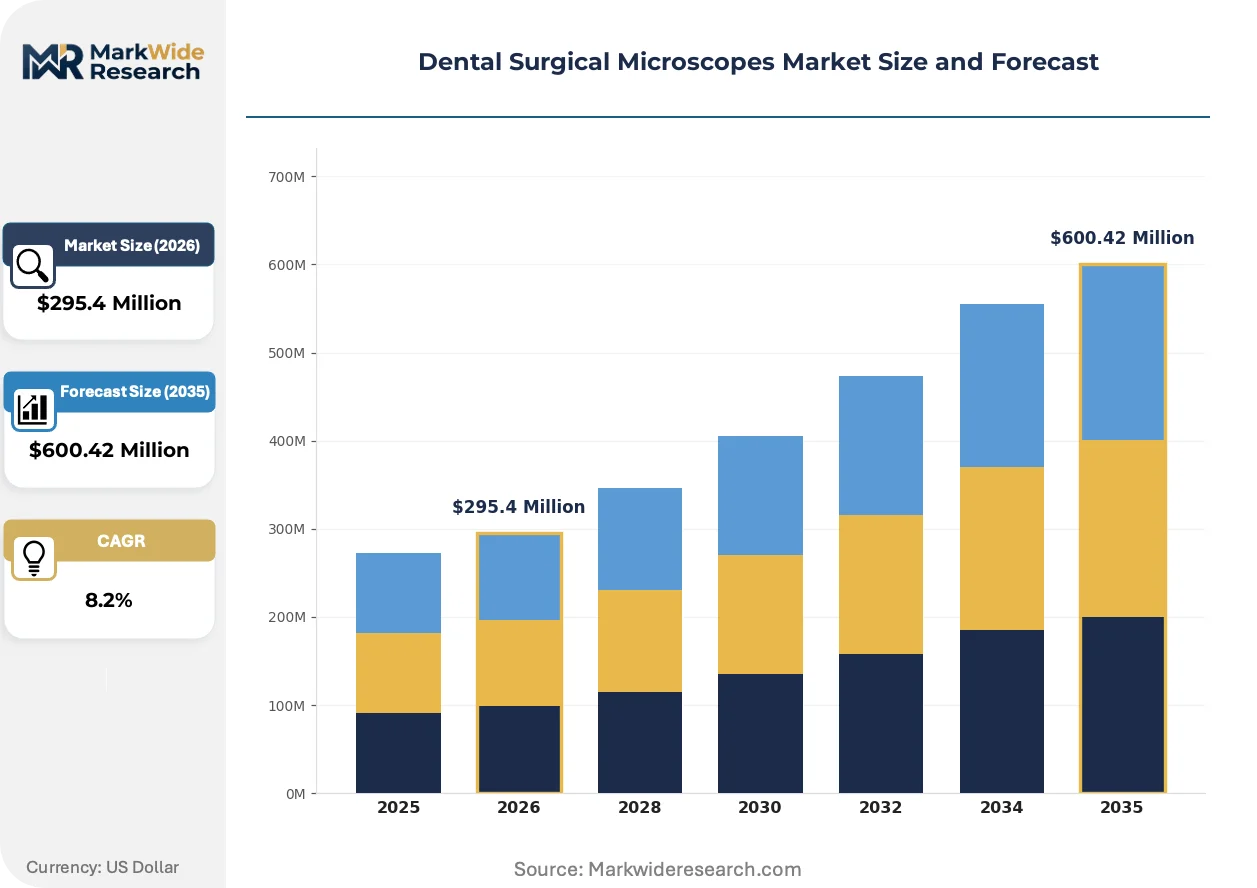
| Market Size in 2026 | $295.4 Million |
| Market Size in 2035 | $600.42 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Definition, Digital, Compact, Portable End User: Dentists, Dental Hospitals, Clinics, Educational Institutions Technology: Optical, LED Illumination, Fiber Optic, Video Integration Application: Endodontics, Periodontics, Oral Surgery, Prosthodontics |
| Companies Covered | Carl Zeiss AG, Leica Microsystems, Zumax Medical Co., Ltd., Global Surgical Corporation, Seiler Instrument, Labo America, Inc., Karl Kaps GmbH & Co. KG, Foshan SOCO Precision Instrument Co., Ltd., Alltion (Wuzhou) Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Surgical Microscopes Market Trends and Innovations
Digital documentation requirements and teledentistry maturation are forcing convergence between surgical visualization and real-time data capture, compressing the boundary between operative equipment and health information infrastructure.
4K and 8K camera sensors integrated directly into trinocular heads are hybridizing surgical microscopes with broadcast-grade documentation systems. University hospitals in Germany and Japan are adopting these configurations for resident training and remote consultation. The technology is compressing aftermarket camera attachment sales while elevating base system price points.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa medical devices. Manufacturers must now maintain vigilance systems tracking device performance across installed bases. European dental hospitals are responding by consolidating procurement around vendors with established quality management systems.
Service contract unbundling is separating hardware warranty from preventive maintenance and software updates. Mid-tier United States dental practices are selecting third-party service providers for optical calibration while retaining manufacturer coverage for electronic components. This fragmentation is most visible in Texas and Florida markets where independent dental service organizations operate dense technician networks.
Dental Surgical Microscopes Market Segmentation
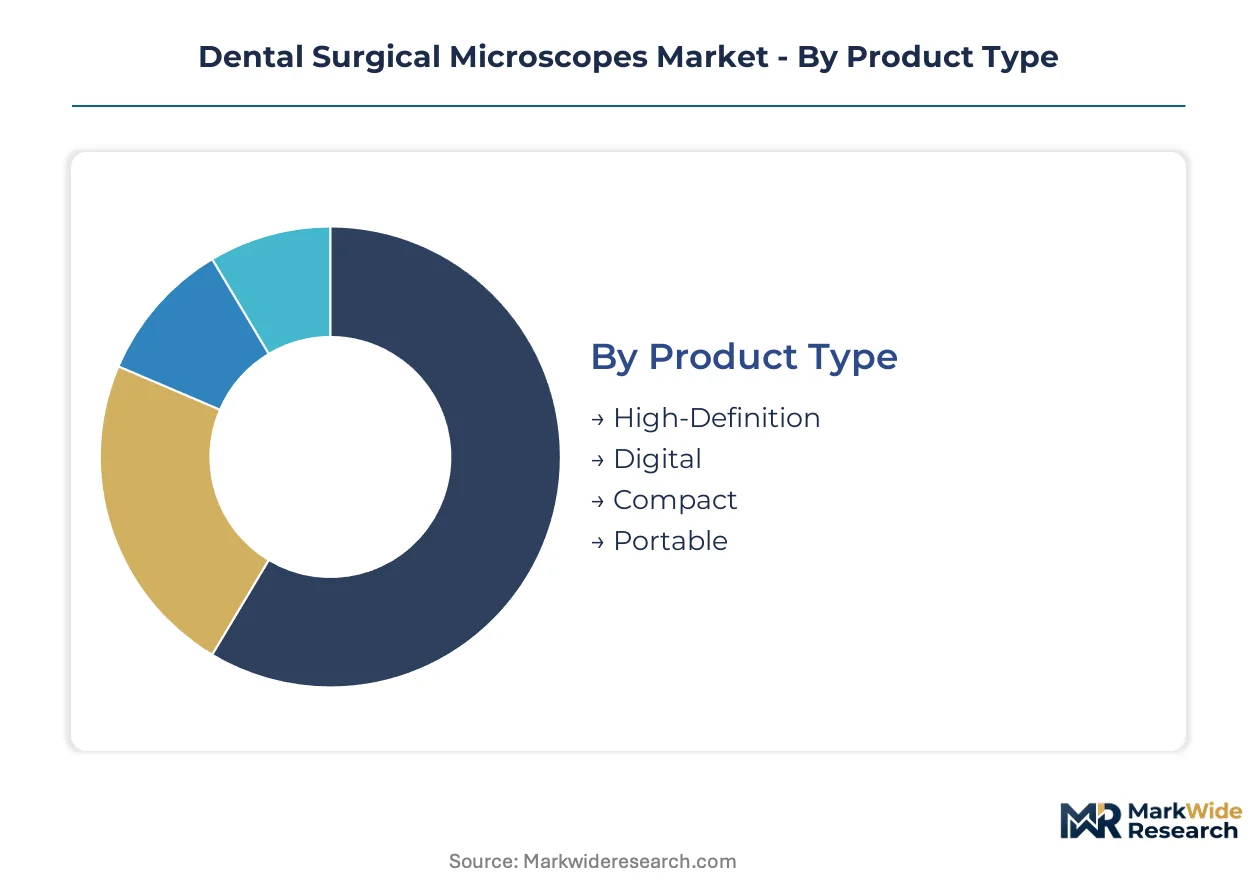
Dental surgical microscope segmentation reveals distinct purchasing patterns across precision requirements and infrastructure constraints. Equipment specifications diverge sharply between university hospital installations and mobile field deployments. Understanding these divides clarifies where manufacturers must differentiate optical performance against portability and cost.
Product Type:
End-use spectrum spans from fixed university installations requiring broadcast-grade documentation to mobile units serving rural populations without permanent dental infrastructure.
- High-Definition:Systems integrate 4K and 8K sensors directly into trinocular heads for real-time procedural recording. German university hospitals and Japanese training centers drive procurement as malpractice documentation requirements intensify and remote consultation protocols mature.
- Digital:Platforms embed computational imaging for measurement calibration and image enhancement during microsurgical procedures. Demand concentrates in United States private practices seeking workflow integration with electronic health records and teledentistry platforms.
- Compact:Reduced footprint configurations serve space-constrained operatories in urban dental clinics where square meter costs limit equipment allocation.
- Portable:Battery-powered units with collapsible stands deploy to rural United States field clinics and mobile dental units serving populations without fixed infrastructure access.
The dominant share belongs to High-Definition systems, while Portable configurations are closing the gap fastest as federally qualified health centers expand mobile service mandates.
End User:
Customer type stratification follows capital availability and procedure complexity, with institutional buyers prioritizing training documentation and private practices emphasizing throughput economics.
- Dental Hospitals:Large-scale procurement by academic medical centers in Germany, Japan, and the United States emphasizes trinocular configurations with integrated video for resident education and multi-disciplinary case review.
- Clinics:Specialized endodontic and periodontic practices represent concentrated demand for fluorescence-filter systems enabling caries detection alongside operative visualization.
- Dentists:Solo and small-group private practices in Texas and Florida markets favor leasing structures and modular upgrade paths to manage capital deployment.
- Educational Institutions:Dental schools in Japan and Germany face curriculum standardization gaps for microscope-assisted techniques, slowing equipment placement despite training mandates.
Dental Hospitals command the largest installed base, though Clinics are expanding procurement most aggressively as specialized procedure reimbursement improves.
Technology:
Illumination and imaging architecture determines optical performance boundaries and regulatory classification pathways across installed base generations.
- Optical:Apochromatic lens systems with stereoscopic eyepieces remain the foundational configuration, with German and Japanese optical glass manufacturers controlling critical raw material supply.
- LED Illumination:Coaxial LED arrays have displaced halogen across new installations, offering color temperature stability and reduced thermal load during extended procedures.
- Fiber Optic:Legacy systems retain niche presence in retrofit environments where mounting hardware incompatibility complicates LED platform upgrades.
- Video Integration:Direct sensor embedding into microscope heads is displacing aftermarket camera attachments while elevating base system price points and regulatory scrutiny under EU MDR post-market surveillance.
LED Illumination leads current installations, yet Video Integration is climbing fastest as documentation requirements harden across malpractice insurance and teledentistry protocols.
Application:
Procedure-specific magnification demands create distinct performance thresholds, with endodontic workflows requiring resolution capabilities beyond general dental microscopy.
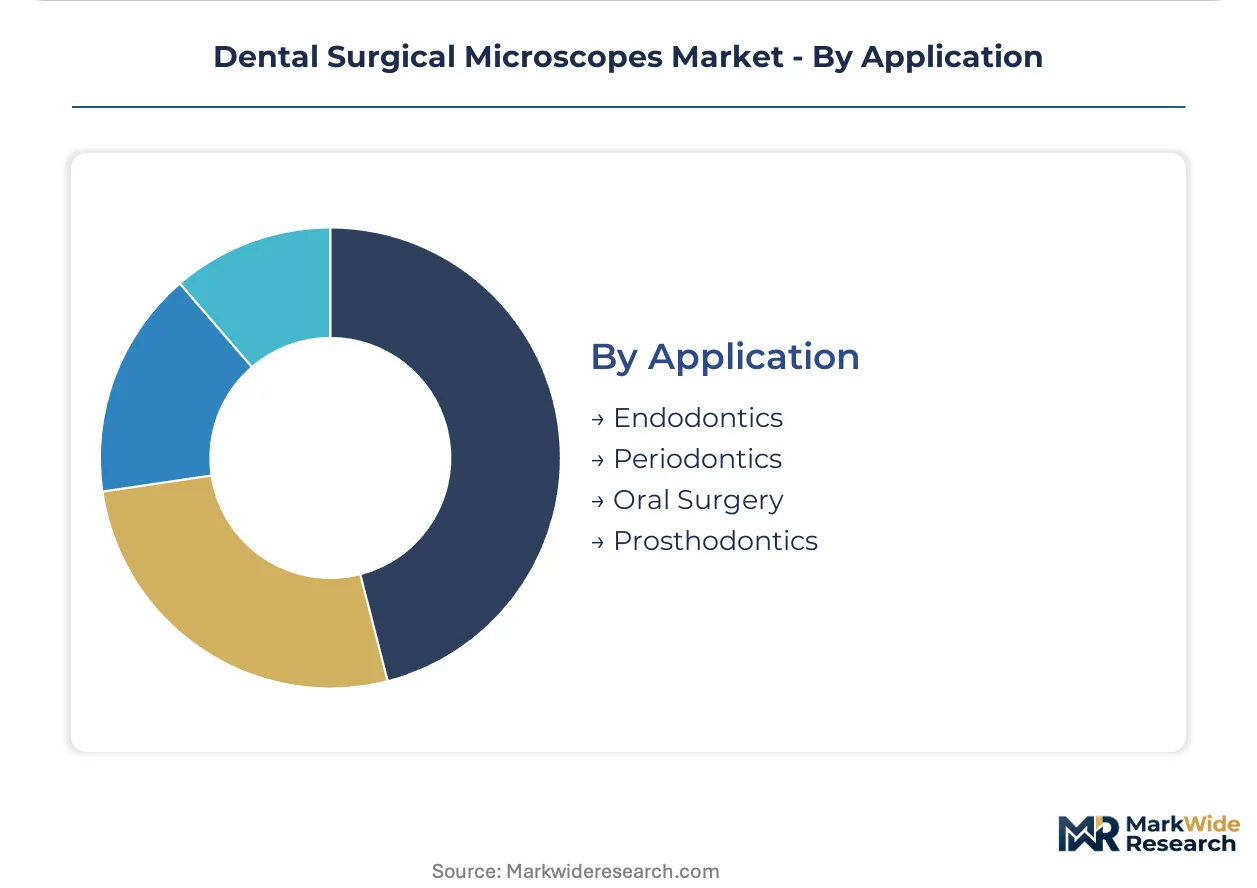
- Endodontics:Canal negotiation and apical surgery demand magnification ranges from 10x to 25x with working distances of 200 millimeters, driving adoption of systems with fine-focus mechanisms and integrated measurement tools.
- Periodontics:Regenerative procedures and microsurgical flap management require fluorescence discrimination for tissue viability assessment, favoring filter-equipped configurations.
- Oral Surgery:Implant placement and bone grafting procedures utilize lower magnification ranges where loupes compete, capping microscope penetration in price-sensitive segments.
- Prosthodontics:Margin evaluation and shade matching impose color fidelity requirements that stress-test apochromatic lens performance across LED color temperature settings.
Endodontics maintains the deepest microscope penetration, while Periodontics is gaining share fastest as regenerative procedure reimbursement expands in United States and German markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA equipment depreciation incentives and MDR compliance mandates are reshaping procurement patterns across dental surgical microscope markets. National health system reimbursement codes and aging demographic concentrations create divergent demand intensities.
United States
Federally qualified health centers are expanding mobile dental unit mandates across rural Texas and Florida markets. FDA 510(k) clearance pathways govern commercial entry while malpractice insurers harden documentation requirements for microsurgical claims defense. Compact portable configurations capture field clinic demand where fixed infrastructure remains absent.
Germany
University hospitals in Bavaria and North Rhine-Westphalia emphasize trinocular configurations with integrated 4K video for resident education. CE marking requirements under EU MDR accelerate replacement cycles for legacy systems across academic medical centers. Stuttgart and Munich clusters concentrate precision optical manufacturing for apochromatic lens supply.
Japan
PMDA optical performance verification extends approval timelines by 8-14 months compared to FDA pathways. Tokyo and Osaka dental hospitals drive demand for precision endodontic procedures serving the over-65 demographic. Kanto and Kansai regions anchor specialized training center procurement for microscope-assisted technique certification.
China
Domestic manufacturers in Guangdong and Jiangsu provinces compete on modular upgrade paths for mid-tier dental practices. NMPA regulatory pathways shape product development cycles for surgical visualization systems. Yangtze River Delta clusters concentrate assembly capacity for LED illumination components.
Dental Surgical Microscopes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base stratifies between vertically integrated optical manufacturers and modular system assemblers. Three archetypes dominate: premium-tier precision specialists, mid-tier cost optimizers, and regional volume fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as financing structures shift toward recurring service revenue models.
Within the premium-tier precision segment, Carl Zeiss AG and Leica Microsystems exemplify channel control through vertically integrated optical manufacturing. Zumax Medical Co., Ltd. occupies a position among modular system specialists competing on total cost of ownership reduction. These three anchors demonstrate how geographic origin and corporate structure correlate with strategic archetype positioning across university hospital, private clinic, and mobile deployment segments.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| Leica Microsystems |
| Zumax Medical Co., Ltd. |
| Global Surgical Corporation |
| Seiler Instrument |
| Labo America, Inc. |
| Karl Kaps GmbH & Co. KG |
| Foshan SOCO Precision Instrument Co., Ltd. |
| Alltion (Wuzhou) Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Japanese optical glass manufacturers determines both the premium commanded by apochromatic lens systems and the vulnerability of mid-tier assemblers to export restriction shocks. Equipment leasing structures compress upfront hardware margins while elevating recurring service revenue as the primary profitability anchor across procurement tiers.
Pricing Analysis
Certification level creates the primary spread across procurement tiers, with FDA 510(k)-cleared and CE MDR-marked systems commanding substantial premiums over uncertified alternatives in institutional channels. Three-tier pricing structure separates university hospital configurations with integrated 4K documentation from mid-tier clinic systems and economy portable units for mobile deployment. Cost compression in the economy tier intensifies as domestic Chinese manufacturers expand modular upgrade paths. Solo private practices in Texas and Florida exhibit highest price sensitivity, while German academic medical centers prioritize optical performance over acquisition cost.
Supply Chain Analysis
Export control regimes restricting precision optical technology flows constrain component access for manufacturers outside Germany and Japan. Apochromatic lens production concentrates in Stuttgart and Munich clusters, with LED illumination module assembly centered in China's Yangtze River Delta. Raw material dependencies encompass rare earth elements for lens coatings, high-purity optical glass substrates, and semiconductor sensors for integrated video systems. Single-source vulnerability in German optical glass supply creates exposure to geopolitical disruption. Distribution runs through specialized dental equipment distributors with regional service technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental surgical microscope incumbents face sustained substitution pressure from magnification loupes satisfying routine procedures, requiring defensive positioning around precision workflows beyond loupe capability.
For Market Incumbents: Build certification moats through accelerated CE MDR and FDA 510(k) pathway investments that raise compliance barriers for modular competitors. Deepen backward integration into apochromatic lens manufacturing to secure supply continuity against German and Japanese export restrictions. Anchor hospital system partnerships around training infrastructure for microsurgical technique certification, addressing the operator pool expansion constraint that limits market penetration. For New Entrants and Emerging Players: Pursue white-space capture in portable configurations for federally qualified health center mobile dental units across rural United States markets. Target the mid-tier clinic segment with fluorescence-filter hybrid systems that merge diagnostic and operative workflows. Deploy leasing-first go-to-market structures that align with capital-constrained private practice procurement patterns in Texas and Florida. For Investors and Strategic Acquirers: EU MDR post-market surveillance mandates reshape the acquisition landscape toward vendors with established quality management systems and vigilance infrastructure. Frame long-term viability around recurring service revenue streams displacing transactional hardware sales across the projection horizon. Target modular system specialists with upgrade-path intellectual property. Monitor reimbursement code expansions for microsurgical dental procedures as the primary inflection signal for upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR compliance timelines determine competitive access to German and French hospital procurement. |
| Hospital System Partnership | University hospital training center placements lock in resident education pathways and future clinic demand. |
| Software Companion Development | Teledentistry platform integration elevates documentation capabilities toward malpractice insurer requirements. |
| Reimbursement Strategy | National health system code expansion directly influences private practice upgrade cycle timing. |
| Backward Integration into Optics | In-house apochromatic lens production mitigates German and Japanese supply concentration risk. |
Research Methodology
A spread of perspectives from dental equipment procurement managers, biomedical engineers at university hospitals, GPO contracts specialists, and aftermarket service technicians converged on the working assumptions. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, EU MDR vigilance databases, hospital procurement records, and dental school curriculum documentation. Bottom-up equipment placement tracking and top-down market sizing triangulated volume estimates across the analysis window.
Demand-supply balance dynamics anchored the forecast framework, with segmentation across product type, end user, technology, and application dimensions modeled throughout the projection horizon. CAGRs derived from installed base replacement cycles, teledentistry protocol maturation rates, and reimbursement code expansion trajectories. Procedure-specific magnification requirements and mobile dental unit deployment mandates served as industry-specific forecast inputs.
Sensitivities concentrate around PMDA approval timeline extensions, EU MDR vigilance cost escalation, and loupe substitution thresholds in general dentistry. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and training curriculum standardization. Material shifts in optical glass export controls or microsurgical reimbursement coverage would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Global Biopsy Needles Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Global Gauze Swabs Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Global Surgical Suction Instruments Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Endometrial Ablation Market