
 Neonatal Infant Care Market | 2026-2036
Neonatal Infant Care Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal Infant Care Market Analysis
Hospital procurement committees are bifurcating between premium integrated systems and modular point-of-care upgrades as budget pressures intensify across developed health systems. GE Healthcare leverages its installed base of maternal-infant care platforms to sustain recurring service revenue in North American academic medical centers. Drägerwerk AG & Co. KGaA anchors its position through German-engineered ventilation interfaces that dominate European NICU retrofit cycles. Philips Healthcare differentiates via ambient experience lighting and noise-reduction protocols that command premium placement in Gulf state greenfield hospitals.
Neonatal infant care encompasses thermoregulation, cardiorespiratory monitoring, phototherapy, and nutritional delivery systems engineered for patients below 37 weeks gestational age or under 2,500 grams birth weight, with incubators typically maintaining 36.0–36.5°C servo-controlled environments and radiant warmers delivering 100% relative humidity at body-temperature set points. Monitoring Devices capture the largest margin pool as multi-parameter platforms integrate pulse oximetry, capnography, and EEG into single bedside units that reduce alarm fatigue and nursing workload. Phototherapy Equipment is accelerating fastest as LED-based systems displace fluorescent tubes in outpatient and home care channels where bilirubin management extends beyond traditional hospital stays. Incubators remain mature in Western Europe and North America but see replacement demand across Southeast Asian tertiary centers building level-III NICU capacity.
FDA premarket notification requirements for neonatal ventilators and warming devices enforce electromagnetic compatibility and thermal safety testing that extends development timelines by 12–18 months for non-US manufacturers. CE marking under the EU Medical Device Regulation mandates clinical evidence for novel neonatal interfaces, pushing European vendors toward post-market surveillance investments that reshape competitive cost structures. Stakeholders must monitor how Japan's PMDA streamlines priority review for neonatal orphan devices and whether India's CDSCO aligns with ISO 13485 to unlock import substitution in its expanding government hospital network.
Market Dynamics
Integrated monitoring platforms are consolidating previously siloed thermoregulation, cardiorespiratory, and neurological surveillance into unified bedside architectures, forcing equipment vendors to restructure R&D roadmaps around interoperability rather than standalone device excellence.
Growth Catalysts
- EU MDR clinical evidence mandates:Post-market surveillance investments by European vendors are accelerating platform consolidation as manufacturers bundle devices to amortize regulatory compliance costs across integrated systems.
- Level-III NICU construction in Southeast Asia:Government hospital networks in Vietnam, Thailand, and Indonesia are procuring complete neonatal infrastructure suites, creating pull-through demand for monitoring and respiratory platforms.
- LED phototherapy miniaturization:Solid-state lighting advances enable home-care bilirubin management, extending treatment episodes beyond traditional inpatient stays and opening ambulatory revenue streams.
Market Restraints
- Electromagnetic compatibility testing costs:FDA premarket notification requirements for warming devices impose 12–18 month timeline extensions on non-US manufacturers, compressing their viable market entry windows.
- Single-source sensor dependencies:Pulse oximetry and capnography modules rely on concentrated semiconductor supply chains in East Asia, exposing procurement committees to allocation risk during component shortages.
- Fluorescent phototherapy residual stock:Existing installed bases of tube-based systems in secondary hospitals create substitution inertia that slows LED upgrade cycles despite superior efficacy profiles.
Strategic Opportunities
- Japan PMDA priority review pathway:Streamlined orphan device designation for neonatal innovations reduces time-to-reimbursement for novel respiratory interfaces targeting premature populations under 1,000 grams.
- Remote patient monitoring convergence:Integration of wireless telemetry with cloud-based analytics platforms enables tertiary centers to extend surveillance coverage into step-down nurseries and regional referral networks.
- India CDSCO ISO 13485 alignment:Regulatory harmonization unlocks import substitution potential as domestic manufacturers qualify for government hospital tenders previously restricted to CE-marked or FDA-cleared equipment.
Industry Challenges
- Neonatal biomedical engineering specialization:Shortage of clinicians trained in servo-controlled thermoregulation and multi-parameter alarm management constrains effective utilization of advanced monitoring platforms.
- Legacy incubator protocol integration:Academic medical centers face technical debt when retrofitting 1990s-era warming devices with modern data architectures, requiring costly middleware development.
- CE marking MDR technical documentation:Novel neonatal interfaces must generate clinical evidence portfolios that extend development cycles and strain mid-cap manufacturer regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal Infant Care Market |
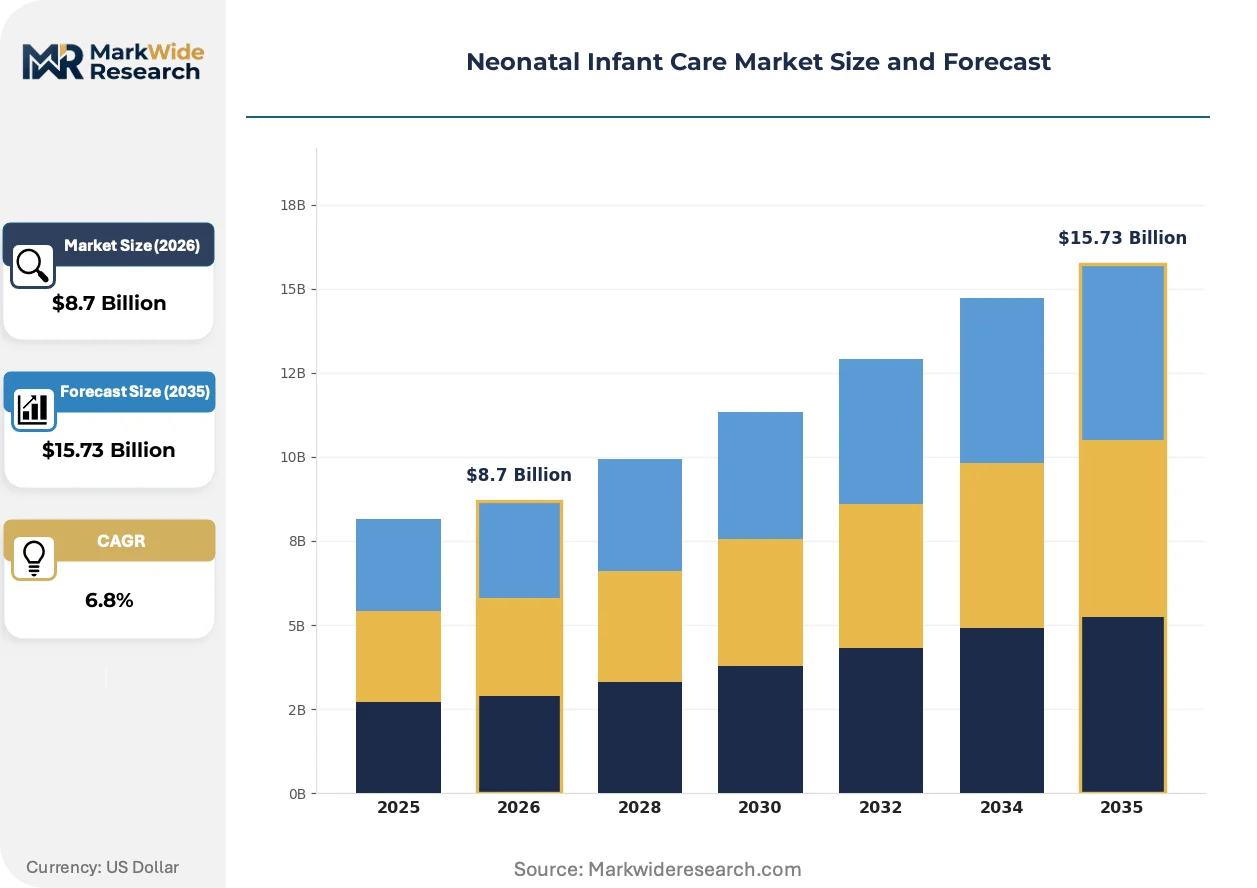
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incubators, Radiant Warmers, Phototherapy Equipment, Monitoring Devices End User: Hospitals, Clinics, Neonatal Units, Home Care Services Delivery Mode: In-Hospital, Out-Patient, Mobile Health, Telehealth Solutions Application: Premature Care, Respiratory Support, Nutritional Support, Infection Management |
| Companies Covered | GE Healthcare, Drägerwerk AG & Co. KGaA, Medtronic, Philips Healthcare, Masimo Corporation, Fisher & Paykel Healthcare, Natus Medical Incorporated, Atom Medical Corporation, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal Infant Care Market Emerging Trajectories
Neonatal care technology is pivoting from standalone device excellence toward ecosystem interoperability, with regulatory pressure and reimbursement mechanics accelerating platform consolidation over point-solution procurement.
Multi-parameter monitoring architectures are fragmenting traditional device categories by embedding pulse oximetry, capnography, and amplitude-integrated EEG into single bedside units. Tertiary hospital procurement committees in the United States, Germany, and Japan are specifying these integrated platforms for new NICU construction, compressing demand for standalone monitors and forcing vendors to restructure service organizations around unified calibration and maintenance protocols.
CE marking under the EU Medical Device Regulation now mandates clinical evidence for novel neonatal interfaces rather than predicate equivalence. European vendors are redirecting R&D budgets toward post-market surveillance infrastructure and real-world evidence collection, reshaping competitive cost structures and favoring larger manufacturers with dedicated regulatory affairs capacity over specialized entrants.
Hospital procurement committees are bifurcating acquisition strategies between premium integrated systems and modular point-of-care upgrades as budget pressures intensify across developed health systems. Gulf state greenfield hospitals favor complete platform deployments, while North American academic medical centers prioritize incremental enhancements to existing maternal-infant care footprints, with service contract unbundling emerging as a negotiation lever in both contexts.
Neonatal Infant Care Market Segmentation
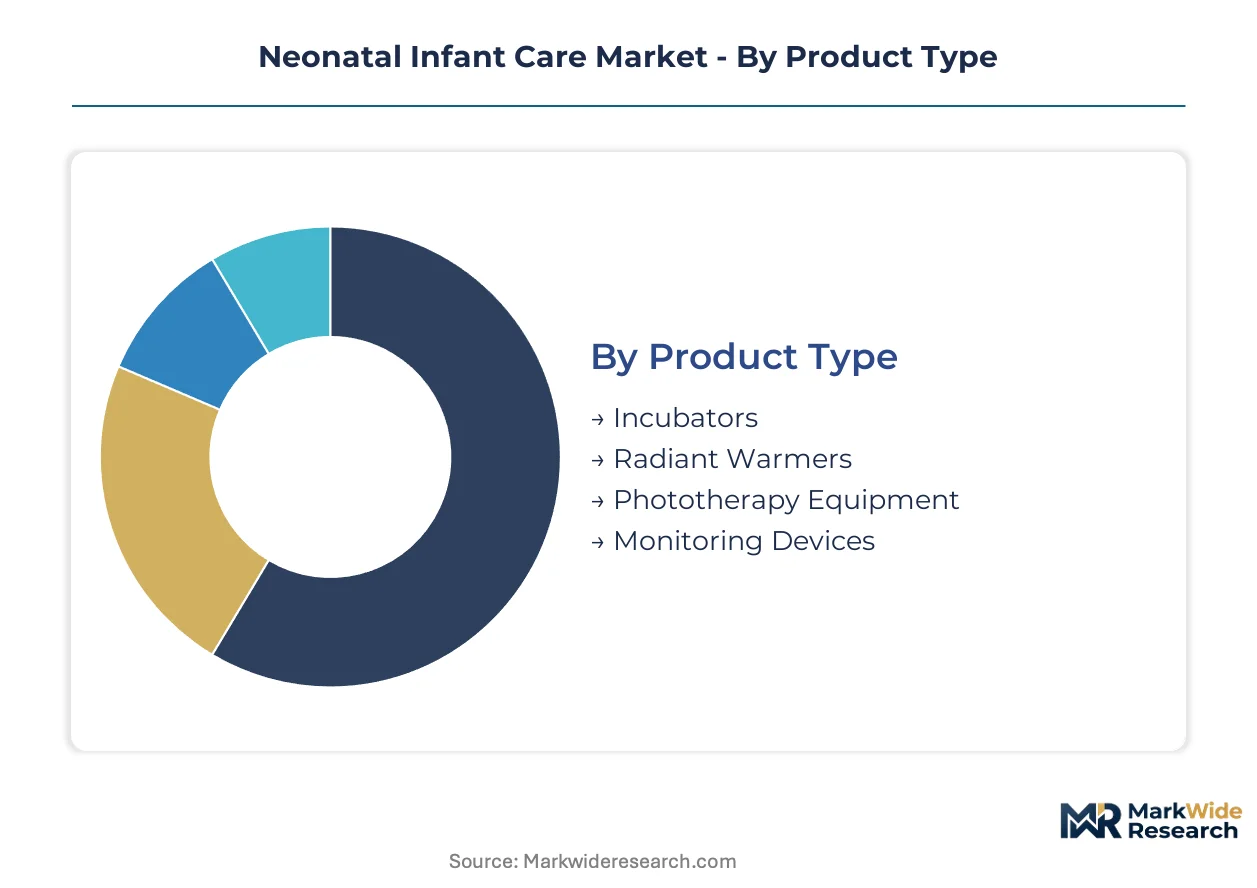
Segmentation in neonatal infant care reveals distinct procurement patterns across acute versus ambulatory settings, with technology maturity and reimbursement pathways determining channel economics for each product category.
Product Type:
Channel mix varies sharply: incubators and radiant warmers flow through hospital capital equipment committees with 5-7 year replacement cycles, while phototherapy and monitoring devices penetrate outpatient and home care via distributor networks.
- Incubators:Double-walled servo-controlled enclosures maintain 36.0–36.5°C with humidity regulation for infants under 1,500 grams. Demand concentrates in Vietnamese and Indonesian tertiary centers building level-III NICU capacity as government hospital networks expand infrastructure.
- Monitoring Devices:Multi-parameter platforms integrate pulse oximetry, capnography, and amplitude-integrated EEG into single bedside units. Procurement committees in United States academic medical centers specify these for new construction to reduce alarm fatigue and nursing workload.
- Radiant Warmers:Open-care platforms delivering 100% relative humidity at body-temperature set points for resuscitation and procedures.
- Phototherapy Equipment:LED-based systems displacing fluorescent tubes in ambulatory bilirubin management.
Incubators dominate installed base across Southeast Asian expansion projects. Monitoring Devices represent where margin expansion concentrates.
End User:
Customer type determines service contract structures, with hospitals demanding comprehensive preventive maintenance while home care operators prioritize portable device reliability and remote troubleshooting capabilities.
- Hospitals:Tertiary centers with level-III NICUs procure integrated platform suites bundling thermoregulation, monitoring, and respiratory support. German university hospitals anchor European demand through CE marking-driven retrofit cycles.
- Neonatal Units:Dedicated perinatal centers within larger hospital systems command premium placement for ambient experience technologies including noise-reduction protocols and circadian lighting systems.
- Clinics:Secondary maternity facilities with limited surgical capabilities.
- Home Care Services:Post-discharge bilirubin monitoring and low-acuity respiratory support.
Hospitals capture the highest equipment expenditure per bed. Home Care Services is climbing the fastest as early discharge protocols extend treatment episodes beyond traditional inpatient stays.
Delivery Mode:
Volume distribution tracks reimbursement fragmentation, with in-hospital procedures fully covered under DRG-based payment while mobile and telehealth solutions navigate variable private payer policies.
- In-Hospital:Continuous surveillance and intervention for infants under 28 weeks gestational age or under 1,000 grams birth weight. Japanese perinatal centers drive demand for integrated platforms through PMDA priority review pathways that accelerate novel respiratory interface adoption.
- Telehealth Solutions:Cloud-based analytics platforms enabling tertiary centers to extend monitoring coverage into regional referral networks. United States health systems deploy these for step-down nursery surveillance amid nursing shortage pressures.
- Out-Patient:Scheduled phototherapy and developmental follow-up.
- Mobile Health:Transport incubators and portable monitoring for inter-facility transfers.
In-Hospital retains the deepest technology penetration. Telehealth Solutions is gaining share fastest as workforce constraints force architectural decentralization of neonatal surveillance.
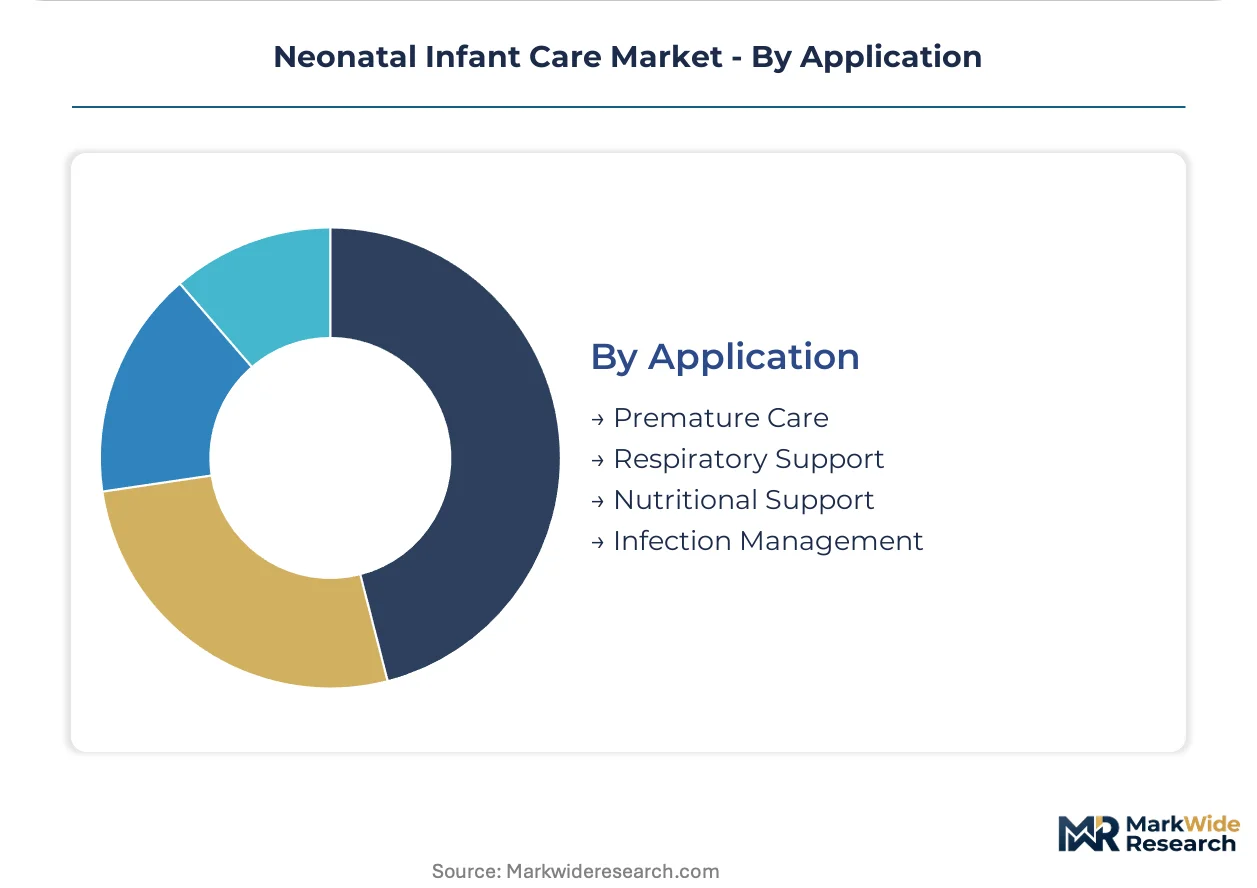
Application:
Clinical indication shapes regulatory pathway complexity, with respiratory support facing the most stringent FDA and CE marking requirements while infection management leverages predicate device frameworks.
- Respiratory Support:Non-invasive ventilation interfaces and high-flow nasal cannula systems for infants with respiratory distress syndrome. Development timelines extend 12–18 months for non-US manufacturers due to FDA electromagnetic compatibility and thermal safety testing mandates.
- Premature Care:Integrated thermoregulation and neurological surveillance for infants below 37 weeks gestational age. Gulf state greenfield hospitals specify complete platform deployments including ambient experience lighting and noise-reduction protocols.
- Nutritional Support:Enteral feeding pumps and parenteral delivery systems calibrated for micro-volumes.
- Infection Management:Phototherapy adjuncts and isolation incubator configurations.
Respiratory Support commands the highest R&D investment intensity. Premature Care is where platform consolidation accelerates most quickly as vendors bundle devices to amortize regulatory compliance costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics hub underwrites Western Europe's distribution dominance for neonatal care platforms, while Pacific Rim manufacturing corridors anchor component supply for integrated monitoring systems.
United States
Academic medical centers in Boston and Philadelphia drive integrated platform procurement for level-III NICU construction. FDA premarket notification requirements enforce electromagnetic compatibility testing that extends development timelines for warming devices. The Research Triangle Park cluster in North Carolina concentrates post-market surveillance infrastructure for respiratory support innovations.
Germany
University hospitals in Munich and Heidelberg anchor European demand through CE marking-driven retrofit cycles under EU MDR mandates. The country's national pharmaceutical regulator requires clinical evidence portfolios for novel neonatal interfaces rather than predicate equivalence. Baden-Württemberg's precision engineering corridor supplies servo-controlled thermoregulation components to regional OEMs.
Japan
Perinatal centers in Tokyo and Osaka leverage PMDA priority review pathways to accelerate novel respiratory interface adoption for infants under 1,000 grams. METI streamlines orphan device designation timelines for premature care innovations. The Kobe biomedical cluster concentrates amplitude-integrated EEG manufacturing for multi-parameter monitoring platforms.
India
Government hospital networks in Maharashtra and Tamil Nadu are expanding level-III NICU capacity through centralized procurement of complete infrastructure suites. CDSCO alignment with ISO 13485 unlocks import substitution as domestic manufacturers qualify for tenders previously restricted to CE-marked equipment. The Hyderabad medical device corridor incubates LED phototherapy assembly for Southeast Asian export.
Vietnam
Tertiary centers in Ho Chi Minh City and Hanoi are procuring integrated neonatal platforms as Ministry of Health hospital networks expand infrastructure. The country's national pharmaceutical regulator is harmonizing technical documentation requirements with ASEAN medical device directives. The Da Nang high-tech park is attracting regional distribution hubs for Southeast Asian retrofit demand.
Neonatal Infant Care Market Vendor Landscape
Listed leaders compete with private specialists across regulatory affairs capacity, creating a tiered structure where scale determines MDR compliance amortization. Consolidation pressure favors manufacturers with dedicated post-market surveillance infrastructure over specialized entrants. Three archetypes dominate: diversified health systems leveraging maternal-infant installed bases, precision engineering specialists anchoring European retrofit cycles, and ambient experience innovators capturing Gulf state greenfield premiums. Competitive moves concentrate on platform bundling to spread compliance costs and service contract unbundling as a negotiation lever.
Within the diversified health systems tier, GE Healthcare and Philips Healthcare exemplify archetypes competing through installed base leverage and ambient experience differentiation respectively. Drägerwerk AG & Co. KGaA occupies a position representing German-engineered precision specialists. These three anchors illustrate how geographic origin and corporate structure map onto divergent competitive vectors: US-based conglomerates, German GmbH & Co. KGaA engineering houses, and Dutch-origin health technology platforms each represent distinct strategic postures in procurement committee negotiations.
| Leading Market Players |
|---|
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Medtronic |
| Philips Healthcare |
| Masimo Corporation |
| Fisher & Paykel Healthcare |
| Natus Medical Incorporated |
| Atom Medical Corporation |
| Cardinal Health |
| Others |
Supply Flow & Price Mechanics
FDA premarket notification requirements for neonatal warming devices and ventilators simultaneously gate supply qualification and stratify price tiers, forcing non-US manufacturers to absorb extended development timelines that compress their viable entry windows while allowing domestic incumbents to command premium positioning.
Pricing Analysis
Volume-discount tiering structures separate integrated platform suites from modular point-of-care upgrades, with German-engineered precision systems and US-based maternal-infant care platforms commanding premium placement against Southeast Asian value-tier alternatives. Price differentiation rests on CE marking MDR compliance depth and FDA clearance status, with Gulf state greenfield hospitals showing lowest price sensitivity for complete ambient experience deployments while Vietnamese government tenders prioritize standard-tier procurement. Cost compression in fluorescent-to-LED phototherapy substitution is intensifying as outpatient channel expansion accelerates.
Supply Chain Analysis
Inventory lead-times for pulse oximetry and capnography modules extend during semiconductor allocation cycles, exposing procurement committees to component shortage vulnerability. Manufacturing concentrates in Germany, the United States, and Japan for precision thermoregulation components, while LED phototherapy assembly draws from Chinese and Indian electronics corridors. Single-source sensor dependencies in East Asian semiconductor supply chains create structural risk. Distribution runs through hospital capital equipment committees for incubators and radiant warmers, with phototherapy and monitoring devices penetrating outpatient channels via specialized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neonatal infant care market is entering a cyclical recovery phase as level-III NICU construction across Southeast Asian government hospital networks restarts capital expenditure flows delayed by pandemic-era budget freezes.
For Market Incumbents: Shield installed base revenue by unbundling service contracts as a negotiation lever against modular point-of-care competitors, and deepen backward integration into servo-controlled thermoregulation component production to offset semiconductor supply volatility. FDA premarket notification timeline advantages for domestic manufacturers represent a defensible moat against European and Asian entrants.
For New Entrants and Emerging Players: Post-market surveillance service gaps in EU MDR compliance create entry opportunity for regulatory affairs specialists targeting mid-cap European manufacturers lacking dedicated surveillance infrastructure. Home care phototherapy channels show highest penetrability given LED miniaturization trends and early discharge protocol expansion. Pursue distributor partnerships with Southeast Asian government tender systems as the fastest qualification pathway.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated monitoring platform development as multi-parameter bedside unit R&D absorbs greater regulatory compliance costs. Long-term viability favors manufacturers with demonstrated CE marking MDR technical documentation capacity and established post-market surveillance infrastructure. Monitor Japan PMDA priority review pathway utilization rates as inflection indicator for novel respiratory interface adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evidence mandates favor manufacturers with dedicated regulatory affairs infrastructure over specialized entrants. |
| Hospital System Partnership | Academic medical center procurement committees specify integrated platforms for new level-III NICU construction. |
| Software Companion Development | Cloud-based analytics platforms enable tertiary centers to extend surveillance into step-down nurseries and regional networks. |
| Reimbursement Strategy | Japan PMDA priority review pathways accelerate time-to-reimbursement for novel respiratory interfaces under 1,000 gram targets. |
| Backward Integration | In-house production of servo-controlled thermoregulation components reduces exposure to East Asian semiconductor allocation risk. |
Methodological Framework
Cross-validation between primary interviews with NICU administrators, biomedical engineers, hospital procurement committee members, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, CE marking MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across product type, end user, delivery mode, and application segments triangulates with top-down macroeconomic drivers.
Sensitivity analysis frameworks test forecast robustness across regulatory timeline scenarios and semiconductor supply disruption assumptions over the projection horizon. Segmentation dimensions modeled include product category maturity, acuity level, reimbursement pathway, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, capacity expansion announcements, and technology substitution rates. Forecast inputs incorporate LED phototherapy miniaturization curves and level-III NICU construction pipelines.
Forecasts assume regulatory continuity in FDA premarket notification requirements, EU MDR clinical evidence mandates, and Japan PMDA priority review pathways; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Umbilical Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal and Infant Care Equipment Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Europe Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Dialysis Market