
 Neonatal Dialysis Market | 2026-2036
Neonatal Dialysis Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal Dialysis Market Analysis
The split between premium integrated systems and commodity consumables is hardening in neonatal dialysis. Fresenius Medical Care dominates high-end machine platforms through captive supply of proprietary cartridges. Baxter International competes across peritoneal dialysis kits with manufacturing scale that anchors its hospital contracts. Asahi Kasei Medical specializes in membrane filtration components that differentiate its technology leadership in ultrafiltration precision.
Neonatal dialysis encompasses blood purification therapies engineered for infants below 28 days gestational age, typically requiring extracorporeal circuits with priming volumes under 50 milliliters and ultrafiltration accuracy to 10 milliliter precision. Its primary purpose is correcting electrolyte imbalances and fluid overload in critically ill neonates with acute kidney injury or congenital anomalies. Continuous Renal Replacement Therapy leads technology adoption in pediatric hospitals due to hemodynamic tolerance in unstable patients, while Bioartificial Kidneys represent the fastest-growing segment as experimental platforms advance toward clinical validation. Peritoneal Dialysis Kits retain margin concentration in home health care settings where reimbursement favors disposable recurring revenue.
FDA pediatric humanitarian device exemptions and EMA pediatric investigation plans shape product development timelines and market access for neonatal-specific devices, while ISO 13959 water quality standards constrain hemodialysis system design. Japan's PMDA accelerates conditional approvals for orphan pediatric indications, creating parallel regulatory tracks that fragment certification requirements across major markets. Stakeholders must monitor convergence between bioartificial kidney clinical data and payer willingness to fund experimental modalities outside established dialysis reimbursement.
Market Dynamics
The convergence of miniaturized extracorporeal circuit design with FDA pediatric humanitarian device exemptions is compressing development timelines and reshaping competitive entry barriers for neonatal-specific platforms.
Growth Catalysts
- FDA Pediatric Pathways:Humanitarian device exemptions accelerate regulatory clearance for devices targeting orphan neonatal indications, reducing time-to-market for specialized hemofiltration systems.
- Tertiary NICU Infrastructure:Pediatric hospitals in the United States and Germany are expanding dedicated dialysis units with integrated continuous renal replacement therapy capabilities.
- Membrane Filtration Precision:Advances in hollow-fiber membrane manufacturing enable ultrafiltration accuracy to 10 milliliter precision, supporting hemodynamic stability in critically ill neonates.
Market Restraints
- Input Cost Volatility:Specialized biocompatible polymers for circuit priming components face price instability from concentrated petrochemical feedstock suppliers.
- Supply Concentration Risk:Proprietary cartridge systems tie hospitals to single-source machine platforms, limiting negotiating leverage and switching flexibility.
- Technical Limitation:Current bioartificial kidney platforms remain experimental with unresolved vascular access durability for sub-2 kilogram patients.
Strategic Opportunities
- Home Health Peritoneal Dialysis:Reimbursement structures in Japan favor disposable recurring revenue models for outpatient neonatal care.
- EMA Pediatric Investigation Plans:Structured development incentives create parallel regulatory tracks that reward early clinical validation in European markets.
- Bioartificial-CRRT Convergence:Integration of renal tubule assist devices with continuous hemofiltration circuits opens hybrid therapeutic categories.
Industry Challenges
- Specialized Perfusionist Shortage:Operating miniaturized extracorporeal systems demands rare pediatric nephrology-critical care cross-training that academic programs undersupply.
- ISO 13959 Compliance Burden:Water quality standards for hemodialysis require capital-intensive infrastructure upgrades that strain smaller pediatric hospital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal Dialysis Market |
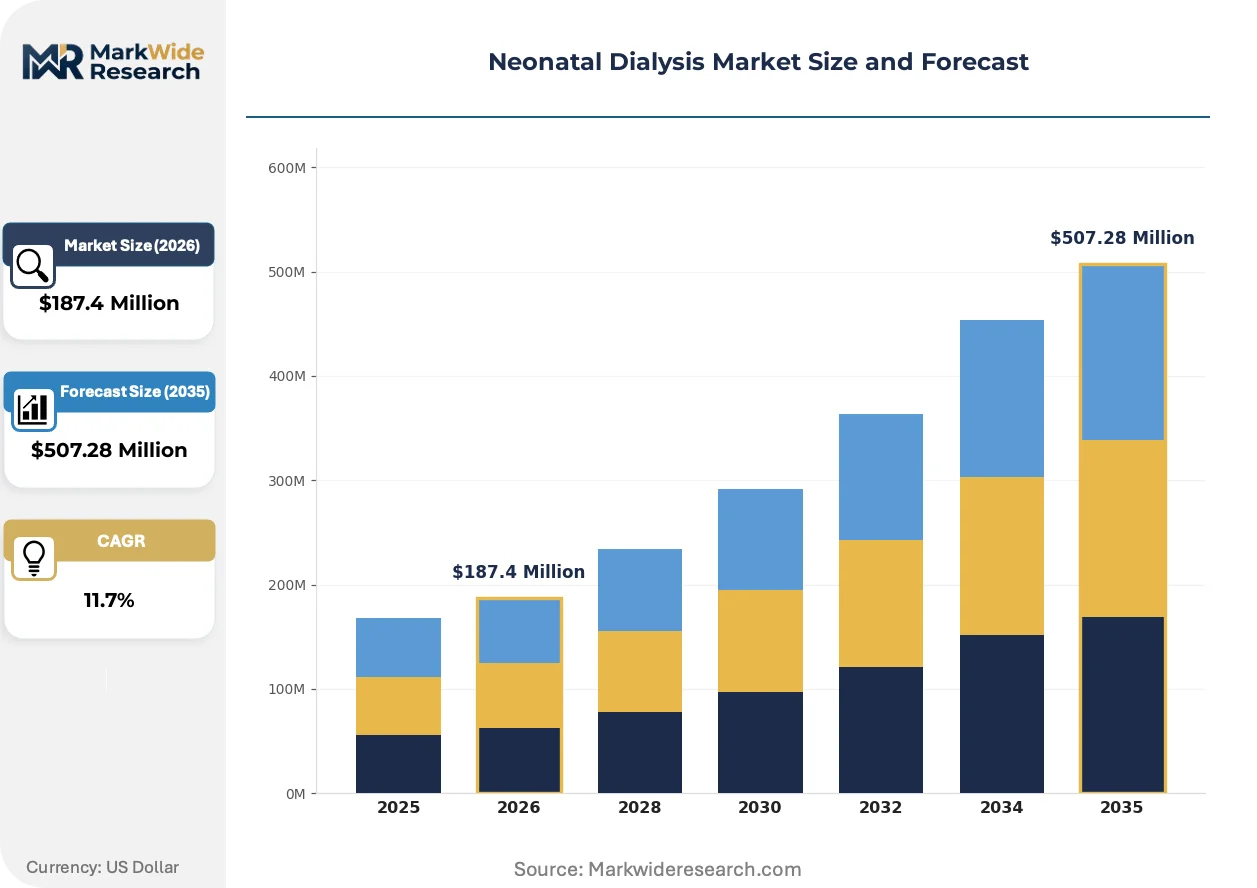
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialysis Machines, Catheters, Hemodialysis Equipment, Peritoneal Dialysis Kits End User: Pediatric Hospitals, Specialty Clinics, Home Health Care, Research Institutions Technology: Continuous Renal Replacement Therapy, Automated Peritoneal Dialysis, Membrane Filtration, Bioartificial Kidneys Application: Acute Kidney Injury, Chronic Kidney Disease, Transplant Preparation, Fluid Management |
| Companies Covered | Fresenius Medical Care, Medtronic, Baxter International, B. Braun, Nikkiso, Asahi Kasei Medical, Bellco, Omnica Corporation, Infomed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal Dialysis Market Emerging Trajectories
Neonatal dialysis technology is pivoting from scaled-down adult systems toward purpose-built platforms with circuit architectures engineered specifically for neonatal physiology and fluid management requirements.
Microfluidic circuit design is electrifying the field by enabling priming volumes under 50 milliliters that match neonatal blood volume constraints. Pediatric intensive care units in Germany and Japan are piloting these platforms for acute kidney injury protocols. The technology is compressing the gap between hemofiltration safety margins and therapeutic efficacy thresholds.
PMDA conditional approval pathways for orphan pediatric indications are creating accelerated regulatory tracks that diverge from standard device certification timelines. Japanese manufacturers leverage this framework to commercialize experimental platforms before completing full pivotal trials. Bioartificial kidney developers target Japan as the initial commercialization geography for this reason.
Hospital procurement for neonatal dialysis is consolidating around integrated service contracts that bundle machine placement, disposable supply, and clinical training. This displaces traditional capital purchase models in United States tertiary centers. Pediatric hospital networks in Texas and California have pioneered this structure, forcing equipment vendors to restructure pricing and support offerings.
Neonatal Dialysis Market Segmentation
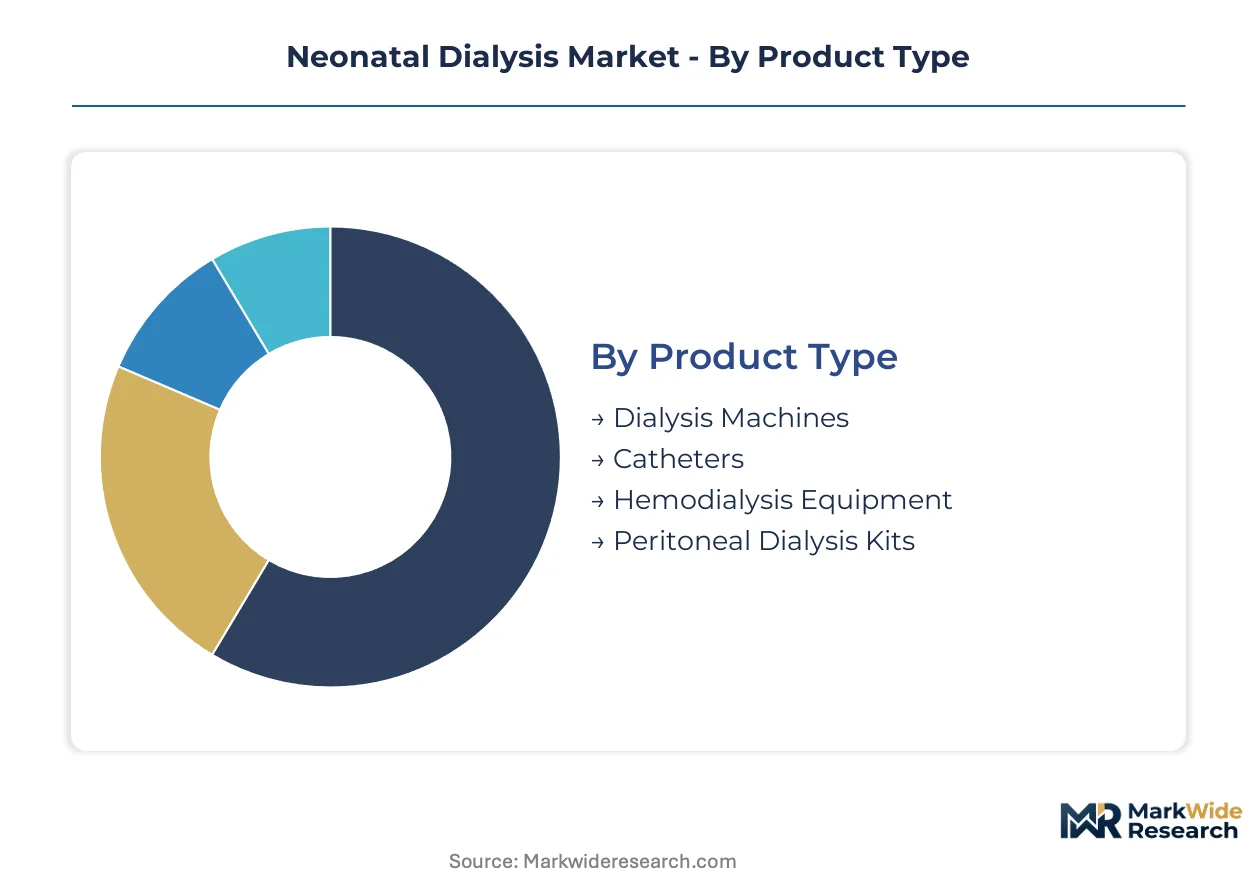
Neonatal dialysis procurement splits sharply between capital-intensive machine platforms and recurring consumable revenue streams. Hospital purchasing committees weight total cost of ownership differently across product categories, with technology maturity and regulatory clearance status driving contract structures.
Product Type:
Pediatric hospitals prioritize capital efficiency and disposable supply security when selecting equipment categories.
- Dialysis Machines:Integrated platforms with proprietary cartridge systems command premium placement in United States tertiary NICUs. Fresenius Medical Care and Baxter International dominate hospital contracts through bundled service agreements that lock in multi-year disposable supply commitments.
- Catheters:Vascular access devices engineered for sub-2 kilogram patients require specialized biocompatible materials and precision manufacturing. Demand concentrates in Germany and Japan where academic medical centers drive protocol standardization for acute kidney injury interventions.
- Hemodialysis Equipment:Miniaturized systems with priming volumes under 50 milliliters serve hemodynamically unstable neonates in pediatric intensive care units.
- Peritoneal Dialysis Kits:Disposable sets generate recurring revenue in home health settings where Japanese reimbursement favors outpatient chronic management.
Dialysis Machines lead on scale; Bioartificial Kidney convergence platforms gain momentum fastest.
End User:
Site of care determines reimbursement pathways and equipment specification requirements.
- Pediatric Hospitals:Tertiary NICUs in the United States and Germany deploy continuous renal replacement therapy capabilities for acute kidney injury protocols. These centers absorb capital costs for integrated platforms while training specialized perfusionist-nephrologist teams.
- Specialty Clinics:Outpatient dialysis centers in Japan manage stable chronic cases through automated peritoneal dialysis, leveraging PMDA conditional approval pathways for experimental modalities.
- Home Health Care:Family-managed peritoneal dialysis expands in markets with favorable reimbursement for disposable supply models.
- Research Institutions:Academic centers in Texas and California pilot bioartificial kidney platforms under FDA humanitarian device exemptions.
Pediatric Hospitals anchor installed base volume; Home Health Care expands most quickly.
Technology:
Clinical indication and patient hemodynamic stability dictate technology selection.
- Continuous Renal Replacement Therapy:Sustained low-efficiency dialysis maintains fluid and electrolyte balance in critically ill neonates with hemodynamic instability. CRRT dominates adoption in German and United States pediatric ICUs where multi-organ failure protocols require gentle ultrafiltration.
- Automated Peritoneal Dialysis:Cycler-based nocturnal therapy enables chronic management without continuous nursing supervision. Japanese home health programs favor this modality for stable patients discharged from tertiary centers.
- Membrane Filtration:Hollow-fiber precision manufacturing from Asahi Kasei Medical enables 10 milliliter ultrafiltration accuracy.
- Bioartificial Kidneys:Renal tubule assist devices remain experimental with unresolved vascular access durability for extremely low birth weight infants.
Continuous Renal Replacement Therapy holds dominant share; Bioartificial Kidneys pursue steepest expansion trajectory.
Application:
Acuity level and treatment duration shape equipment configuration and supply consumption patterns.
- Acute Kidney Injury:Sudden renal function loss in septic or asphyxiated neonates demands immediate CRRT initiation with precise ultrafiltration control. This indication drives machine placement in United States and German pediatric hospitals expanding dedicated dialysis units.
- Chronic Kidney Disease:Congenital anomalies requiring long-term management favor peritoneal dialysis for growth preservation and neurodevelopmental protection. Japanese reimbursement structures support home-based chronic therapy.
- Transplant Preparation:Bridge-to-transplant dialysis stabilizes infants awaiting donor organ availability.
- Fluid Management:Elective ultrafiltration supports cardiopulmonary bypass recovery and congenital heart surgery recovery protocols.
Acute Kidney Injury generates highest equipment utilization; Transplant Preparation shows fastest protocol adoption growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains denser tertiary NICU infrastructure per capita than the United States, while Japan accelerates experimental platform commercialization through conditional regulatory pathways. Both markets anchor regional demand patterns with divergent procurement philosophies.
United States
Pediatric hospital networks in Texas and California pioneer bundled service contracts that displace traditional capital purchase models. FDA humanitarian device exemptions compress timelines for specialized hemofiltration systems targeting orphan neonatal indications. Academic medical centers in Boston and Houston absorb capital costs for integrated continuous renal replacement therapy platforms.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia drive protocol standardization for acute kidney injury interventions. EMA pediatric investigation plans create structured development incentives that reward early clinical validation. Hollow-fiber membrane manufacturing clusters in Baden-Württemberg enable 10 milliliter ultrafiltration precision for hemodynamic stability.
Japan
PMDA conditional approval pathways for orphan pediatric indications fragment certification requirements from standard device timelines. Home health programs in Tokyo and Osaka favor automated peritoneal dialysis cycler systems for stable chronic cases. Manufacturers leverage accelerated tracks to commercialize experimental platforms before completing full pivotal trials.
United Kingdom
NHS specialized commissioning frameworks concentrate neonatal dialysis capacity in designated tertiary centers across London and the Midlands. MHRA alignment with EMA pediatric investigation plans streamlines parallel regulatory submissions. Research institutions in Cambridge and Oxford pilot bioartificial kidney platforms under convergent FDA-EMA frameworks.
Neonatal Dialysis Market Vendor Landscape
Top-tier vendors anchor hospital contract structures through bundled machine-and-consumable agreements, while mid-scale specialists compete on membrane filtration precision and regional service density. The vendor base stratifies across three functional tiers: integrated platform providers, disposable kit manufacturers, and component specialists supplying hollow-fiber membranes and precision filtration elements. Two dominant competitive moves are reshaping positioning: captive supply chain integration into proprietary cartridge systems, and geographic expansion through academic medical center partnerships in high-NICU-density markets.
Within the integrated platform tier, Fresenius Medical Care and Baxter International exemplify divergent strategic anchoring—Fresenius represents machine-platform dominance through proprietary cartridge ecosystems, while Baxter occupies a position spanning peritoneal dialysis kit manufacturing scale. Asahi Kasei Medical sits within the component specialist archetype, supplying membrane filtration elements that differentiate technology leadership in ultrafiltration precision for sub-50-milliliter priming volumes.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Medtronic |
| Baxter International |
| B. Braun |
| Nikkiso |
| Asahi Kasei Medical |
| Bellco |
| Omnica Corporation |
| Infomed |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany and Japan anchor membrane filtration component manufacturing, constraining pricing flexibility for machine-platform vendors dependent on hollow-fiber supply while reinforcing premium positioning for integrated systems with captive cartridge production.
Pricing Analysis
Bundled service contracts dominate United States tertiary NICUs while unbundled consumable procurement persists in European academic centers. Three-tier pricing structure across premium integrated platforms, standard modular systems, and economy peritoneal kits reflects FDA clearance tier and after-sales training intensity. Pricing pressure stems from hospital procurement consolidation in Texas and California networks demanding multi-year fixed-rate agreements. Pediatric hospitals exhibit lowest price sensitivity for CRRT platforms due to hemodynamic stability requirements, while home health providers in Japan negotiate aggressively on peritoneal dialysis kit volumes.
Supply Chain Analysis
ISO 13959 water quality certification and FDA pediatric device qualification gate entry for hemodialysis system suppliers, extending development timelines for new entrants. Manufacturing concentrates in Germany, Japan, and the United States for precision hollow-fiber membranes, biocompatible polymers, and miniaturized pump assemblies. Specialized polymer feedstocks for circuit priming components face single-source vulnerability from concentrated petrochemical suppliers. Distribution runs through hospital GPO contracts and direct academic medical center partnerships, with Japanese manufacturers leveraging PMDA conditional approval pathways for accelerated commercialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neonatal dialysis market functions as a stable compounder anchored by irreversible tertiary NICU infrastructure expansion and regulatory incentive structures that perpetuate premium pricing for cleared pediatric-specific platforms.
For Market Incumbents: Cement machine-platform dominance through backward integration into proprietary cartridge manufacturing, eliminating hollow-fiber supply vulnerability to Asahi Kasei Medical and German membrane specialists. Expand dedicated neonatal dialysis unit partnerships in Bavaria and North Rhine-Westphalia academic centers to preempt EMA pediatric investigation plan competitors. Lock in perfusionist-nephrologist training programs as switching costs against emerging bioartificial kidney platforms. For New Entrants and Emerging Players: Microfluidic circuit architectures with sub-50-milliliter priming volumes offer a technology-first wedge against scaled-down adult system incumbents. Target Japanese home health peritoneal dialysis as the most penetrable segment, exploiting PMDA conditional approval pathways that compress commercialization timelines versus FDA tracks. Pursue automated cycler development partnerships with Tokyo and Osaka discharge planning networks. For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists with hollow-fiber precision manufacturing capabilities and dormant pediatric regulatory filings. Long-term viability rests on bioartificial kidney clinical validation convergence with CRRT infrastructure, creating hybrid platform categories. Watch FDA humanitarian device exemption grant velocity as the inflection signal for experimental modality reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Conditional Approval Pursuit | Japanese regulatory pathway compresses commercialization timelines for experimental bioartificial kidney platforms before full pivotal completion. |
| Hospital System Partnership | Texas and California pediatric networks pioneer bundled service contracts that displace capital purchase models for integrated CRRT platforms. |
| Membrane Manufacturing Scale-Up | Baden-Württemberg hollow-fiber clusters enable 10-milliliter ultrafiltration precision that differentiates hemodynamic stability performance. |
| Reimbursement Strategy Development | Japanese disposable recurring revenue models for home health peritoneal dialysis anchor chronic case profitability outside acute hospital settings. |
| FDA Pediatric Pathway Navigation | Humanitarian device exemptions for orphan neonatal indications accelerate specialized hemofiltration system clearance timelines. |
Methodological Framework
Direct dialogue with pediatric nephrologists, NICU perfusionists, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers grounded qualitative findings, cross-validated against FDA 510(k) filings, EMA pediatric investigation plan databases, PMDA approval registries, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation reconciled equipment placement data with consumable volume flows.
Bottom-up modeling aggregated installed base counts by technology segment across United States, German, and Japanese tertiary centers, while top-down analysis calibrated aggregate market expansion against NICU bed growth projections and regulatory pathway velocity. Segmentation dimensions spanned product type, end-user site of care, technology modality, and application acuity. CAGRs derived from equipment replacement cycles, consumable utilization rates per patient-day, and reimbursement trajectory assumptions. Forecast inputs incorporated PMDA conditional approval conversion rates and FDA pediatric humanitarian exemption grant patterns.
The model holds under stable tertiary NICU infrastructure investment and sustained regulatory incentive structures; deviation in bioartificial kidney clinical validation timelines or reimbursement denial for experimental modalities would shift trajectory. Forecasts embed assumptions regarding membrane manufacturing scale and polymer feedstock supply continuity. A model refresh is warranted upon material change in FDA pediatric device review staffing levels or EMA pediatric investigation plan restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Umbilical Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
Preterm Birth Prevention and Management Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market