
 Neonatal and Prenatal Devices Market | 2026-2036
Neonatal and Prenatal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal and Prenatal Devices Market Outlook
The neonatal nursing workforce shortage is collapsing delivery capacity across multiple health systems. GE HealthCare leverages integrated maternal-infant care platforms to sustain installed base loyalty in tertiary centers. Koninklijke Philips N.V. dominates wireless fetal monitoring with sensor arrays that reduce bedside intervention. Medtronic anchors critical care ventilation portfolios for extremely low birth weight infants.
Neonatal and prenatal devices comprise thermoregulation systems, hemodynamic monitors, respiratory support apparatus, and diagnostic imaging equipment engineered for patients below 28 days postnatal and gestational assessment prior to delivery. Phototherapy devices incorporate LED arrays emitting 430-490 nm wavelength to treat unconjugated hyperbilirubinemia while minimizing heat stress and insensible water loss. Fetal monitors using pulsed Doppler ultrasound and tocodynamometry constitute the largest revenue pool among product categories, reflecting obstetric liability concerns and cesarean decision-support protocols. Wireless monitoring is displacing hardwired telemetry in labor suites, enabling ambulatory maternal positioning that shortens active labor duration.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and commercial launch sequencing for manufacturers. The analysis indicates stakeholders must monitor reimbursement parity between hospital-based and home-based maternal monitoring modalities as payers recalibrate perinatal episode payment frameworks.
Market Dynamics
Wireless telemetry architectures are collapsing the installed base of hardwired fetal monitoring systems across tertiary maternity units, forcing incumbents to defend replacement cycles through platform integration strategies.
Growth Catalysts
- EU MDR conformity assessments:Stricter technical documentation requirements for wireless fetal monitors are accelerating hospital procurement of next-generation platforms that preempt regulatory obsolescence.
- LED phototherapy arrays:Solid-state 430-490 nm wavelength devices reduce heat stress and insensible water loss in neonatal intensive care, expanding protocol adoption for unconjugated hyperbilirubinemia management.
- Tertiary hospital expansion in China:Provincial health commissions are scaling perinatal intensive care capacity, concentrating demand for hemodynamic monitors and respiratory support apparatus in tier-one cities.
Market Restraints
- Neonatal nursing workforce shortage:Specialized critical care training pipelines cannot match expansion of level III and IV nursery beds across United States health systems.
- Sensor component concentration:Piezoelectric pressure transducers and Doppler ultrasound crystals depend on limited Asian contract manufacturers, creating single-source vulnerability.
- FDA 510(k) pathway friction:Substantial equivalence determinations for wireless monitoring algorithms extend development timelines and compress commercialization windows.
Strategic Opportunities
- Home-based maternal monitoring:Reimbursement parity experiments in Germany are opening ambulatory telemetry channels that bypass hospital episode payment frameworks.
- AI-enabled cardiotocography interpretation:Machine learning classification of fetal heart rate patterns converges with wireless sensor arrays to reduce false-positive cesarean triggers.
- Sub-Saharan Africa:Underpenetrated markets for thermoregulation systems present white space as bilateral health financing scales neonatal mortality reduction programs.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for wireless device software components delay market entry by 8-14 months.
- Legacy telemetry integration:Hardwired infrastructure in existing labor suites requires costly retrofitting to accommodate hybrid wireless architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal and Prenatal Devices Market |
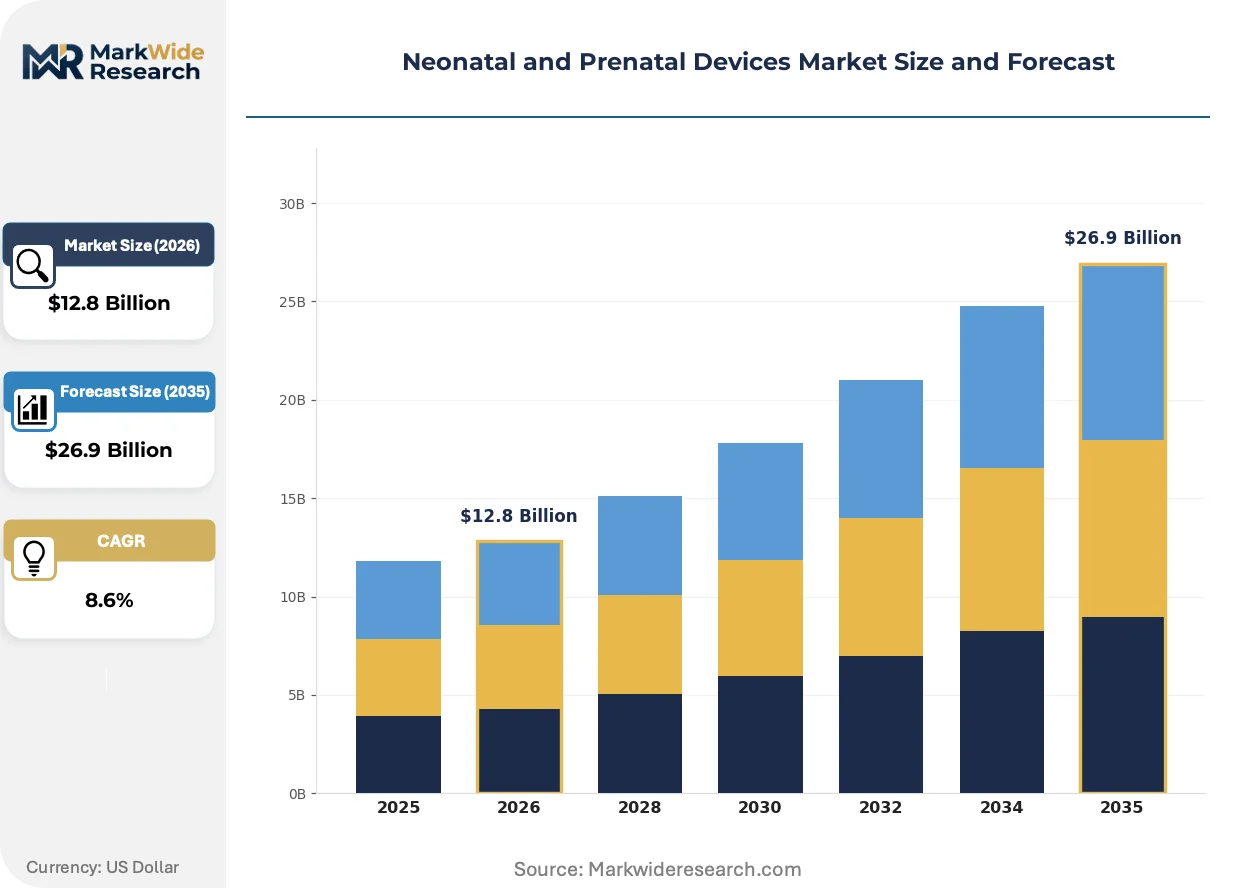
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incubators, Phototherapy Devices, Fetal Monitors, Delivery Beds Technology: Wireless Monitoring, Pulse Oximetry, Ultrasound Imaging, Blood Gas Analyzers End User: Hospitals, Clinics, Maternity Units, Home Care Application: Neonatal Care, Prenatal Monitoring, Labor Management, Maternal Health |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Medtronic, Drägerwerk AG & Co. KGaA, Masimo, Cardinal Health, Natus Medical Incorporated, Fisher & Paykel Healthcare Limited, Getinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal and Prenatal Devices Market Strategic Shifts
Digital biomarker extraction from continuous cardiotocography streams is redefining clinical decision protocols, compressing the gap between raw physiological data and actionable obstetric intelligence.
Capacitive sensing arrays for non-invasive fetal electrocardiography capture electrical signals through maternal abdominal electrodes without gel coupling or acoustic coupling. Tertiary maternity units in Germany and the United States are piloting these platforms for antepartum surveillance of arrhythmia. This contactless modality is supplanting traditional Doppler ultrasound for extended monitoring sessions, reducing cumulative thermal exposure and enabling sleep-state assessment.
EU MDR Article 10 technical documentation mandates for clinical evaluation reports now require post-market performance follow-up for all wireless fetal monitoring devices. Manufacturers must maintain systematic procedures to collect and review experience gained from devices in the post-production phase. Class IIa and IIb device categories face heightened scrutiny of biocompatibility and electromagnetic compatibility testing, driving consolidation of notified body relationships.
Hospital procurement committees are unbundling device acquisition from multi-year service contracts, forcing vendors to price monitoring hardware and predictive maintenance separately. This disintermediation of after-sales revenue is most visible in United States integrated delivery networks, where capital equipment committees now benchmark total cost of ownership across 7-10 year horizons rather than upfront capital expenditure alone.
Neonatal and Prenatal Devices Market Segmentation
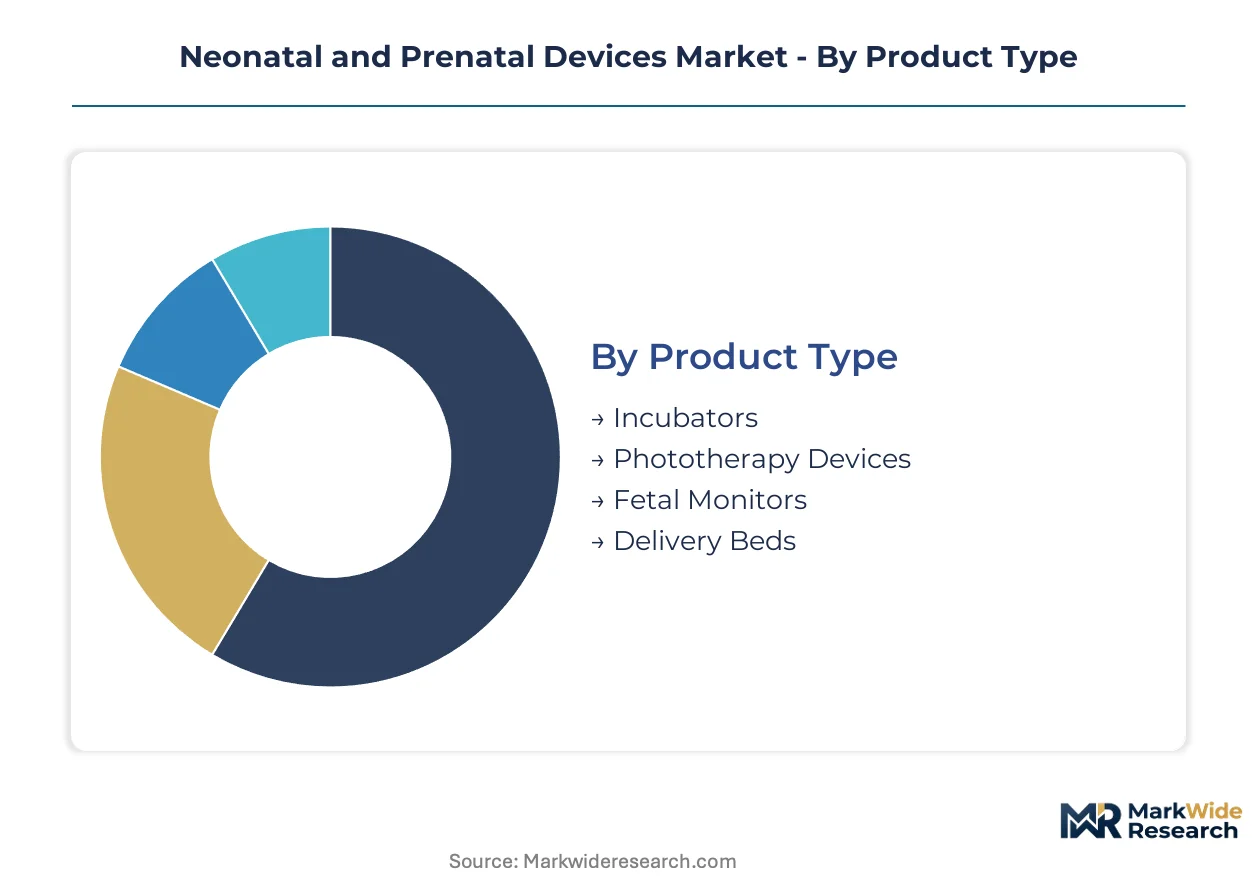
Segmentation in neonatal and prenatal devices reveals divergent margin structures across hardware platforms and monitoring modalities. Product mix decisions determine exposure to regulatory pathway complexity and service contract attach rates.
Product Type:
Margin pools concentrate in systems requiring intensive calibration protocols and disposable sensor ecosystems.
- Fetal Monitors:Pulsed Doppler ultrasound and tocodynamometry systems generate recurring revenue through transducer replacement cycles. Tertiary maternity units in the United States and Germany are consolidating procurement around platforms with wireless telemetry architectures that preempt EU MDR technical documentation requirements.
- Phototherapy Devices:Solid-state LED arrays emitting 430-490 nm wavelength eliminate infrared heat load associated with halogen predecessors. Hospitals in China are expanding protocol adoption for unconjugated hyperbilirubinemia management as provincial health commissions scale perinatal intensive care capacity.
- Incubators:Servo-controlled thermoregulation systems with humidity management modules anchor level III nursery infrastructure.
- Delivery Beds:Hydraulic and electric positioning platforms with Trendelenburg capability support obstetric emergency protocols.
Fetal monitors hold installed capacity. Phototherapy devices are rotating up the share rankings.
Technology:
Technology selection determines regulatory scrutiny intensity and software validation burden.
- Wireless Monitoring:Capacitive sensing arrays and Bluetooth Low Energy telemetry enable ambulatory maternal positioning in labor suites. FDA 510(k) substantial equivalence determinations for algorithm-enabled cardiotocography extend development timelines for manufacturers.
- Ultrasound Imaging:Portable systems with transabdominal and transvaginal probes support antepartum anatomical assessment. Demand concentrates in hospital-based maternity units across Germany where obstetric liability protocols mandate continuous surveillance capabilities.
- Pulse Oximetry:Reflectance and transmittance sensors for neonatal oxygen saturation monitoring integrate with multiparameter platforms.
- Blood Gas Analyzers:Point-of-care systems for arterialized capillary samples guide ventilator management in extremely low birth weight infants.
Wireless monitoring commands premium positioning. Pulse oximetry maintains volume leadership through platform bundling.
End User:
End user channel structure shapes pricing transparency and contract negotiation leverage.
- Hospitals:Tertiary centers with level III and IV nurseries drive procurement of hemodynamic monitors and respiratory support apparatus. United States integrated delivery networks benchmark total cost of ownership across 7-10 year horizons.
- Maternity Units:Dedicated obstetric facilities within hospital campuses concentrate demand for fetal monitoring infrastructure and delivery beds.
- Clinics:Outpatient prenatal assessment centers utilize portable ultrasound imaging for gestational dating and anatomical screening.
- Home Care:Ambulatory telemetry channels bypass hospital episode payment frameworks where reimbursement parity experiments enable remote maternal monitoring.
Hospitals anchor capital equipment demand. Home care is climbing the fastest as payment models shift.
Application:
Application focus determines regulatory classification and clinical evidence requirements.
- Neonatal Care:Thermoregulation systems, hemodynamic monitors, and respiratory support apparatus for patients below 28 days postnatal require ISO 13485 quality management system certification.
- Prenatal Monitoring:Fetal surveillance and maternal vital sign assessment prior to delivery constitute the largest revenue pool among application categories.
- Labor Management:Continuous cardiotocography and tocodynamometry guide cesarean decision-support protocols in tertiary maternity units.
- Maternal Health:Ambulatory blood pressure and glucose monitoring extend surveillance beyond acute care episodes.
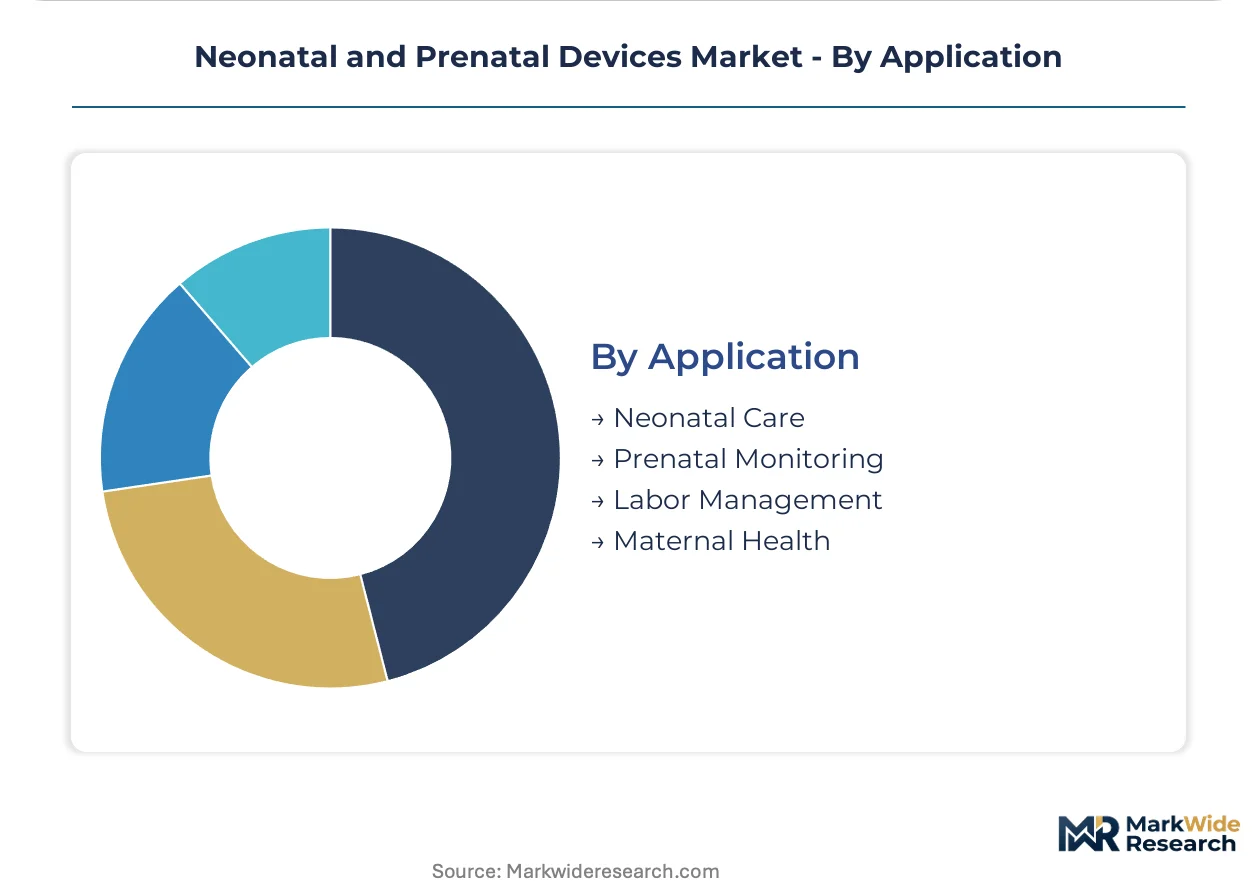
Prenatal monitoring holds installed capacity. Neonatal care is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways anchor procurement decisions in the United States, while EU MDR conformity assessments reshape competitive positioning across Germany. China's NMPA accelerates provincial hospital expansion. Regulatory divergence between these jurisdictions forces manufacturers to maintain parallel compliance architectures.
United States
Level III and IV nursery bed expansion drives demand for hemodynamic monitors and respiratory support apparatus. FDA 510(k) substantial equivalence determinations for wireless monitoring algorithms extend development timelines. Tertiary centers in Boston and Houston benchmark total cost of ownership across seven-to-ten-year horizons.
Germany
Reimbursement parity experiments for home-based maternal monitoring open ambulatory telemetry channels. EU MDR Article 10 technical documentation mandates require post-market performance follow-up for wireless fetal devices. Industrial clusters around Munich and Berlin concentrate notified body relationships and biocompatibility testing capacity.
China
Provincial health commissions scale perinatal intensive care capacity in tier-one cities. NMPA regulatory harmonization with international standards accelerates market entry for multinational manufacturers. Shanghai and Beijing anchor demand concentration for LED phototherapy arrays and servo-controlled incubators.
Japan
PMDA quality management system requirements enforce rigorous software validation for wireless monitoring platforms. METI industrial policy supports domestic production of piezoelectric pressure transducers. Tokyo-Osaka corridor hospitals prioritize integrated maternal-infant care platforms.
India
CDSCO medical device rules tighten registration requirements for imported neonatal thermoregulation systems. Central government health financing scales neonatal mortality reduction programs in underserved states. Maharashtra and Karnataka concentrate private hospital procurement of portable ultrasound imaging systems.
Neonatal and Prenatal Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with consolidated control over wireless telemetry architectures and respiratory support portfolios. Mid-scale regional fabricators compete on price for phototherapy devices and delivery beds. Strategic archetypes include platform integrators bundling hardware with predictive maintenance contracts, component specialists supplying Doppler ultrasound crystals and pressure transducers, and regional assemblers serving price-sensitive procurement committees. Dominant competitive moves include M&A to capture wireless algorithm capabilities and capacity expansion in tier-one Chinese cities to preempt provincial hospital procurement cycles.
Within the integrated platform tier, GE HealthCare and Koninklijke Philips N.V. exemplify archetypes combining maternal-infant care portfolios with installed base loyalty strategies. Medtronic occupies a position representing critical care ventilation specialization for extremely low birth weight applications. These three entities anchor competitive dynamics through their respective strengths in tertiary center relationships, wireless sensor arrays, and neonatal intensive care apparatus.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Medtronic |
| Drägerwerk AG & Co. KGaA |
| Masimo |
| Cardinal Health |
| Natus Medical Incorporated |
| Fisher & Paykel Healthcare Limited |
| Getinge |
| Others |
Value Chain & Pricing Dynamics
LED phototherapy arrays displacing halogen thermoregulation systems are redrawing component sourcing maps from Japanese precision optics hubs toward Taiwanese semiconductor packaging centers while collapsing the historical premium commanded by legacy thermal management platforms.
Pricing Analysis
Price spreads between United States tertiary centers and provincial Chinese hospitals exceed 40 percent for equivalent wireless fetal monitoring platforms. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard configurations, and economy-grade phototherapy devices without predictive maintenance bundling. Cost compression in the economy tier is intensifying as Indian regional assemblers enter delivery bed and incubator fabrication. Hospital procurement committees in integrated delivery networks exhibit lowest price sensitivity due to total cost of ownership benchmarking, while municipal health bureaus in tier-two Chinese cities demonstrate highest sensitivity to upfront capital expenditure.
Supply Chain Analysis
Strategic stockpiling of piezoelectric pressure transducers and Doppler ultrasound crystals has replaced just-in-time preferences among tier-one manufacturers following pandemic-era shortages. Component fabrication concentrates in Japan, South Korea, and coastal Chinese provinces. Raw material dependencies include rare-earth elements for magnetic resonance sensors, gallium nitride substrates for LED arrays, and specialized polymers for disposable transducer housings. Single-source vulnerability in Asian contract manufacturers for wireless telemetry chipsets constitutes the dominant structural risk. Distribution runs through regional medical device distributors with GPO contracting relationships in the United States and direct hospital sales forces in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless fetal monitoring adoption is still below 35 percent penetration in tier-one Chinese maternity units, creating substantial runway for platform vendors before saturation dynamics emerge.
For Market Incumbents: Compound installed base loyalty through predictive maintenance contracts that lock tertiary centers into sensor replacement ecosystems before EU MDR conformity assessments force hardware refresh cycles. Accelerate backward integration into piezoelectric transducer production to neutralize Asian contract manufacturer concentration risk. Prioritize software companion development for AI-enabled cardiotocography interpretation to defend against algorithm specialists. For New Entrants and Emerging Players: Lead with portable ultrasound imaging systems targeting outpatient prenatal clinics in India and sub-Saharan Africa where capital equipment budgets exclude tier-one platform procurement. Home-based maternal monitoring in Germany offers the most penetrable reimbursement environment for ambulatory telemetry challengers. Pursue hospital-at-home partnership models that bypass traditional capital equipment committees. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors wireless algorithm specialists with FDA 510(k) clearance momentum and notified body relationships in Germany. Long-term viability over the next decade rests on capturing the sensor-to-software data architecture that defines next-generation perinatal care platforms. Monitor NMPA registration velocity for multinational manufacturers as the inflection signal for Chinese provincial hospital procurement timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Wireless Algorithms | Accelerates market entry ahead of EU MDR technical documentation mandates for fetal monitoring platforms. |
| Hospital System Partnership | Locks multi-year sensor replacement revenue through integrated maternal-infant care platform deployments in tertiary centers. |
| CE Marking Pathway Investment | Preempts regulatory obsolescence of hardwired telemetry systems under Article 10 clinical evaluation requirements. |
| Software Companion Development | Captures recurring revenue from AI-enabled cardiotocography interpretation layered over hardware installed base. |
| Reimbursement Strategy for Home Monitoring | Exploits German parity experiments to bypass hospital episode payment frameworks for ambulatory telemetry. |
Study Parameters
The analysis maps fetal monitors, phototherapy devices, incubators, and wireless telemetry architectures, each validated through neonatal intensive care unit directors, hospital biomedical engineers, GPO contracts managers, and regulatory affairs specialists at device manufacturers. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, and NMPA registration records. Bottom-up demand modeling across product categories triangulated with top-down market sizing from hospital procurement database analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, technology modality, end user channel, and application focus dimensions while deriving expansion rates from procedure volume trajectories and replacement cycle dynamics. Forecast inputs included provincial hospital bed expansion targets in China, EU MDR transition timelines, and reimbursement parity pilot scale in Germany.
Underlying assumptions cover regulatory pathway stability and sensor component supply continuity, with deviation risk concentrated in FDA substantial equivalence determination delays and neonatal nursing workforce availability constraints. Practitioners should keep alternative scenarios live as wireless telemetry adoption curves and payer reimbursement frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Infant Resuscitators Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
Perinatal Software Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Critical Care Equipment Market