
 Endotracheal Tube Cuffs Market | 2026-2036
Endotracheal Tube Cuffs Market Size, Share, and Industry Trends Forecast 2026-2036
Endotracheal Tube Cuffs Market Foresight
Equipment leasing and pay-per-use anesthesia circuits are rewriting capital deployment patterns for airway device procurement. Medtronic leverages its hospital system partnerships to sustain high-volume cuff supply contracts across integrated delivery networks. Teleflex anchors its position through specialized intensive care product bundles that reduce switching costs for critical care departments.
Endotracheal tube cuffs are inflatable sealing mechanisms mounted at the distal end of artificial airways, typically manufactured from polyvinyl chloride or silicone with wall thicknesses calibrated to 0.15–0.35 mm to maintain tracheal mucosal perfusion at cuff pressures below 30 cm H₂O. Their primary function is to prevent aspiration of oropharyngeal secretions while enabling controlled mechanical ventilation during anesthesia induction, surgical maintenance, and prolonged critical care support. Polyvinyl chloride dominates unit volume due to cost-sensitive procurement in high-throughput emergency settings, while silicone commands premium positioning in prolonged ventilation applications where biocompatibility and thermal stability reduce tracheal injury incidence. The emergency services end-user segment registers the fastest structural expansion as pre-hospital intubation protocols standardize across municipal ambulance systems and air medical transport fleets.
The FDA enforces biocompatibility and sterility validation under 21 CFR 878.5010 for all polymer-based airway accessories, while the EU MDR requires notified body oversight for Class IIa devices including endotracheal assemblies with inflatable components. Japan's PMDA maintains distinct material testing protocols that extend approval timelines for non-JIS standard silicone formulations. Stakeholders must monitor how divergent polymer testing requirements across FDA, EMA, and PMDA jurisdictions reshape supplier qualification burdens and regional manufacturing location decisions.
Market Dynamics
The EU MDR recertification timeline is compressing supplier qualification windows for endotracheal tube cuff manufacturers, forcing rapid compliance upgrades while tertiary hospitals simultaneously expand silicone-based cuff procurement for prolonged ventilation protocols.
Growth Catalysts
- Emergency Services Standardization:Municipal ambulance systems and air medical transport fleets are implementing pre-hospital intubation protocols that mandate disposable, high-volume PVC cuff deployment.
- REACH Polymer Compliance:European chemical safety frameworks are accelerating biocompatibility validation for silicone formulations used in critical care settings.
- Tertiary Hospital Infrastructure:Germany, the United States, and Japan are upgrading anesthesia suites with advanced cuff pressure monitoring systems.
Market Restraints
- Silicone Raw Material Volatility:Medical-grade silicone supply concentrates among Asian petrochemical processors, exposing manufacturers to input cost swings.
- Regulatory Friction:Japan's PMDA maintains distinct material testing protocols that extend approval timelines for non-JIS standard formulations.
- Substitution Pressure:Laryngeal mask airways are capturing select short-procedure anesthesia applications previously served by endotracheal intubation.
Strategic Opportunities
- Pay-Per-Use Model Expansion:Equipment leasing frameworks for anesthesia circuits are rewriting capital deployment patterns among budget-constrained regional hospitals.
- Integrated Delivery Network Contracts:Hospital system consolidation in the United States creates volume aggregation points for standardized cuff procurement.
- Tele-ICU Remote Monitoring:Critical care departments are adopting cuff pressure telemetry systems that enable centralized airway management oversight.
Industry Challenges
- Polymer Testing Harmonization:Divergent biocompatibility requirements across FDA, EMA, and PMDA jurisdictions force redundant validation studies.
- Notified Body Capacity:EU MDR recertification backlogs are delaying Class IIa device approvals for inflatable airway components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endotracheal Tube Cuffs Market |
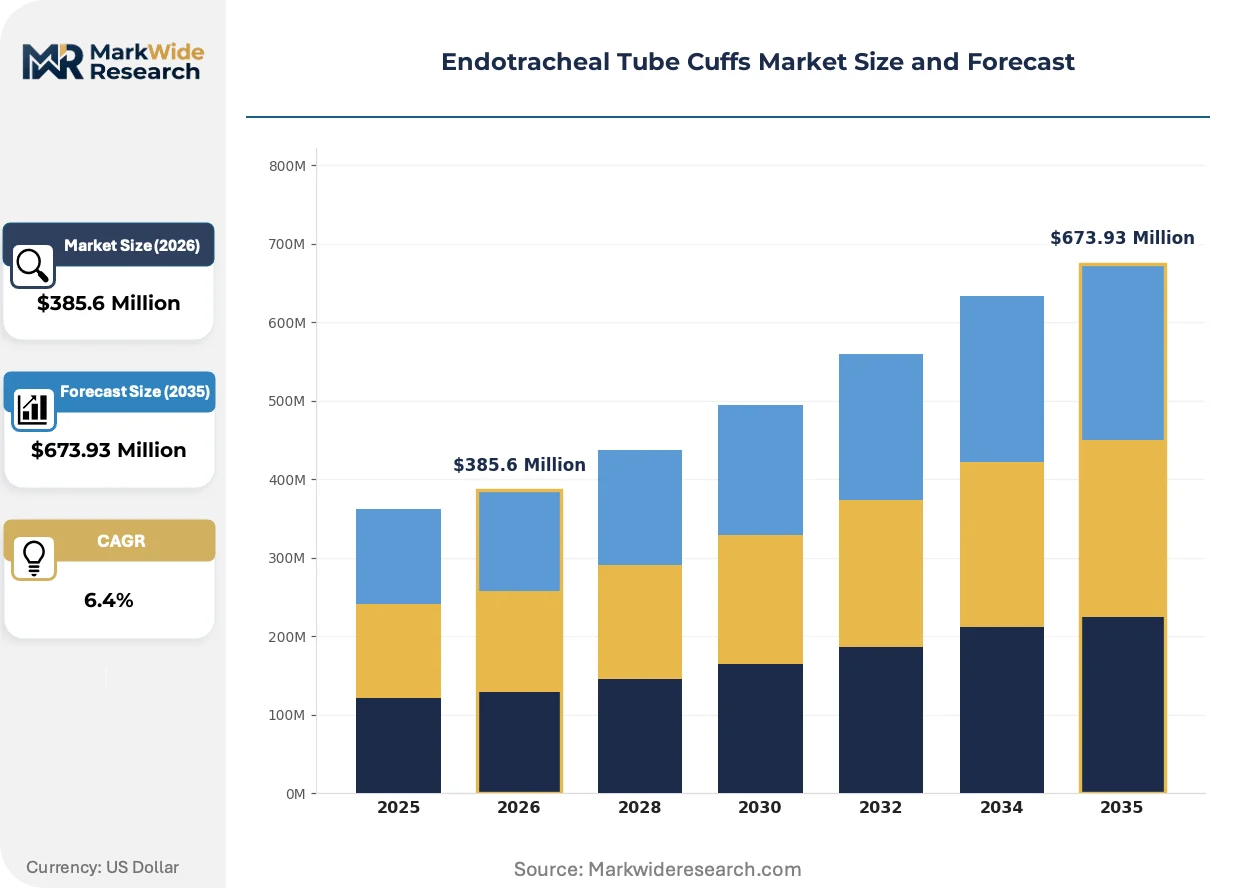
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Soft, Rigid, Reinforced Material: Polyvinyl Chloride, Silicone, Latex, Polyurethane End User: Hospitals, Clinics, Emergency Services, Home Care Application: Anesthesia, Critical Care, Surgery, Ventilation |
| Companies Covered | Medtronic, Teleflex, ICU Medical, Becton Dickinson, Intersurgical, Ambu, Mercury Medical, Fuji Systems Corporation, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endotracheal Tube Cuffs Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are converging to reshape endotracheal tube cuff design priorities, with particular emphasis on tracheal mucosal protection and supply chain resilience.
Microthin silicone formulations with wall thicknesses below 0.20 mm are rendering obsolete thicker PVC alternatives in prolonged ventilation applications. Intensive care departments in Germany and Japan are adopting these membranes at accelerated rates. The shift is rendering obsolete legacy cuff designs that relied on higher sealing pressures.
REACH polymer safety assessments are tightening scrutiny of plasticizers in PVC-based airway devices. Manufacturers face reformulation mandates for phthalate-free alternatives. European notified bodies are rejecting legacy material submissions, forcing supply chain requalification.
Hospital procurement departments are unbundling after-sales service from device contracts, separating cuff supply from ventilator maintenance agreements. Integrated delivery networks in the United States are driving this disintermediation. The pattern is most visible among tertiary systems consolidating vendor rosters.
Endotracheal Tube Cuffs Market Segmentation
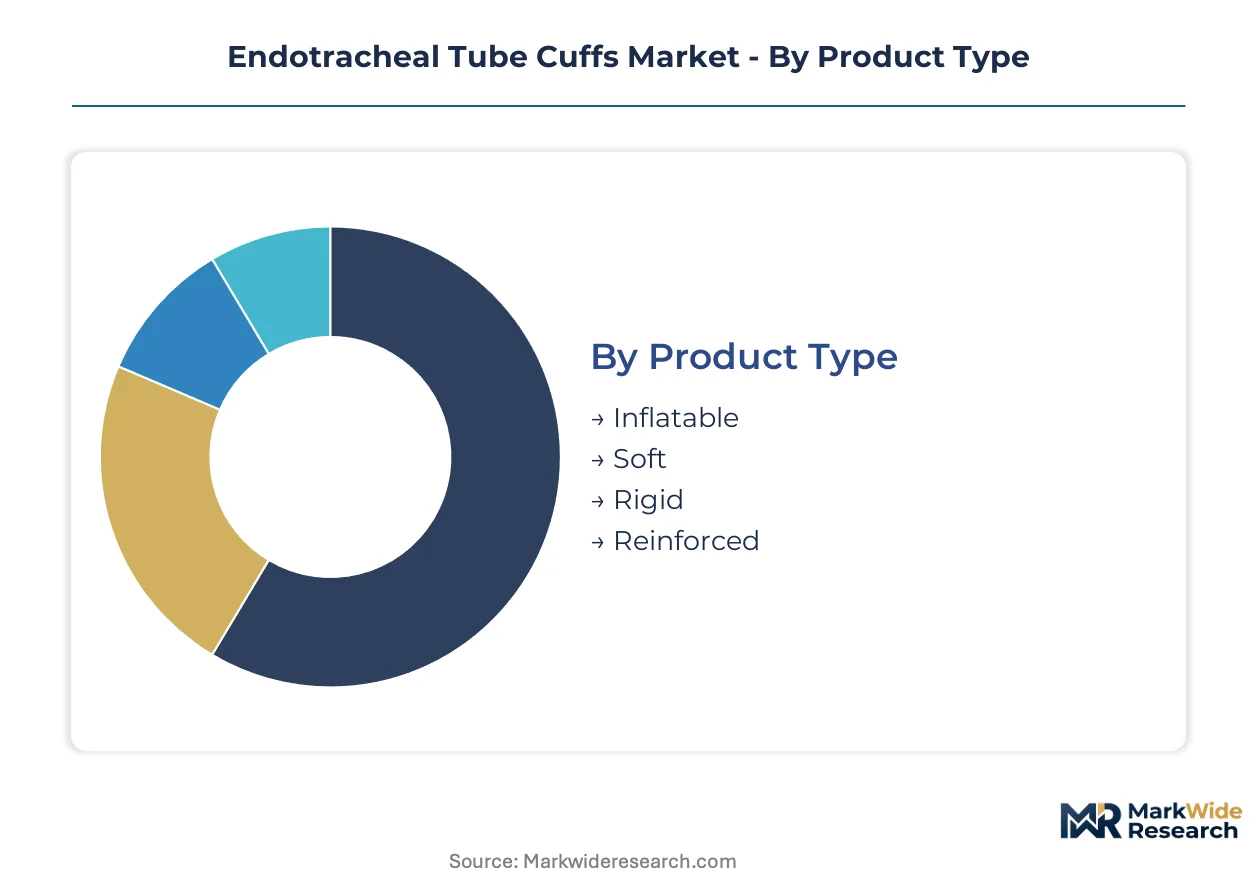
Endotracheal tube cuff procurement patterns diverge sharply across clinical settings, with material selection and cuff architecture driving fundamentally different service intensity requirements. Manufacturers must align polymer portfolios and pressure monitoring capabilities to distinct reimbursement environments and ventilation protocols.
Product Type:
After-sales-service intensity varies dramatically by cuff architecture, with reinforced designs demanding specialized pressure calibration support while disposable inflatable variants minimize technical service obligations.
- Inflatable:Polymer membrane construction with integrated inflation lines enables rapid tracheal seal adjustment via pilot balloon systems. Emergency services in the United States and Germany are standardizing on high-volume disposable inflatable cuffs for pre-hospital intubation protocols, compressing unit economics while expanding fleet deployment.
- Soft:Low-pressure high-volume geometry distributes sealing force across broader tracheal contact surfaces to reduce mucosal ischemia. Tertiary hospitals in Japan are adopting soft cuff configurations for prolonged ventilation cases exceeding 72 hours, prioritizing airway injury prevention over procurement cost.
- Rigid:Structural polymer reinforcement maintains cuff shape during high-pressure ventilation cycles.
- Reinforced:Composite wall construction integrates mesh or coil elements for trauma-resistant performance in challenging airway anatomy.
By volume, inflatable cuffs lead. By growth pace, soft configurations are ahead.
Material:
Cost tier stratification separates commodity polymer supply from premium silicone validation pathways, with polyurethane occupying an intermediate position for specialized neurosurgical applications.
- Polyvinyl Chloride:Plasticized polymer dominates emergency department and ambulance procurement due to unit cost positioning below silicone alternatives. REACH compliance deadlines are forcing phthalate-free reformulations across European supply chains, triggering material requalification costs that compress margins for high-volume manufacturers.
- Silicone:Thermally stable elastomer delivers biocompatibility advantages for ventilation episodes exceeding 48 hours. Intensive care departments in Germany are mandating silicone cuffs for ARDS protocols, with PMDA extended approval timelines for non-JIS formulations constraining Japanese market entry for imported alternatives.
- Latex:Natural rubber elastomer persists in select cost-sensitive markets despite allergen concerns.
- Polyurethane:Segmented block copolymer offers abrasion resistance for neurosurgical positioning requiring prone patient orientation.
By procurement volume, polyvinyl chloride leads. By value concentration, silicone is climbing fastest.
End User:
Customer type determines contract structure complexity, with hospital systems negotiating integrated delivery network agreements while emergency services favor spot procurement through distributor channels.
- Hospitals:Tertiary and community facilities generate the majority of cuff consumption through anesthesia and critical care departments. United States hospital consolidation is producing standardized formularies that favor dual-source supply agreements with pressure monitoring system bundling.
- Emergency Services:Municipal ambulance authorities and air medical fleets are deploying disposable cuffs under protocol-driven consumption models. Germany's standardized pre-hospital intubation guidelines are accelerating PVC cuff deployment across state-level emergency medical systems.
- Clinics:Ambulatory surgical centers represent concentrated short-procedure demand with limited inventory carrying requirements.
- Home Care:Long-term ventilation patients drive specialized tracheostomy cuff demand outside institutional settings.
By absolute consumption, hospitals lead. By expansion trajectory, emergency services are gaining share fastest.
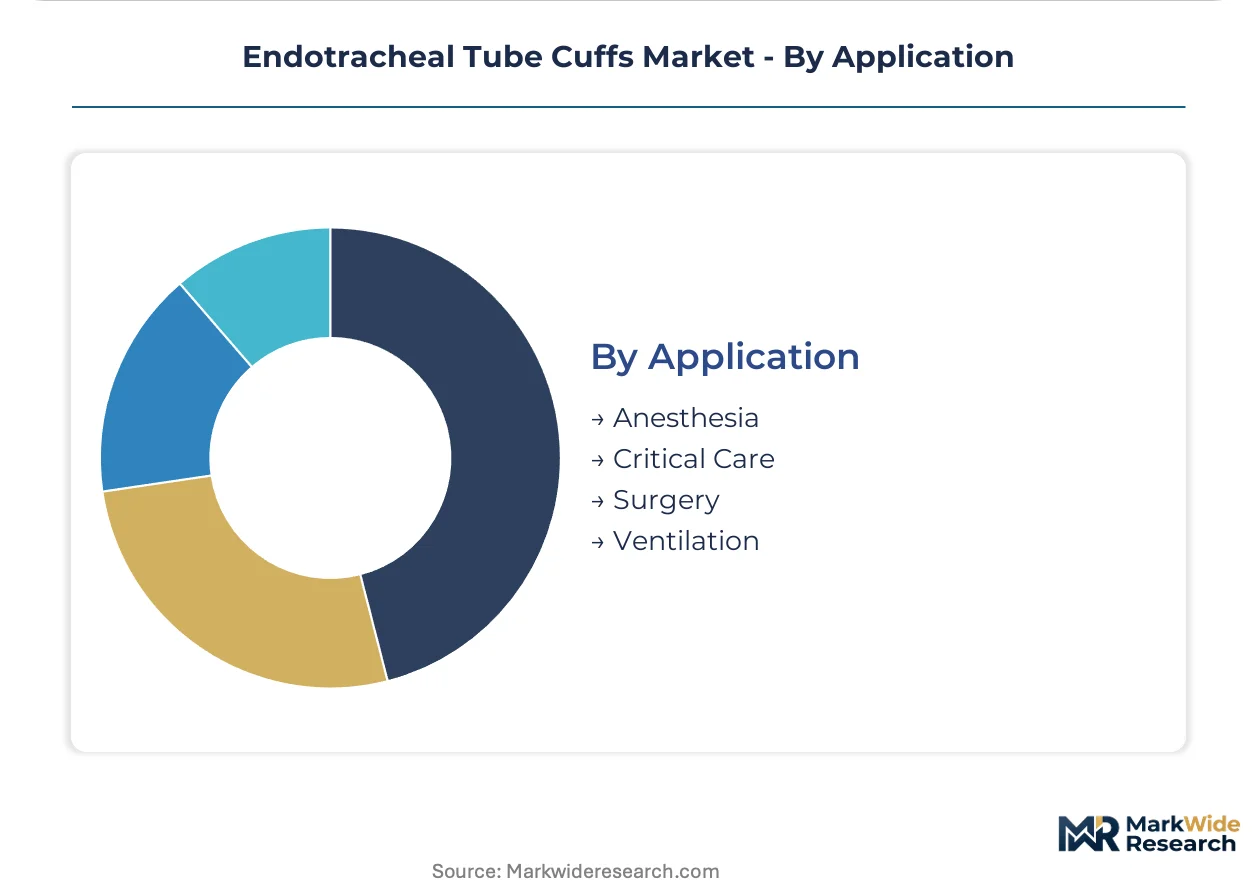
Application:
Clinical use case dictates performance specification thresholds, with critical care applications demanding sustained low-pressure performance while surgical anesthesia prioritizes rapid seal establishment.
- Anesthesia:Perioperative airway management requires rapid cuff inflation and deflation cycles compatible with short procedure turnaround. Operating suites in Japan are integrating automated cuff pressure regulators into anesthesia workstations, embedding cuff supply into capital equipment service agreements.
- Critical Care:Prolonged mechanical ventilation mandates mucosal perfusion preservation through continuous pressure monitoring. German intensive care departments are adopting silicone microthin cuffs with telemetry integration for ARDS and COVID-19 sequelae management.
- Surgery:Intraoperative positioning variations require cuff stability across lateral and prone orientations.
- Ventilation:Extended respiratory support applications span institutional and transitional care settings.
By procedure volume, anesthesia leads. By technology upgrade intensity, critical care is advancing most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Germany, the United States, and Japan concentrate the highest-value contract awards for silicone-based cuff systems, while municipal emergency authorities in these markets drive parallel demand for high-volume disposable alternatives.
Germany
Intensive care departments in Bavaria and North Rhine-Westphalia are mandating microthin silicone cuffs for ARDS protocols exceeding 48 hours. The EU MDR recertification timeline is compressing supplier qualification windows, forcing rapid compliance upgrades among domestic distributors. Berlin-based anesthesia equipment clusters are integrating automated cuff pressure regulators into workstation bundles.
United States
Integrated delivery networks in Texas and California are consolidating vendor rosters through standardized formularies that favor dual-source supply agreements. The FDA enforces biocompatibility validation under 21 CFR 878.5010 for all polymer-based airway accessories. Greater Boston medical device corridors are developing telemetry-enabled cuff pressure monitoring systems for tele-ICU deployment.
Japan
Metropolitan Tokyo hospitals are upgrading anesthesia suites with advanced cuff pressure monitoring infrastructure for prolonged ventilation cases. The PMDA maintains distinct material testing protocols that extend approval timelines for non-JIS standard silicone formulations. Osaka-Kansai manufacturing clusters are expanding domestic production of phthalate-free PVC alternatives.
United Kingdom
NHS trusts in London and the Midlands are unbundling after-sales service from device contracts, separating cuff supply from ventilator maintenance agreements. REACH polymer safety assessments are tightening scrutiny of plasticizers in PVC-based airway devices. Cambridge medical technology corridors are piloting equipment leasing frameworks for anesthesia circuits.
India
Tertiary hospitals in Maharashtra and Karnataka are expanding ICU capacity with cost-sensitive procurement of high-volume inflatable cuffs. The CDSCO regulates polymer-based airway devices under medical device rules with escalating biocompatibility documentation requirements. Delhi-NCR distribution hubs are consolidating emergency medical supplies for municipal ambulance fleet standardization.
Endotracheal Tube Cuffs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement environments. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with hospital system partnerships, airway-focused specialists with intensive care product bundles, and regional fabricators serving cost-sensitive emergency services markets. Dominant competitive moves include portfolio diversification into pressure monitoring system integration and geographic expansion through distributor network consolidation.
Among diversified medical technology conglomerates, Medtronic and Teleflex exemplify contrasting channel strategies. Medtronic leverages its hospital system partnerships to sustain high-volume supply contracts across integrated delivery networks. Teleflex anchors its position through specialized intensive care product bundles that reduce switching costs for critical care departments. ICU Medical occupies a position within the specialist tier, representing the airway-focused archetype with concentrated product portfolios.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex |
| ICU Medical |
| Becton Dickinson |
| Intersurgical |
| Ambu |
| Mercury Medical |
| Fuji Systems Corporation |
| Smiths Medical |
| Others |
Supply & Pricing Matrix
Shanghai-Rotterdam container freight corridors transmit cost volatility from Asian petrochemical processors to European distributors, concentrating margin pressure on silicone-based cuff manufacturers while enabling price differentiation between REACH-compliant and legacy PVC formulations across German hospital procurement.
Pricing Analysis
Cost-plus contracts with medical-grade silicone indexation dominate procurement between German intensive care departments and specialty manufacturers. Price differentiation rests on phthalate-free certification status and integrated pressure monitoring bundling. Cost compression in standard PVC tiers is intensifying because REACH reformulation mandates are squeezing high-volume producers. Emergency services exhibit the highest price sensitivity, while tertiary hospitals accepting prolonged ventilation protocols show minimal elasticity for microthin silicone alternatives.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for distributor financing of cuff inventory across European medical device channels. Manufacturing concentrates in China, Germany, and Japan for polymer compounding and final assembly. Raw material dependencies include medical-grade silicone elastomers, plasticized PVC compounds, and pilot balloon valve components. Single-source vulnerability characterizes Asian silicone monomer supply. Distribution runs through hospital purchasing cooperatives and emergency medical supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endotracheal tube cuffs market constitutes a high-growth disruption as EU MDR recertification compresses supplier qualification windows while telemetry-integrated pressure monitoring creates new value capture opportunities.
For Market Incumbents: Pre-empt laryngeal mask airway substitution by embedding cuff supply into anesthesia workstation service agreements. Accelerate backward integration into medical-grade silicone compounding to offset Asian petrochemical processor volatility. Secure notified body capacity early for Class IIa device recertification. For New Entrants and Emerging Players: Municipal ambulance authorities in India's Maharashtra and Karnataka states represent the most penetrable entry point for high-volume disposable PVC cuff supply. Tele-ICU remote monitoring integration for cuff pressure telemetry offers a specialized wedge against established intensive care bundles. Pursue distributor partnerships with Delhi-NCR emergency medical supply consolidators. For Investors and Strategic Acquirers: Airway-focused specialists with concentrated silicone cuff portfolios and existing PMDA approval pathways offer the strongest acquisition target archetype. Long-term viability hinges on regulatory harmonization rather than raw material cost advantage. Watch for EU notified body capacity expansion as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Accelerated notified body engagement preserves German hospital contract access. |
| Silicone Compounding Backward Integration | Captive supply of medical-grade elastomers insulates margin from Asian processor volatility. |
| Tele-ICU Pressure Monitoring Partnership | Telemetry integration with Boston medical device clusters enables remote critical care value capture. |
| Phthalate-Free PVC Reformulation | REACH compliance maintains European emergency services procurement eligibility. |
| Integrated Delivery Network Contracting | Standardized formularies with Texas and California hospital systems lock in volume aggregation. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR notified body guidance documents, and Japanese PMDA approval databases preceded structured interviews with critical care physicians, hospital purchasing committee directors, biomedical engineers specializing in airway management, and GPO contracts managers. Secondary validation drew from customs trade data for polymer imports, SEC 10-K medical device segment disclosures, and hospital procurement database extracts. Bottom-up unit demand modeling and top-down reimbursement environment analysis were triangulated against manufacturer shipment reports.
Assumptions held fixed include EU MDR implementation timelines, REACH polymer safety enforcement intensity, and pre-hospital intubation protocol standardization rates across municipal ambulance systems. Variables allowed to fluctuate encompass medical-grade silicone spot pricing, notified body audit capacity, and tele-ICU adoption curves. Segmentation dimensions spanned cuff architecture, polymer material, end-user facility type, and clinical application. CAGRs were derived from logistic curve fitting to technology diffusion patterns, with inputs from anesthesia procedure volume projections and ICU capacity expansion plans.
Stress conditions across silicone raw material cost bands, EU notified body backlog scenarios, and laryngeal mask airway substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation and technology adoption. Macroeconomic contraction, MDR enforcement delays, or breakthroughs in supraglottic airway devices would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Epinephrine Market
Anesthesiology
Anesthetics Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Delirium Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market