
 Global Neonatal Thermoregulation Market | 2026-2036
Global Neonatal Thermoregulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neonatal Thermoregulation Market Foresight
The EU Medical Device Regulation is recalibrating the cost-of-entry calculus for neonatal thermoregulation equipment across European markets. GE HealthCare leverages its regulatory affairs infrastructure to sustain CE-marked product pipelines with minimal redesign cycles. Drägerwerk AG & Co. KGaA anchors its competitive stance through vertically integrated manufacturing of servo-controlled heating platforms. Philips competes by extending its digital-therapeutic ecosystem into NICU workflow integration, reducing standalone device commoditization risk.
Neonatal thermoregulation encompasses active and passive systems that maintain core body temperature between 36.5°C and 37.5°C in preterm and low-birth-weight infants through radiant heat transfer, convective warming, or conductive mattress surfaces. These devices prevent cold stress, reduce metabolic oxygen consumption, and stabilize cardiorespiratory function during the critical first hours of extrauterine life. Incubators dominate the product type landscape due to their enclosed microenvironment control, while radiant warmers represent the fastest-expanding segment driven by surgical access requirements and resuscitation protocols. NICUs anchor end-user demand with the highest acuity caseloads, though birth centers are emerging as a volume growth pocket as low-risk delivery settings adopt basic thermal monitoring capabilities.
The FDA's premarket notification pathway for neonatal warmers and the EU MDR's clinical evaluation requirements shape product development timelines and market access costs for manufacturers targeting Western markets. Japan's PMDA enforces JIS-standard electromagnetic compatibility testing that adds a distinct compliance layer for Asia-Pacific entry. India's CDSCO and BIS certification processes for imported medical devices create additional gatekeeping that local assemblers such as Phoenix Medical Systems navigate with greater agility than multinational entrants. Stakeholders must weigh regulatory capital intensity against the volume opportunity in government-procurement-driven markets where tender specifications increasingly mandate servo-controlled feedback mechanisms and integrated thermal monitoring documentation.
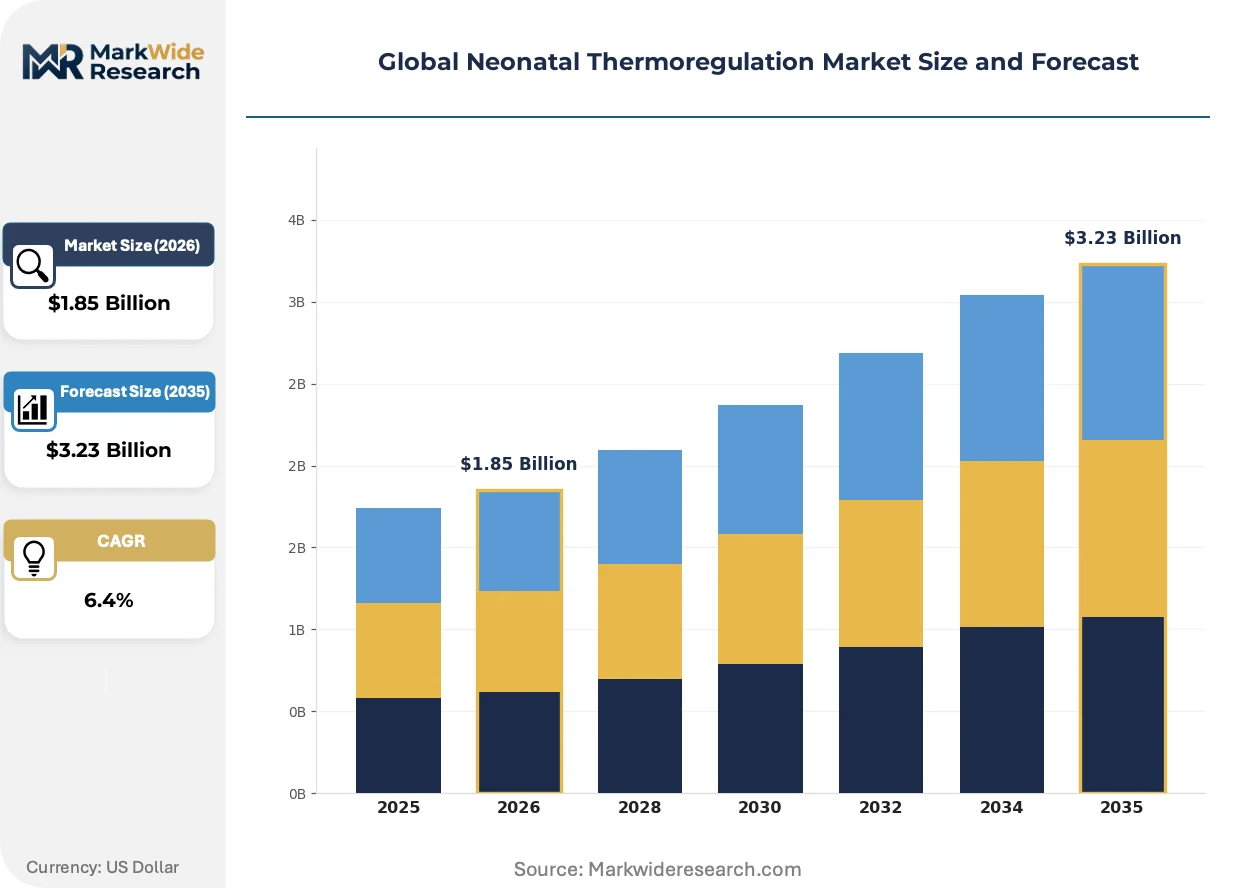
Market Dynamics
Servo-controlled feedback mechanisms are redefining competitive differentiation as government tenders increasingly mandate real-time thermal monitoring documentation alongside device procurement.
Growth Catalysts
- India's SNCU Expansion:Government-funded Special Newborn Care Units are scaling across secondary hospitals, creating sustained demand for radiant warmers and incubators with integrated monitoring.
- EU MDR Compliance Thresholds:Tightened clinical evidence requirements for thermal monitoring devices are filtering out marginal competitors and consolidating procurement toward certified suppliers.
- Preterm Birth Incidence:Rising rates of low-birth-weight deliveries in developing economies are expanding the addressable patient population requiring active thermoregulation support.
Market Restraints
- Electronics Supply Concentration:Servo-control sensors and microprocessors concentrate in East Asian foundries, exposing manufacturers to single-source vulnerability.
- MDR Transition Costs:European clinical evaluation requirements for legacy device recertification are absorbing R&D capital that would otherwise flow to feature innovation.
- Passive Thermal Care Substitution:Kangaroo mother care and plastic wrap interventions in resource-limited settings displace device-based warming for stable neonates.
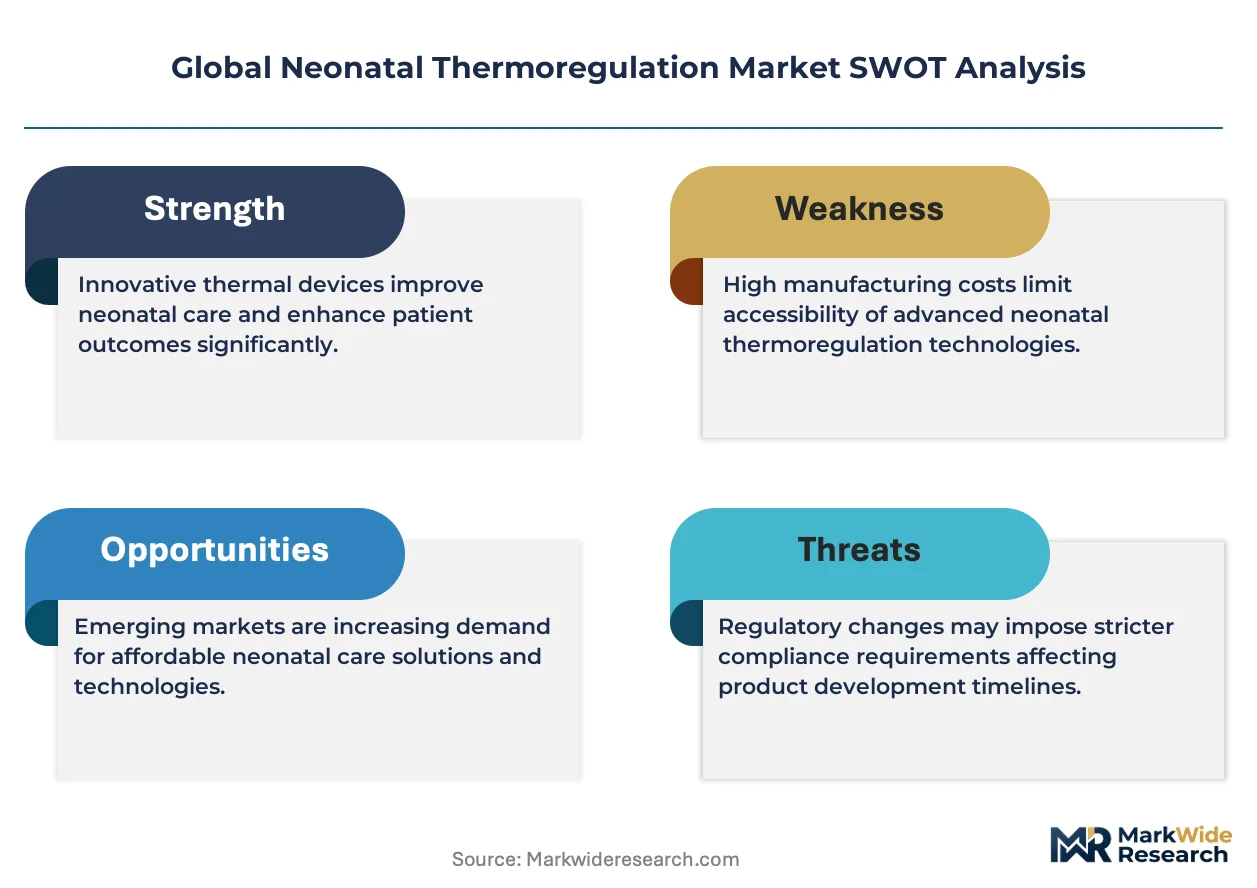
Strategic Opportunities
- Birth Center Channel Development:Low-risk delivery settings in the United States and Western Europe are adopting basic thermal monitoring capabilities, creating a volume tier below NICU equipment.
- Digital-Therapeutic Convergence:Integration of warming platforms with electronic health record systems and predictive analytics opens recurring revenue streams beyond hardware sales.
- Japan's PMDA Pathway:JIS-standard electromagnetic compatibility certification, while rigorous, creates defensible positioning for compliant entrants in a high-value, consolidated market.
Industry Challenges
- Biomedical Engineering Talent Scarcity:NICU equipment manufacturers face acute shortages of specialists capable of bridging thermal physics, embedded systems, and clinical workflow design.
- Legacy System Integration Friction:New servo-controlled warmers must interface with heterogeneous hospital IT infrastructures, extending deployment timelines and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neonatal Thermoregulation Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiant Warmers, Incubators, Heated Mattresses, Servo-Controlled Warmers, Resuscitation Warmers Application: Temperature Management, Hypothermia Prevention, Thermal Monitoring, Neonatal Intensive Care, Postnatal Care End User: NICUs, Pediatric Clinics, Specialty Care Centers, Maternity Wards, Birth Centers Deployment Mode: Hospital-Based, Mobile Unit, Home Healthcare, Telemedicine, Ambulatory Care |
| Companies Covered | GE HealthCare, Drägerwerk AG & Co. KGaA, Natus Medical Incorporated, Atom Medical Corporation, Philips, Fisher & Paykel Healthcare, Phoenix Medical Systems, Medtronic, Inspiration Healthcare Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neonatal Thermoregulation Market Shifts & Advancements
Real-time data integration and predictive thermal modeling are compressing the gap between device functionality and clinical decision support, reshaping how warming platforms deliver value beyond basic temperature maintenance.
Closed-loop servo-control with machine-learned thermal response curves is overtaking fixed-threshold heating algorithms in premium incubator segments. Level III NICUs in Germany and the United States are adopting these systems to reduce nursing intervention frequency. The technology is compressing differentiation timelines as algorithm performance becomes a primary procurement criterion alongside hardware specifications.
Japan's PMDA has tightened electromagnetic compatibility testing protocols for neonatal warming devices under revised JIS standards. Manufacturers must now demonstrate immunity to surgical equipment interference before market authorization. Pediatric surgical centers represent the most affected segment, driving demand for shielded radiant warmer architectures.
Hospital purchasing consortiums are consolidating thermal equipment procurement into multi-year managed service agreements that bundle devices, disposables, and maintenance. Independent distributors in India and Brazil are losing access to large accounts as direct manufacturer relationships deepen. This pattern is most pronounced in India's government hospital networks, where centralized tendering favors vendors with national service infrastructure.
Global Neonatal Thermoregulation Market Segmentation
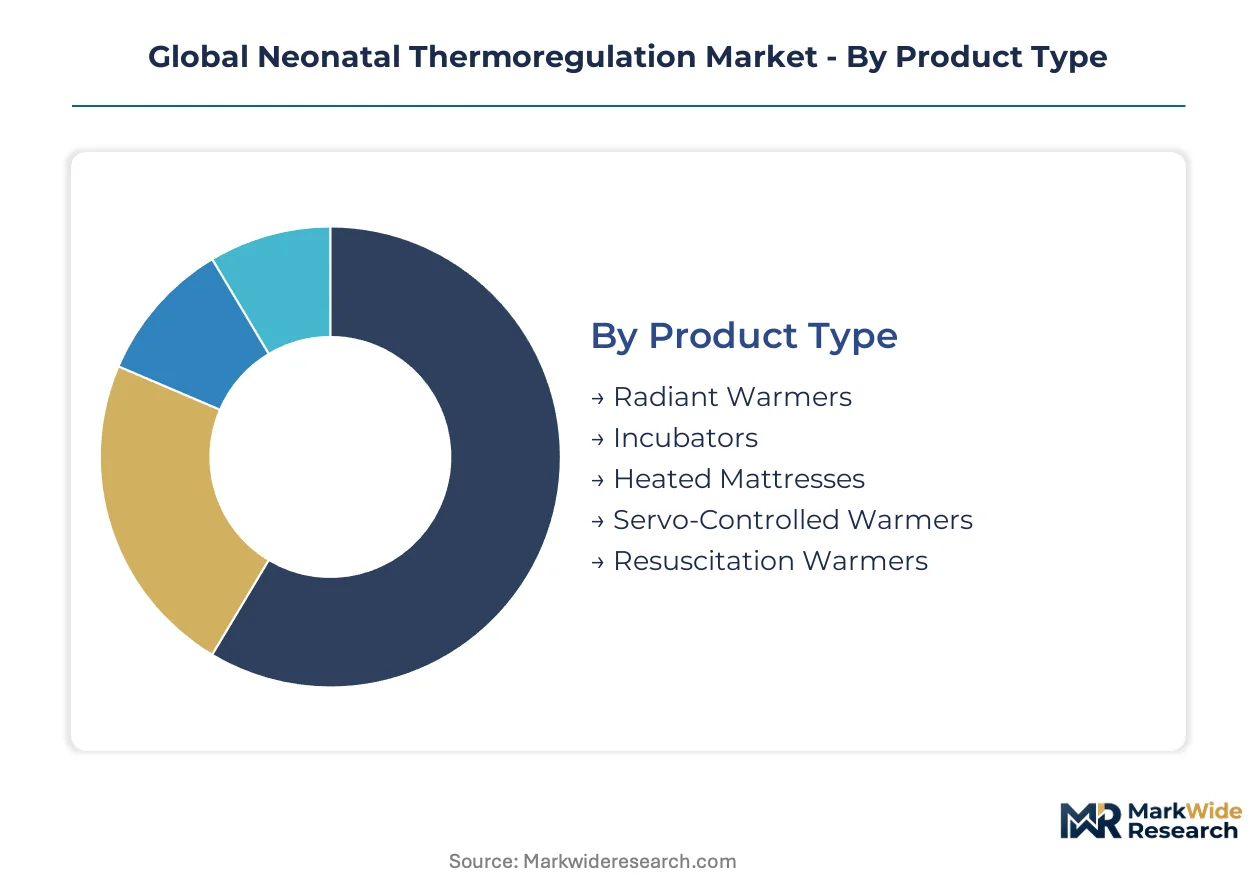
Neonatal thermoregulation equipment fragments across multiple functional dimensions, each commanding distinct procurement logic and margin profiles. Understanding these splits reveals where servo-control premiums concentrate versus where basic thermal monitoring suffices.
Product Type:
Volume concentrates in enclosed microenvironment systems, while premium pricing attaches to real-time feedback architectures.
- Incubators:Enclosed housing with humidity and oxygen control dominates installed base across Level III NICUs in Germany and the United States. Demand concentrates where prolonged thermal stability is required for extremely low-birth-weight infants, with procurement favoring servo-integrated models that reduce nursing intervention frequency.
- Radiant Warmers:Overhead heating platforms with unobstructed surgical access are gaining share fastest in India's government-funded SNCU expansion, where resuscitation protocols and procedure-ready positioning outweigh enclosed-environment benefits. Tenders increasingly mandate integrated thermal monitoring documentation alongside device procurement.
- Servo-Controlled Warmers:Closed-loop feedback systems with machine-learned thermal response curves command premium positioning in tertiary facilities.
- Heated Mattresses:Conductive warming surfaces serve transport and secondary care settings with lower acuity requirements.
- Resuscitation Warmers:Rapid-deployment radiant units designed for delivery room stabilization protocols.
Today's leader: Incubators. Tomorrow's challenger: Radiant Warmers.
Application:
Clinical use cases stratify by acuity intensity and reimbursement attachment.
- Neonatal Intensive Care:Continuous thermal management for preterm and critically ill newborns anchors premium equipment demand. Level III NICUs in Japan and the United States specify electromagnetic compatibility certification under revised JIS standards, filtering procurement toward shielded architectures that withstand surgical equipment interference.
- Temperature Management:Core body stabilization between 36.5°C and 37.5°C represents the foundational therapeutic objective across all device categories. Government hospital networks in India centralize tendering for this capability, favoring vendors with national service infrastructure over independent distributors.
- Hypothermia Prevention:Cold stress mitigation in the first hours of extrauterine life drives immediate post-delivery deployment.
- Thermal Monitoring:Real-time data integration with electronic health record systems opens recurring revenue streams.
- Postnatal Care:Stabilization support following initial NICU discharge or for moderate-risk deliveries.
Neonatal Intensive Care captures current margin concentration; Temperature Management is expanding fastest as basic monitoring penetrates lower-acuity settings.
End User:
Facility type determines specification intensity and contract structure.
- NICUs:Highest-acuity caseloads command fully featured servo-controlled platforms with predictive thermal modeling. Hospital purchasing consortiums are consolidating procurement into multi-year managed service agreements that bundle devices, disposables, and maintenance, deepening direct manufacturer relationships.
- Birth Centers:Low-risk delivery settings in the United States and Western Europe are adopting basic thermal monitoring capabilities, creating a volume tier below NICU equipment specifications. This segment offers channel development opportunity as standards for neonatal readiness rise in out-of-hospital birth settings.
- Pediatric Clinics:Follow-up thermal assessment for discharged neonates with ongoing risk factors.
- Specialty Care Centers:Focused facilities for cardiac, surgical, or metabolic neonatal conditions.
- Maternity Wards:General delivery units requiring immediate newborn stabilization capability.
NICUs anchor premium demand; Birth Centers represent the steepest expansion trajectory as monitoring standards extend to low-risk settings.
Deployment Mode:
Physical placement of thermoregulation capability follows care decentralization trends.
- Hospital-Based:Fixed installation within NICU, delivery suite, or maternity ward infrastructure constitutes the dominant deployment pattern. Legacy system integration friction extends deployment timelines as new servo-controlled warmers must interface with heterogeneous hospital IT infrastructures.
- Mobile Unit:Transport incubators and warming platforms serve inter-facility transfers and emergency response. India's rural health mission deploys these units to extend Special Newborn Care Unit reach into district hospital networks.
- Home Healthcare:Portable warming solutions for high-risk infants discharged early or in hospice contexts.
- Telemedicine:Remote thermal monitoring integration with centralized clinical decision support.
- Ambulatory Care:Same-day thermal assessment in non-admitted settings.
Hospital-Based deployment retains volume dominance; Mobile Unit configurations are climbing fastest as health systems pursue geographic coverage extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Germany, Japan, and the United States anchor premium equipment development, while India's manufacturing workforce scales cost-efficient production for government procurement programs.
United States
Level III NICUs in academic medical centers specify FDA-cleared servo-controlled platforms with predictive thermal modeling capabilities. The FDA's premarket notification pathway shapes product development timelines for manufacturers targeting hospital purchasing consortiums. Boston and Minneapolis medical device clusters concentrate engineering resources for closed-loop algorithm development.
Germany
Tertiary neonatal centers demand electromagnetic compatibility certification under EU MDR clinical evaluation requirements. The EU Medical Device Regulation filters procurement toward established CE-marked suppliers with robust technical documentation. Baden-Württemberg's precision manufacturing corridor supplies servo-control sensor assemblies to regional equipment fabricators.
Japan
Pediatric surgical centers require JIS-standard electromagnetic immunity testing for radiant warmer architectures. PMDA's tightened protocols under revised JIS standards create defensible positioning for compliant entrants in this consolidated high-value market. Tokyo and Osaka metropolitan areas concentrate demand from university-affiliated perinatal centers.
India
Government-funded Special Newborn Care Units are scaling across secondary hospitals in Maharashtra and Karnataka, creating sustained demand for radiant warmers with integrated thermal monitoring. CDSCO and BIS certification processes for imported devices favor local assemblers with greater regulatory agility. Tamil Nadu's medical device manufacturing zone near Chennai supplies cost-optimized warming platforms for national health mission tenders.
Brazil
Public hospital networks in São Paulo and Minas Gerais are consolidating thermal equipment procurement through centralized purchasing programs. ANVISA's medical device registration requirements extend market access timelines for international manufacturers. Southeast industrial corridors near Campinas host regional distribution hubs serving Latin American markets.
Global Neonatal Thermoregulation Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with regulatory affairs infrastructure capable of sustaining multi-jurisdiction compliance. Market concentration remains moderate, with premium-tier positioning defined by servo-control algorithm performance and integrated monitoring documentation capabilities. Two strategic archetypes dominate: vertically integrated manufacturers of heating platforms, and digital-therapeutic ecosystem builders reducing standalone device commoditization risk. Competitive moves center on multi-year managed service agreements bundling devices with disposables and maintenance, plus backward integration into sensor and microprocessor supply chains.
Within the diversified conglomerate tier, GE HealthCare and Philips occupy positions spanning regulatory infrastructure and digital workflow integration. Drägerwerk AG & Co. KGaA exemplifies the vertically integrated archetype through captive manufacturing of servo-controlled heating architectures. Among Asia-Pacific specialists, Atom Medical Corporation and Phoenix Medical Systems represent contrasting approaches to regional certification agility versus multinational scale.
| Leading Market Players |
|---|
| GE HealthCare |
| Drägerwerk AG & Co. KGaA |
| Natus Medical Incorporated |
| Atom Medical Corporation |
| Philips |
| Fisher & Paykel Healthcare |
| Phoenix Medical Systems |
| Medtronic |
| Inspiration Healthcare Group plc |
| Others |
Supply & Pricing Matrix
Government tenders in India mandating servo-controlled feedback mechanisms with integrated thermal monitoring documentation are forcing manufacturers to absorb sensor and microprocessor costs into bundled service contracts, compressing hardware margins while elevating recurring revenue streams.
Pricing Analysis
Bundled managed service agreements are displacing standalone device transactions as hospital purchasing consortiums consolidate procurement. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked servo-controlled platforms with predictive algorithms from basic radiant warmers and heated mattresses. Price differentiation hinges on FDA clearance tier and national service infrastructure scale. Pricing pressure stems from India's centralized government tendering favoring cost-optimized warming platforms. Birth centers exhibit highest price sensitivity; Level III NICUs in Japan and Germany demonstrate lowest.
Supply Chain Analysis
Servo-control sensors and microprocessor assemblies rest on Taiwanese foundries, Japanese precision component fabricators, and German sensor specialists. Raw material dependencies span platinum resistance temperature detectors, embedded heating elements, and electromagnetic shielding alloys. Single-source vulnerability in East Asian semiconductor fabrication exposes manufacturers to allocation constraints. Distribution runs through direct manufacturer relationships with hospital purchasing consortiums, bypassing independent distributors in government hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement shifts toward servo-controlled platforms with machine-learned thermal response curves and integrated EHR documentation capabilities.
For Market Incumbents: Hedge against standalone device commoditization by deepening backward integration into sensor and microprocessor supply chains. Capture recurring revenue through multi-year managed service agreements bundling devices, disposables, and predictive analytics software. Counter emerging local assemblers in India by accelerating CE marking pathways under EU MDR clinical evaluation requirements.
For New Entrants and Emerging Players: Capture white-space opportunity in United States birth centers adopting basic thermal monitoring capabilities. Target India's government-funded SNCU expansion with cost-optimized radiant warmers featuring integrated documentation. Penetrate through channel partnerships with independent distributors losing access to large accounts as direct manufacturer relationships deepen.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated heating platform specialists with captive sensor manufacturing and established regulatory affairs infrastructure across FDA, CE marking, and PMDA jurisdictions. Five-to-ten year viability favors manufacturers bridging thermal physics expertise with embedded systems and clinical workflow design. Watch India's CDSCO certification agility and EU MDR recertification timelines as inflection indicators for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Control Algorithm Development | Machine-learned thermal response curves differentiate premium positioning in German and United States Level III NICUs. |
| CE Marking Pathway Investment | EU MDR clinical evaluation requirements filter procurement toward established suppliers with robust technical documentation. |
| Hospital System Partnership | Multi-year managed service agreements with purchasing consortiums displace transactional device sales. |
| Backward Integration into Sensors | Captive supply of servo-control components mitigates East Asian foundry concentration risk. |
| Software Companion Development | EHR integration and predictive analytics open recurring revenue streams beyond hardware commoditization. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and Brazil, with primary inputs from each market combining structured interviews with neonatologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, CDSCO registration records, PMDA approval summaries, and hospital procurement tender databases. Bottom-up and top-down triangulation cross-validates unit shipment estimates against reported manufacturer revenues and government health mission budget allocations.
Granularity-level modeling disaggregates volume and value across product type, application, end user, and deployment mode dimensions, with additional segmentation by regulatory certification tier and national service infrastructure scale. CAGRs derive from regression analysis of historical installed base expansion against preterm birth incidence trajectories and government health expenditure commitments. Forecast inputs incorporate EU MDR transition timelines, India's SNCU expansion targets, and JIS-standard electromagnetic compatibility certification requirements.
Regulatory approval delays, semiconductor supply allocation disruptions, and government procurement budget revisions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about tender specification evolution and sensor cost trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Infant Resuscitators Market
Neonatal Care
Neonatal Infant Care Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Dialysis Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Umbilical Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market