
 Umbilical Market | 2026-2036
Umbilical Market Size, Share, and Industry Trends Forecast 2026-2036
Umbilical Market Analysis
Software-defined monitoring and predictive maintenance services bundled with umbilical supply contracts is repositioning vendor-customer relationships toward lifecycle partnerships. Nexans leverages integrated cable and umbilical manufacturing to sustain project delivery timelines. Aker Solutions anchors its position through proprietary connection systems for harsh environments. TechnipFMC competes across integrated subsea production packages where umbilicals form critical links.
An umbilical is an integrated assembly of hydraulic lines, electrical conductors, fiber-optic cables, and sometimes steel tubes encased in polymer sheathing, designed to transmit power, signals, and fluids between subsea installations and surface facilities. Steel-reinforced thermoplastic constructions dominate deepwater applications where collapse resistance and fatigue life determine operational limits. Multifunctional umbilicals capture expanding share as operators consolidate multiple service lines into single cross-section designs to reduce installation complexity. Offshore oil and gas applications retain the largest value pool, though renewable energy—particularly floating offshore wind—represents the fastest-growing demand segment.
API 17E and ISO 13628-5 standards govern umbilical design verification and manufacturing quality for subsea service. Brazil's ANP and Norway's Petroleum Safety Authority enforce supplementary national qualification protocols that shape procurement specifications. The EU's F-Gas Regulation and REACH chemical restrictions are influencing polymer compound selection and supplier qualification pathways. Stakeholders must monitor how evolving offshore wind certification requirements from DNV and emerging carbon-intensity disclosure rules reshape material sourcing and manufacturing location decisions.
Market Dynamics
Deepwater field tiebacks in Brazil's pre-salt basin are compressing umbilical procurement cycles, forcing manufacturers to pre-qualify steel-reinforced thermoplastic constructions for faster deployment. API 17E and ISO 13628-5 qualification timelines now determine contract awards before final investment decisions.
Growth Catalysts
- Brazil ANP qualification protocols:Pre-salt basin operators mandate domestic content ratios that localize umbilical manufacturing capacity.
- Floating offshore wind:Turbine developers bundle dynamic power cables with control umbilicals for simplified mooring systems.
- Steel tube integration:Multifunctional designs consolidate chemical injection, hydraulic power, and fiber-optic monitoring into single cross-sections.
Market Restraints
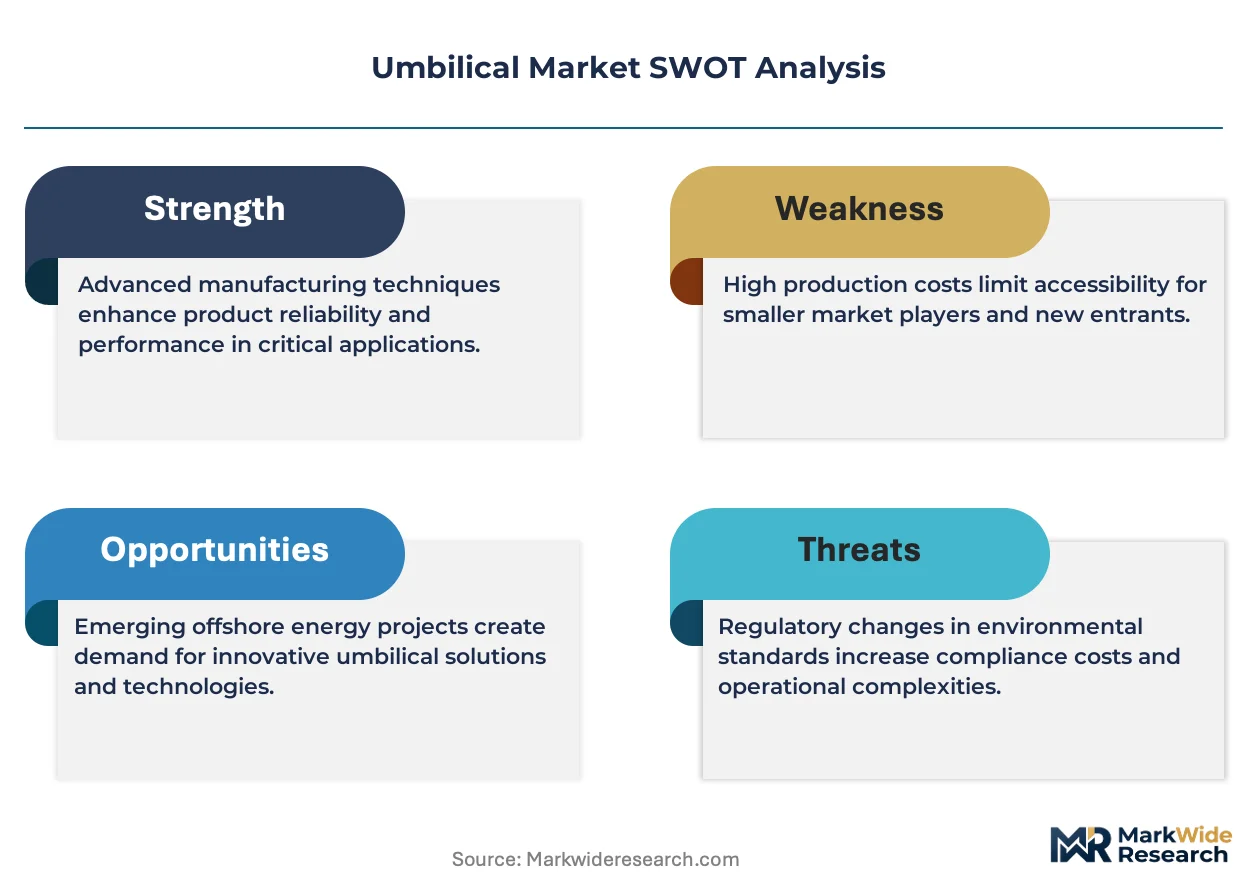
- High-performance polymer feedstock concentration:Specialty thermoplastic elastomer supply concentrates among European compounders, creating input cost volatility.
- Collapse resistance testing:Deepwater hydrostatic pressure requirements extend qualification timelines by 18-24 months for unproven constructions.
- Steel-reinforced flexible pipe substitution:Riser-integrated flowline solutions displace separate umbilical deployments in certain tieback architectures.
Strategic Opportunities
- Norway Petroleum Safety Authority inspection regimes:Mandatory integrity monitoring creates aftermarket service contracts for installed umbilical bases.
- F-Gas Regulation phase-down:EU restrictions on fluorinated polymers accelerate bio-based sheath compound development.
- Integrated S-lay vessel contracting:Installation contractors bundle umbilical lay with subsea infrastructure, compressing procurement channels.
Industry Challenges
- Subsea connection system certification:Proprietary termination designs require vessel-specific compatibility testing that fragments fleet deployment flexibility.
- Fatigue life prediction modeling:Insufficient field data on polymer creep in high-pressure/high-temperature wells forces conservative design margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Umbilical Market |
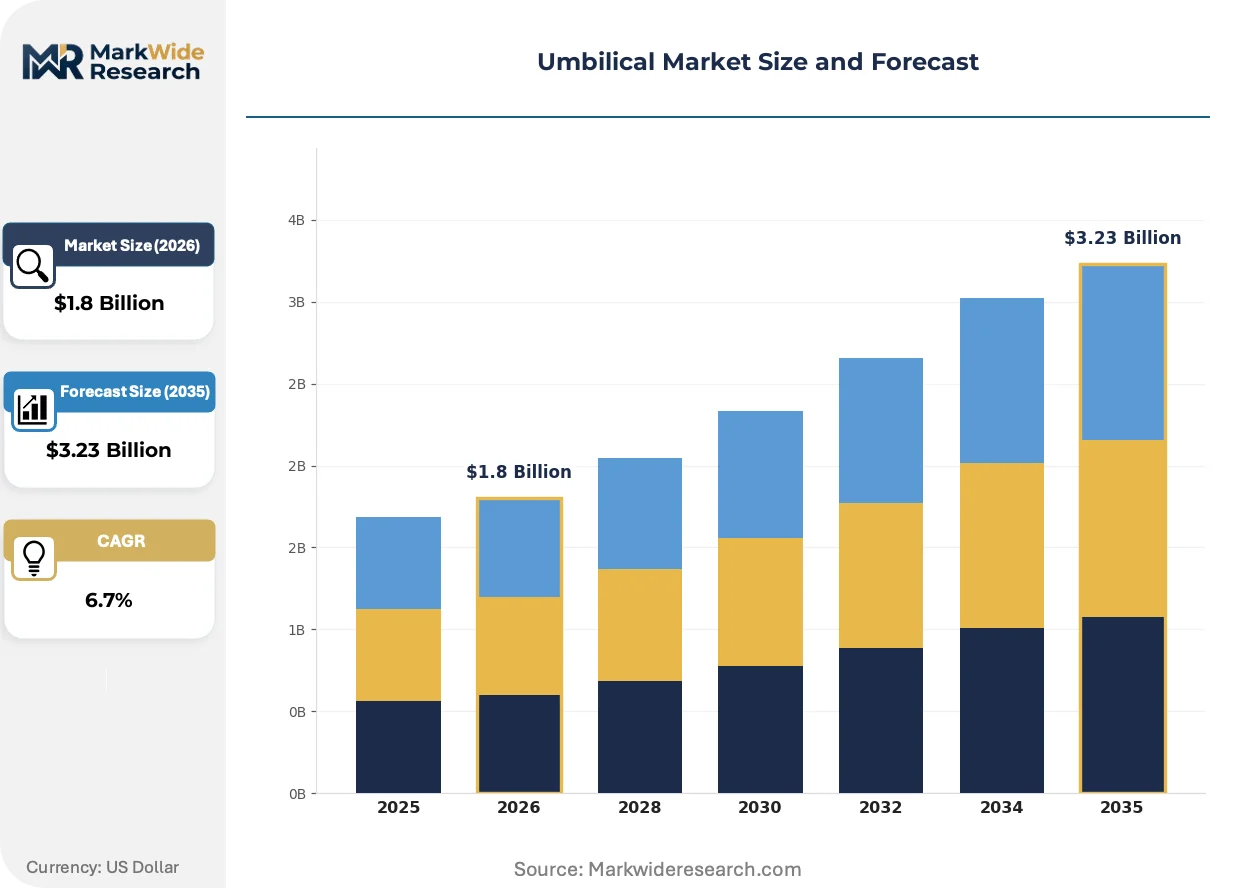
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Umbilical, Double Umbilical, Multifunctional Umbilical, Specialty Umbilical Application: Offshore Oil & Gas, Marine, Industrial, Renewable Energy Installation Type: Onshore, Offshore, Subsea, Surface Material: Rubber, Thermoplastic, Steel, Composite |
| Companies Covered | Nexans, Subsea 7, Aker Solutions, Vallourec, JDR Cable Systems, TechnipFMC, Oceaneering International, Halliburton, Prysmian Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Umbilical Market Emerging Trajectories
Steel-reinforced thermoplastic umbilical construction is fragmenting into component-substitution pathways as operators demand field-replaceable elements. Manufacturing processes are compressing around continuous extrusion rather than batch-built assemblies.
Dynamic power cable technology is modularizing around floating offshore wind mooring integration. Developers in the Celtic Sea and Pacific Northwest are specifying plug-and-play electrical interfaces that separate generator connection from structural load paths. This architecture is modularizing installation sequencing, allowing turbine commissioning before final umbilical termination.
EU F-Gas Regulation restrictions on perfluorinated compounds are forcing polymer compound reformulation across sheath and insulation layers. Compounders are accelerating bio-based thermoplastic elastomer qualification to maintain CE marking compliance. Offshore wind certification bodies DNV and Bureau Veritas are expanding test protocols to cover these alternative materials in dynamic bending applications.
Lifecycle service contracting is displacing discrete equipment procurement in deepwater oil and gas. Brazilian operators now specify predictive maintenance algorithms as contract deliverables alongside physical umbilical supply. Norwegian field developments are bundling integrity monitoring subscriptions with initial capital equipment, shifting vendor relationships toward performance-guarantee structures.
Umbilical Market Segmentation
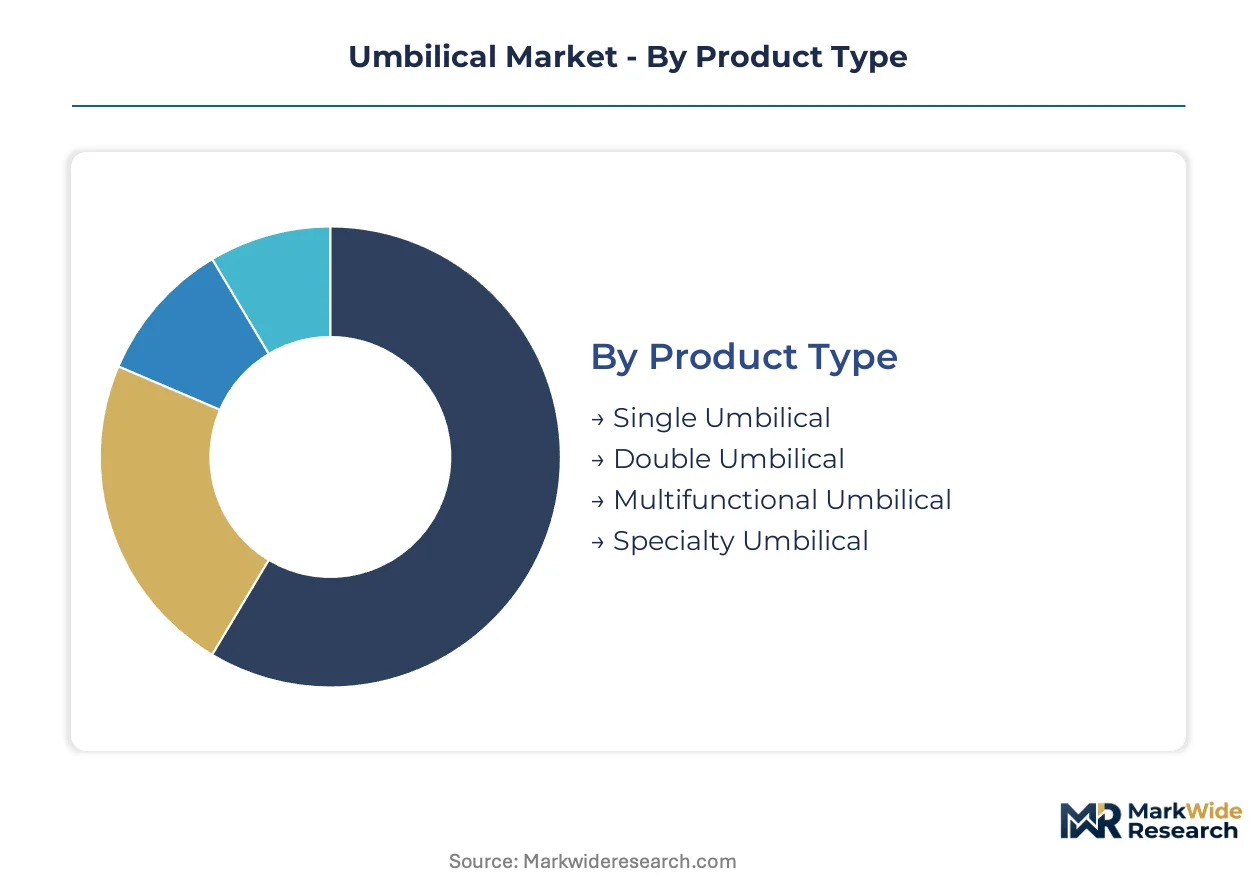
Umbilical procurement specifications vary sharply by deployment environment and functional load, forcing manufacturers to maintain parallel qualification tracks. Segment boundaries are blurring as multifunctional designs consolidate previously discrete product categories.
Product Type:
Supply concentration in steel-reinforced thermoplastic manufacturing favors vendors with integrated polymer compounding capabilities.
- Multifunctional Umbilical:Integrated assemblies combine hydraulic lines, electrical conductors, fiber-optic cables, and steel tubes within polymer sheathing. Brazil's pre-salt basin operators specify these for deepwater tiebacks to reduce installation complexity and vessel time.
- Specialty Umbilical:Custom-engineered constructions address extreme pressure, temperature, or chemical resistance requirements. North Sea developments and Gulf of Mexico ultra-deepwater fields drive qualification of aramid-reinforced and high-density polyethylene variants.
- Single Umbilical:Dedicated hydraulic or electrical lines for simple subsea control functions.
- Double Umbilical:Parallel redundant circuits for critical safety systems in production riser control.
Multifunctional umbilicals absorb the bulk of installed capacity; specialty umbilicals are expanding most quickly as frontier fields push operational envelopes.
Application:
Cost tier stratification separates capital-intensive subsea oil and gas deployments from emerging renewable energy specifications with shorter qualification cycles.
- Offshore Oil & Gas:Subsea production control, chemical injection, and monitoring for fixed platforms and floating facilities. API 17E and ISO 13628-5 qualification mandates govern procurement, with Norway's Petroleum Safety Authority and Brazil's ANP layering supplementary national protocols.
- Renewable Energy:Dynamic power cables and control umbilicals for floating offshore wind mooring systems. Celtic Sea and Pacific Northwest developers specify plug-and-play electrical interfaces that separate generator connection from structural load paths.
- Marine:Ship-to-shore power connections and dynamic positioning system controls.
- Industrial:Offshore platform utilities and coastal processing facility interconnections.
Offshore oil and gas retains the dominant revenue share; renewable energy applications are climbing the fastest as floating wind projects advance to commercial scale.
Installation Type:
Volume concentration in subsea deployments shapes manufacturing batch sizing and inventory pre-positioning strategies.
- Subsea:Seabed-laid umbilicals connecting wellheads, manifolds, and riser bases to surface facilities. Hydrostatic collapse resistance requirements extend qualification timelines for unproven constructions.
- Offshore:Platform-mounted and free-hanging dynamic sections subject to wave-induced fatigue. S-lay vessel contracting bundles are compressing procurement channels for integrated installation packages.
- Onshore:Coastal processing facility interconnections with simplified environmental loading.
- Surface:Temporary deployment and testing configurations.
Subsea installations command the largest committed manufacturing capacity; offshore dynamic sections are gaining share fastest as floating production systems multiply.
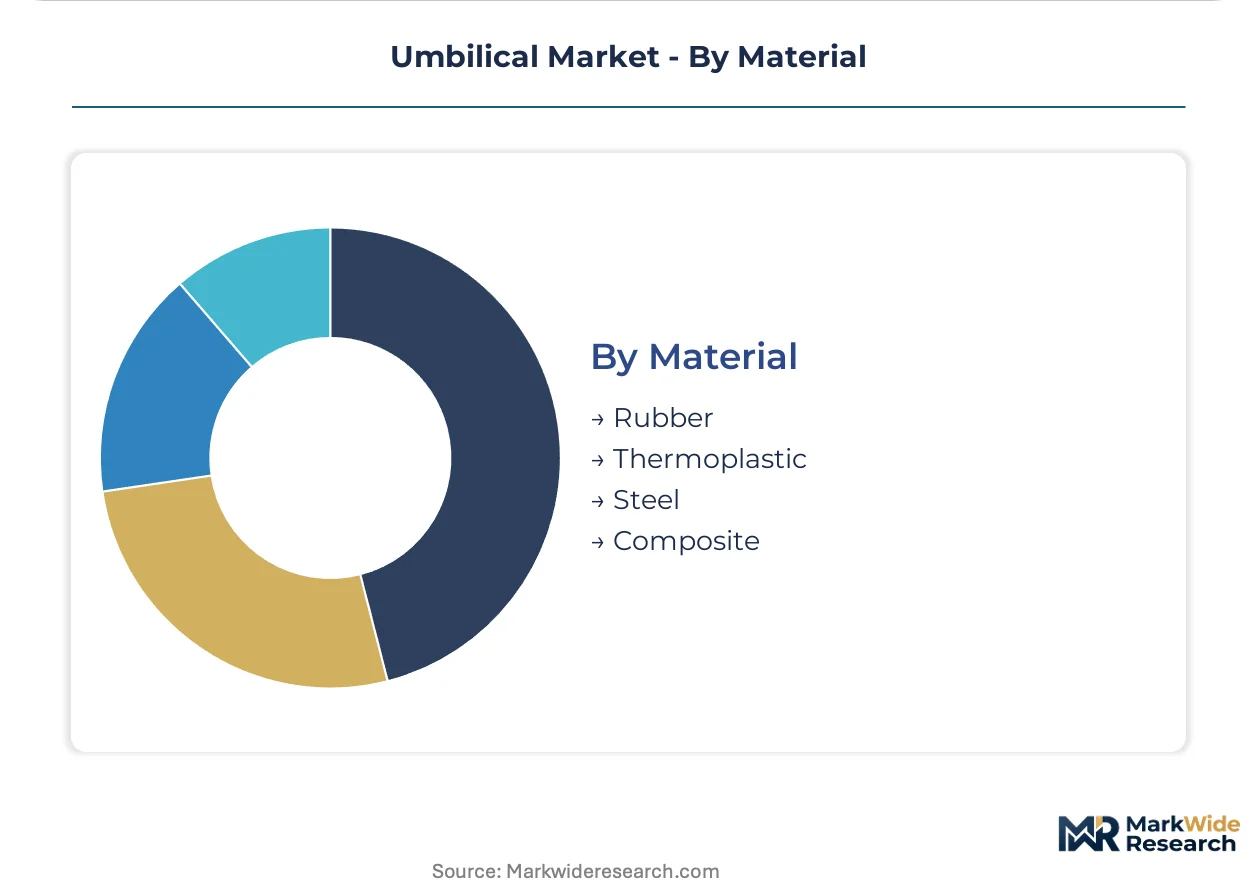
Material:
Margin structure diverges sharply between commodity polymer feedstocks and specialty high-performance compounds subject to REACH and F-Gas regulatory constraints.
- Thermoplastic:Steel-reinforced polymer constructions dominate deepwater applications where collapse resistance and fatigue life determine operational limits. EU F-Gas Regulation restrictions are accelerating bio-based thermoplastic elastomer qualification to maintain CE marking compliance.
- Steel:Armoring layers and integrated tubes for chemical injection and hydraulic power transmission. European compounder concentration in specialty elastomer supply creates input cost volatility for sheathing applications.
- Rubber:Legacy sheath compounds facing phase-out under fluorinated polymer restrictions.
- Composite:Aramid and carbon fiber reinforcements for weight-sensitive dynamic applications.
Thermoplastic constructions anchor the installed base; composite materials are advancing fastest as floating wind developers target mass reduction in dynamic cable systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in Western Europe and East Asia, while deployment demand clusters around Atlantic basin deepwater provinces and emerging Asia-Pacific offshore wind zones.
Brazil
Pre-salt basin developments drive steel-reinforced thermoplastic procurement at unprecedented scale. ANP qualification protocols mandate domestic content ratios that localize manufacturing partnerships. Rio de Janeiro's Niterói industrial corridor hosts qualification testing facilities serving Petrobras-led field tiebacks.
Norway
North Sea brownfield rejuvenation and Arctic frontier exploration sustain specialty umbilical demand for extreme pressure environments. The Petroleum Safety Authority enforces mandatory integrity monitoring regimes that create aftermarket service opportunities. Stavanger and Bergen anchor vendor engineering centers for subsea connection system development.
United States
Gulf of Mexico ultra-deepwater fields and Pacific Northwest floating wind pilots generate divergent specification requirements. BSEE well control regulations and emerging BOEM offshore wind leasing rules shape procurement timelines. Houston's Energy Corridor houses project management offices coordinating integrated S-lay vessel contracting.
China
State-backed offshore oil development and indigenous floating wind programs accelerate local qualification of steel tube-integrated designs. MIIT marine equipment certification and GB standards for subsea cables drive manufacturing quality protocols. Shanghai and Qingdao cluster polymer compounding and armoring line investments.
United Kingdom
Celtic Sea floating wind lease rounds and North Sea decommissioning obligations create bifurcated demand for dynamic cables and replacement umbilicals. The Offshore Petroleum Regulator for Environment and Decommissioning (OPRED) and emerging Great British Energy frameworks influence contract structures. Aberdeen maintains subsea engineering expertise despite manufacturing migration.
Umbilical Market Vendor Landscape
Top-tier vendors anchor integrated subsea production packages, while mid-scale specialists concentrate on component-level qualification and regional installation partnerships. Market structure tilts toward consolidation around steel-reinforced thermoplastic manufacturing capabilities. Three archetypes dominate: cable-centric conglomerates with polymer compounding integration, subsea engineering houses with proprietary connection systems, and installation contractors bundling procurement with vessel access. Competitive moves center on backward integration into high-performance polymer feedstock and lifecycle service contracting with predictive maintenance guarantees.
Among European cable conglomerates, Nexans and Prysmian Group exemplify polymer-to-system integration archetypes. Aker Solutions and TechnipFMC occupy positions spanning engineering design through installation execution. These four represent distinct strategic postures: Nexans emphasizes manufacturing scale, Prysmian leverages cross-industry cable expertise, Aker Solutions anchors proprietary harsh-environment terminations, and TechnipFMC competes across integrated production system packages where umbilicals form critical infrastructure links.
| Leading Market Players |
|---|
| Nexans |
| Subsea 7 |
| Aker Solutions |
| Vallourec |
| JDR Cable Systems |
| TechnipFMC |
| Oceaneering International |
| Halliburton |
| Prysmian Group |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down mandates gate qualified supply access and premium-tier pricing power by forcing compounders to reformulate sheath polymers ahead of CE marking deadlines. Buyers face bifurcated procurement timelines as bio-based thermoplastic elastomer qualification extends vendor onboarding while legacy fluorinated constructions face forced obsolescence.
Pricing Analysis
Cost-down pressure on standard-grade umbilicals accelerates because Brazilian pre-salt operators compress procurement cycles through pre-qualified vendor lists. Three-tier pricing structure across API 17E-certified premium, ISO 13628-5 standard, and unrated economy levels reflects qualification investment recovery timelines. Price differentiation hinges on collapse resistance certification depth and bundled predictive maintenance algorithms. Floating offshore wind developers exhibit lowest price sensitivity due to mooring integration complexity, while industrial onshore buyers drive hardest unit-cost negotiations.
Supply Chain Analysis
Dual-sourcing requirements from Petrobras and Equinor mandate qualified backup suppliers for steel-reinforced thermoplastic constructions, fragmenting volume concentration. Manufacturing gravity centers on Norway, Brazil, and China as ANP domestic content rules and MIIT marine equipment certification localize assembly. Feedstock supply draws from German and Belgian specialty elastomer compounders, creating tariff exposure as REACH chemical restrictions tighten import pathways. Distribution runs through integrated S-lay vessel contractors bundling umbilical lay with subsea infrastructure deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive polymer compounding capabilities determine margin capture and qualification timeline control.
For Market Incumbents: Hedge against steel tube-integrated riser substitution by deepening backward integration into high-performance thermoplastic elastomer feedstock. Pre-position manufacturing capacity in Rio de Janeiro's Niterói corridor to capture ANP-mandated domestic content ratios. Lock in lifecycle service contracts with predictive maintenance guarantees before Norwegian Petroleum Safety Authority inspection regimes commoditize aftermarket monitoring.
For New Entrants and Emerging Players: Installation contractors represent the most accessible channel partners for bypassing capital-intensive armoring line investments. Target Celtic Sea floating wind developers specifying plug-and-play electrical interfaces as the most penetrable white-space segment. Lead with modular dynamic power cable designs that separate generator connection from structural load paths to compress commissioning timelines.
For Investors and Strategic Acquirers: Consolidation of European specialty elastomer compounders is the leading indicator that feedstock supply will tighten and qualified manufacturing capacity will command scarcity premiums. Frame long-term viability around 5-10 year offshore wind installation windows where floating project pipelines determine umbilical demand trajectories. Prioritize acquisition targets with integrated polymer-to-system capabilities and DNV certification track records in dynamic bending applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of bio-based thermoplastic elastomers secures CE marking compliance ahead of F-Gas phase-down deadlines. |
| Lifecycle Service Contracting | Predictive maintenance subscriptions bundled with initial supply shift vendor relationships toward performance-guarantee structures. |
| Regional Manufacturing Localization | ANP domestic content mandates in Brazil and MIIT certification in China force assembly proximity to deployment demand. |
| Dynamic Power Cable Modularization | Plug-and-play electrical interfaces for floating wind separate generator connection from structural load paths. |
| Integrity Monitoring Platform Development | Norwegian Petroleum Safety Authority inspection regimes create aftermarket revenue streams from installed umbilical bases. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving subsea project engineers, polymer compound procurement leads, offshore installation contractors, and floating wind development executives. API 17E qualification databases, ANP domestic content compliance records, and DNV certification registries provided manufacturing quality benchmarks. Bottom-up project pipeline tracking across Brazil's pre-salt basin and Celtic Sea lease rounds triangulated with top-down vendor capacity assessments.
Segment-level granularity modeled product type across multifunctional, specialty, single, and double umbilical constructions; application across offshore oil and gas, renewable energy, marine, and industrial end-uses; installation type across subsea, offshore, onshore, and surface deployments; and material across thermoplastic, steel, rubber, and composite variants. CAGRs derived from weighted project sanctioning timelines and qualification cycle compression rates. Forecast inputs incorporated floating offshore wind capacity additions and pre-salt field tieback acceleration scenarios.
Caveats apply where API 17E revision timelines or F-Gas Regulation enforcement intensity could materially shift the outlook. Deviation in Brazilian pre-salt investment cadence or Norwegian integrity monitoring mandate scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal and Infant Care Equipment Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Infant Care Market