
 Neonatal and Infant Care Equipment Market | 2026-2036
Neonatal and Infant Care Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal and Infant Care Equipment Market Foresight
Neonatal intensive care units within hospital networks is consolidating as the dominant procurement channel, displacing standalone clinic purchases across major metropolitan health systems. GE Healthcare leverages its embedded monitoring ecosystem to anchor long-term service contracts in North American academic medical centers. Drägerwerk AG & Co. KGaA competes through specialized ventilation platforms designed for extremely low birth weight infants. Koninklijke Philips N.V. sustains technology leadership in digital patient monitoring architectures that integrate with enterprise electronic health records.
Neonatal and infant care equipment encompasses thermoregulation devices, respiratory support systems, physiological monitors, and developmental assessment tools engineered for patients from birth through twelve months, with incubators typically maintaining thermal environments within 0.5 degrees Celsius of set points and ventilators delivering tidal volumes as low as 2 milliliters. This equipment serves the clinical imperative of stabilizing premature and critically ill infants while supporting neurodevelopmental outcomes during the highest-risk period of human life. Incubators and warmers occupy mature margin pools where replacement cycles and energy efficiency upgrades drive purchasing decisions, while telehealth solutions represent the fastest-expanding technology dimension as remote neonatology consultations extend specialist reach into underserved birth centers. Monitors and digital monitoring platforms concentrate value capture through recurring sensor and software subscription revenues rather than capital equipment margins alone.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and commercialization costs for manufacturers seeking multi-regional market access. ISO 13485 quality management systems and IEC 60601-1-10 usability standards further constrain design choices for devices intended for fragile neonatal populations. Stakeholders must weigh regulatory compliance investments against the strategic imperative to serve emerging markets where national health programs are building centralized referral capacity for complex newborn conditions.
Market Dynamics
Telehealth-enabled remote neonatology is consolidating specialist reach into tier-two birth centers, compressing the traditional hub-and-spoke referral model that concentrated complex cases in academic medical centers.
Growth Catalysts
- EU MDR conformity assessments:Stricter technical documentation requirements for respiratory devices are accelerating product standardization across European markets, reducing fragmentation in device interoperability.
- India's Special Newborn Care Units:Government-funded expansion under national health mission programs is creating procurement pipelines for thermoregulation and monitoring equipment in secondary cities.
- Sensor miniaturization:Advances in microfabrication are enabling non-invasive continuous glucose and oxygen saturation monitoring in extremely low birth weight infants, opening new clinical applications.
Market Restraints
- Platinum-group metal volatility:Incubator heating elements and pulse oximeter sensors depend on platinum and palladium inputs subject to South African and Russian supply concentration risks.
- FDA 510(k) pathway friction:Substantial equivalence determinations for neonatal ventilators now require expanded clinical data, extending premarket timelines by twelve to eighteen months.
- Reusable device substitution:Refurbished incubators from tertiary hospital replacement cycles are capturing price-sensitive demand in private clinic chains, compressing new equipment margins.
Strategic Opportunities
- Brazil's ANVISA fast-track:Priority review pathways for neonatal respiratory devices are opening accelerated market access for manufacturers with existing FDA or EMA approvals.
- AI-integrated alarm management:Machine learning algorithms reducing false-positive apnea alerts are converging with cloud-based monitoring platforms to create subscription revenue models.
- Direct-to-hospital distribution:Bypassing traditional medical device distributors through manufacturer-employed clinical specialists is capturing margin in high-volume NICU networks.
Industry Challenges
- Neonatal-perinatal medicine workforce gaps:Shortages of trained neonatologists in community birth centers are limiting effective deployment of advanced monitoring equipment outside tertiary settings.
- Legacy EHR integration complexity:Proprietary data formats from incumbent monitoring vendors are forcing costly middleware development for hospitals pursuing enterprise architecture consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal and Infant Care Equipment Market |
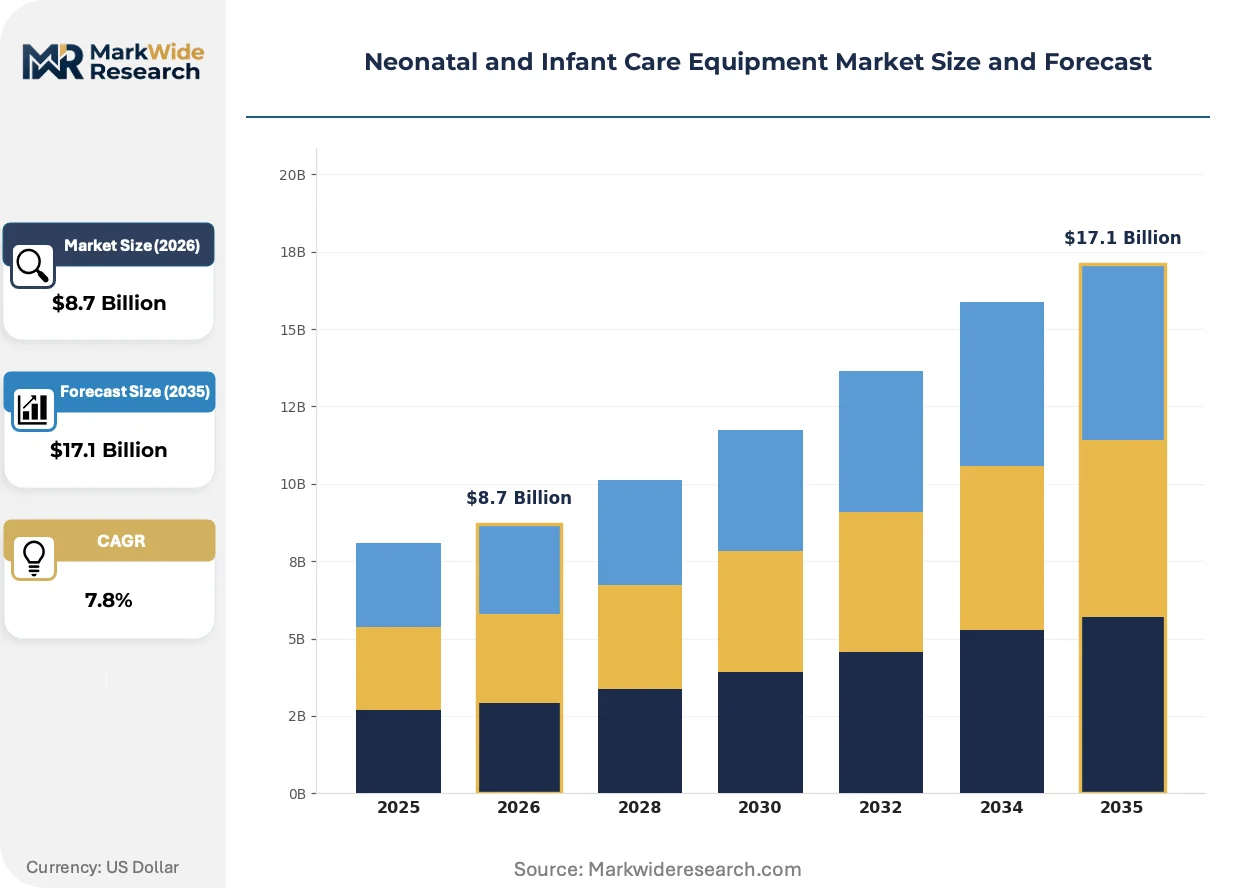
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incubators, Warmers, Monitors, Ventilators End User: Hospitals, Clinics, Diagnostic Centers, Homecare Technology: Closed Loop Systems, Reusable Equipment, Digital Monitoring, Telehealth Solutions Application: Therapeutic Care, Routine Check-ups, Emergency Resuscitation, Developmental Monitoring |
| Companies Covered | GE Healthcare, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., Medtronic, Masimo, Fisher & Paykel Healthcare, BD, Getinge, Atom Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal and Infant Care Equipment Market Shifts & Advancements
Digital twin simulations of infant thermoregulation are compressing device development cycles while enabling personalized incubator protocols based on gestational age and weight-specific metabolic models.
Closed-loop automated oxygen control is rewriting clinical workflows in NICU respiratory management. The technology continuously adjusts fraction of inspired oxygen based on real-time pulse oximetry feedback. Level III NICUs in Germany and the Netherlands are adopting these systems at replacement cycle points. This capability is rewriting staffing ratios by reducing manual titration demands on respiratory therapists during overnight shifts.
REACH restrictions on perfluorinated compounds are forcing material transitions in incubator humidification chambers and breathing circuit components. Manufacturers are validating silicone and thermoplastic elastomer alternatives through accelerated aging studies. Neonatal ventilator product lines with EU market priority are most affected, with several suppliers establishing dedicated polymer substitution task forces.
Consolidated procurement through hospital network central offices is displacing individual unit purchasing authority. Group purchasing organizations are aggregating demand across multi-hospital systems and extracting volume-based price concessions. This pattern is most visible in US metropolitan markets where health system mergers have concentrated NICU beds under single corporate umbrellas.
Neonatal and Infant Care Equipment Market Segmentation
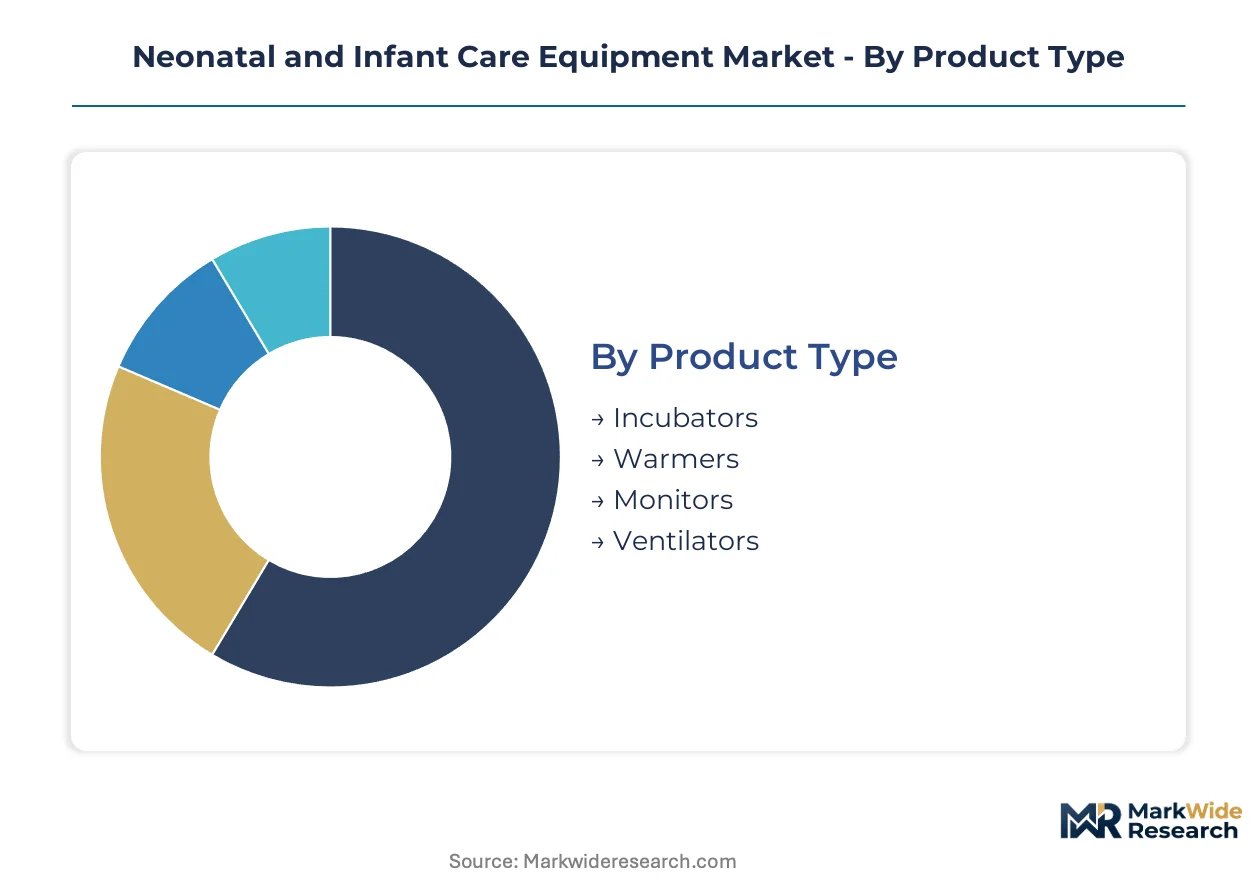
Equipment segmentation in neonatal care reflects divergent procurement logics across acute care networks and ambulatory settings. Buyers prioritize either capital efficiency or clinical capability depending on patient acuity and reimbursement structures.
Product Type:
Procurement committees weight replacement cycles against interoperability with existing monitoring ecosystems when allocating capital across device categories.
- Incubators:Double-walled servo-controlled thermal environments maintain neutral temperature zones for infants below 1500 grams. Demand clusters in India under government-funded Special Newborn Care Unit expansions, where energy efficiency upgrades drive purchasing decisions against legacy radiant warmers.
- Monitors:Multiparameter platforms integrate pulse oximetry, cardiorespiratory patterns, and temperature through single display architectures. North American academic medical centers anchor demand through recurring sensor and software subscription revenues rather than equipment margins alone.
- Warmers:Radiant heat sources with servo-control mechanisms provide rapid thermal support during resuscitation and procedures.
- Ventilators:Pressure-limited and volume-targeted modes deliver tidal volumes as low as 2 milliliters for extremely low birth weight infants.
Monitors lead on scale; incubators lead on momentum through government-funded infrastructure builds.
End User:
Facility certification levels determine equipment sophistication thresholds and corresponding price bands.
- Hospitals:Level III and IV NICUs within consolidated health networks command multi-parameter monitoring suites and advanced ventilation platforms. Group purchasing organizations aggregate demand across multi-hospital systems in US metropolitan markets, extracting volume-based price concessions.
- Homecare:Portable pulse oximeters and apnea monitors enable early discharge protocols for stable preterm infants. Reimbursement expansion under Medicaid home health programs in several US states accelerates equipment deployment outside institutional settings.
- Clinics:Secondary birth centers in tier-two cities acquire refurbished incubators from tertiary hospital replacement cycles.
- Diagnostic Centers:Developmental assessment tools including automated auditory brainstem response systems support outpatient screening protocols.
Hospitals dominate absolute volume; homecare demonstrates the steepest expansion trajectory.
Technology:
Recurring revenue potential versus upfront capital recovery shapes manufacturer R&D allocation across technology platforms.
- Digital Monitoring:Cloud-native architectures with AI-integrated alarm management reduce false-positive apnea alerts through machine learning algorithms. Enterprise electronic health record integration drives purchasing decisions among hospitals pursuing architecture consolidation.
- Telehealth Solutions:Real-time video consultation platforms with remote physiological data streaming extend neonatologist reach into community birth centers. Germany and the Netherlands lead adoption at Level III NICU replacement cycle points.
- Closed Loop Systems:Automated oxygen titration based on continuous pulse oximetry feedback rewrites respiratory therapist staffing ratios during overnight shifts.
- Reusable Equipment:Refurbishment protocols for incubators and warmers capture price-sensitive demand in private clinic chains.
Digital monitoring commands installed base; telehealth solutions are climbing the fastest.
Application:
Clinical workflow intensity and regulatory documentation requirements segment equipment deployment patterns.
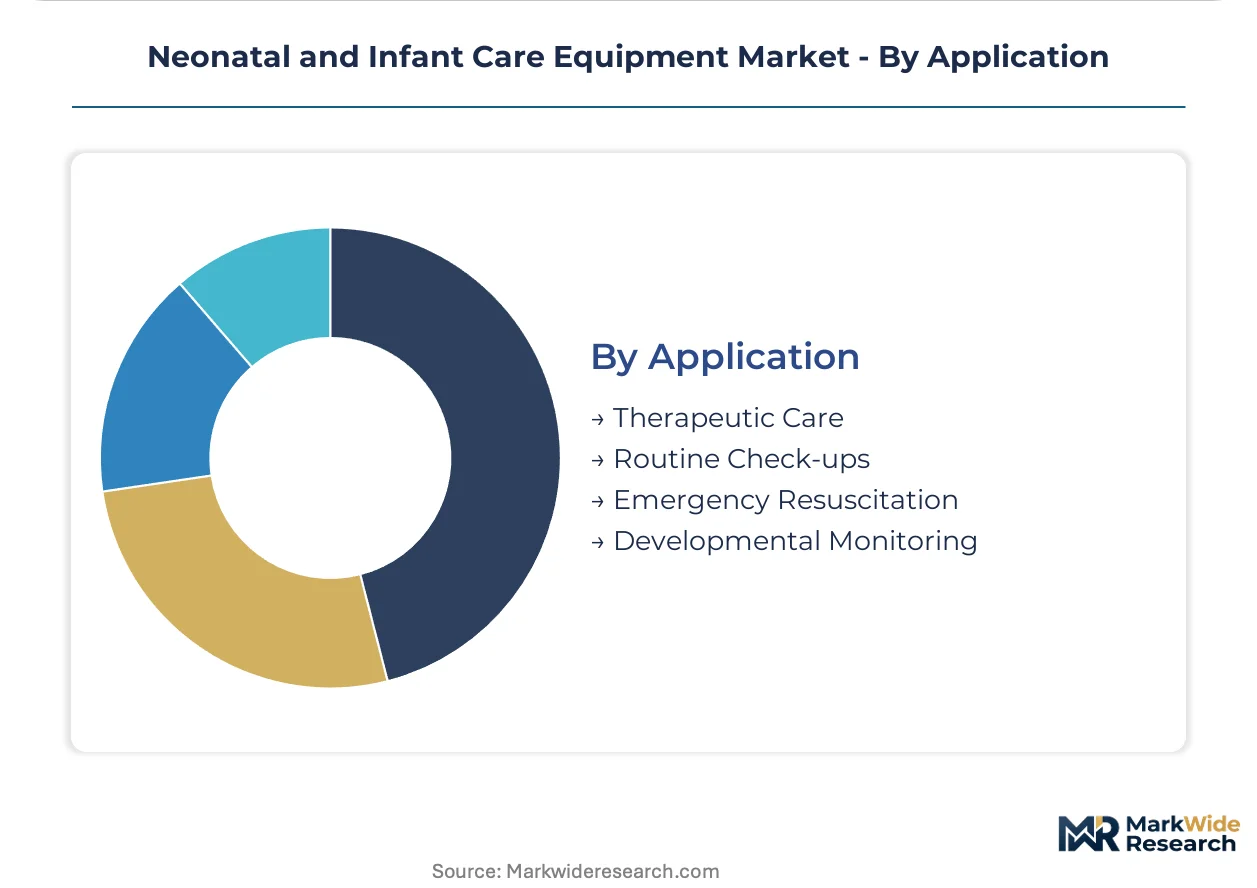
- Therapeutic Care:Continuous thermal regulation and respiratory support for premature infants requires 24-hour monitoring capabilities. FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines for devices intended for fragile neonatal populations.
- Emergency Resuscitation:T-piece resuscitators and radiant warmers with integrated oxygen blenders stabilize infants in delivery rooms. Neonatal-perinatal medicine workforce gaps in community birth centers limit effective deployment outside tertiary settings.
- Routine Check-ups:Digital scales and automated blood pressure cuffs support standardized growth monitoring protocols.
- Developmental Monitoring:Near-infrared spectroscopy and amplitude-integrated electroencephalography track neurodevelopmental outcomes.
Therapeutic care anchors procurement volume; emergency resuscitation is gaining share fastest through point-of-care expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions where FDA and EU MDR compliance costs widen competitive gaps between incumbent and emerging producers. Manufacturers now site final assembly in lower-cost regulatory environments while maintaining design and quality functions in established markets.
United States
Academic medical centers in Boston and Philadelphia anchor procurement for multi-parameter monitoring suites with embedded AI alarm management. FDA 510(k) clearance timelines for neonatal ventilators now stretch eighteen months, favoring incumbents with established predicate device portfolios. The Southeast corridor from North Carolina to Florida concentrates refurbished equipment redistribution networks serving price-sensitive clinic chains.
Germany
Level III NICUs in Munich and Hamburg drive adoption of closed-loop automated oxygen control systems at replacement cycle points. BfArM oversight aligns with EU MDR technical documentation requirements, accelerating interoperability standards across ventilation platforms. The Baden-Württemberg industrial cluster hosts precision sensor manufacturers supplying pulse oximetry modules to device integrators.
India
Government-funded Special Newborn Care Units under the National Health Mission are expanding procurement pipelines in secondary cities including Pune, Hyderabad, and Chennai. CDSCO registration requirements for imported respiratory devices are streamlining through mutual recognition agreements with FDA and EMA. Karnataka's medical device manufacturing zone near Bangalore is attracting contract assembly operations for thermoregulation equipment.
Brazil
ANVISA fast-track priority review for neonatal respiratory devices is compressing market entry timelines for manufacturers with existing FDA or EMA approvals. São Paulo's consolidated hospital networks are aggregating demand through group purchasing organizations, extracting volume concessions from distributors. The Minas Gerais corridor hosts refurbishment operations capturing replacement-cycle incubators from tertiary facilities.
Netherlands
Telehealth-enabled remote neonatology platforms are deploying fastest in Amsterdam and Utrecht academic networks, extending specialist reach into community birth centers. Health and Youth Care Inspectorate oversight aligns with EU MDR conformity assessments for digital monitoring architectures. The Eindhoven high-tech cluster supplies microfabricated sensor components for non-invasive glucose monitoring development.
Neonatal and Infant Care Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement through hospital networks favoring full-service incumbents over component suppliers. The vendor landscape organizes into three tiers: diversified medical technology conglomerates with embedded service ecosystems, mid-scale specialists with ventilation or monitoring depth, and regional fabricators serving price-sensitive replacement markets. Dominant competitive moves include backward integration into sensor manufacturing and direct-to-hospital distribution bypassing traditional medical device distributors.
Within the diversified conglomerate tier, GE Healthcare, Koninklijke Philips N.V., and Drägerwerk AG & Co. KGaA exemplify positioning anchored by long-term service contracts and enterprise electronic health record integration capabilities. These entities represent the archetype of technology leadership through recurring revenue models rather than capital equipment margins alone. Among specialists, Fisher & Paykel Healthcare and Masimo occupy positions defined by respiratory and physiological monitoring depth respectively.
| Leading Market Players |
|---|
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| Medtronic |
| Masimo |
| Fisher & Paykel Healthcare |
| BD |
| Getinge |
| Atom Medical Corporation |
| Others |
Supply & Pricing Matrix
REACH restrictions on perfluorinated compounds gate qualified supply for incubator humidification chambers and breathing circuit components, limiting premium-tier pricing access to manufacturers with validated silicone and thermoplastic elastomer alternatives through accelerated aging studies. Buyers in EU-prioritized ventilator product lines now face material substitution costs that stratify procurement tiers between compliant and non-compliant suppliers.
Pricing Analysis
Distributor margins of 15-25 percent in traditional medical device channels are compressing as direct-to-hospital distribution bypasses intermediaries through manufacturer-employed clinical specialists. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multi-parameter monitoring suites from refurbished incubators and basic radiant warmers. Cost compression in the economy tier is intensifying because private clinic chains in Brazil and India capture price-sensitive demand through tertiary hospital replacement cycles. Group purchasing organizations in consolidated US health networks demonstrate lowest price sensitivity due to volume aggregation, while standalone diagnostic centers in secondary Indian cities exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Dual-sourcing requirements for platinum-group metals in pulse oximeter sensors and incubator heating elements mandate multi-supplier qualification across South African and Russian concentrate producers, though geographic concentration in South African mining districts and Russian refining capacity creates persistent single-source vulnerability. Microfabricated sensor components draw from the Eindhoven high-tech cluster in the Netherlands and precision manufacturing zones in Baden-Württemberg, Germany. Supply chain risk centers on platinum and palladium price volatility driven by South African power grid instability and sanctions exposure on Russian metal flows. Distribution runs through hospital network central offices and group purchasing organizations in consolidated metropolitan health systems, displacing individual unit purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neonatal and infant care equipment market operates as a regulatory compounder where EU MDR conformity assessments and FDA 510(k) pathway friction continuously elevate compliance investment thresholds, driving demand toward incumbents with established predicate device portfolios and multi-regional quality management systems.
For Market Incumbents: Lock in long-term service contracts through embedded monitoring ecosystem integration with enterprise electronic health records, defending against refurbished equipment substitution by capturing replacement-cycle revenue through energy efficiency upgrade programs. Deepen backward integration into microfabricated sensor manufacturing to reduce platinum-group metal exposure and anchor proprietary pulse oximetry module supply.
For New Entrants and Emerging Players: AI-integrated alarm management algorithms reducing false-positive apnea alerts offer a technology-first wedge into cloud-native monitoring platforms where subscription revenue models displace capital equipment margins. Target telehealth-enabled remote neonatology in tier-two birth centers across Germany and the Netherlands, deploying direct-to-hospital clinical specialist teams to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale ventilation specialists because consolidated procurement through hospital network central offices favors full-service vendors with regulatory dossiers across FDA, EMA, and ANVISA jurisdictions. Monitor CDSCO mutual recognition agreement implementation pace with FDA and EMA as the inflection indicator for Indian manufacturing zone investment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates interoperability standards across ventilation platforms in German Level III NICUs. |
| Direct-to-Hospital Distribution Buildout | Captures margin in high-volume NICU networks by bypassing traditional medical device distributors. |
| AI-Integrated Alarm Management Development | Reduces false-positive apnea alerts through machine learning algorithms converging with cloud platforms. |
| Backward Integration into Sensor Manufacturing | Anchors proprietary pulse oximetry supply from Eindhoven and Baden-Württemberg precision clusters. |
| Refurbishment Protocol Standardization | Captures price-sensitive demand in Brazilian private clinic chains through tertiary replacement cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with neonatologists, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers with secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CDSCO registration data. Bottom-up equipment unit forecasts triangulated against top-down health system capital expenditure patterns.
Segment-weighting approaches modeled product type, end user facility certification level, technology platform, and clinical application dimensions across the projection horizon. CAGRs derived from replacement cycle timing, government-funded infrastructure expansion pipelines, and sensor miniaturization adoption curves. Forecast inputs incorporated Special Newborn Care Unit buildout schedules under India's National Health Mission and closed-loop automated oxygen control adoption rates in German and Dutch Level III NICUs.
The model holds under stable regulatory mutual recognition agreements and continued government health mission funding; deviation in platinum-group metal supply disruption or EU MDR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Europe Fetal and Neonatal Care Equipment Market
Neonatal Care
Infant Resuscitators Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Perinatal Software Market
Neonatal Care
Global NICU Catheter Market