
 Neonatal Respiratory Distress Syndrome Market | 2026-2036
Neonatal Respiratory Distress Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal Respiratory Distress Syndrome Market Foresight
Single-source surfactant supply agreements between hospital systems and manufacturers are consolidating into multi-year, multi-vendor contracts. Chiesi Farmaceutici S.p.A. anchors European surfactant production through its porcine-derived portfolio. AbbVie Inc. leverages synthetic surfactant R&D pipelines to compete in markets with religious or ethical restrictions on animal-derived therapies. Fisher & Paykel Healthcare Limited specializes in heated humidified high-flow nasal cannula systems that reduce mechanical ventilation dependency in premature infants.
Neonatal respiratory distress syndrome is a breathing disorder caused by surfactant deficiency in preterm infants, clinically defined by increased work of breathing, hypoxemia, and diffuse atelectasis on chest radiography within hours of birth; exogenous surfactant replacement administered via endotracheal tube remains the foundational pharmacotherapy, with dosing calibrated to birth weight and disease severity to restore alveolar surface tension equilibrium. Surfactants occupy the largest revenue pool given mandatory prophylaxis in infants below 30 weeks gestational age, while preventive care protocols represent the fastest-expanding treatment segment as antenatal corticosteroid administration and early CPAP strategies delay or eliminate surfactant rescue dosing. Mechanical ventilation equipment generates durable aftermarket revenue through consumables and servicing contracts despite declining utilization rates per patient.
The FDA maintains stringent pediatric study requirements under the Pediatric Research Equity Act, compelling manufacturers to generate neonatal-specific safety data rather than extrapolating from adult trials. EMA's orphan drug incentives have accelerated surfactant biosimilar development pathways in Europe, though post-approval pharmacovigilance obligations extend through adolescent follow-up periods. Stakeholders must monitor evolving non-invasive respiratory support algorithms that threaten to displace surfactant revenue models without fully eliminating the underlying clinical need.
Market Dynamics
Preventive surfactant protocols are compressing rescue dosing volumes while expanding total eligible infant populations, creating a volume-value tension that manufacturers must navigate through indication expansion and delivery innovation.
Growth Catalysts
- Antenatal corticosteroid protocols:Maternal administration of betamethasone reduces surfactant deficiency severity, expanding the addressable population of infants requiring prophylactic rather than rescue therapy.
- EMA orphan drug incentives:Accelerated biosimilar surfactant pathways in Europe compress development timelines for porcine-derived alternatives, stimulating manufacturer pipeline investment.
- Tertiary birthing center consolidation:High-risk neonatal respiratory services concentrate in United States academic medical centers, creating dedicated procurement channels for advanced surfactant formulations.
Market Restraints
- Porcine-derived supply vulnerability:Religious and ethical restrictions in Middle Eastern and South Asian markets limit addressable demand for animal-source surfactants, forcing synthetic alternative development.
- FDA Pediatric Research Equity Act requirements:Mandatory neonatal-specific safety trials extend approval timelines and inflate development costs compared to adult indication extrapolation.
- Heated humidified high-flow nasal cannula substitution:Non-invasive respiratory support delays or eliminates surfactant administration in moderate prematurity cases, threatening revenue per patient.
Strategic Opportunities
- Surfactant administration without intubation:Laryngeal mask airway and thin catheter delivery methods enable minimally invasive surfactant therapy, expanding treatment to infants previously managed with CPAP alone.
- Indian tertiary neonatal network expansion:Underpenetrated institutional delivery infrastructure in Maharashtra and Tamil Nadu creates demand for surfactant cold-chain distribution partnerships.
- Post-approval pharmacovigilance data monetization:Longitudinal adolescent follow-up obligations under EMA frameworks generate real-world evidence assets for label expansion and payer negotiations.
Industry Challenges
- Neonatal pharmacology expertise scarcity:Pediatric formulation scientists and neonatal clinical trialists command premium compensation, constraining sponsor capacity to run concurrent development programs.
- Mechanical ventilation aftermarket compression:Declining ventilator days per patient reduces consumables revenue and service contract values, forcing equipment manufacturers to restructure pricing models.
- Multi-vendor contract complexity:Hospital system consolidation of surfactant procurement across porcine, synthetic, and biosimilar sources strains inventory management and formulary standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal Respiratory Distress Syndrome Market |
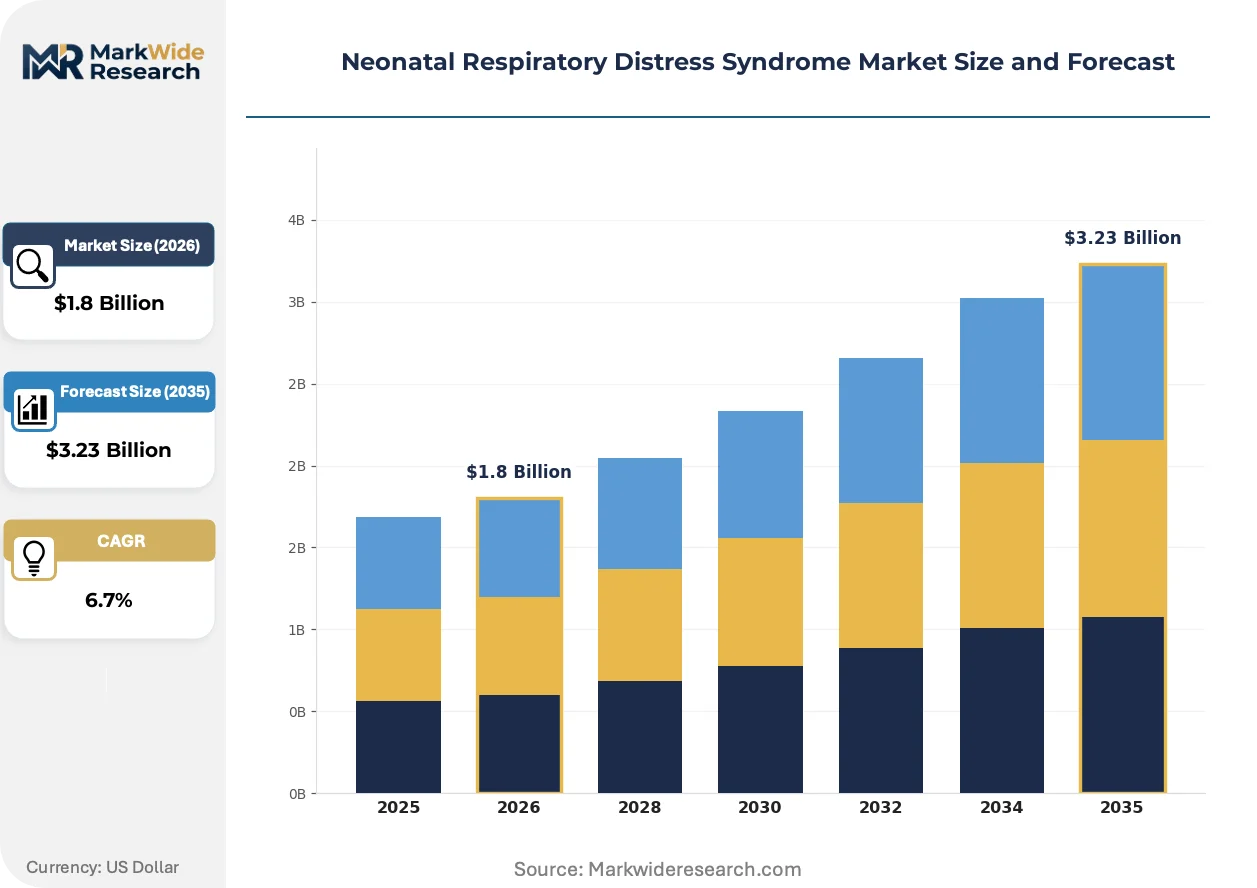
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Bronchodilators, Corticosteroids, Antibiotics Delivery Mode: Inhalation, Intravenous, Oral, Subcutaneous End User: Hospitals, Neonatal Intensive Care Units, Home Care, Clinics Treatment Protocol: Preventive Care, Supportive Care, Pharmacotherapy, Mechanical Ventilation |
| Companies Covered | AbbVie Inc., Chiesi Farmaceutici S.p.A., Pfizer Inc., Novartis AG, Merck & Co., Inc., Drägerwerk AG & Co. KGaA, Fisher & Paykel Healthcare Limited, Medtronic plc, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal Respiratory Distress Syndrome Market Shifts & Advancements
Minimally invasive surfactant therapy techniques are redefining treatment thresholds, while regulatory frameworks on both sides of the Atlantic accelerate biosimilar competition and reshape competitive positioning around delivery devices rather than active pharmaceutical ingredients alone.
Synthetic surfactant formulations containing peptide analogs of surfactant protein B are absorbing clinical trial investment previously directed toward animal-derived alternatives. Tertiary neonatal intensive care units in the United States and Germany are adopting these formulations for infants with contraindications to porcine products. The technology is absorbing market share in ethical-restriction markets while simultaneously compressing pricing power across the surfactant category.
EMA's 2023 refinement of pediatric investigation plan requirements for orphan respiratory drugs has shortened biosimilar surfactant approval timelines by permitting extrapolated efficacy from pharmacodynamic endpoints. European manufacturers are responding with accelerated filing strategies for porcine-derived biosimilars. The policy shift most affects mid-gestation prophylaxis indications, where sponsors can leverage existing surfactant protein concentration biomarker data.
Consolidated surfactant procurement through neonatal intensive care network purchasing cooperatives is replacing individual hospital formulary decisions in the United States. These cooperatives negotiate multi-year supply agreements spanning prophylactic and rescue indications, displacing traditional distributor relationships. The behavioral shift is most visible in California and Texas, where state-level perinatal quality collaboratives have centralized high-risk delivery center designation and attendant pharmaceutical procurement.
Neonatal Respiratory Distress Syndrome Market Segmentation
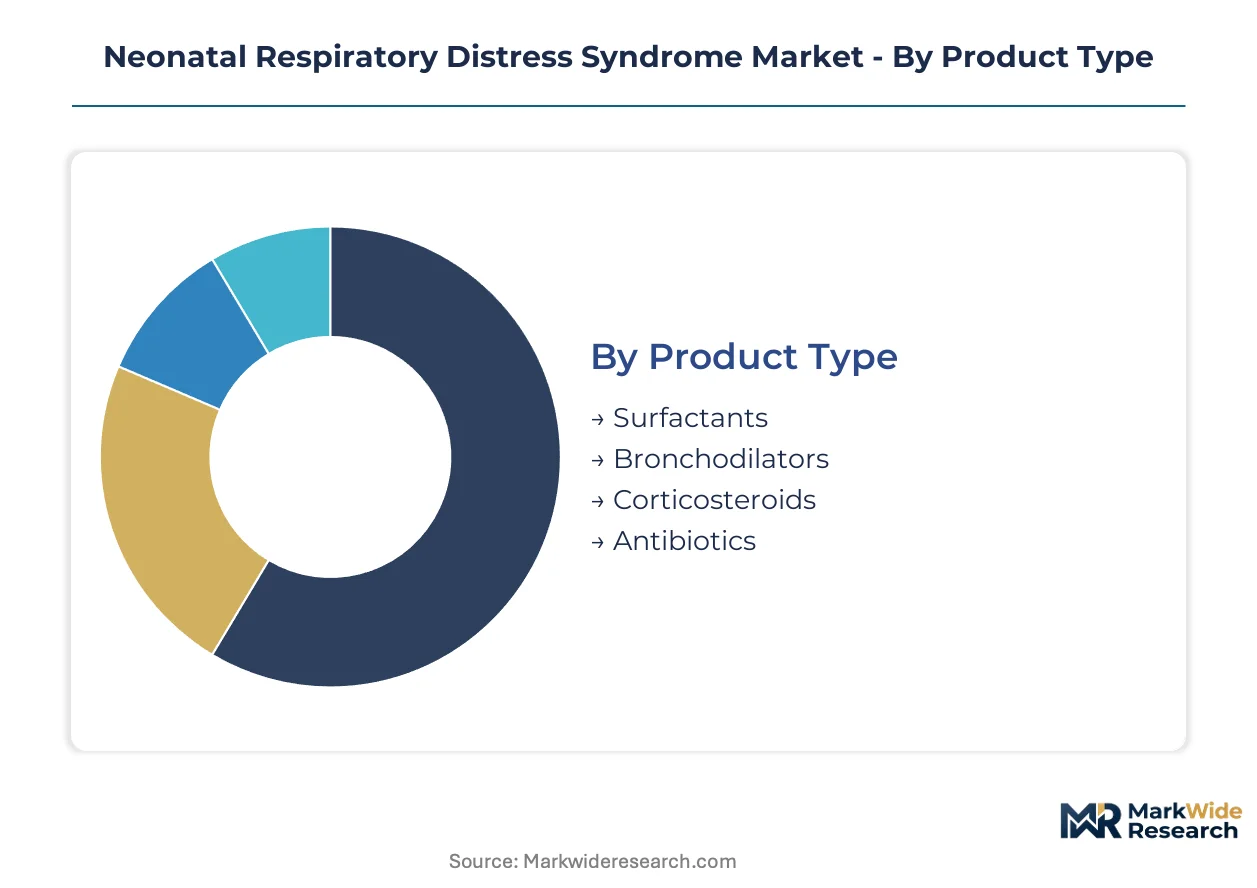
Segmentation in neonatal respiratory distress syndrome markets reveals how regulatory pathways, delivery complexity, and care settings fragment procurement decisions. Manufacturers must align formulation portfolios with the specific approval burdens and clinical workflows governing each category.
Product Type:
FDA Pediatric Research Equity Act mandates and EMA orphan drug frameworks impose divergent certification timelines across pharmaceutical classes, with animal-derived biologics facing distinct pharmacovigilance obligations versus synthetic small molecules.
- Surfactants:Porcine-derived and synthetic phospholipid-protein formulations restore alveolar surface tension equilibrium in preterm infants. Demand concentrates in United States tertiary birthing centers where prophylactic protocols below 30 weeks gestational age drive procurement volume; EMA pharmacovigilance obligations through adolescent follow-up extend real-world evidence generation timelines.
- Bronchodilators:Beta-agonist and anticholinergic agents reduce airway resistance in infants with reactive airway components. Adoption is accelerating in Indian tertiary neonatal networks where institutional delivery infrastructure expansion creates new addressable populations for inhaled therapy protocols.
- Corticosteroids:Systemic and inhaled glucocorticoid formulations modulate inflammatory responses in ventilator-dependent infants.
- Antibiotics:Broad-spectrum agents address secondary infection prophylaxis in mechanically ventilated neonates.
Leading the category by volume: Surfactants. Expanding most quickly: Bronchodilators.
Delivery Mode:
Route selection determines device compatibility requirements and reimbursement coding complexity, with invasive versus non-invasive pathways commanding different per-procedure economics.
- Inhalation:Nebulized and metered-dose aerosol delivery enables targeted pulmonary deposition without systemic exposure. Heated humidified high-flow nasal cannula systems in German and United States NICUs are displacing intubation-dependent administration, compressing revenue per patient while expanding eligible infant populations.
- Intravenous:Direct vascular administration ensures bioavailability for systemic corticosteroids and antibiotics. Concentrated demand in California perinatal quality collaboratives where centralized high-risk delivery designation streamlines procurement of parenteral formulations.
- Oral:Enteral administration of palatable liquid formulations supports transition-to-feeding protocols.
- Subcutaneous:Depot injections provide sustained corticosteroid release in home care transition settings.
Fastest volume growth: Inhalation. Highest revenue per procedure: Intravenous.
End User:
Facility accreditation tiers determine formulary breadth and cold-chain infrastructure requirements, segmenting addressable markets by care complexity.
- Hospitals:General acute care settings manage moderate prematurity with non-invasive support. Procurement in Texas state-level collaboratives aggregates demand across multi-hospital systems, favoring multi-vendor surfactant contracts over single-source agreements.
- Neonatal Intensive Care Units:Level III and IV centers administer prophylactic surfactant and mechanical ventilation. United States academic medical centers anchor synthetic surfactant adoption where porcine-derived contraindications drive peptide-analog formulation demand.
- Home Care:Discharge-ready infants receive ongoing bronchodilator and corticosteroid therapy.
- Clinics:Outpatient follow-up facilities manage respiratory surveillance post-NICU discharge.
Dominant procurement volume: Neonatal Intensive Care Units. Fastest network expansion: Home Care.
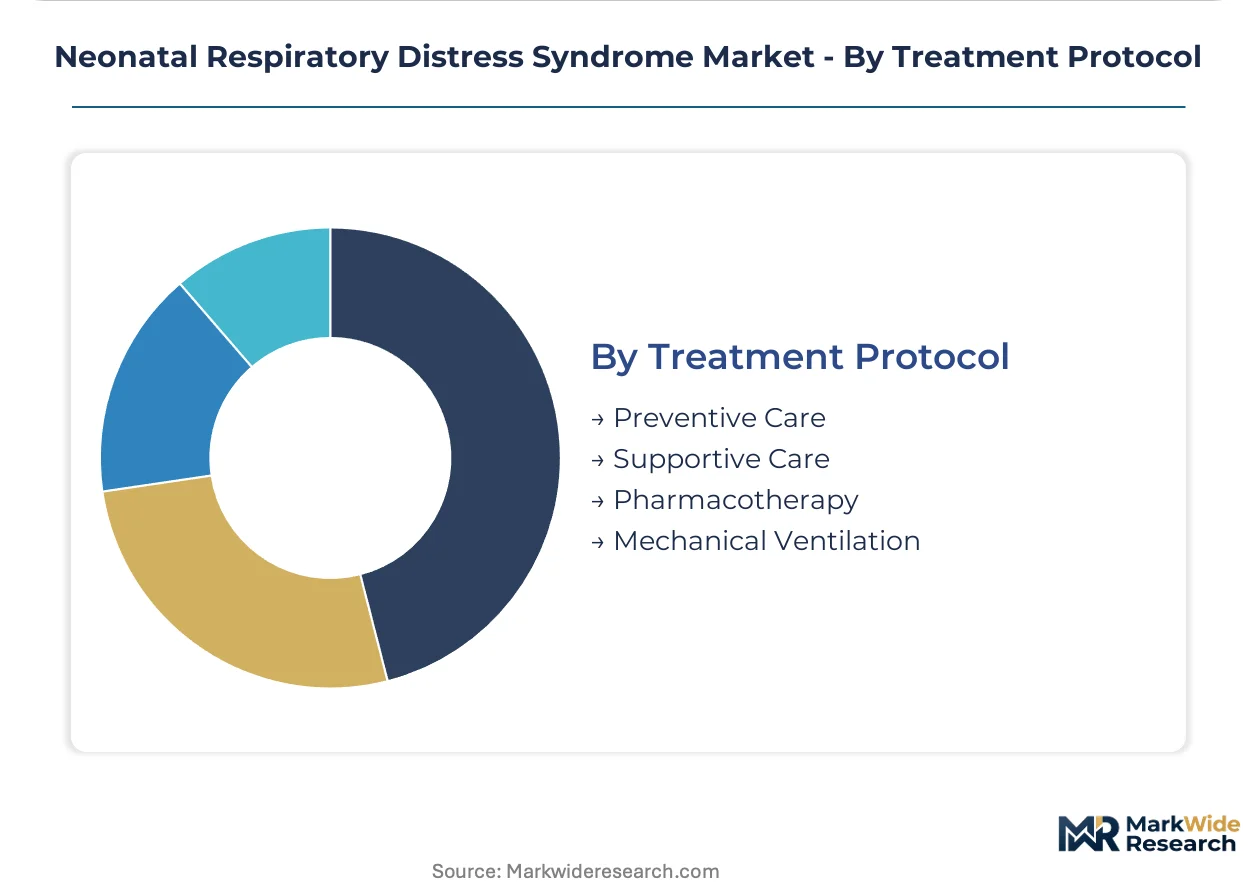
Treatment Protocol:
Protocol positioning along the severity spectrum dictates pricing power, with preventive interventions commanding premium positioning versus rescue therapy commoditization.
- Preventive Care:Antenatal corticosteroid administration and early CPAP strategies delay or eliminate surfactant rescue dosing. Maternal betamethasone protocols in Maharashtra and Tamil Nadu institutional delivery networks are expanding addressable populations for prophylactic rather than emergent intervention.
- Pharmacotherapy:Exogenous surfactant replacement via endotracheal tube remains foundational for surfactant deficiency. Synthetic formulations with peptide analogs of surfactant protein B absorb clinical trial investment previously directed toward porcine alternatives in ethical-restriction markets.
- Supportive Care:Thermal regulation, nutritional optimization, and infection control complement respiratory interventions.
- Mechanical Ventilation:Conventional and high-frequency oscillatory ventilation generates aftermarket revenue through consumables despite declining ventilator days per patient.
Steepest expansion trajectory: Preventive Care. Largest installed base: Pharmacotherapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for neonatal respiratory distress syndrome therapies concentrates in tertiary birthing centers across five major economies, each shaped by distinct regulatory pathways and care delivery architectures.
United States
Tertiary birthing center consolidation in California and Texas drives synthetic surfactant procurement through state-level perinatal quality collaboratives. FDA Pediatric Research Equity Act mandates compel manufacturers to generate neonatal-specific safety data rather than extrapolate from adult trials. Academic medical centers in Boston and San Francisco anchor peptide-analog formulation adoption where porcine-derived contraindications apply.
Germany
Heated humidified high-flow nasal cannula systems in Bavarian and North Rhine-Westphalian NICUs displace intubation-dependent surfactant administration. EMA orphan drug incentives accelerate biosimilar surfactant pathways, compressing development timelines for porcine-derived alternatives. The Frankfurt-Rhine-Main cluster concentrates device manufacturing partnerships with tertiary respiratory care networks.
India
Institutional delivery infrastructure expansion in Maharashtra and Tamil Nadu creates demand for surfactant cold-chain distribution partnerships. CDSCO pediatric study requirements extend approval timelines compared to adult indication pathways. Mumbai and Chennai tertiary neonatal networks aggregate procurement across public and private sector birthing centers.
Japan
PMDA pediatric investigation plan frameworks govern surfactant biosimilar submissions, requiring adolescent follow-up pharmacovigilance. The Kanto region around Tokyo concentrates Level III and IV NICU capacity, driving prophylactic protocol standardization. Osaka-based medical device manufacturers supply heated humidification systems that reduce mechanical ventilation dependency.
Saudi Arabia
Religious restrictions on porcine-derived therapies stimulate synthetic surfactant demand in Riyadh and Jeddah tertiary centers. SFDA pediatric drug approval pathways align with Gulf Cooperation Council harmonization initiatives. The Eastern Province industrial corridor anchors medical device distribution infrastructure serving high-risk neonatal networks.
Neonatal Respiratory Distress Syndrome Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers navigate volume-value tension between preventive and rescue surfactant protocols. The vendor base stratifies across animal-derived biologics, synthetic peptide formulations, and respiratory support devices. Three archetypes prevail: European biopharmaceutical incumbents with porcine supply chains, diversified healthcare conglomerates with synthetic R&D pipelines, and specialized device manufacturers with heated humidification platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves, particularly around minimally invasive delivery technologies.
Among biopharmaceutical specialists, Chiesi Farmaceutici S.p.A. and AbbVie Inc. exemplify divergent sourcing strategies—porcine-derived versus synthetic—while Fisher & Paykel Healthcare Limited occupies a position within the device-specialist tier. These three entities represent the competitive spectrum: animal-source biologics, ethical-restriction alternatives, and non-invasive respiratory support systems that threaten to displace traditional surfactant revenue models.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Chiesi Farmaceutici S.p.A. |
| Pfizer Inc. |
| Novartis AG |
| Merck & Co., Inc. |
| Drägerwerk AG & Co. KGaA |
| Fisher & Paykel Healthcare Limited |
| Medtronic plc |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Captive porcine sourcing through European biopharmaceutical incumbents anchors both supply security and pricing power across the surfactant category, with backward integration into animal husbandry operations insulating procurement from spot-market phospholipid volatility while supporting premium positioning against synthetic alternatives.
Pricing Analysis
Service-bundling separates cold-chain logistics and pharmacovigilance reporting from base pharmaceutical pricing, with United States tertiary centers negotiating multi-year contracts that wrap inventory management, temperature-controlled distribution, and adolescent follow-up data collection into per-dose fees. Three-tier pricing structure across prophylactic rescue, minimally invasive delivery, and biosimilar formulations reflects FDA Pediatric Research Equity Act compliance costs and EMA orphan exclusivity premiums. Cost compression in rescue surfactant runs through heated humidified high-flow nasal cannula substitution, which delays or eliminates administration in moderate prematurity. Price-sensitive buyers cluster in Indian state-level perinatal networks where institutional delivery expansion strains procurement budgets, while United States academic medical centers exhibit lowest sensitivity given bundled reimbursement through DRG codes.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia and Gulf Cooperation Council harmonization initiatives reshape sourcing toward synthetic peptide formulations that circumvent religious restrictions on porcine-derived inputs. Manufacturing concentrates in Italy, Germany, and the United States, with phospholipid extraction from porcine lung tissue and recombinant protein production in bacterial expression systems serving as dual raw material pillars. Single-source vulnerability permeates porcine-derived supply chains where European animal health regulations constrain herd expansion. Distribution runs through neonatal intensive care network purchasing cooperatives in California and Texas that aggregate demand across multi-hospital systems, displacing traditional pharmaceutical distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Pediatric Research Equity Act mandates function as a cost-of-compliance moat, with neonatal-specific safety trial requirements extending approval timelines and inflating development costs beyond the reach of undercapitalized entrants.
For Market Incumbents: Anchor synthetic surfactant R&D pipelines in peptide-analog formulations to defend against heated humidified high-flow nasal cannula displacement and capture ethical-restriction market share in Middle Eastern and South Asian geographies. Deepen backward integration into recombinant protein production capacity to reduce dependency on animal-source phospholipid suppliers. Fortify multi-vendor contract positioning through bundled pharmacovigilance services that extend real-world evidence generation timelines.
For New Entrants and Emerging Players: Underpenetrated institutional delivery infrastructure in Maharashtra and Tamil Nadu tertiary neonatal networks offers white-space expansion for surfactant cold-chain distribution partnerships. Minimally invasive surfactant therapy delivery devices present a penetrable equipment segment where regulatory pathways compress versus pharmaceutical approval timelines. Pursue hospital system partnerships through risk-sharing arrangements that align surfactant procurement costs with clinical outcome metrics.
For Investors and Strategic Acquirers: Exit pathways concentrate in device-specialist acquisitions by diversified healthcare conglomerates seeking respiratory platform expansion. Long-term viability favors manufacturers with dual porcine-synthetic formulation portfolios and established EMA pharmacovigilance infrastructure. Monitor biosimilar surfactant filing volumes at EMA as an inflection indicator for pricing compression velocity in European markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Minimally Invasive Delivery Device Development | Laryngeal mask airway and thin catheter systems expand eligible infant populations beyond intubation-dependent protocols. |
| Synthetic Surfactant Peptide Analog Investment | Recombinant surfactant protein B formulations capture ethical-restriction markets and compress animal-source dependency. |
| EMA Orphan Drug Pathway Acceleration | Extrapolated efficacy from pharmacodynamic endpoints shortens biosimilar surfactant approval timelines in Europe. |
| Neonatal Network Purchasing Cooperative Partnership | California and Texas perinatal quality collaboratives aggregate demand across multi-hospital systems. |
| Adolescent Pharmacovigilance Data Monetization | Longitudinal follow-up obligations under EMA frameworks generate real-world evidence assets for label expansion. |
Research Methodology
FDA 505(b)(2) submissions, EMA pediatric investigation plans, and ClinicalTrials.gov registries formed the secondary backbone, supplemented by formulary database audits and GPO contract disclosures. Primary interviews with neonatologists, hospital procurement managers, regulatory affairs leads, and surfactant manufacturing executives validated quantitative assumptions. Bottom-up patient volume modeling across gestational age strata triangulated against top-down pharmaceutical revenue estimates.
Historical trendline analysis of surfactant dosing volumes per live birth cohort informed projection frameworks across the analysis window. Segmentation dimensions encompassed product type, delivery mode, end-user facility tier, and treatment protocol positioning. CAGRs derived from slope-consistency tests against antenatal corticosteroid protocol penetration curves and mechanical ventilation day trajectories. Forecast inputs incorporated tertiary birthing center consolidation patterns and EMA biosimilar filing velocity.
Revisions become necessary when regulatory pathway modifications, surfactant administration technology substitutions, or neonatal intensive care network restructuring materialize outside modeled parameters. Forecasts reflect documented assumptions regarding prophylactic protocol adoption rates and porcine-source supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Europe Fetal and Neonatal Care Equipment Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
Neonatal Dialysis Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Perinatal Software Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market