
 Contact Type Liquid Handling Workstation Market | 2026-2036
Contact Type Liquid Handling Workstation Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Type Liquid Handling Workstation Market Insights
Switzerland's precision instrument manufacturing base is realigning toward higher-throughput contact type liquid handling architectures. Hamilton Robotics leverages its Mechatronics heritage to sustain leadership in robotic liquid handling platforms for clinical diagnostics. Tecan Group anchors its position through specialized OEM partnerships that extend reach into genomics workflows across European and North American laboratories.
Contact type liquid handling workstations are electromechanical systems that employ disposable tips or fixed probes to aspirate and dispense measured fluid volumes with positional accuracy typically within micrometer tolerances, serving primary functions in assay preparation, sample normalization, and reagent distribution across pharmaceutical and academic research environments. Automated workstations dominate the product type landscape due to labor cost pressures and reproducibility requirements in high-throughput screening applications, while microfluidics technology represents the fastest-growing segment as miniaturization reduces reagent consumption and enables massively parallel experimentation. Pharmaceutical companies constitute the largest end user category, though academic institutions are gaining share where NIH and NSF funding expands core facility automation budgets.
FDA 21 CFR Part 11 compliance requirements shape software and data integrity specifications for workstations deployed in regulated pharmaceutical quality control laboratories, while EMA GMP Annex 15 guidelines influence validation protocols for equipment qualification across European manufacturing sites. ISO 8655 standards for piston-operated volumetric apparatus establish international reference points for accuracy and precision claims that manufacturers must substantiate. Stakeholders should monitor evolving EPA and OSHA exposure limits for laboratory aerosols, as these will drive demand for enclosed workstation architectures with integrated HEPA filtration.
Market Dynamics
Pharmaceutical quality control laboratories are consolidating liquid handling infrastructure around FDA 21 CFR Part 11 validated platforms, compressing procurement cycles and elevating vendor qualification barriers for workstation manufacturers.
Growth Catalysts
- EMA GMP Annex 15:Equipment qualification mandates across European manufacturing sites are accelerating replacement of legacy manual pipetting systems with automated contact type architectures.
- Genomics workflows:Academic core facilities receiving NIH and NSF funding expansions are deploying higher-throughput liquid handling capacity to support CRISPR screening and next-generation sequencing sample prep.
- Microfluidics miniaturization:Reagent cost reduction of 90% per assay through nanoliter-scale dispensing is driving adoption in high-throughput screening operations at pharmaceutical discovery sites.
Market Restraints
- Precision component supply:Linear motor and optical encoder manufacturing concentrates in German and Swiss industrial clusters, creating geographic supply vulnerability for workstation assemblers.
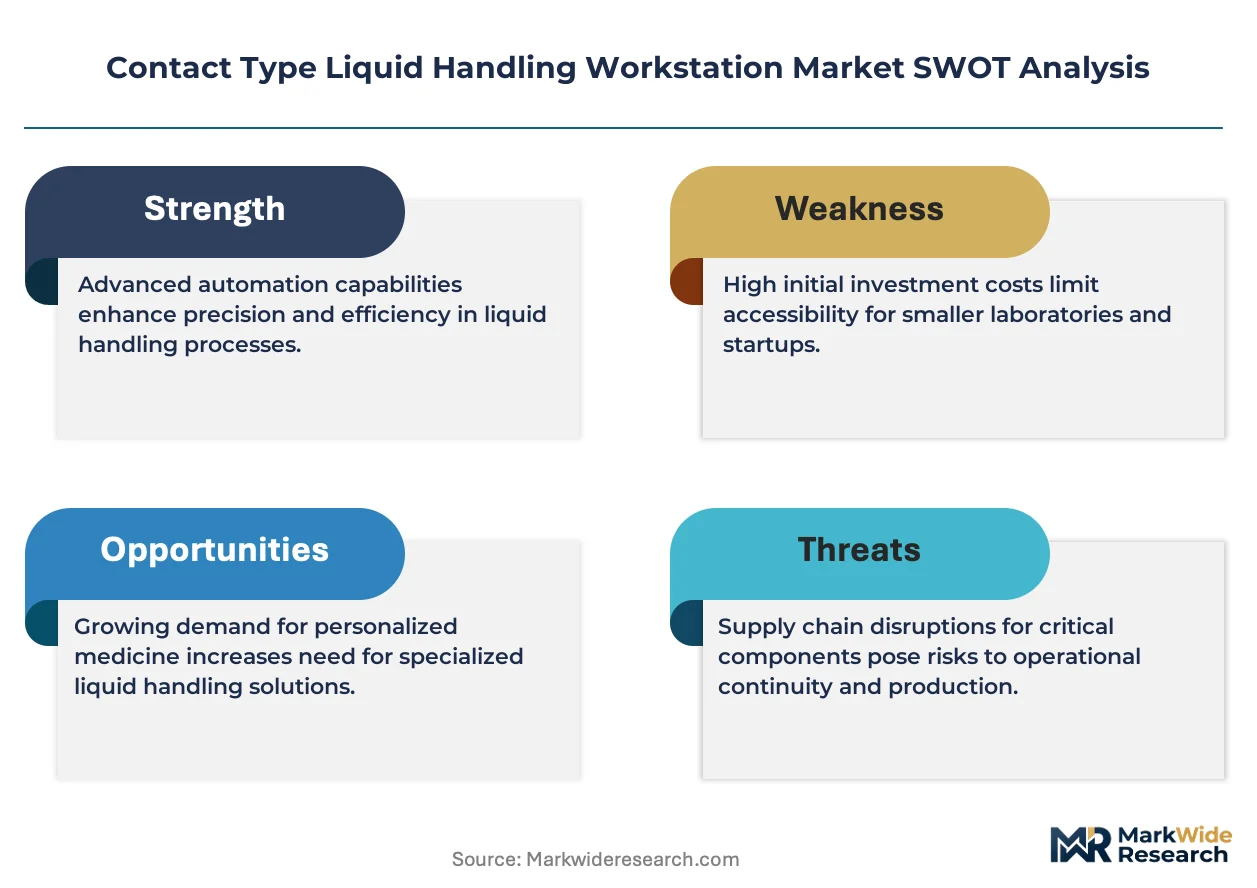
- Capital intensity:Automated platform installations require $150,000-$500,000 per unit with 18-24 month validation timelines, freezing budget cycles at mid-tier contract research organizations.
- Acoustic liquid handling:Tipless dispensers from Labcyte and EDC Biosystems are displacing contact type systems in compound management applications where cross-contamination risk dominates purchasing criteria.
Strategic Opportunities
- Cell therapy manufacturing:GMP-compliant closed-system liquid handling for CAR-T production represents an underpenetrated application with distinct regulatory requirements from research-grade equipment.
- EPA aerosol exposure limits:Tightening OSHA permissible exposure limits for laboratory airborne contaminants will mandate enclosed workstation architectures with integrated HEPA filtration, favoring integrated system vendors.
- Cloud-connected diagnostics:Convergence of liquid handling platforms with laboratory information management systems enables remote monitoring and predictive maintenance revenue streams.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional engineering combining precision mechanics, fluid dynamics, and embedded software faces acute hiring constraints in Boston and Basel metropolitan areas.
- ISO 8655 calibration:Piston-operated volumetric apparatus certification requires traceable gravimetric verification that extends field service deployment timelines and strains manufacturer service networks.
- Legacy integration:Pharmaceutical quality control laboratories maintain 15-20 year equipment lifecycles, forcing workstation vendors to support obsolete communication protocols alongside modern API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Type Liquid Handling Workstation Market |
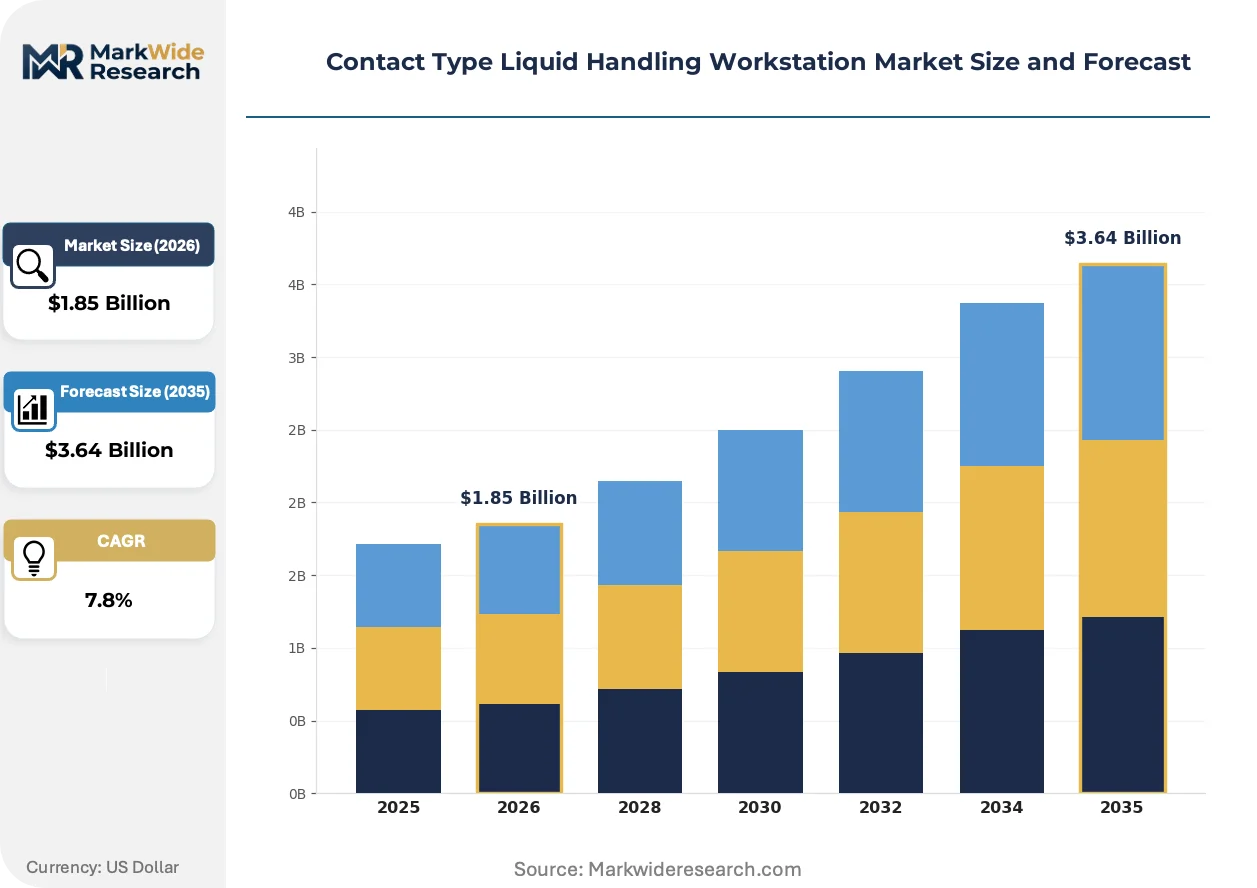
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Workstation, Manual Workstation, Semi-Automated Workstation, Multi-Channel Pipette End User: Pharmaceutical Companies, Academic Institutions, Clinical Laboratories, Research Facilities Application: Drug Discovery, Genomics, Proteomics, High-Throughput Screening Technology: Robotic Liquid Handling, Microfluidics, Valved Liquid Handling, Touchless Dispensing |
| Companies Covered | Hamilton Robotics, Beckman Coulter Lifesciences, Tecan Group, PerkinElmer, Agilent Technologies, Eppendorf, Thermo Fisher Scientific, SPT Labtech, MGI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Type Liquid Handling Workstation Market Trends and Innovations
Contact type liquid handling architectures are converging with digital laboratory infrastructure, compressing the boundary between physical sample processing and computational experiment design. Three developments are restructuring competitive positioning.
Modular deck configurations are unifying previously separate sample prep, nucleic acid extraction, and analytical transfer operations onto single robotic platforms. Pharmaceutical discovery groups in Massachusetts and California are standardizing on these unified systems to reduce footprint and technician training burden. The structural consequence is consolidation of vendor relationships as multi-function platforms displace point solutions.
EMA MDR requirements for in-vitro diagnostic device manufacturing are mandating enhanced traceability and audit trail capabilities for liquid handling software. European contract manufacturers are retrofitting existing installations with upgraded data integrity modules rather than replacing hardware. In-vitro diagnostic kit producers face the steepest compliance burden, with Swiss and German notified bodies enforcing the most stringent interpretation of software lifecycle documentation.
Service unbundling is fragmenting traditional capital equipment purchasing into reagent rental and per-run consumption models. Academic core facilities with constrained capital budgets are adopting these arrangements most aggressively. The shift is most visible in NIH-funded institutions where indirect cost recovery structures favor operational expenditures over equipment depreciation.
Contact Type Liquid Handling Workstation Market Segmentation
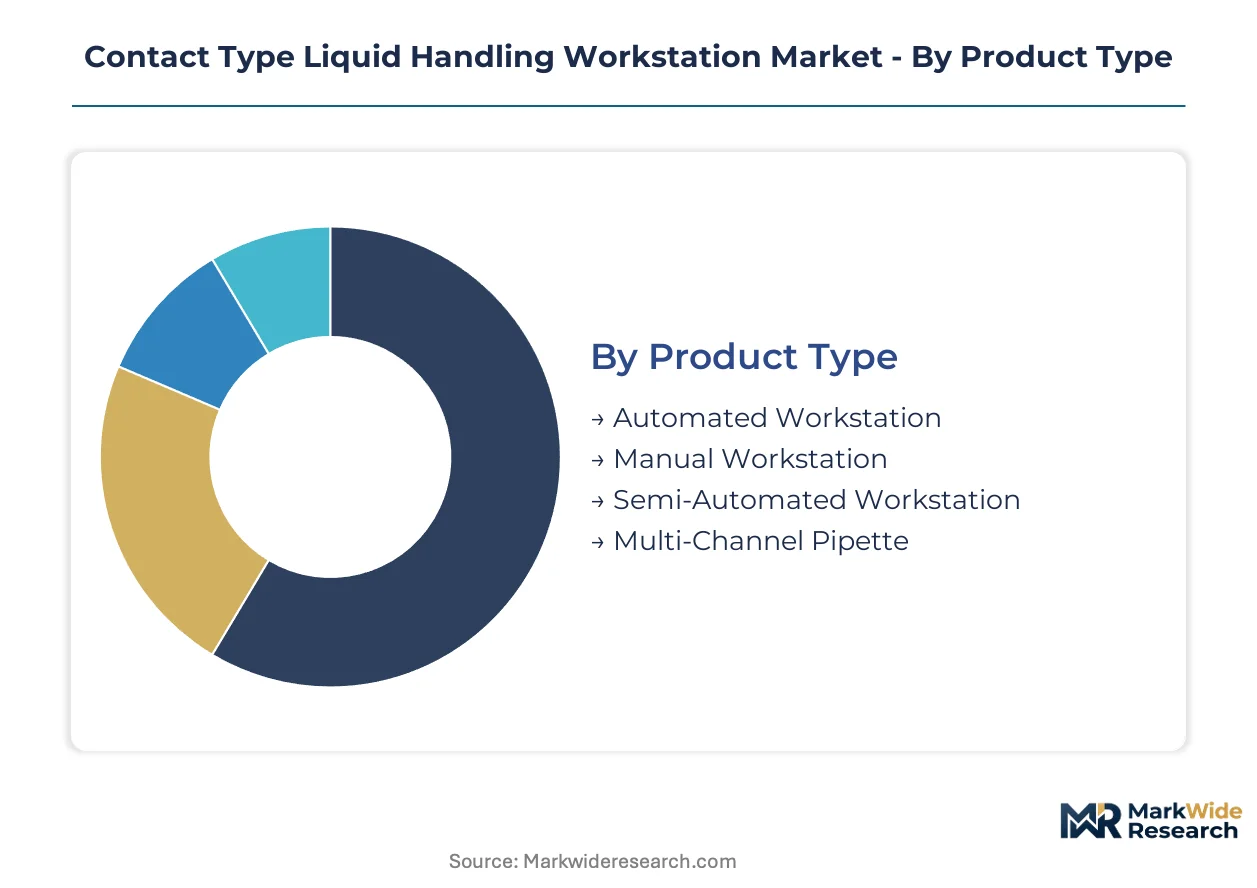
Segmentation in contact type liquid handling workstations reveals how regulatory validation requirements, throughput demands, and capital constraints fragment purchasing behavior across pharmaceutical, academic, and clinical environments. Understanding these divides exposes where FDA 21 CFR Part 11 compliance, EMA GMP Annex 15 qualification, and research-grade flexibility create distinct product-market fit profiles.
Product Type:
FDA 21 CFR Part 11 and EMA GMP Annex 15 impose divergent software validation and equipment qualification burdens across workstation categories, with automated platforms facing the steepest documentation requirements for pharmaceutical quality control deployment.
- Automated Workstation:Electromechanical systems integrate robotic arms, precision pipetting heads, and deck configurations for walk-away operation in high-throughput screening. Pharmaceutical companies in Massachusetts and California are consolidating procurement around these platforms to compress assay preparation timelines and eliminate technician-to-technician variability in drug discovery pipelines.
- Manual Workstation:Benchtop units with electronic piston control and programmable step sequences assist technicians in repetitive pipetting tasks without full robotic integration. Academic core facilities with constrained capital budgets favor these systems where NIH funding structures prioritize operational expenditures over equipment depreciation schedules.
- Semi-Automated Workstation:Hybrid architectures combine user-directed plate handling with automated tip loading and liquid-level sensing for medium-throughput applications.
- Multi-Channel Pipette:Handheld or stand-mounted electronic dispensers with 8- to 384-channel configurations address sample normalization workflows in genomics laboratories.
Leading the category by volume: Automated Workstation. Growing fastest: Multi-Channel Pipette.
End User:
Capital intensity and validation timelines create sharp purchasing stratification, with pharmaceutical quality control laboratories absorbing 18-24 month qualification periods that freeze budget cycles at contract research organizations.
- Pharmaceutical Companies:Discovery groups and quality control divisions deploy validated platforms for compound management, assay preparation, and release testing under FDA and EMA oversight. Genentech, Novartis, and Roche facilities in Basel and South San Francisco anchor demand concentration where GMP compliance mandates automated traceability.
- Academic Institutions:Core facilities receiving NIH and NSF instrumentation grants prioritize modular systems with reagent rental arrangements to circumvent capital expenditure constraints. Harvard, Stanford, and ETH Zurich automation centers are expanding liquid handling capacity to support CRISPR screening and next-generation sequencing sample prep workflows.
- Clinical Laboratories:Diagnostic service providers require CLIA-compliant platforms with audit trail capabilities for patient sample processing.
- Research Facilities:Government and private institutes without clinical diagnostic mandates favor flexible configurations adaptable across proteomics, metabolomics, and cell biology applications.
Volume concentration: Pharmaceutical Companies. Steepest expansion trajectory: Academic Institutions.
Application:
Reagent cost structures and sample throughput requirements determine where nanoliter-scale precision justifies platform investment versus manual pipetting retention.
- Drug Discovery:High-throughput screening operations in pharmaceutical lead optimization consume the largest installed base of contact type workstations. Bristol Myers Squibb and Merck facilities in New Jersey and Pennsylvania are standardizing on unified sample prep-to-assay platforms to reduce technician training burden and footprint.
- Genomics:Next-generation sequencing library preparation and CRISPR screening demand 96- and 384-format compatibility with integrated thermocycler and magnetic bead handling. Broad Institute and Sanger Centre core facilities are deploying specialized configurations for massively parallel nucleic acid processing.
- Proteomics:Sample fractionation and mass spectrometry front-end preparation require low-volume accuracy for precious clinical specimens.
- High-Throughput Screening:Compound management and biochemical assay miniaturization drive tip consumption volumes that favor integrated stacker and waste management systems.
Installed base leader: Drug Discovery. Climbing the fastest: Genomics.
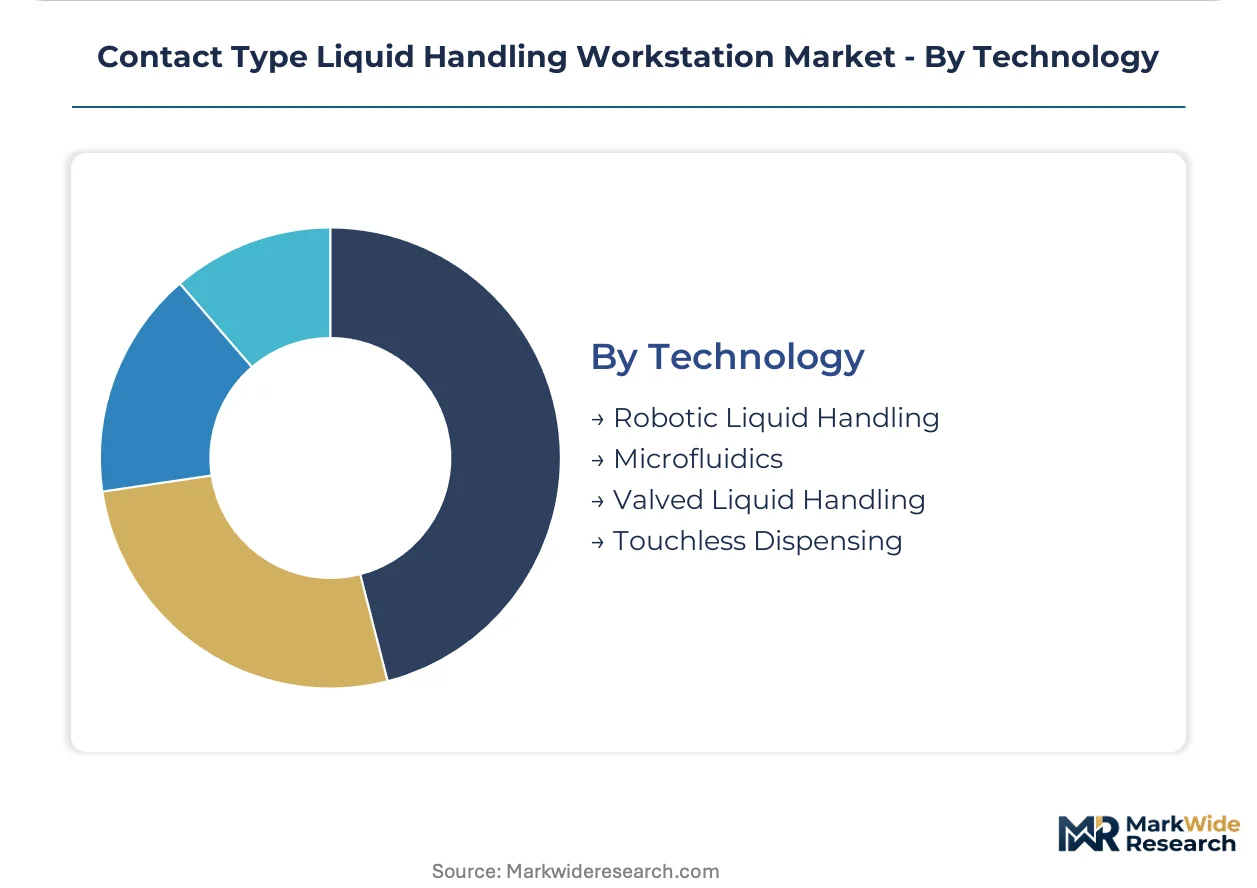
Technology:
Competitive displacement risk from acoustic and inkjet dispensing architectures is concentrating R&D investment in microfluidics and touchless methods that eliminate cross-contamination pathways.
- Robotic Liquid Handling:Cartesian coordinate systems with linear motor drives and optical encoder feedback achieve positional accuracy within micrometer tolerances for fixed-probe and disposable-tip architectures. Hamilton Robotics and Tecan Group manufacturing in Switzerland and Germany sustain technology leadership through precision mechatronics integration.
- Microfluidics:Integrated channel networks fabricated in glass, polymer, or silicon enable nanoliter-scale reagent consumption and massively parallel experimentation. Illumina and 10x Genomics partnerships with workstation vendors are accelerating adoption in single-cell genomics workflows where reagent cost reduction exceeds 90% per assay.
- Valved Liquid Handling:Rotary and solenoid valve manifolds provide positive displacement dispensing without disposable tips for high-viscosity or volatile reagents.
- Touchless Dispensing:Inkjet, acoustic, and piezoelectric methods eliminate physical probe contact with sample or reagent.
Revenue concentration: Robotic Liquid Handling. Gaining share fastest: Microfluidics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision linear motor and optical encoder manufacturing clusters in southern Germany and northern Switzerland anchor the geographic supply base for contact type liquid handling workstation assembly. Pharmaceutical R&D investment concentrates in Massachusetts, California, and Basel where GMP-compliant automation demand is strongest.
United States
FDA 21 CFR Part 11 validation requirements and NIH funding expansions drive pharmaceutical and academic procurement respectively. The EPA and OSHA are tightening permissible exposure limits for laboratory aerosols, mandating enclosed workstation architectures. Greater Boston and South San Francisco host Genentech, Merck, and emerging biotech automation centers where GMP-compliant platforms anchor drug discovery infrastructure.
Germany
EMA GMP Annex 15 equipment qualification mandates accelerate replacement of manual pipetting systems in pharmaceutical quality control laboratories. The country's national pharmaceutical regulator enforces stringent software lifecycle documentation for in-vitro diagnostic manufacturing. Baden-Württemberg and Bavaria concentrate precision mechatronics suppliers including linear motor fabricators and optical encoder specialists that feed workstation assembly operations.
Switzerland
Swissmedic oversight of clinical diagnostics manufacturing elevates data integrity requirements for liquid handling software deployed in regulated environments. Hamilton Robotics leverages its Mechatronics heritage from Bonaduz while Tecan Group anchors its position through specialized OEM partnerships. The Zurich-Basel corridor sustains precision instrument manufacturing density unmatched outside southern Germany.
China
NMPA regulatory harmonization with international GMP standards is expanding domestic pharmaceutical automation demand beyond research-grade equipment. The country's national pharmaceutical regulator is tightening software validation requirements for diagnostic device manufacturing. Yangtze River Delta biotech clusters in Shanghai and Suzhou are deploying higher-throughput liquid handling capacity for CRISPR screening and next-generation sequencing sample preparation.
United Kingdom
MHRA post-Brexit regulatory autonomy is maintaining alignment with EMA GMP Annex 15 equipment qualification standards for pharmaceutical manufacturing. The Sanger Centre and Broad Institute partnerships are expanding academic core facility automation budgets for genomics workflows. Cambridge and Oxford metropolitan areas concentrate CRISPR screening operations that demand 384-format liquid handling compatibility with integrated thermocycler modules.
Contact Type Liquid Handling Workstation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microfluidics miniaturization and cell therapy manufacturing applications. The vendor base stratifies across three tiers: precision mechatronics specialists with Swiss and German manufacturing heritage, diversified life science conglomerates with broad automation portfolios, and emerging specialists in nanoliter-scale dispensing architectures. Dominant competitive moves include strategic OEM partnerships extending reach into genomics workflows and service unbundling into reagent rental and per-run consumption models that circumvent academic capital constraints.
Within the precision mechatronics tier, Hamilton Robotics and Tecan Group exemplify archetypes anchored in Swiss manufacturing heritage. Beckman Coulter Lifesciences occupies a position among diversified life science conglomerates with broad automation portfolios. These three entities represent distinct strategic postures: Hamilton Robotics leverages mechatronics integration from Bonaduz, Tecan Group anchors through specialized OEM partnerships across European and North American laboratories, and Beckman Coulter Lifesciences exemplifies the scale-driven conglomerate model with extensive service network coverage.
| Leading Market Players |
|---|
| Hamilton Robotics |
| Beckman Coulter Lifesciences |
| Tecan Group |
| PerkinElmer |
| Agilent Technologies |
| Eppendorf |
| Thermo Fisher Scientific |
| SPT Labtech |
| MGI |
| Others |
Pricing and Supply Chain Analysis
Captive precision mechatronics integration in Swiss and German manufacturing clusters anchors both supply security and pricing power for workstation assemblers, with Hamilton Robotics and Tecan Group leveraging in-house linear motor fabrication to defend margin structures against commoditization pressures from Asian contract manufacturers.
Pricing Analysis
Warranty and field service bundling separates premium-tier vendors from unbundled research-grade competitors, with FDA 21 CFR Part 11 validation packages commanding substantial premiums over academic configurations. Three-tier pricing structure across GMP-validated, research-grade, and entry-level manual systems reflects certification burden and software documentation depth. Cost compression in mid-tier automated platforms is intensifying because acoustic liquid handling substitutes erode contact-type volumes in compound management. Academic core facilities exhibit highest price sensitivity where NIH indirect cost structures favor operational expenditure models.
Supply Chain Analysis
Mechatronics engineering talent scarcity in Boston and Basel metropolitan areas constrains production scaling for precision workstation assembly. Component sourcing draws from German linear motor fabricators, Swiss optical encoder specialists, and Japanese precision bearing suppliers. Single-source vulnerability concentrates in Baden-Württemberg linear drive manufacturing where specialized tooling limits rapid supplier switching. Distribution runs through direct field service organizations for GMP-compliant installations and laboratory distributor networks for research-grade systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contact type liquid handling workstation market is executing a technology-transition phase where microfluidics miniaturization displaces legacy robotic pipetting architectures in genomics and single-cell applications.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Accelerate FDA 21 CFR Part 11 and EMA GMP Annex 15 validation documentation to elevate vendor qualification barriers against emerging acoustic liquid handling competitors. Deepen backward integration into precision linear motor fabrication to secure component supply against German and Swiss manufacturing bottlenecks. For New Entrants and Emerging Players: Launch via reagent rental and per-run consumption models to circumvent academic capital expenditure constraints. Target NIH-funded core facilities in Massachusetts and California where operational expenditure structures favor service-based purchasing over equipment depreciation. Prioritize cell therapy manufacturing applications where GMP-compliant closed-system architectures remain underpenetrated by established vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in precision mechatronics specialists with Swiss manufacturing heritage and established OEM partnership networks. Long-term viability hinges on sustained R&D differentiation against touchless dispensing substitutes. Watch EPA and OSHA aerosol exposure limit tightening as the signal indicating accelerated demand for enclosed workstation architectures with integrated HEPA filtration.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidics Platform Development | Partnerships with Illumina and 10x Genomics accelerate single-cell genomics workflow penetration. |
| GMP Validation Documentation Investment | FDA 21 CFR Part 11 compliance packages elevate barriers against research-grade competitors in pharmaceutical QC. |
| Service Unbundling into Consumption Models | Reagent rental arrangements unlock NIH-funded academic core facilities with constrained capital budgets. |
| Precision Component Backward Integration | In-house linear motor fabrication secures supply against German and Swiss manufacturing cluster bottlenecks. |
| Cloud-Connected Diagnostics Integration | Laboratory information management system convergence enables predictive maintenance revenue streams. |
Research Methodology
FDA 510(k) filings, EMA qualification documentation, and NIH instrumentation grant databases formed the secondary backbone, supplemented by customs records for precision mechatronics component trade flows. Primary interviews with pharmaceutical automation directors, academic core facility managers, GMP compliance officers, and laboratory distributor principals validated installed base estimates and procurement timeline assumptions. Bottom-up triangulation across vendor shipment data and top-down cross-check against pharmaceutical R&D capital expenditure disclosures anchored volume and value estimates.
Bottom-up modeling segmented the market by product type, end user, application, and technology across the projection horizon, with robotic liquid handling, microfluidics, and touchless dispensing treated as distinct competitive architectures. CAGRs were derived from regression analysis of historical pharmaceutical automation investment cycles and academic funding trajectories. Forecast inputs incorporated EMA MDR implementation timelines for in-vitro diagnostic manufacturing and EPA aerosol exposure limit revision schedules.
Regulatory harmonization delays, precision component supply disruptions, and acoustic liquid handling substitution acceleration are the dominant revision risks that could compress contact-type workstation demand. Forecasts reflect documented assumptions regarding NIH and NSF funding continuity, GMP validation timeline standardization, and Swiss-German mechatronics manufacturing capacity expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Asia-Pacific Medical Device Reprocessing Market
Medical Equipment
ECG Equipment Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Medical Filter Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Tanning Units Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Global Portable Beds Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Dialysis Equipment Market