
 Neonatal Phototherapy Devices Market | 2026-2036
Neonatal Phototherapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal Phototherapy Devices Market Outlook
Multi-source procurement for LED emitters and optical components is decoupling from legacy single-vendor dependencies among tier-one manufacturers. GE Healthcare leverages captive semiconductor partnerships to secure wavelength-stable blue LEDs for bilirubin breakdown. Koninklijke Philips N.V. anchors its position through integrated photodiode feedback systems that auto-adjust irradiance. Drägerwerk AG & Co. KGaA competes on modular platform architectures that accommodate bedside and incubator-mounted configurations.
Neonatal phototherapy devices emit therapeutic light in the blue spectrum range to convert unconjugated bilirubin into water-soluble isomers excreted via infant hepatic and renal pathways, with LED systems typically delivering 430-490 nm peak wavelength at irradiance levels of 30-50 μW/cm²/nm. LED-based systems dominate installed base economics due to 50,000-hour emitter lifespan and minimal thermal load versus legacy fluorescent alternatives. Hospitals constitute the primary end-user channel where capital equipment procurement cycles and bundled service contracts concentrate margin pools, while portable configurations represent the fastest-growing technology segment as point-of-care models expand into secondary birthing centers.
FDA 510(k) clearance and CE marking under the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for manufacturers seeking commercial access. ISO 9001 and IEC 60601-1-2 electromagnetic compatibility standards further constrain design architectures for devices deployed in electrically sensitive neonatal intensive care environments. Stakeholders must monitor evolving photobiological safety standards and reimbursement parity between inpatient and outpatient phototherapy delivery models.
Market Dynamics
LED emitter supply consolidation and wavelength-precision requirements are forcing hospital procurement teams to requalify vendor relationships, with bilirubin-specific blue spectrum stability emerging as the decisive technical discriminator in capital equipment tenders.
Growth Catalysts
- EU Medical Device Regulation (MDR) enforcement:Stricter clinical evidence requirements for infant safety equipment are accelerating replacement cycles of legacy fluorescent systems in German and French neonatal intensive care units.
- Point-of-care expansion:Secondary birthing centers in Japan and the United States are adopting portable LED configurations to reduce inpatient transfer volumes for hyperbilirubinemia cases.
- Bilirubin metalloporphyrin research:Adjunct phototherapy protocols combining light treatment with pharmaceutical interventions are extending device utilization rates in academic medical centers.
Market Restraints
- Blue LED die supply concentration:Epitaxial wafer production for medical-grade emitters clusters in East Asian foundries, exposing tier-one device manufacturers to single-source vulnerability.
- FDA 510(k) timeline extension:Substantial equivalence determinations for novel optical feedback systems now average 18-24 months, compressing product launch windows.
- Fluorescent phototherapy residual base:Budget-constrained municipal hospitals in Southern Europe retain functional legacy installations, delaying LED upgrade cycles.
Strategic Opportunities
- Home phototherapy reimbursement parity:United States Medicaid expansion of outpatient bilirubin treatment coverage is creating demand for prescription-grade portable units.
- Integrated photodiode-thermistor convergence:Multi-sensor platforms combining irradiance monitoring with thermal load management are opening premium pricing tiers in Japanese tertiary hospitals.
- Rural India deployment:District hospital networks under the National Health Mission represent unserved volume for solar-battery hybrid phototherapy systems.
Industry Challenges
- IEC 60601-1-2 electromagnetic compatibility certification:Testing protocols for electrically sensitive neonatal environments require specialized anechoic chamber capacity that bottlenecks product release schedules.
- Optical calibration technician scarcity:Field service networks lack personnel trained in spectroradiometer verification of 430-490 nm peak wavelength maintenance across 50,000-hour LED lifespans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal Phototherapy Devices Market |
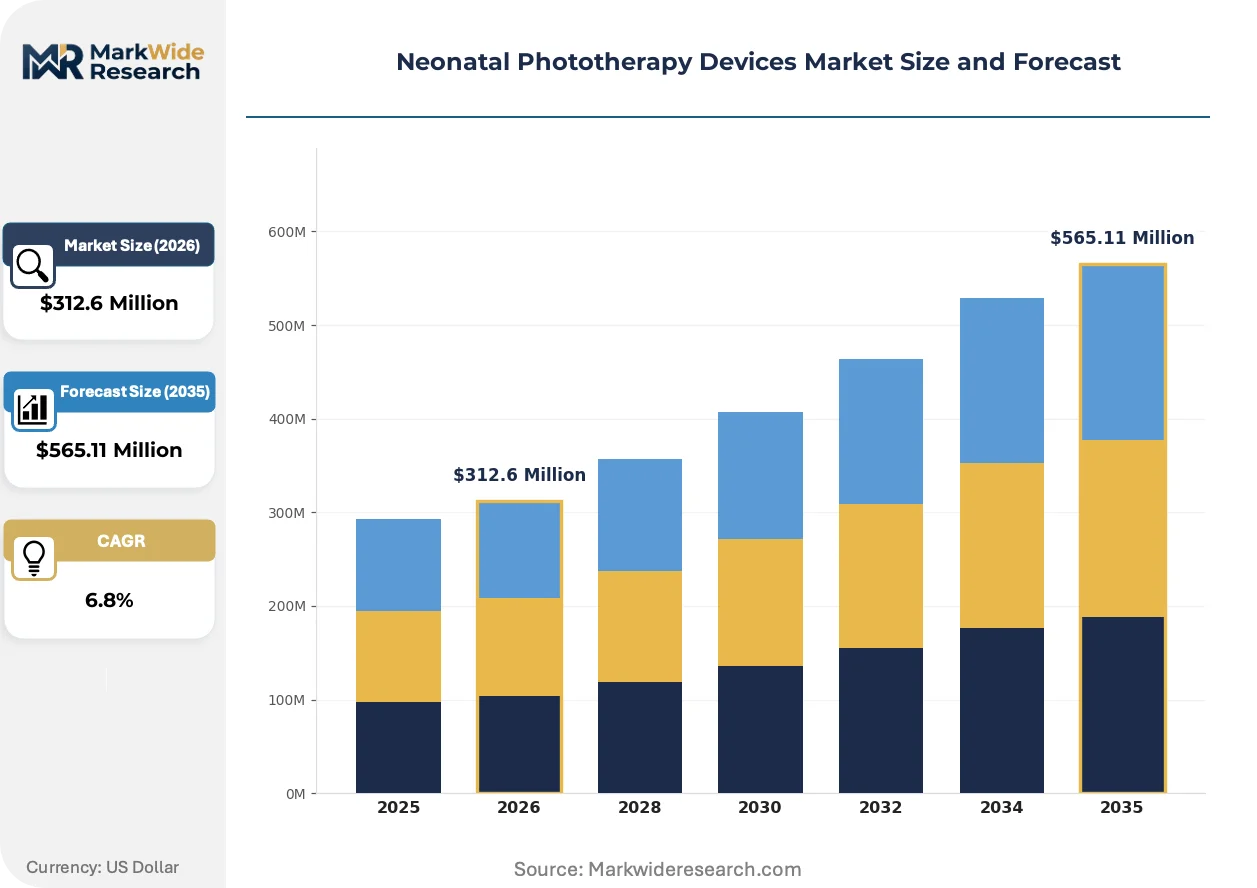
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Fiber Optic Application: Jaundice Treatment, Phototherapy for Preterm Infants, Skin Conditions, Diagnostic Procedures End User: Hospitals, Clinics, Home Care, Research Institutions Technology: Conventional, Advanced, Portable, Combination Therapy |
| Companies Covered | GE Healthcare, Natus Medical, Atom Medical Corporation, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., Phoenix Medical Systems Pvt. Ltd., Herbert Waldmann GmbH & Co. KG, Ibis Medical Equipment and Systems Pvt Ltd, Weyer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal Phototherapy Devices Market Strategic Shifts
Spectral engineering and closed-loop irradiance control are redefining therapeutic efficacy benchmarks, compressing the gap between consumer-grade light sources and clinical phototherapy systems.
Fiber-coupled LED arrays with remote emitter architecture are electrifying thermal management design in incubator-integrated phototherapy systems. Neonatal intensive care units in German university hospitals are specifying these configurations to eliminate radiant heat load on thermally vulnerable infants. The technology is electrifying competitive positioning by decoupling optical output from bedside footprint constraints.
CE marking under the EU Medical Device Regulation now mandates post-market clinical follow-up for phototherapy devices, compelling manufacturers to maintain European adverse event registries. This surveillance obligation is restructuring service contract economics toward multi-year performance guarantees. Pediatric device divisions are responding by embedding wireless connectivity for remote irradiance logging in new product architectures.
Hospital procurement committees are unbundling after-sales service from capital equipment purchases, forcing OEMs to compete with independent biomedical service organizations. This disintermediation is most pronounced in United States health system consolidation, where centralized clinical engineering departments negotiate multi-hospital maintenance agreements. Device manufacturers are countering with outcome-based uptime guarantees tied to spare parts subscription models.
Neonatal Phototherapy Devices Market Segmentation
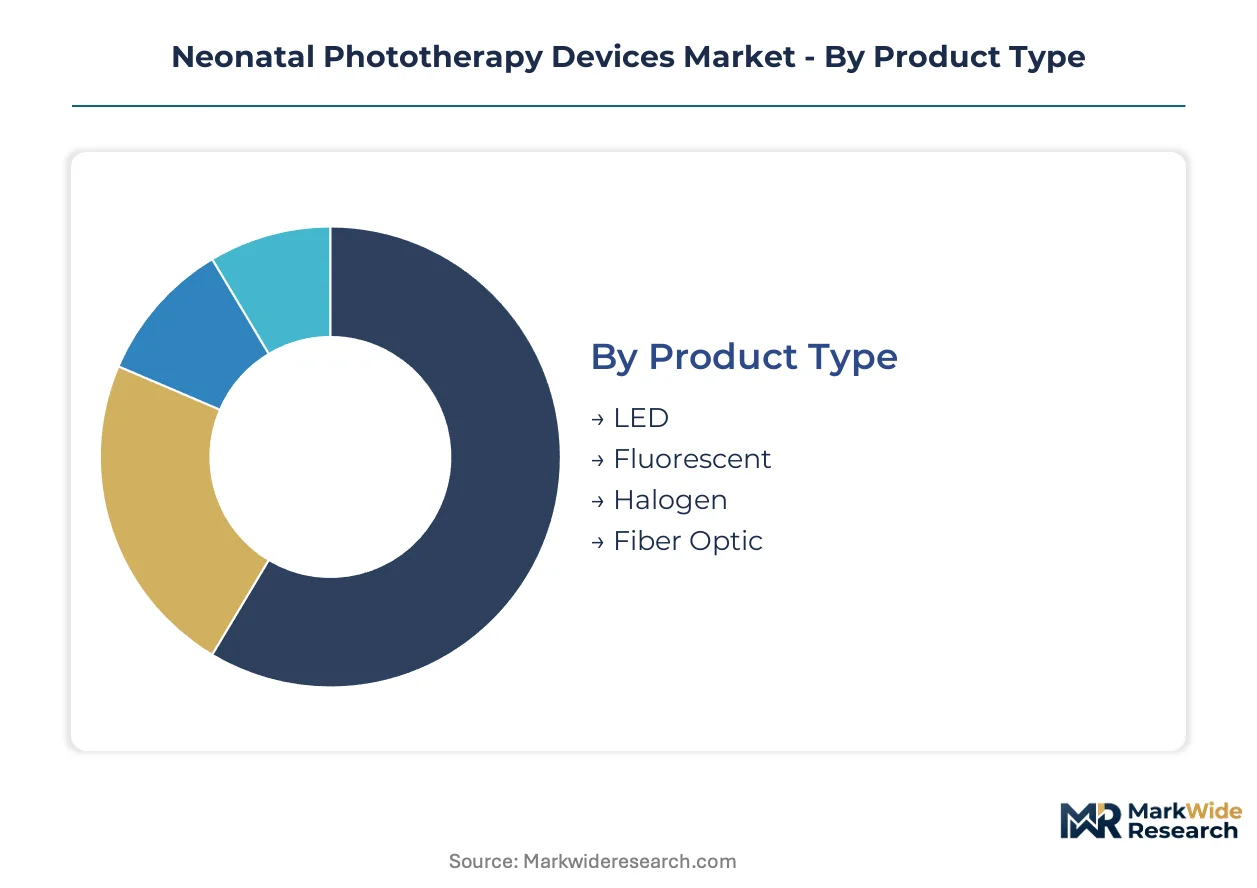
Segmentation in neonatal phototherapy devices maps directly to procurement decision hierarchies in hospital neonatal intensive care units. LED upgrade cycles, portable configuration demand, and reimbursement parity between inpatient and outpatient settings create divergent margin pools across product and application categories.
Product Type:
Replacement cycles for legacy emitter technologies are accelerating as wavelength precision becomes the decisive tender discriminator in capital equipment procurement.
- LED:Solid-state emitters deliver 430-490 nm peak wavelength with 50,000-hour operational lifespan and minimal thermal load. German university hospitals specify these systems for incubator-integrated configurations, driven by EU MDR enforcement accelerating fluorescent phase-out.
- Fluorescent:Legacy tube-based systems dominate residual installed base in budget-constrained municipal hospitals across Southern Europe. Replacement demand concentrates where CE marking timelines and clinical evidence requirements force compliance-driven upgrades.
- Halogen:Incandescent filament technology retains niche presence in low-resource settings requiring minimal capital outlay. Field service networks in rural India maintain these systems under National Health Mission equipment pools.
- Fiber Optic:Remote emitter architecture decouples optical output from bedside footprint, eliminating radiant heat load on thermally vulnerable infants. Japanese tertiary hospitals specify fiber-coupled arrays for photodiode-thermistor convergence platforms.
LED systems sit at the top of the volume ranking, with fiber optic configurations climbing the fastest as thermal management specifications tighten in academic medical centers.
Application:
Clinical protocol diversification is extending device utilization rates beyond standard-of-care hyperbilirubinemia management.
- Jaundice Treatment:Core therapeutic indication targeting unconjugated bilirubin conversion via blue spectrum irradiation. United States Medicaid reimbursement expansion for outpatient treatment is reshaping demand toward portable configurations.
- Phototherapy for Preterm Infants:Specialized protocols for low-birth-weight neonates requiring precise irradiance control and thermal load management. Integrated photodiode feedback systems auto-adjust output in Japanese neonatal intensive care units.
- Skin Conditions:Adjunct applications for neonatal dermatological conditions extend capital equipment depreciation schedules. Research institutions in France explore metalloporphyrin combination protocols.
- Diagnostic Procedures:Bilirubin quantification and therapeutic response monitoring integrate with electronic health record systems. Wireless connectivity for remote irradiance logging satisfies EU MDR post-market surveillance mandates.
Jaundice treatment commands the largest installed base, though phototherapy for preterm infants shows the steepest expansion trajectory as gestational age-specific protocols proliferate.
End User:
Procurement authority concentration varies sharply across care settings, with centralized clinical engineering departments reshaping vendor relationships.
- Hospitals:Primary channel where capital equipment cycles and bundled service contracts concentrate margin pools. United States health system consolidation drives multi-hospital maintenance agreement negotiations.
- Clinics:Secondary birthing centers in Japan and the United States adopt portable LED configurations to reduce inpatient transfer volumes for hyperbilirubinemia cases.
- Home Care:Prescription-grade portable units gain traction where reimbursement parity emerges between inpatient and outpatient phototherapy delivery models.
- Research Institutions:Academic medical centers drive adjunct protocol development combining light treatment with pharmaceutical interventions, extending device utilization rates.
Hospitals retain dominant procurement volume, while home care gains share fastest as Medicaid coverage expansion reconfigures care delivery geography.
Technology:
Platform architecture decisions determine competitive positioning across thermal management, electromagnetic compatibility, and connectivity specifications.
- Conventional:Fixed-installation systems with manual irradiance adjustment dominate legacy installed base. IEC 60601-1-2 certification bottlenecks constrain product release schedules for electromagnetic compatibility testing.
- Advanced:Closed-loop irradiance control with spectral engineering redefines therapeutic efficacy benchmarks. FDA 510(k) timeline extension for novel optical feedback systems compresses launch windows.
- Portable:Point-of-care configurations represent the fastest-growing technology segment as secondary birthing centers expand phototherapy capacity. Solar-battery hybrid systems target district hospital networks in rural India.
- Combination Therapy:Multi-modal platforms integrating phototherapy with pharmaceutical delivery systems command premium pricing in tertiary academic settings.
Conventional platforms anchor installed base economics, with portable systems expanding most quickly across decentralized care delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals anchor procurement sophistication for neonatal phototherapy systems, with wavelength-precision specifications cascading to secondary markets in France and Japan. Regulatory enforcement patterns in these clusters determine replacement cycle velocity across hospital neonatal intensive care units worldwide.
United States
Medicaid reimbursement expansion for outpatient bilirubin treatment is reshaping demand geography toward portable configurations. FDA 510(k) clearance timelines now stretch to 18-24 months for novel optical feedback systems, compressing product launch windows for manufacturers. Health system consolidation in Texas and California drives multi-hospital maintenance agreement negotiations through centralized clinical engineering departments.
Germany
EU Medical Device Regulation enforcement accelerates fluorescent system phase-out in university hospital neonatal intensive care units across Bavaria and North Rhine-Westphalia. CE marking mandates post-market clinical follow-up, compelling manufacturers to maintain European adverse event registries. Berlin-based pediatric device divisions embed wireless connectivity for remote irradiance logging to satisfy surveillance obligations.
Japan
Secondary birthing centers in Kanto and Kansai regions adopt portable LED configurations to reduce inpatient transfer volumes for hyperbilirubinemia cases. METI standards for medical electrical equipment constrain electromagnetic compatibility design architectures. Tokyo tertiary hospitals specify fiber-coupled arrays with integrated photodiode-thermistor convergence platforms for thermal load management.
India
District hospital networks under the National Health Mission represent unserved volume for solar-battery hybrid phototherapy systems in Maharashtra and Tamil Nadu. CDSCO medical device registration requirements are tightening for infant safety equipment imported from East Asian manufacturing clusters. Bangalore-based equipment pools maintain legacy halogen systems in rural deployment configurations.
France
ANSM pharmacovigilance integration with medical device surveillance creates dual regulatory exposure for phototherapy system manufacturers serving Paris and Lyon academic medical centers. Research institutions in Île-de-France explore metalloporphyrin combination protocols extending device utilization rates. Provence-Alpes-Côte d'Azur municipal hospitals retain fluorescent installations where budget constraints delay LED upgrade cycles.
Neonatal Phototherapy Devices Market Competitive Environment
Global majors compete with regional champions across wavelength-precision technology and service contract economics. Market structure tilts toward consolidated procurement authority where hospital system consolidation concentrates vendor negotiations. Three archetypes dominate: diversified medical technology conglomerates with captive semiconductor partnerships, specialized neonatal equipment fabricators with modular platform architectures, and regional champions with cost-optimized configurations for emerging markets. Competitive moves concentrate on outcome-based uptime guarantees and multi-year performance commitments tied to spare parts subscription models.
Among diversified conglomerates, GE Healthcare and Koninklijke Philips N.V. occupy positions anchored by integrated feedback systems and wavelength-stable emitter supply chains. Drägerwerk AG & Co. KGaA exemplifies the specialized fabricator archetype through modular platform architectures. Regional champions including Phoenix Medical Systems Pvt. Ltd. and Ibis Medical Equipment and Systems Pvt Ltd represent cost-optimized configurations targeting district hospital networks in South Asia. Herbert Waldmann GmbH & Co. KG and Weyer GmbH sit within the mid-tier specialist segment serving European procurement specifications.
| Leading Market Players |
|---|
| GE Healthcare |
| Natus Medical |
| Atom Medical Corporation |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| Phoenix Medical Systems Pvt. Ltd. |
| Herbert Waldmann GmbH & Co. KG |
| Ibis Medical Equipment and Systems Pvt Ltd |
| Weyer GmbH |
| Others |
Value Chain & Pricing Dynamics
EU MDR post-market surveillance obligations gate qualified supply access and premium-tier pricing power, as manufacturers embedding wireless connectivity for remote irradiance logging capture service-contract premiums while budget-tier competitors face exclusion from German university hospital tenders.
Pricing Analysis
Blue LED die cost pass-through from East Asian epitaxial wafer foundries structures tiered pricing across the market. Three-tier pricing separates FDA-cleared systems with integrated photodiode feedback from CE-marked standard configurations and uncertified economy units. Pricing pressure stems from health system consolidation in the United States, where centralized clinical engineering departments negotiate multi-hospital maintenance agreements. Municipal hospitals in Southern Europe exhibit highest price sensitivity, while Japanese tertiary hospitals accept premium positioning for thermal management specifications.
Supply Chain Analysis
India's PLI scheme for medical electronics and domestic-content mandates in National Health Mission procurement are reshaping sourcing for solar-battery hybrid configurations. Epitaxial wafer production concentrates in Taiwan, South Korea, and China, with medical-grade emitter supply drawing from single-source East Asian foundries. Optical components and photodiode sensors feed from Japanese and German precision manufacturing clusters. Single-source vulnerability in blue LED die supply creates structural risk. Distribution runs through hospital procurement committees and group purchasing organizations, with regional equipment pools serving rural India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neonatal phototherapy devices market functions as a stable compounder, with regulatory upgrade cycles driving replacement demand regardless of macroeconomic conditions.
For Market Incumbents: Extend service contract economics toward multi-year performance guarantees tied to spare parts subscription models. GE Healthcare and Koninklijke Philips N.V. should deepen backward integration into wavelength-stable emitter supply chains to counter East Asian foundry concentration. Defend against disintermediation by independent biomedical service organizations through outcome-based uptime guarantees in United States health system consolidation markets. For New Entrants and Emerging Players: Biomedical service organizations represent the most viable channel partner type for market entry. District hospital networks in rural India under the National Health Mission offer the most penetrable white-space target, with solar-battery hybrid configurations addressing unserved volume. Secondary birthing centers in Japan seeking portable LED configurations to reduce inpatient transfer volumes present a second entry point. A rental-plus-service model bypasses capital equipment procurement cycle barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among modular platform specialists with incubator-integrated configuration capabilities. The market offers long-term viability through recurring service revenue attachment to capital equipment bases. Acquisition targets should display CE marking completion and European adverse event registry infrastructure. The signal to monitor is Medicaid reimbursement parity expansion for home phototherapy in additional United States states.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance timelines now stretch 18-24 months for novel optical feedback systems. |
| CE Marking Pathway | EU MDR mandates post-market clinical follow-up, restructuring service contract economics. |
| Hospital System Partnership | Multi-hospital maintenance agreements concentrate procurement authority in consolidated systems. |
| Software Companion Development | Wireless connectivity for remote irradiance logging satisfies surveillance obligations. |
| Reimbursement Strategy | Medicaid expansion for outpatient bilirubin treatment reshapes demand geography. |
Study Parameters
Multiple input streams — neonatal intensive care unit procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs specialists — were reconciled against FDA 510(k) filings, CE marking databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up triangulation across equipment installation records and top-down validation through manufacturer revenue disclosures anchored market sizing. Primary interviews with clinical engineering directors at German university hospitals and Japanese tertiary facilities informed wavelength-precision specification trends.
Historical shipment data cross-referenced against panel input from device manufacturers and component suppliers structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology platform, with regional regulatory clusters treated as a distinct dimension. CAGRs were derived from replacement cycle velocity analysis and point-of-care expansion patterns. Forecast inputs incorporated EU MDR enforcement timelines and Medicaid reimbursement parity expansion trajectories.
Revisions become necessary when FDA 510(k) timeline extensions accelerate, East Asian foundry supply disruptions materialize, or electromagnetic compatibility certification bottlenecks intensify. Forecasts reflect assumptions about regulatory enforcement continuity and hospital capital expenditure stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal and Infant Care Equipment Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Infant Resuscitators Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Umbilical Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Neonatal and Prenatal Devices Market