
 Asia-Pacific Fetal and Neonatal Care Equipment Market | 2026-2036
Asia-Pacific Fetal and Neonatal Care Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fetal and Neonatal Care Equipment Market Outlook
Multi-source procurement of critical components is shifting toward captive manufacturing partnerships across the Asia-Pacific fetal and neonatal care equipment supply base. GE Healthcare leverages its established imaging-to-critical-care platform to bundle neonatal monitoring with broader hospital infrastructure contracts. Koninklijke Philips NV anchors its regional position through deep channel relationships with government hospital networks in India and Southeast Asia. Phoenix Medical Systems competes aggressively on cost-engineered phototherapy units designed for mid-tier maternity wards.
Fetal and neonatal care equipment encompasses thermoregulation, respiratory support, diagnostic monitoring, and phototherapy systems engineered for gestational ages below thirty-seven weeks and birth weights under two thousand five hundred grams, typically operating within precision ranges of ±0.5°C thermal stability and ±2% oxygen delivery accuracy. The primary commercial purpose centers on reducing neonatal mortality and morbidity in facility-based deliveries across resource-variable health systems. Monitoring systems command the dominant revenue share due to their integration with hospital information networks and recurring sensor replacement cycles. Wireless and telemedicine-enabled platforms represent the fastest-expanding technology dimension, driven by India's tele-ICU pilots and Australia's rural outreach programs. Conventional analog equipment persists in price-sensitive procurement channels but faces margin compression from digital upgrade mandates.
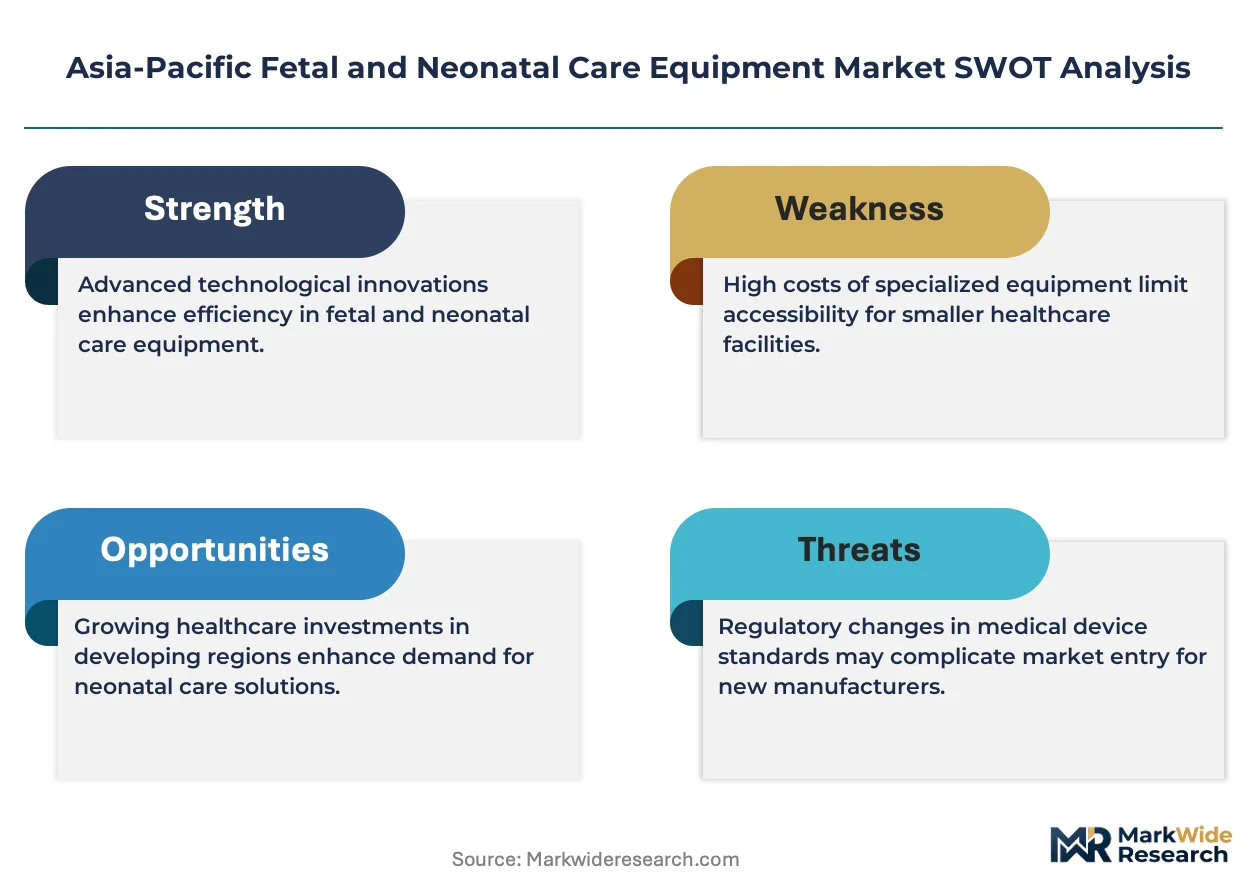
India's CDSCO medical device rules and China's NMPA registration requirements shape product standardization and market access timelines for imported equipment across the region. Australia's TGA alignment with EU MDR standards creates a dual-compliance burden for manufacturers serving multiple Asia-Pacific jurisdictions. The EU AI Act's extraterritorial influence on software-as-medical-device classifications is beginning to affect digital monitoring platforms with algorithmic diagnostic features. Stakeholders must evaluate regulatory divergence between ASEAN harmonization initiatives and national certification pathways when prioritizing market entry sequencing.
Market Dynamics
Government hospital upgrade programs across India's southern states and China's eastern provinces are concentrating demand for integrated neonatal monitoring platforms, while local manufacturing incentives compress import dependency for thermoregulation and phototherapy systems.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for medical device manufacturing accelerate domestic incubator and phototherapy unit assembly, reducing landed cost disadvantages for public hospital tenders.
- Tele-ICU pilots:India's national digital health mission and Australia's rural outreach programs expand wireless monitoring deployment into district hospitals and remote maternity wards.
- Tier-II maternity ward expansion:Vietnam and Indonesia are adding neonatal intensive care capacity in provincial hospitals, creating equipment procurement pipelines outside capital-city clusters.
Market Restraints
- Sensor import concentration:Pulse oximetry and thermal probe components remain concentrated in single-source supply corridors, exposing assemblers to semiconductor fab scheduling volatility.
- Dual-registration burden:Australia's TGA alignment with EU MDR standards forces parallel compliance documentation for equipment serving both Australasian and European markets, extending certification timelines.
- Analog equipment margin compression:Digital upgrade mandates in India's public procurement specifications strand existing installed bases and depress resale values for conventional monitoring systems.
Strategic Opportunities
- ASEAN harmonization gaps:Divergent national certification pathways across Southeast Asia create first-mover advantage for manufacturers establishing mutual recognition agreements with Singapore's HSA as a regional reference regulator.
- Software-as-medical-device classification:The EU AI Act's extraterritorial influence on algorithmic diagnostic features opens compliance consulting and platform redesign revenue streams for digital monitoring vendors.
- Phototherapy unit cost engineering:Mid-tier maternity wards in Indonesia and Philippines seek LED-based jaundice treatment systems below premium pricing tiers, rewarding localized assembly partnerships.
Industry Challenges
- Biomedical technician scarcity:Tier-III hospitals across India's northern and central states lack trained staff for preventive maintenance of precision thermal regulation systems, elevating warranty claim rates.
- Legacy HIS integration:Government hospital information networks in Vietnam and Indonesia operate on fragmented data standards, complicating seamless monitoring-to-records connectivity for imported platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fetal and Neonatal Care Equipment Market |
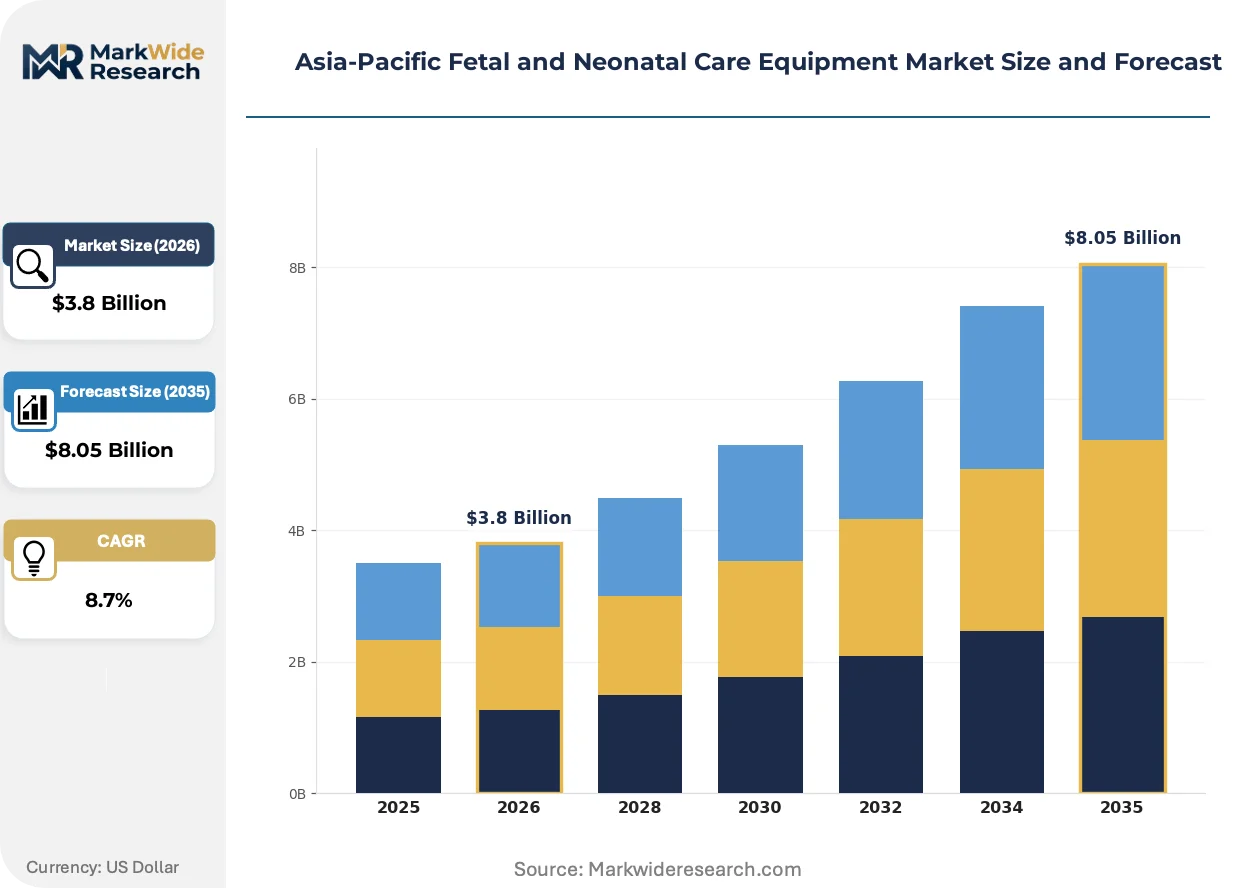
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incubators, Phototherapy Units, Resuscitation Equipment, Monitoring Systems End User: Hospitals, Neonatal Clinics, Research Institutions, Home Care Providers Technology: Conventional, Digital, Wireless, Telemedicine Solutions Application: Premature Care, Respiratory Support, Thermal Management, Diagnostic Monitoring |
| Companies Covered | Drägerwerk AG & Co. KGaA, Atom Medical Corporation, GE Healthcare, Beckton Dickinson and Company, Koninklijke Philips NV, Masimo, Natus Medical Incorporated, Phoenix Medical Systems, Vyaire Medical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fetal and Neonatal Care Equipment Market Strategic Shifts
Wireless telemetry and embedded AI diagnostics are reconfiguring competitive advantage around data integration capabilities rather than standalone hardware specifications, compressing traditional equipment replacement cycles.
Non-invasive hemoglobin monitoring through multi-wavelength spectroscopy is absorbing clinical validation workflows previously reserved for invasive blood sampling. District hospitals in India's Tamil Nadu and Karnataka are piloting these systems for early anemia detection in low-birth-weight infants. The technology is absorbing capital allocation from conventional laboratory analyzers as point-of-care diagnostic priorities shift toward bed-side immediacy.
China's NMPA streamlined registration pathways for Class II medical devices in 2023, reducing technical documentation requirements for incubators and radiant warmers with established predicate device histories. Domestic manufacturers in Jiangsu and Zhejiang provinces exploit these compressed timelines to outpace imported equipment approval schedules. Foreign suppliers now prioritize NMPA-synchronized technical files to avoid exclusion from provincial bulk procurement tenders.
Public hospital consortia in Australia and New Zealand are consolidating equipment purchasing through centralized tender frameworks, displacing individual hospital procurement autonomy. State health departments in Queensland and New South Wales negotiate enterprise-wide service agreements bundling devices, consumables, and remote technical support. This concentration shifts vendor selection criteria toward total cost-of-ownership metrics and penalizes suppliers lacking regional service infrastructure depth.
Asia-Pacific Fetal and Neonatal Care Equipment Market Segmentation
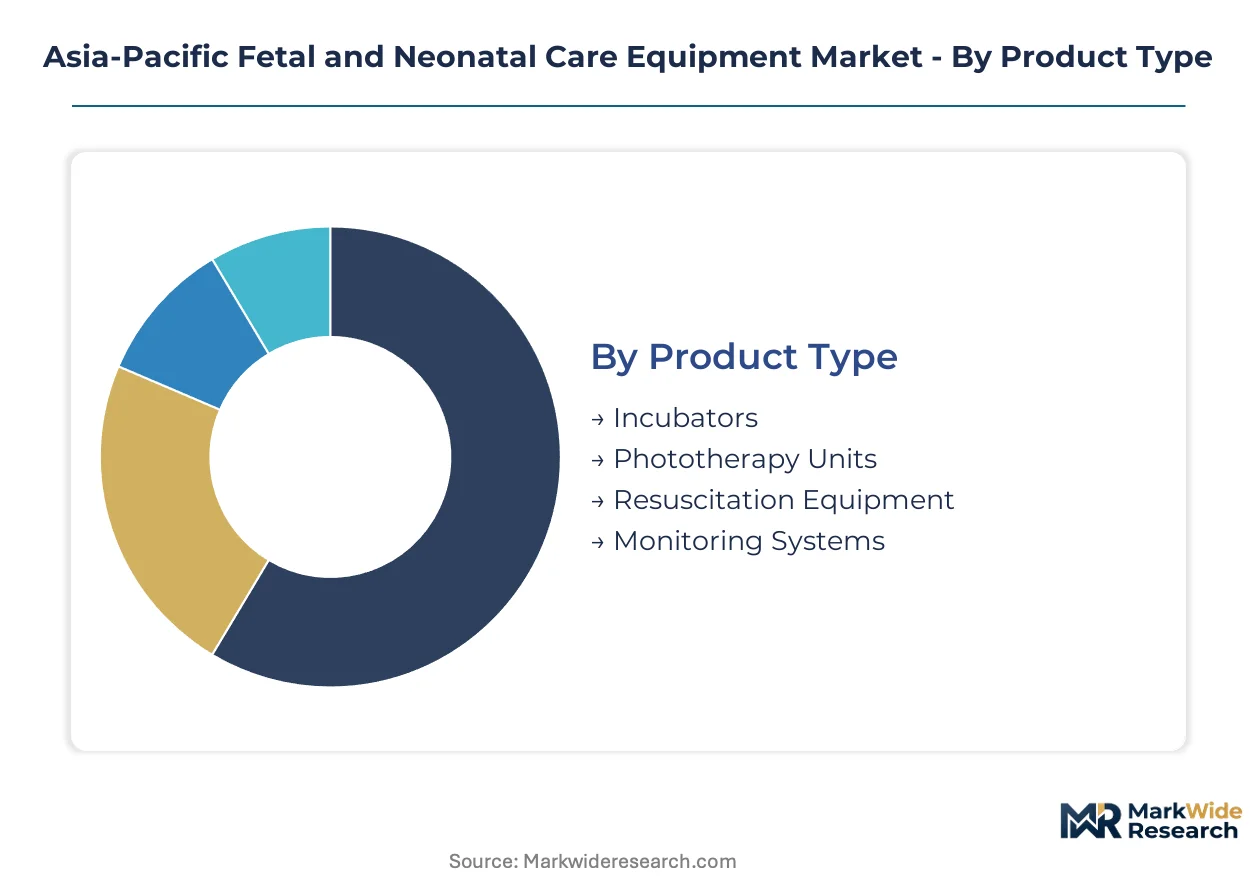
Segmentation in the Asia-Pacific fetal and neonatal care equipment market reveals divergent procurement patterns across public hospital tiers and technology readiness levels. Product specifications, connectivity requirements, and service infrastructure availability determine vendor selection criteria within each category.
Product Type:
Procurement budgets and clinical workflow integration requirements separate buyers across product categories.
- Monitoring Systems:Multi-parameter platforms track vital signs including SpO2, heart rate, respiratory rate, and temperature through integrated sensor arrays. India's southern states and China's eastern provinces concentrate demand through public hospital upgrade programs that mandate HIS-compatible digital platforms.
- Incubators:Servo-controlled thermal regulation systems maintain neutral thermal environment for infants below 1500g birth weight through air-servo or skin-servo modes. Vietnam and Indonesia's tier-II maternity wards drive volume procurement as provincial hospitals expand NICU capacity.
- Phototherapy Units:LED-based jaundice treatment systems deliver 360-degree irradiation for hyperbilirubinemia management.
- Resuscitation Equipment:T-piece resuscitators and self-inflating bags with positive end-expiratory pressure valves support delivery-room stabilization.
Monitoring Systems lead volumes today; Phototherapy Units are gaining share fastest through cost-engineered LED platforms.
End User:
Facility scale and patient acuity determine equipment sophistication requirements across customer types.
- Hospitals:Tertiary medical centers and district hospitals operate the highest-acuity neonatal intensive care units requiring full-platform integration. India's PLI scheme accelerates domestic assembly for public hospital tenders.
- Neonatal Clinics:Specialized maternity facilities focus on intermediate care for stable preterm infants needing thermal support and feeding assistance. Indonesia's provincial capitals see fastest clinic network expansion.
- Home Care Providers:Discharge planning programs in Australia deploy portable phototherapy and pulse oximetry for rural monitoring.
- Research Institutions:Academic medical centers validate novel diagnostic modalities including non-invasive hemoglobin spectroscopy.
Hospitals dominate absolute procurement value; Home Care Providers show steepest expansion trajectory through Australia's rural outreach models.
Technology:
Digital infrastructure maturity and connectivity mandates separate adoption curves across technology tiers.
- Digital:Embedded microprocessor control enables precision parameter regulation with alarm management and data logging. China's NMPA streamlined Class II registration pathways accelerate digital platform deployment.
- Telemedicine Solutions:Cloud-connected platforms enable remote specialist consultation for district hospitals lacking on-site neonatologists. India's national digital health mission pilots tele-ICU integration.
- Wireless:Bluetooth and Wi-Fi-enabled telemetry reduce cable clutter and support kangaroo mother care positioning.
- Conventional:Analog control systems persist in price-sensitive procurement channels facing margin compression from upgrade mandates.
Digital platforms anchor current installed base; Telemedicine Solutions climb the fastest as India's district hospital connectivity improves.
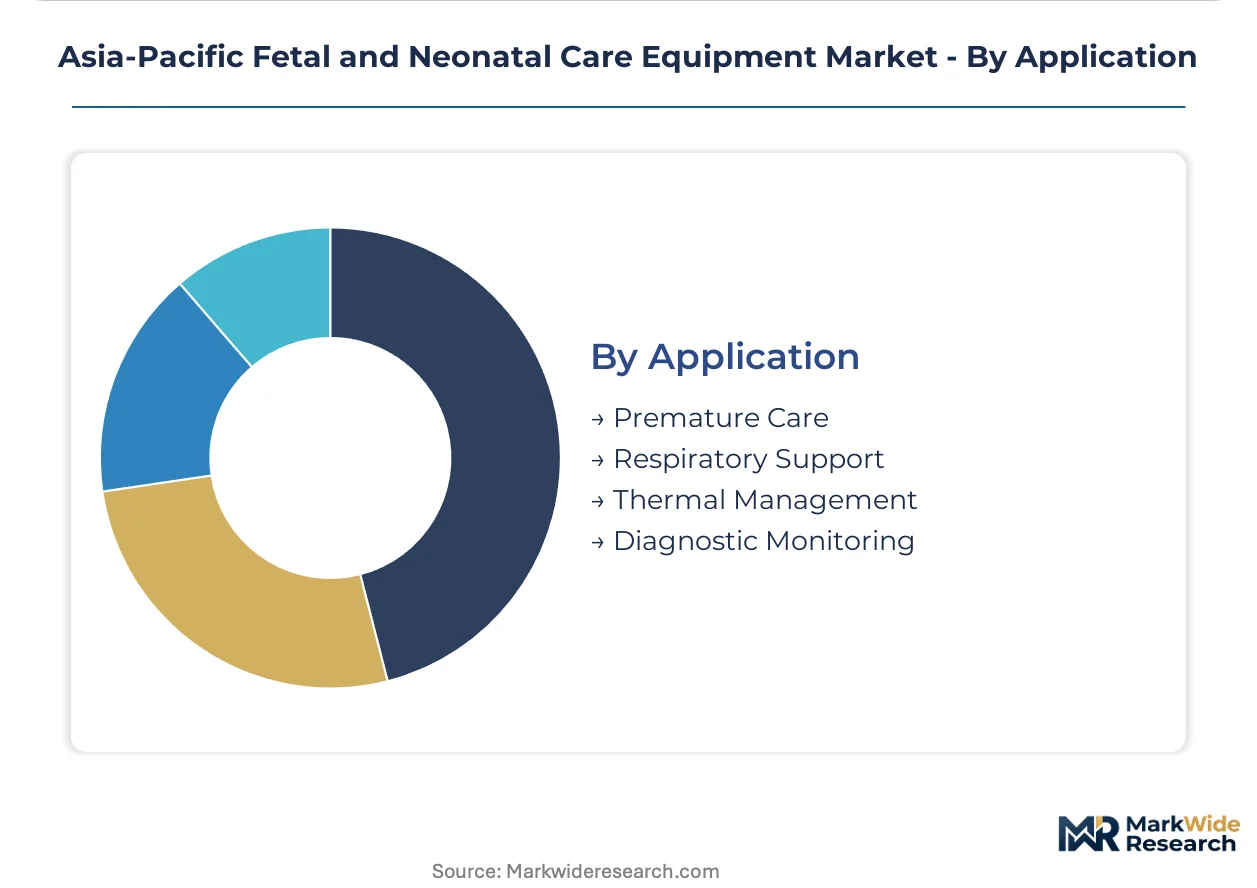
Application:
Clinical priority and reimbursement pathways shape equipment allocation across therapeutic domains.
- Diagnostic Monitoring:Continuous vital signs surveillance with trend analysis and early warning score integration absorbs largest capital allocation. Australia's TGA-aligned procurement frameworks favor integrated monitoring-to-records platforms.
- Premature Care:Gestational age-specific protocols below 32 weeks require precision thermal regulation, respiratory support, and nutritional monitoring. Tamil Nadu and Karnataka district hospitals pilot non-invasive hemoglobin systems.
- Thermal Management:Incubators and radiant warmers maintain thermoregulation for low-birth-weight infants.
- Respiratory Support:CPAP, high-flow nasal cannula, and mechanical ventilation systems address respiratory distress syndrome.
Diagnostic Monitoring commands dominant revenue share; Premature Care expands most quickly through point-of-care validation workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors regional manufacturing capacity for neonatal thermoregulation systems, while India's southern states concentrate demand through public hospital upgrade programs. Vietnam and Indonesia expand provincial NICU networks outside capital-city clusters. Australia's centralized procurement frameworks reshape vendor selection criteria toward service infrastructure depth.
China
Jiangsu and Zhejiang province manufacturers exploit NMPA's streamlined Class II registration pathways to compress approval timelines for incubators and radiant warmers. Provincial bulk procurement tenders in Shanghai and Jiangsu now favor domestic suppliers with synchronized technical documentation. Suzhou and Hangzhou industrial clusters specialize in servo-controlled thermal regulation systems for low-birth-weight infants.
India
Tamil Nadu and Karnataka district hospitals pilot non-invasive hemoglobin spectroscopy for premature care protocols below 32 weeks gestational age. CDSCO medical device rules shape product standardization timelines for imported monitoring platforms. Telangana's medical device manufacturing zones leverage PLI scheme incentives to assemble cost-engineered phototherapy units for tier-II maternity wards.
Vietnam
Provincial hospitals in Da Nang and Can Tho add neonatal intensive care capacity as tier-II maternity ward expansion accelerates outside Ho Chi Minh City and Hanoi. The country's national pharmaceutical regulator maintains divergent certification pathways from ASEAN harmonization initiatives. Central Highlands hospital consortia create procurement pipelines for LED-based jaundice treatment systems.
Indonesia
Mid-tier maternity wards in Surabaya and Bandung seek phototherapy units below premium pricing tiers, rewarding localized assembly partnerships with regional fabricators. Java-based hospital information networks operate on fragmented data standards that complicate monitoring-to-records connectivity. Bali and Sulawesi provincial capitals see fastest clinic network expansion for intermediate neonatal care.
Australia
Queensland and New South Wales state health departments negotiate enterprise-wide service agreements bundling devices, consumables, and remote technical support. TGA alignment with EU MDR standards creates dual-compliance documentation burdens for equipment serving both Australasian and European markets. Rural outreach programs in Western Australia deploy portable phototherapy and pulse oximetry for home-based monitoring.
Asia-Pacific Fetal and Neonatal Care Equipment Market Competitive Environment
Global majors compete with regional champions across channel relationships and manufacturing partnerships. The vendor base separates into imaging-to-critical-care platforms, government hospital network specialists, and cost-engineered equipment fabricators. Three strategic archetypes dominate: integrated critical-care conglomerates, deep-channel regional anchors, and localized assembly specialists. M&A activity concentrates on digital monitoring capabilities, while capacity expansion targets India's PLI scheme zones.
Among integrated critical-care conglomerates, GE Healthcare and Koninklijke Philips NV occupy positions bundling neonatal monitoring with broader hospital infrastructure contracts. Drägerwerk AG & Co. KGaA represents the precision-engineering archetype with German GmbH structure. Phoenix Medical Systems exemplifies the cost-engineered regional specialist tier. These three anchors illustrate how competitive positioning stratifies across premium-platform, government-channel, and mid-tier-economy vectors.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Atom Medical Corporation |
| GE Healthcare |
| Beckton Dickinson and Company |
| Koninklijke Philips NV |
| Masimo |
| Natus Medical Incorporated |
| Phoenix Medical Systems |
| Vyaire Medical |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing partnerships across India's PLI scheme zones anchor supply positions for domestic assemblers while compressing landed cost disadvantages against imported equipment. This integration choice concentrates pricing power with regional fabricators serving tier-II maternity wards, forcing global majors to rebundle service agreements and remote technical support to defend margin positions.
Pricing Analysis
Semiconductor and sensor import costs pass through directly into phototherapy and monitoring system price points, with pulse oximetry probe shortages amplifying volatility in tier-III hospital procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates GE Healthcare and Philips government-network contracts from Phoenix Medical Systems' cost-engineered LED platforms. Cost compression in economy tiers intensifies as India's digital upgrade mandates strand analog installed bases. Tier-II provincial hospitals in Vietnam and Indonesia exhibit highest price sensitivity; Australian state health departments show lowest sensitivity due to total cost-of-ownership evaluation frameworks.
Supply Chain Analysis
Freight cost differentials between air-shipped precision sensors and sea-freighted incubator chassis shape working capital requirements for assemblers serving dispersed district hospital networks. Component supply concentrates in China for servo-control electronics, Taiwan for semiconductor fabs, and Japan for precision thermal probes. Raw material dependencies span medical-grade plastics, LED arrays, and pulse oximetry diodes. Single-source vulnerability in thermal probe supply exposes manufacturers to fab scheduling volatility. Distribution runs through government tender consortia in India, centralized state procurement in Australia, and fragmented hospital networks across Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-as-medical-device platforms and localized assembly partnerships, with India's PLI scheme compressing production costs for domestic manufacturers serving mid-tier maternity wards.
For Market Incumbents: Anticipate regulatory divergence between ASEAN harmonization initiatives and national certification pathways by synchronizing technical documentation with Singapore's HSA as a regional reference regulator. Deepen channel control through enterprise-wide service agreements bundling devices, consumables, and remote technical support to offset price pressure from cost-engineered regional competitors. Invest in algorithmic diagnostic feature development to capture EU AI Act compliance consulting revenue streams. For New Entrants and Emerging Players: Begin with phototherapy unit cost engineering for Indonesia's mid-tier maternity wards, where LED-based jaundice treatment systems below premium pricing tiers face supply gaps. Target Vietnam's provincial hospital consortia in Da Nang and Can Tho as the most penetrable geography outside saturated capital-city clusters. Pursue localized assembly partnerships with regional fabricators to bypass import dependency disadvantages in public tenders. For Investors and Strategic Acquirers: Roll-up economics work for digital monitoring platform specialists because India's tele-ICU pilots and Australia's rural outreach programs are consolidating procurement around data integration capabilities rather than standalone hardware. Long-term viability hinges on software recurring revenue models displacing equipment replacement cycles. Target acquisition archetypes include wireless telemetry developers with embedded AI diagnostic validation. Watch for NMPA registration timeline compression as inflection indicator for domestic manufacturer competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Synchronized Technical Files | Streamlined Class II registration prevents exclusion from China's provincial bulk procurement tenders. |
| Tele-ICU Platform Integration | Cloud-connected monitoring captures India's national digital health mission pilot expansion. |
| LED Phototherapy Cost Engineering | Localized assembly partnerships unlock Indonesia's mid-tier maternity ward procurement pipelines. |
| Singapore HSA Mutual Recognition | Regional reference regulator status accelerates ASEAN market entry sequencing. |
| EU AI Act Compliance Consulting | Algorithmic diagnostic feature redesign opens software-as-medical-device revenue streams. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committees, GPO contracts managers, and CDSCO regulatory affairs specialists with secondary validation against NMPA registration databases, hospital procurement tenders, and TGA compliance filings. Bottom-up equipment shipment tracking and top-down healthcare expenditure analysis triangulated market sizing across the analysis window.
Segment-weighting approaches distributed value and volume projections across product type, end user, technology tier, and application dimensions, with gestational age-specific protocol requirements and HIS compatibility mandates as industry-specific forecast inputs. CAGRs derived from equipment replacement cycle compression, digital upgrade mandate penetration curves, and provincial hospital capacity expansion pipelines.
Several conditions sit outside the modeled scope, including semiconductor fab capacity shocks, abrupt regulatory reclassification of software diagnostic features, and pandemic-era hospital capital expenditure freezes. Forecasts reflect assumptions about telemedicine infrastructure rollout continuity and PLI scheme incentive stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Preterm Birth Prevention and Management Market
Neonatal Care
Europe Fetal and Neonatal Care Equipment Market
Neonatal Care
Perinatal Software Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Umbilical Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market
Neonatal Care
Neonatal Infant Care Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market