
 Infant Resuscitators Market | 2026-2036
Infant Resuscitators Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Resuscitators Market Foresight
ISO 13485 certification is unwinding the competitive landscape by forcing smaller suppliers out of tender processes for hospital-grade equipment. GE Healthcare leverages integrated imaging and respiratory portfolios to sustain long-term service contracts with academic medical centers. Philips anchors its position through connected-care ecosystems that link resuscitation data to electronic health records. Drägerwerk AG dominates European procurement channels with anesthesia and ventilation bundled offerings.
Infant resuscitators are pressure-limited mechanical or pneumatic devices designed to deliver controlled tidal volumes and positive end-expiratory pressure to newborns with respiratory depression, typically incorporating manometers, pressure-relief valves, and patient valves rated for flows under 15 L/min. Their primary purpose is to establish spontaneous breathing during the golden minute after delivery when hypoxia causes irreversible neurologic injury. Bag-valve-mask devices occupy the highest unit-volume tier due to universal deployment in delivery rooms, yet automated resuscitators capture disproportionate margin pools as NICUs upgrade from manual to pressure-targeted ventilation. Neonatal intensive care units represent the most concentrated end-user segment, while emergency medical services channels face slower penetration because of equipment portability requirements and paramedic training gaps.
FDA 510(k) clearance, CE marking under the EU Medical Device Regulation, and ISO 10651-4 standards collectively determine which manufacturers access reimbursed procurement channels in the United States, European Union, and Japan. These frameworks elevate barrier costs for new entrants while rewarding incumbents with established quality management systems and clinical validation libraries. Stakeholders must weigh whether to absorb compliance investments in-house or exit lower-margin geographies where notified body backlogs extend time-to-market.
Market Dynamics
Automated resuscitation platforms are displacing manual bag-valve-mask systems in NICU procurement, driven by pressure-targeted ventilation protocols and liability concerns around operator-dependent performance variation during the golden minute after delivery.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated review timelines for predicate-device submissions are compressing time-to-market for iterative resuscitator designs. Hospital systems in the United States prioritize FDA-cleared equipment in competitive tenders.
- Neonatal intensive care unit expansion:Academic medical centers in Germany and Japan are adding dedicated resuscitation bays with integrated respiratory monitoring. Capital budgets for perinatal services are expanding across tertiary hospital networks.
- Positive end-expiratory pressure (PEEP) valve miniaturization:Advances in silicone molding and precision spring manufacturing are enabling consistent 5 cm H₂O delivery in portable devices. This technical maturation is extending automated resuscitation into emergency medical services channels previously limited to manual devices.
Market Restraints
- Medical-grade polymer supply concentration:Specialized polycarbonate and silicone suppliers in Germany and Switzerland control critical raw material streams for pressure-relief valve housings. Disruptions propagate quickly through device manufacturing schedules.
- ISO 10651-4 testing burden:Full validation protocols for pneumatic resuscitators require extensive clinical simulation datasets. Smaller manufacturers lack capital reserves to complete notified body submissions under EU Medical Device Regulation timelines.
- Competition from low-cost manual resuscitators:Disposable bag-valve-mask devices from Southeast Asian contract manufacturers satisfy basic regulatory requirements in price-sensitive procurement environments. Automated platforms struggle to demonstrate sufficient clinical outcome differentiation to justify capital expenditure multiples.
Strategic Opportunities
- Connected-care ecosystem integration:Resuscitation data streams linking to electronic health records are creating recurring revenue attachments. Philips and GE Healthcare are bundling device placement with long-term service contracts.
- Emergency medical services penetration:Paramedic training programs in the United States are expanding neonatal resuscitation certification requirements. Portable automated devices with simplified interfaces address documented skill-retention gaps in prehospital settings.
- Japanese PMDA priority review vouchers:Orphan pediatric device designations offer accelerated market access for innovative resuscitation technologies. METI funding for perinatal health infrastructure is expanding procurement pools for domestic and imported equipment.
Industry Challenges
- Biomedical engineer specialization scarcity:Neonatal respiratory device design requires rare cross-training in fluid dynamics, materials science, and clinical workflow optimization. Recruitment pipelines from academic programs in the United States and Germany fail to match industry demand.
- Legacy equipment interoperability:Automated resuscitators must interface with existing patient monitoring architectures from diverse manufacturers. Integration testing consumes substantial development resources without direct revenue recognition.
- CE marking notified body backlogs:EU Medical Device Regulation implementation has constrained assessment capacity. Extended review timelines are freezing product launch schedules and consuming working capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Resuscitators Market |
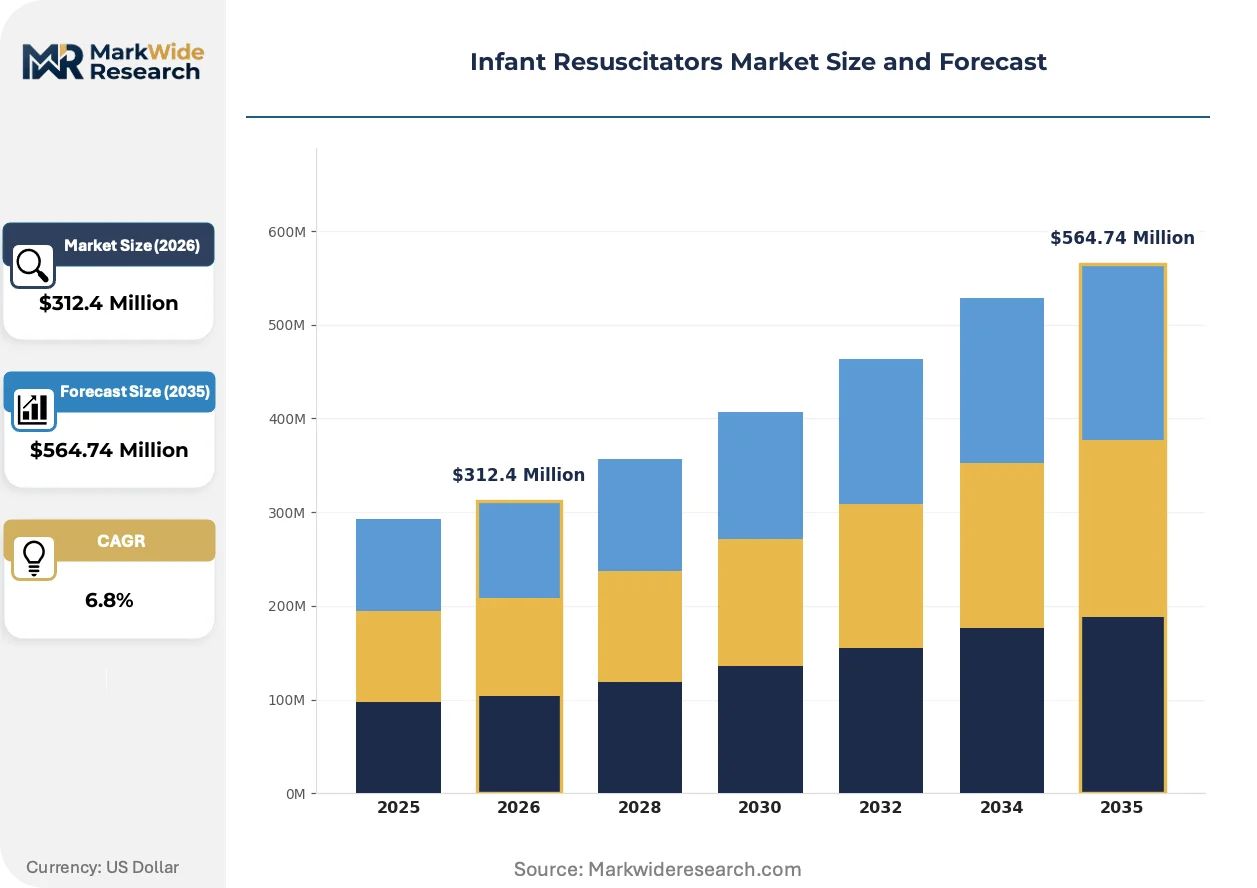
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bag-Valve-Mask, Neonatal Resuscitation Device, Automated Resuscitator, Laryngoscope Technology: Mechanical, Electrical, Manual, Digital End User: Hospitals, Clinics, Neonatal Intensive Care Units, Emergency Medical Services Delivery Mode: Bilevel Positive Airway Pressure, Continuous Positive Airway Pressure, Face Mask, Endotracheal Tube |
| Companies Covered | GE Healthcare, Philips, Medtronic, Drägerwerk AG, Laerdal Medical, Fisher & Paykel Healthcare, Ambu A/S, Flexicare (Group) Limited, Mercury Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Resuscitators Market Shifts & Advancements
Pressure-limited ventilation technology is fragmenting into distinct performance tiers, with premium automated systems diverging from commodity manual devices on clinical outcome metrics and total cost-of-ownership calculations.
Tidal volume targeting algorithms are bifurcating the installed base between academic medical centers and community hospitals. NICU directors in the United States and Germany are prioritizing devices with integrated flow sensors and real-time feedback displays. This capability expansion is compressing margins for basic pneumatic resuscitators while creating service-attachment revenue pools for integrated platform vendors.
EU Medical Device Regulation clinical evidence requirements are elevating barrier costs for new market entrants. Manufacturers must now submit prospective clinical data rather than predicate-device equivalency arguments. Class IIa resuscitator submissions face extended notified body review timelines, favoring incumbents with established quality management systems and post-market surveillance infrastructures.
Hospital procurement committees are unbundling device acquisition from service contracts in competitive tenders. Group purchasing organizations in the United States are negotiating separate pricing for capital equipment, preventive maintenance, and disposable components. This disaggregation is most visible in multi-hospital systems seeking to optimize total cost-of-ownership across standardized device fleets.
Infant Resuscitators Market Segmentation
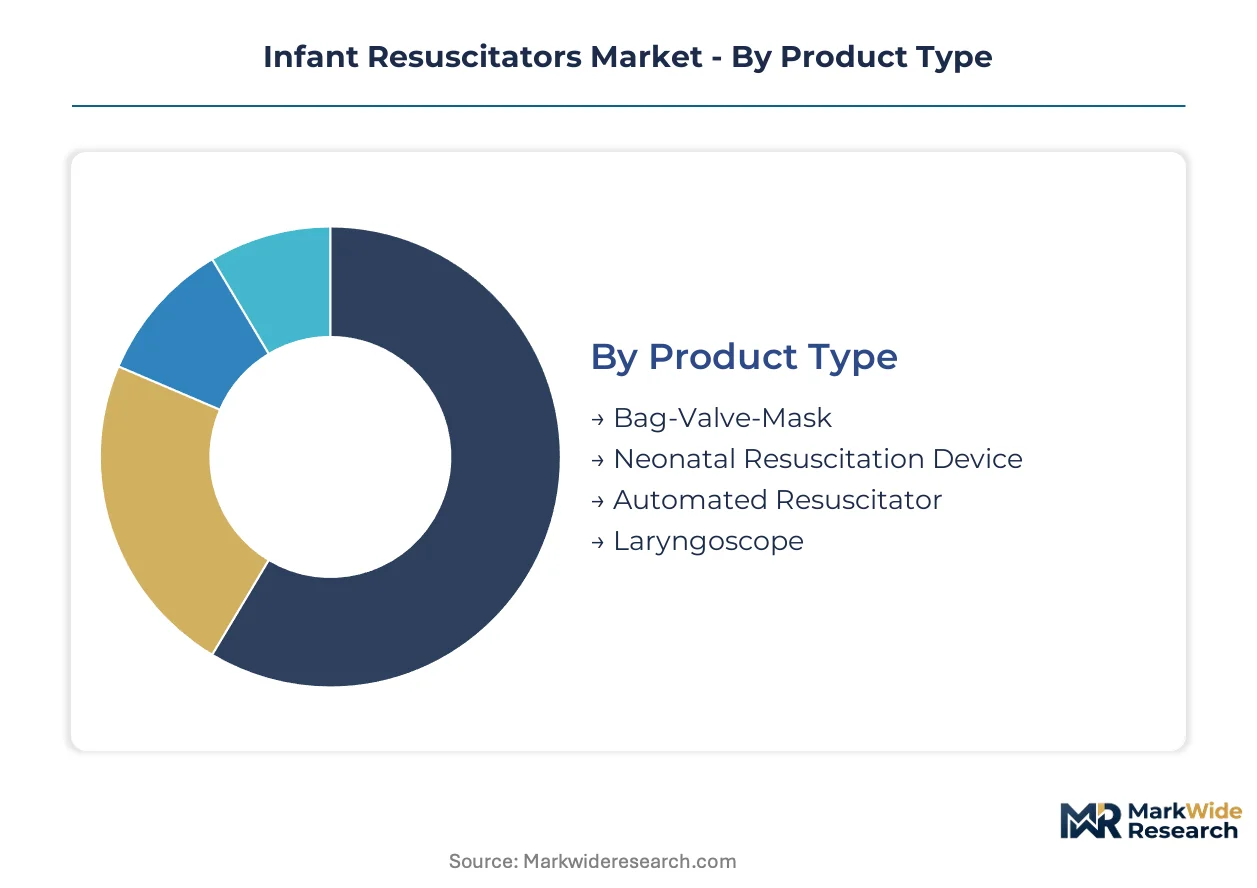
Segmentation in infant resuscitators reveals how procurement committees allocate capital across performance tiers, from disposable delivery-room equipment to integrated NICU platforms. Understanding these divides exposes where manufacturers capture margin versus where price competition erodes returns.
Product Type:
Margin pools concentrate in automated platforms where software-enabled ventilation commands service-attachment revenue, while manual devices compete on unit economics in high-volume tenders.
- Bag-Valve-Mask:Disposable pneumatic devices composed of silicone self-inflating bags, pressure-relief valves, and pop-off mechanisms rated to 40 cm H₂O. Demand concentrates in United States delivery rooms where Joint Commission mandates universal availability, though reimbursement compression limits pricing power.
- Automated Resuscitator:Microprocessor-controlled platforms with tidal volume targeting, PEEP delivery, and integrated spirometry. Academic medical centers in Germany and Japan prioritize these for NICU resuscitation bays, driven by liability concerns over operator-dependent performance variation.
- Neonatal Resuscitation Device:Stand-alone warming and ventilation workstations for perinatal suites.
- Laryngoscope:Illuminated blade systems for endotracheal intubation in emergency scenarios.
The dominant share belongs to Bag-Valve-Mask, while Automated Resuscitator is closing the gap fastest.
Technology:
Volume splits across technology tiers reflect training infrastructure maturity and capital availability in end-use settings.
- Mechanical:Pneumatic systems relying on spring-loaded valves and manual flow adjustment without electronic feedback. Community hospitals in price-sensitive procurement environments favor these for reliability and minimal maintenance requirements.
- Digital:Sensor-integrated platforms with real-time pressure and flow visualization, algorithmic leak compensation, and data logging. United States academic medical centers drive specification requirements here, seeking connectivity to electronic health records.
- Manual:Operator-dependent devices requiring continuous hand compression and visual assessment of chest rise.
- Electrical:Motor-driven bellows systems with battery backup for transport scenarios.
Mechanical technology still commands the largest installed base, though Digital platforms are expanding most quickly in tertiary care networks.
End User:
Customer-type segmentation tracks how clinical workflow complexity shapes equipment specification and service contract attachment rates.
- Neonatal Intensive Care Units:Dedicated perinatal centers with 24-hour respiratory therapy coverage and in-house biomedical engineering. These facilities in Japan and Germany specify integrated monitoring compatibility and demand comprehensive preventive maintenance agreements.
- Emergency Medical Services:Prehospital providers requiring portable, battery-operated devices with simplified interfaces. United States paramedic training programs are expanding neonatal certification, creating specification pressure for ruggedized automated platforms with skill-retention features.
- Hospitals:General acute-care facilities with mixed adult-pediatric service lines.
- Clinics:Outpatient settings with limited resuscitation capabilities and basic regulatory requirements.
Neonatal Intensive Care Units retain the dominant procurement value, while Emergency Medical Services is gaining share fastest as prehospital protocols mature.
Delivery Mode:
Interface selection determines material specifications, sterilization protocols, and reimbursement coding complexity across care settings.
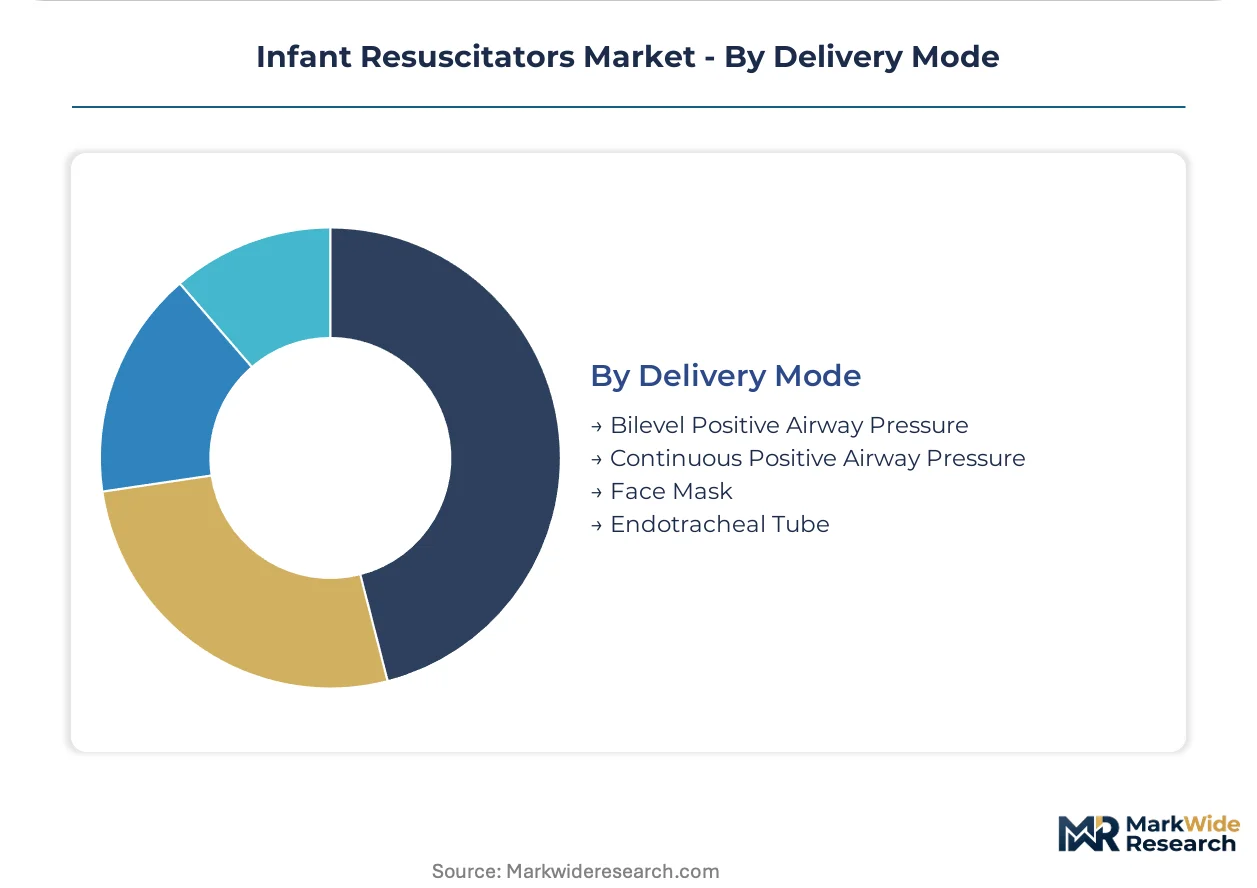
- Continuous Positive Airway Pressure:Nasal prong or mask interfaces delivering 5-8 cm H₂O throughout the respiratory cycle. NICU directors in the United States specify these for primary resuscitation to reduce intubation rates and associated bronchopulmonary dysplasia risk.
- Endotracheal Tube:Invasive ventilation via cuffed or uncuffed tubes for severe respiratory depression or meconium aspiration. German perinatal centers maintain high intubation capability with anesthesia backup, sustaining demand for compatible resuscitator connectors.
- Face Mask:Standard silicone interfaces for initial positive-pressure ventilation in delivery rooms.
- Bilevel Positive Airway Pressure:Alternating pressure delivery for specific respiratory pathologies.
Continuous Positive Airway Pressure holds the dominant clinical preference, while Endotracheal Tube maintains steady utilization in high-acuity settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate purchasing authority for automated resuscitation platforms. Academic medical centers in these markets drive specification requirements toward pressure-targeted ventilation and electronic health record connectivity.
United States
Academic medical centers in Boston and California are expanding NICU resuscitation bay capacity with integrated respiratory monitoring. FDA 510(k) pathway streamlining accelerates predicate-device clearances for iterative designs. Tertiary hospital networks in the Midwest are standardizing device fleets across multi-hospital systems to optimize total cost-of-ownership.
Germany
Perinatal centers in Bavaria and North Rhine-Westphalia maintain high intubation capability with anesthesia backup, sustaining demand for compatible resuscitator connectors. CE marking under EU Medical Device Regulation elevates barrier costs for new entrants. Medical-grade polymer suppliers in Switzerland and southern Germany control critical raw material streams for pressure-relief valve housings.
Japan
METI funding for perinatal health infrastructure expands procurement pools for domestic and imported equipment. PMDA priority review vouchers for orphan pediatric device designations offer accelerated market access for innovative resuscitation technologies. NICU directors in Tokyo and Osaka specify integrated monitoring compatibility and demand comprehensive preventive maintenance agreements.
United Kingdom
NHS procurement frameworks for neonatal services prioritize devices with demonstrated clinical outcome differentiation. MHRA post-Brexit regulatory autonomy creates parallel submission requirements alongside CE marking. London and Southeast England academic medical centers anchor specification development for connected-care ecosystem integration.
India
CDSCO medical device rules are tightening quality benchmarks for imported Class II resuscitation equipment. Maharashtra and Karnataka state health missions are expanding NICU infrastructure in district hospitals. Price-sensitive procurement environments favor basic pneumatic resuscitators, though metropolitan tertiary centers in Delhi-NCR and Chennai are piloting automated platforms.
Infant Resuscitators Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with integrated respiratory portfolios. Consolidation pressure favors incumbents with established FDA and CE marking quality management systems. Three strategic archetypes dominate: imaging-respiratory integrators, connected-care platform vendors, and anesthesia-ventilation bundlers. Competitive moves center on long-term service contract attachments and geographic expansion through distribution partnerships.
Among diversified healthcare technology conglomerates, GE Healthcare, Philips, and Drägerwerk AG occupy positions that exemplify distinct competitive vectors. GE Healthcare represents the imaging-respiratory integration archetype, anchoring its market presence through cross-selling opportunities with academic medical centers. Philips exemplifies the connected-care platform approach, with its positioning reflecting ecosystem strategies that link device data to electronic health records. Drägerwerk AG sits within the anesthesia-ventilation bundling tier, leveraging European procurement channel dominance through combined offerings.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips |
| Medtronic |
| Drägerwerk AG |
| Laerdal Medical |
| Fisher & Paykel Healthcare |
| Ambu A/S |
| Flexicare (Group) Limited |
| Mercury Medical |
| Others |
Supply & Pricing Matrix
ISO 13485 certification gates both supplier qualification and price differentiation simultaneously, forcing hospital-grade equipment tenders toward established quality management systems while compressing margins for uncertified competitors. Medical-grade polymer sourcing and notified body audit costs propagate through final equipment pricing, creating structural separation between premium automated platforms and commodity manual devices.
Pricing Analysis
Cost-plus contracts with medical-grade silicone indexation dominate procurement agreements for NICU-grade automated resuscitators. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard tiers, and basic pneumatic economy tiers, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression in manual bag-valve-mask segments is intensifying because Southeast Asian contract manufacturers satisfy basic regulatory requirements at lower price points. Community hospitals in price-sensitive procurement environments exhibit highest price sensitivity, while academic medical centers prioritize clinical outcome metrics over capital expenditure.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors constrain just-in-time delivery schedules for German and Swiss medical-grade polymer suppliers. Manufacturing concentration in Germany, Switzerland, and the United States controls critical raw material streams for pressure-relief valve housings, silicone molding components, and precision spring assemblies. Single-source vulnerability in specialized polycarbonate feedstock creates exposure to regional production disruptions. Distribution runs through hospital group purchasing organizations and specialized medical device distributors with cold-chain capabilities for temperature-sensitive components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA 510(k) clearance libraries and established notified body relationships create switching costs that protect incumbent positions.
For Market Incumbents: Consolidate service contract attachments with academic medical centers to lock out emerging platform competitors. Deepen backward integration into medical-grade polymer sourcing to insulate against Swiss and German supplier concentration. ISO 10651-4 testing burden threats from EU Medical Device Regulation implementation favor those with capital reserves to accelerate notified body submissions. For New Entrants and Emerging Players: Lead with portable automated resuscitator designs targeting emergency medical services channels where paramedic training gaps create specification pressure for simplified interfaces. Japanese PMDA priority review vouchers offer the most penetrable regulatory pathway for orphan pediatric device designations. Partner with regional distributors possessing established hospital procurement committee relationships rather than direct capital equipment sales forces. For Investors and Strategic Acquirers: EU Medical Device Regulation implementation reshapes the acquisition landscape by elevating barrier costs for quality management system buildouts. Long-term viability across the projection horizon favors targets with established post-market surveillance infrastructures and clinical validation libraries. Watch notified body backlog clearance rates as the signal for product launch velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements favor incumbents with predicate-device libraries and quality management systems. |
| Hospital System Partnership | Long-term service contracts with academic medical centers in Germany and Japan lock in recurring revenue attachments. |
| Software Companion Development | Connected-care ecosystems linking resuscitation data to electronic health records create platform stickiness. |
| Reimbursement Strategy | FDA 510(k) clearance accelerates predicate-device submissions and compresses time-to-market for iterative designs. |
| Backward Integration | Captive supply of medical-grade polymers insulates against German and Swiss raw material concentration risks. |
Research Methodology
Cross-validation between primary interviews with NICU directors, biomedical engineers, hospital purchasing committees, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, CE marking databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up equipment shipment analysis triangulates with top-down healthcare infrastructure spending assessments to constrain estimate variance.
Sensitivity analysis around regulatory approval timelines, raw material cost indices, and NICU capital budget cycles tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product type tier, technology architecture, end-user setting, delivery mode interface, and regional regulatory cluster. CAGRs derive from equipment replacement cycles, infrastructure investment trajectories, and clinical guideline adoption curves in perinatal care.
The analysis sits within stated boundaries; outcomes outside sustained FDA review streamlining, stable medical-grade polymer supply, and continued NICU infrastructure investment would require recalibration. Forecasts reflect assumptions around regulatory pathway efficiency and clinical outcome differentiation persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Perinatal Software Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market