
 India Neonatal and Prenatal Devices Market | 2026-2036
India Neonatal and Prenatal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Neonatal and Prenatal Devices Market Insights
CDSCO's tightened medical device licensing under the Medical Device Rules is decoupling import-dependent supply chains from domestic manufacturing incentives. GE Healthcare leverages its Bengaluru engineering center to sustain local assembly of incubators and warmers. Koninklijke Philips anchors its southern India presence through specialized neonatal monitoring distribution. Phoenix Medical Systems competes on cost-engineered respiratory interfaces designed for government procurement cycles.
Neonatal and prenatal devices comprise thermoregulation systems, cardiorespiratory monitors, phototherapy units, and fetal Doppler apparatus engineered to ISO 13485 quality management standards with biocompatibility-rated polymers for infant contact surfaces. These instruments serve to stabilize premature births, manage neonatal jaundice, and enable antenatal fetal surveillance across institutional and ambulatory settings. Incubators and warmers occupy the largest installed base among device types, while wireless and telemedicine-enabled monitors represent the fastest-expanding technology tier as rural connectivity improves. Hospitals dominate end-user procurement volumes, though homecare segments are gaining traction for post-discharge apnea monitoring in metro satellite townships.
CDSCO mandates device-specific quality standards aligned with BIS certification, while the PLI scheme for medical devices redirects capital toward domestic component sourcing. State-level public health directorates in Kerala and Gujarat enforce additional tender specifications that filter non-compliant suppliers from institutional purchasing. Stakeholders must track how Ayushman Bharat reimbursement expansion into neonatal packages reshapes device specification requirements at district hospitals.
Market Dynamics
Wireless monitoring architectures are fragmenting procurement authority across district hospitals and sub-centers, redistributing device specification power from centralized state tenders to facility-level clinical committees.
Growth Catalysts
- Ayushman Bharat neonatal package expansion:Reimbursement coverage for low-birth-weight interventions is pulling device procurement into 22,000 health and wellness centers.
- PLI scheme for medical devices:Domestic component sourcing mandates under this incentive framework are compressing landed cost differentials for respiratory interfaces and thermoregulation systems.
- Tier-II city hospital infrastructure:National Health Mission funding streams are equipping district facilities with NICU-grade monitoring capacity previously concentrated in metropolitan teaching hospitals.
Market Restraints
- Biocompatibility-rated polymer import dependence:ISO 10993-certified housing materials for infant-contact surfaces concentrate sourcing from German and Japanese specialty chemical suppliers.
- CDSCO licensing timeline friction:Medical Device Rules compliance pathways for novel wireless monitors extend 14-18 months, lagging product development cycles.
- Specialist technician scarcity:Biomedical engineering talent capable of servicing telemedicine-enabled monitors clusters in Bengaluru, Hyderabad, and Chennai, leaving northern and eastern districts underserved.
Strategic Opportunities
- Homecare apnea monitoring:Post-discharge surveillance demand in Gurugram, Noida, and Thane satellite townships is creating ambulatory device rental channels outside institutional procurement.
- Kerala and Gujarat tender specification divergence:State-level public health directorates are layering BIS certification requirements atop central CDSCO mandates, filtering supplier pools and creating first-mover advantages for compliant domestic assemblers.
- 5G-enabled remote fetal surveillance:Convergence of low-latency connectivity with portable Doppler systems is opening antenatal monitoring access in tribal blocks of Madhya Pradesh and Chhattisgarh.
Industry Challenges
- ISO 13485 quality management system implementation:Small-scale domestic manufacturers face 12-24 month certification timelines to meet institutional tender pre-qualification criteria.
- Legacy wired infrastructure integration:District hospitals with 2015-2019 installed base of central monitoring stations require middleware investments to adopt wireless telemetry protocols.
- Biomedical technician training pipeline:NICU-specific device calibration and preventive maintenance skills concentrate in Maharashtra, Karnataka, and Tamil Nadu training centers, constraining nationwide deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Neonatal and Prenatal Devices Market |
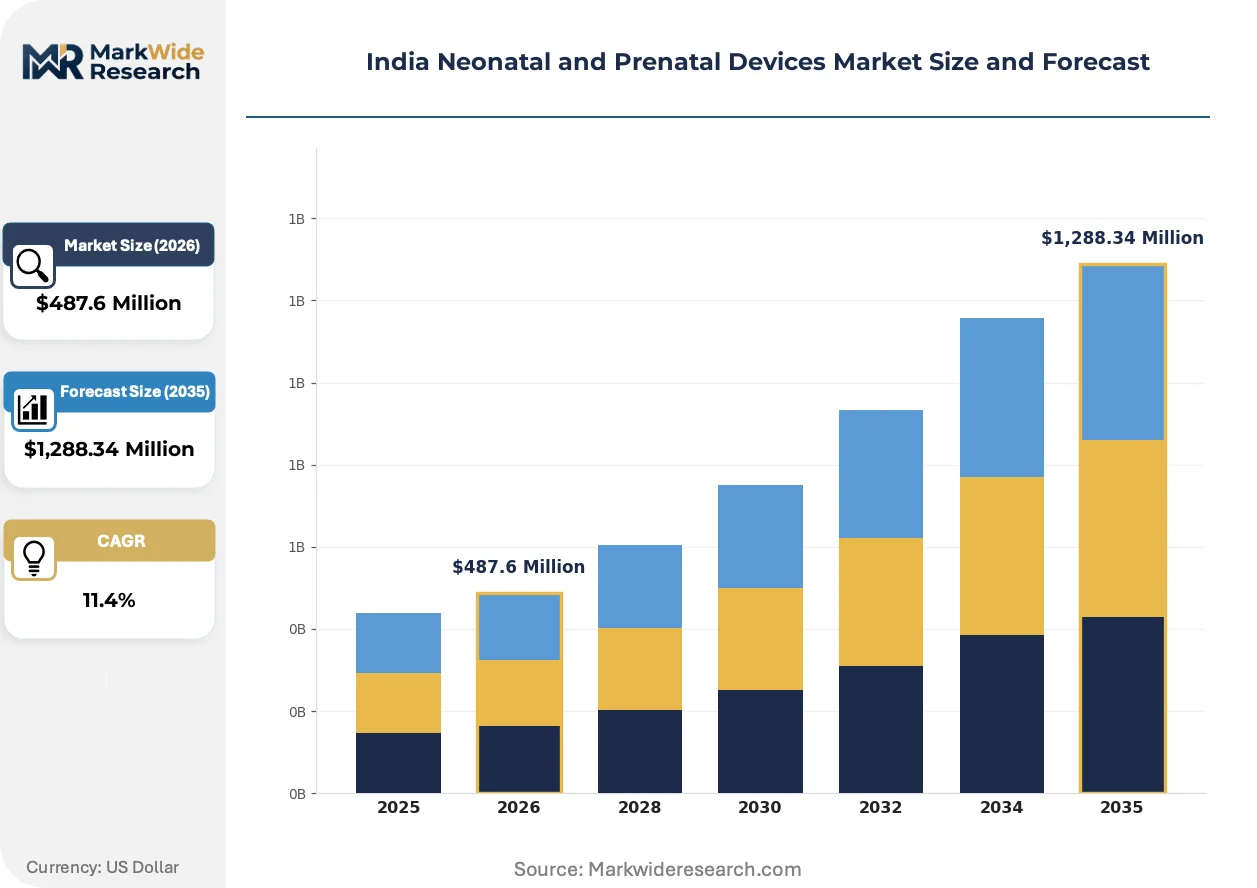
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Incubators, Monitors, Respiratory Devices, Imaging Equipment End User: Hospitals, Clinics, Homecare, Neonatal Units Technology: Digital, Analog, Wireless, Telemedicine Application: Monitoring, Treatment, Diagnostics, Research |
| Companies Covered | GE Healthcare, Koninklijke Philips, Medtronic, Drägerwerk AG & Co. KGaA, Atom Medical Corporation, Natus Medical Incorporated, Fisher & Paykel Healthcare, Masimo, Phoenix Medical Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Neonatal and Prenatal Devices Market Trends and Innovations
Device architectures are converging around portable, connectivity-native designs that compress the traditional boundary between hospital-grade and ambulatory monitoring tiers. This shift is redistributing value capture toward software-integrated platform vendors.
Neonatal monitoring hardware is modularizing around detachable sensor pods and standardized data protocols. District hospitals in Rajasthan and Uttar Pradesh are piloting these configurations to enable equipment sharing across maternity and pediatric wards. The technology is modularizing capital deployment, allowing facilities to scale monitoring capacity incrementally rather than through centralized system purchases.
CDSCO's tightened licensing enforcement under the 2017 Medical Device Rules is bifurcating the supplier landscape between import-dependent multinationals and domestic assemblers meeting BIS certification. This regulatory compression is accelerating local engineering center investments for incubator and warmer assembly. Wireless monitor categories face the steepest compliance adaptation curves as software-as-medical-device classifications extend scrutiny to cloud connectivity components.
Clinical committees at Tier-II facilities are gaining procurement autonomy previously centralized at state directorates. Maharashtra's district hospitals now specify device configurations independently, fragmenting standardization and creating opportunities for regional distributors with technical advisory capacity. This behavioral shift is most visible in Karnataka, where hub-and-spoke NICU networks delegate equipment selection to taluk-level obstetricians rather than state tender boards.
India Neonatal and Prenatal Devices Market Segmentation
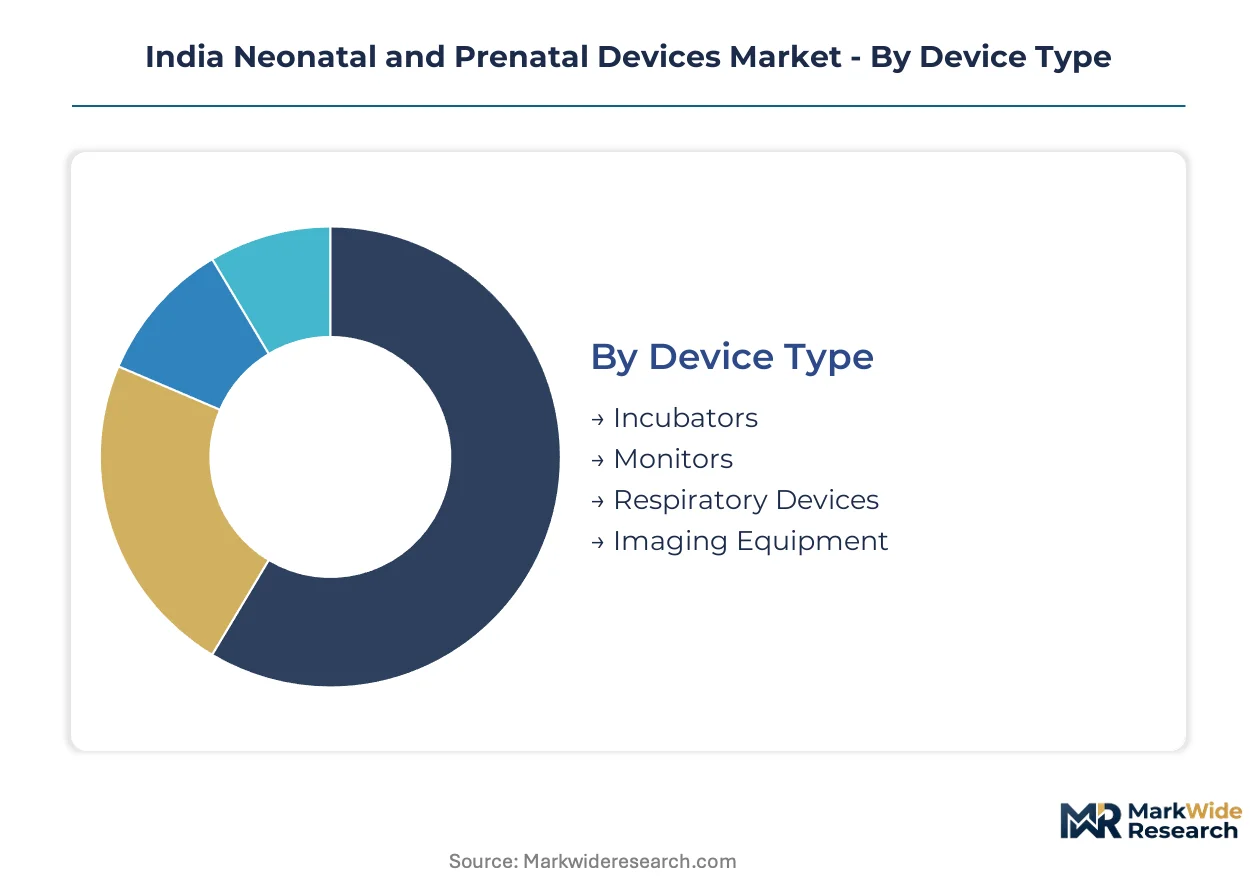
Segmentation reveals how procurement authority fragments across India's neonatal care infrastructure. Device specifications diverge sharply between metropolitan teaching hospitals and district-level facilities emerging under National Health Mission funding.
Device Type:
Supply concentration for finished devices clusters around Bengaluru and Chennai engineering centers, with component sourcing still tethered to German and Japanese polymer suppliers.
- Incubators:Thermoregulation systems with servo-controlled heating and humidity management, built to ISO 13485 standards with biocompatibility-rated polymers for infant contact surfaces. Maharashtra and Karnataka hospitals account for the densest installed base, driven by specialist NICU expansion in Mumbai and Bengaluru teaching institutions.
- Monitors:Cardiorespiratory and multi-parameter telemetry units processing ECG, SpO2, and respiration data. District hospitals in Tamil Nadu and Gujarat are displacing wired central stations with wireless pod-based architectures that redistribute procurement authority to taluk-level clinical committees.
- Respiratory Devices:CPAP interfaces and ventilator circuits engineered for low-birth-weight pulmonary support. Cost-engineered designs from domestic assemblers compete for government procurement cycles.
- Imaging Equipment:Portable ultrasound and digital radiography systems for neonatal cranial and thoracic assessment. Concentrated in tertiary referral centers with dedicated pediatric radiology departments.
Incubators absorb the bulk of installed capacity; monitors are expanding most quickly.
End User:
Customer type determines specification rigor and procurement channel, with institutional tenders imposing stricter BIS certification than ambulatory or rental channels.
- Hospitals:Tertiary and district-level facilities with dedicated NICU infrastructure. CDSCO licensing mandates and state tender specifications filter supplier pools, creating first-mover advantages for compliant domestic assemblers in Kerala and Gujarat.
- Clinics:Secondary maternity centers with limited overnight observation capacity. Procurement concentrates on portable monitoring and basic thermoregulation without full intensive care capability.
- Homecare:Post-discharge apnea monitoring and phototherapy rental channels in Gurugram, Noida, and Thane satellite townships. Demand concentrates where metro hospital referrals create compliance-aware patient populations.
- Neonatal Units:Dedicated intensive care wards within larger hospital complexes. These facilities specify the highest device density per bed and drive technology adoption for wireless telemetry.
Hospitals dominate procurement volume; homecare is gaining share fastest.
Technology:
Technology tier correlates directly with margin structure, with digital-native platforms capturing value from software-integrated service contracts.
- Digital:Microprocessor-controlled devices with embedded data logging and alarm algorithms. Standard for new installations across Tier-II city hospital expansions.
- Analog:Electromechanical systems without software components. Survives in legacy infrastructure requiring middleware investment for connectivity integration.
- Wireless:Telemetry architectures using standardized protocols for pod-to-base communication. Rajasthan and Uttar Pradesh district hospitals pilot modular configurations enabling equipment sharing across maternity and pediatric wards.
- Telemedicine:Cloud-connected platforms enabling remote specialist consultation. CDSCO's software-as-medical-device classifications extend licensing scrutiny to connectivity components, stretching compliance timelines.
Digital platforms anchor current installed base; wireless systems show the steepest expansion trajectory.
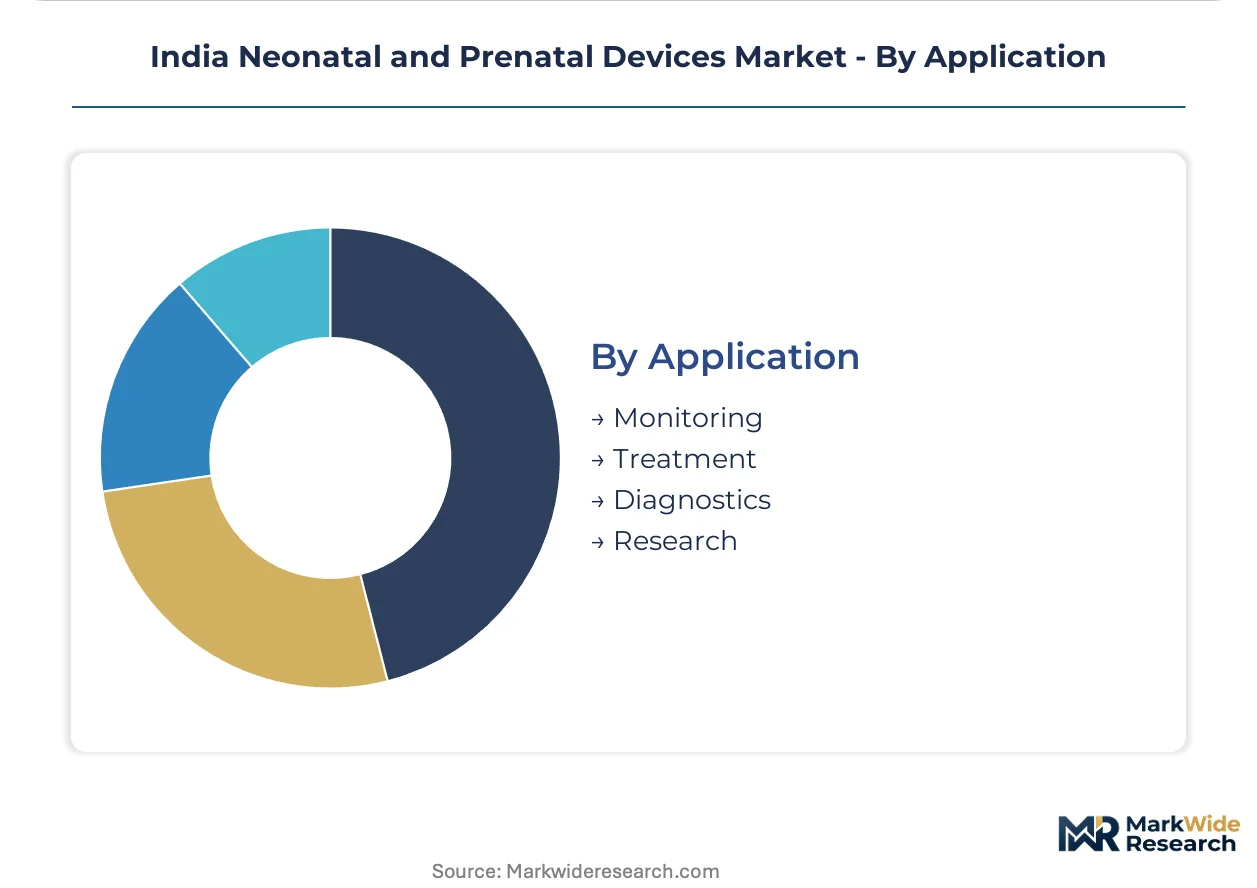
Application:
Application focus determines device specification priority, with monitoring and treatment functions absorbing capital deployment ahead of diagnostic or research configurations.
- Monitoring:Continuous physiological surveillance for cardiorespiratory stability and thermoregulation. Demand concentrates in district hospitals building NICU-grade capacity previously limited to metropolitan teaching centers.
- Treatment:Phototherapy for neonatal jaundice, respiratory support interfaces, and thermoregulation interventions. Government procurement cycles prioritize cost-engineered designs for scale deployment.
- Diagnostics:Fetal Doppler and imaging-based assessment tools. Portable configurations with 5G connectivity are opening access in tribal blocks of Madhya Pradesh and Chhattisgarh.
- Research:Specialized devices for clinical trial endpoints and academic investigation. Concentrated in Bengaluru, Hyderabad, and Chennai where biomedical engineering talent clusters.
Monitoring commands the largest capital allocation; diagnostics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Andhra Pradesh and Tamil Nadu concentrate thermoregulation system assembly, drawing PLI scheme incentives toward domestic component ecosystems.
Maharashtra
Mumbai and Pune teaching hospitals drive NICU-grade incubator procurement as specialist referral networks expand. CDSCO licensing mandates filter supplier pools for state tender participation. The Mumbai-Aurangabad corridor hosts engineering centers assembling servo-controlled warming systems for western India distribution.
Karnataka
Bengaluru's biomedical engineering talent cluster supports wireless monitor calibration and preventive maintenance capacity. State health mission funding equips district hospitals with telemetry systems previously limited to metropolitan centers. The Bengaluru-Mysuru belt anchors GE Healthcare's incubator assembly operations and domestic respiratory interface sourcing.
Tamil Nadu
Chennai medical device clusters specialize in phototherapy unit manufacturing for government procurement cycles. Koninklijke Philips distributes neonatal monitoring systems through southern India logistics networks anchored here. The Sriperumbudur-Oragadam industrial corridor concentrates ISO 13485-certified polymer component suppliers.
Gujarat
Ahmedabad and Surat district hospitals specify BIS certification requirements atop central CDSCO mandates for tender eligibility. State public health directorates enforce additional quality filters that narrow supplier pools for institutional purchasing. The Sanand-Vithalapur belt hosts emerging domestic assemblers cost-engineering respiratory devices for National Health Mission deployment.
Kerala
Thiruvananthapuram and Kochi facilities pioneer hub-and-spoke NICU networks delegating equipment selection to taluk-level clinical committees. State-level tender specifications layer biocompatibility-rated polymer standards above baseline regulatory requirements. The Kochi medical device park attracts component suppliers serving both domestic assembly and export markets.
India Neonatal and Prenatal Devices Market Competitive Landscape
United States and European producers anchor the premium-tier import segment; Indian domestic specialists hold cost-engineered government procurement positions. The supplier landscape bifurcates between CDSCO-licensed multinationals and PLI scheme beneficiaries building local assembly capacity. Three archetypes dominate: import-dependent platform vendors, domestic cost-optimizers, and regional distribution specialists. Competitive moves concentrate on Bengaluru engineering center investments and Kerala-Gujarat state tender pre-qualification racing.
Within the multinational tier, GE Healthcare and Koninklijke Philips exemplify import-anchored platform vendors sustaining local assembly through southern India engineering centers. Among domestic competitors, Phoenix Medical Systems occupies a position representing cost-engineered respiratory interface specialists competing for government procurement cycles. These three anchors illustrate the structural split between premium import dependence and PLI-scheme domestic assembly incentives reshaping supplier positioning across state-level tender markets.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips |
| Medtronic |
| Drägerwerk AG & Co. KGaA |
| Atom Medical Corporation |
| Natus Medical Incorporated |
| Fisher & Paykel Healthcare |
| Masimo |
| Phoenix Medical Systems |
| Others |
Pricing and Supply Chain Analysis
Wireless telemetry architectures are compressing both capital deployment cycles and supplier margin structures as district hospitals fragment procurement authority away from centralized state tenders. This technology shift simultaneously reduces per-bed equipment costs and redistributes pricing power toward regional distributors with technical advisory capacity.
Pricing Analysis
Short lead-time premiums command substantial markups over spot inventory discounts as CDSCO licensing timelines stretch 14-18 months for novel wireless monitors. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified multinationals from BIS-compliant domestic assemblers and uncertified gray-market imports. Cost compression in the economy tier is intensifying because PLI scheme beneficiaries are scaling local respiratory interface assembly. Government procurement cycles show highest price sensitivity; tertiary teaching hospitals with dedicated NICU infrastructure demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty chemical suppliers for ISO 10993-certified biocompatibility-rated polymers. Finished device assembly draws from India, China, and Malaysia; critical sensor components rest on South Korean and Taiwanese semiconductor foundries. Tariff exposure runs through legacy wired infrastructure imports requiring middleware investments for wireless protocol integration. Distribution runs through state-level tender boards in Kerala and Gujarat layering BIS requirements atop central mandates, alongside direct hospital procurement channels in Maharashtra and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CDSCO's tightened Medical Device Rules under the 2017 framework erect a formidable compliance moat, filtering supplier pools to CDSCO-licensed multinationals and PLI-scheme domestic assemblers while excluding undercapitalized entrants.
For Market Incumbents: Deepen backward integration into biocompatibility-rated polymer sourcing to reduce German and Japanese supplier dependency. Expand calibration and preventive maintenance capacity in Bengaluru, Hyderabad, and Chennai to capture service contract value from wireless telemetry deployments. Counter emerging domestic cost-optimizers by accelerating Kerala and Gujarat state tender pre-qualification racing before BIS certification mandates harden. For New Entrants and Emerging Players: Begin with homecare apnea monitoring rental channels in Gurugram, Noida, and Thane satellite townships where metro hospital referrals create compliance-aware patient populations. Target district hospitals in Rajasthan and Uttar Pradesh piloting modular sensor pod configurations for equipment sharing across maternity and pediatric wards. Pursue telemedicine-enabled monitor categories where CDSCO software-as-medical-device classifications have stretched incumbent compliance timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational platform vendors seeking southern India engineering center presence. Long-term viability favors domestic assemblers with demonstrated PLI scheme compliance and state tender pre-qualification in Kerala and Gujarat. Watch Ayushman Bharat reimbursement expansion into neonatal packages as the inflection signal reshaping device specification requirements at district hospitals.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Licensing Fast-Track Investment | Compresses 14-18 month approval timelines for wireless monitor categories ahead of competitors. |
| Kerala-Gujarat Tender Pre-Qualification | Secures first-mover advantage as state public health directorates layer BIS atop central mandates. |
| PLI Scheme Domestic Component Sourcing | Redirects capital toward local polymer and sensor assembly, compressing landed cost differentials. |
| Wireless Telemetry Platform Development | Captures value from software-integrated service contracts as hardware modularizes. |
| Biomedical Technician Training Pipeline | Addresses specialist scarcity constraining nationwide deployment velocity beyond southern clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committees, biomedical engineers, CDSCO regulatory affairs specialists, and GPO contracts managers combined with secondary validation from Medical Device Rules filings, PLI scheme beneficiary disclosures, and state tender documentation. Bottom-up district hospital equipment surveys and top-down National Health Mission funding allocation analysis provided triangulation.
Data-stream reconciliation across device type, end user, technology tier, and application dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from installed base growth rates, replacement cycles, and wireless adoption curves across Tier-II city hospital expansions. Ayushman Bharat reimbursement eligibility expansion and 5G rural connectivity deployment served as industry-specific demand inputs.
Underlying measurement precision varies by segment; wireless and telemedicine-enabled monitors carry tighter precision than legacy analog systems given clearer adoption trajectories. Forecasts reflect assumptions around CDSCO enforcement consistency, PLI scheme continuity, and National Health Mission funding stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Perinatal Software Market
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Infant Resuscitators Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Umbilical Market
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
Neonatal and Infant Care Equipment Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market
Neonatal Care
Global Preterm Birth and PROM Testing Market