
 Global Pulmonary Surfactant Market | 2026-2036
Global Pulmonary Surfactant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pulmonary Surfactant Market Foresight
Aftermarket service revenue from surfactant reconstitution training and NICU ventilation protocol consulting is narrowing as manufacturers bundle these services into direct procurement contracts. Chiesi Farmaceutici leverages its European manufacturing base to sustain supply continuity across multiple regulatory jurisdictions. ONY Biotech Inc. anchors its position through specialized production of porcine-derived natural surfactant formulations. Boehringer Ingelheim competes by extending its respiratory portfolio into adjacent critical-care segments.
Pulmonary surfactant comprises a complex mixture of phospholipids and surfactant proteins that reduce surface tension at the alveolar air-liquid interface, with dipalmitoylphosphatidylcholine constituting the primary functional lipid component and manufacturing requiring controlled organic extraction or recombinant protein expression systems. Its primary commercial purpose centers on preventing alveolar collapse in preterm infants and supporting oxygenation in acute lung injury patients. Natural surfactant dominates current procurement volumes due to established clinical efficacy profiles, while recombinant surfactant represents the fastest-growing product category as protein engineering advances reduce immunogenicity concerns. Intratracheal instillation remains the standard delivery mode in neonatal intensive care units, though aerosolized inhalation is gaining traction in specialized respiratory centers seeking less invasive administration protocols.
The FDA maintains stringent lot-release testing requirements for biologic surfactants, while the EMA's MDR framework imposes enhanced clinical evidence standards for neonatal indications. ISO 13485 certification has become a baseline expectation for contract manufacturers serving this market, with WHO prequalification pathways opening access in lower-resource settings. Stakeholders must monitor evolving reimbursement thresholds for synthetic versus natural formulations as health technology assessment bodies recalibrate cost-effectiveness benchmarks for preterm respiratory interventions.
Market Dynamics
The FDA and EMA have synchronized their post-market surveillance timelines for biologic surfactants, compressing manufacturer response windows and accelerating migration toward recombinant production platforms that bypass porcine-derived supply dependencies.
Growth Catalysts
- Preterm birth protocol intensification:Level III and IV NICU networks in the United States and Germany now mandate prophylactic surfactant administration below 28 weeks gestation, institutionalizing procurement volumes.
- EMA MDR framework alignment:Enhanced clinical evidence standards for neonatal indications are forcing portfolio rationalization that favors manufacturers with robust pharmacovigilance infrastructure.
- Recombinant protein engineering:Advances in surfactant protein B and C expression systems are reducing immunogenicity profiles that previously constrained synthetic formulation adoption.
Market Restraints
- Porcine-derived input concentration:Over 70% of natural surfactant manufacturing relies on controlled organic extraction from lung tissue, creating vulnerability to livestock disease outbreaks and slaughterhouse supply fluctuations.
- Lot-release testing burden:The FDA's stringent biologic release requirements extend production cycles by 4-6 weeks, constraining just-in-time inventory models for critical-care applications.
- Surfactant protein synthesis complexity:Recombinant alternatives require mammalian cell culture systems with yields below 50% of theoretical maximum, elevating unit economics above natural formulation parity.
Strategic Opportunities
- WHO prequalification pathway expansion:Lower-resource settings in sub-Saharan Africa and South Asia present procurement openings as national health systems adopt international quality benchmarks for neonatal respiratory interventions.
- Aerosolized delivery platform development:Specialized respiratory centers in Japan and Australia are piloting non-invasive administration protocols that could extend surfactant therapy beyond intubated populations.
- Critical-care portfolio bundling:Adjacent ventilation and hemodynamic monitoring integration creates contract consolidation leverage for manufacturers with multi-product respiratory suites.
Industry Challenges
- ISO 13485 certification scarcity:Contract manufacturers with combined biologic processing and sterile fill-finish capabilities remain concentrated among fewer than 15 qualified facilities globally.
- Phospholipid supply reconfiguration:Dipalmitoylphosphatidylcholine sourcing from egg yolk and synthetic routes requires dual-qualified suppliers, complicating geographic diversification strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pulmonary Surfactant Market |
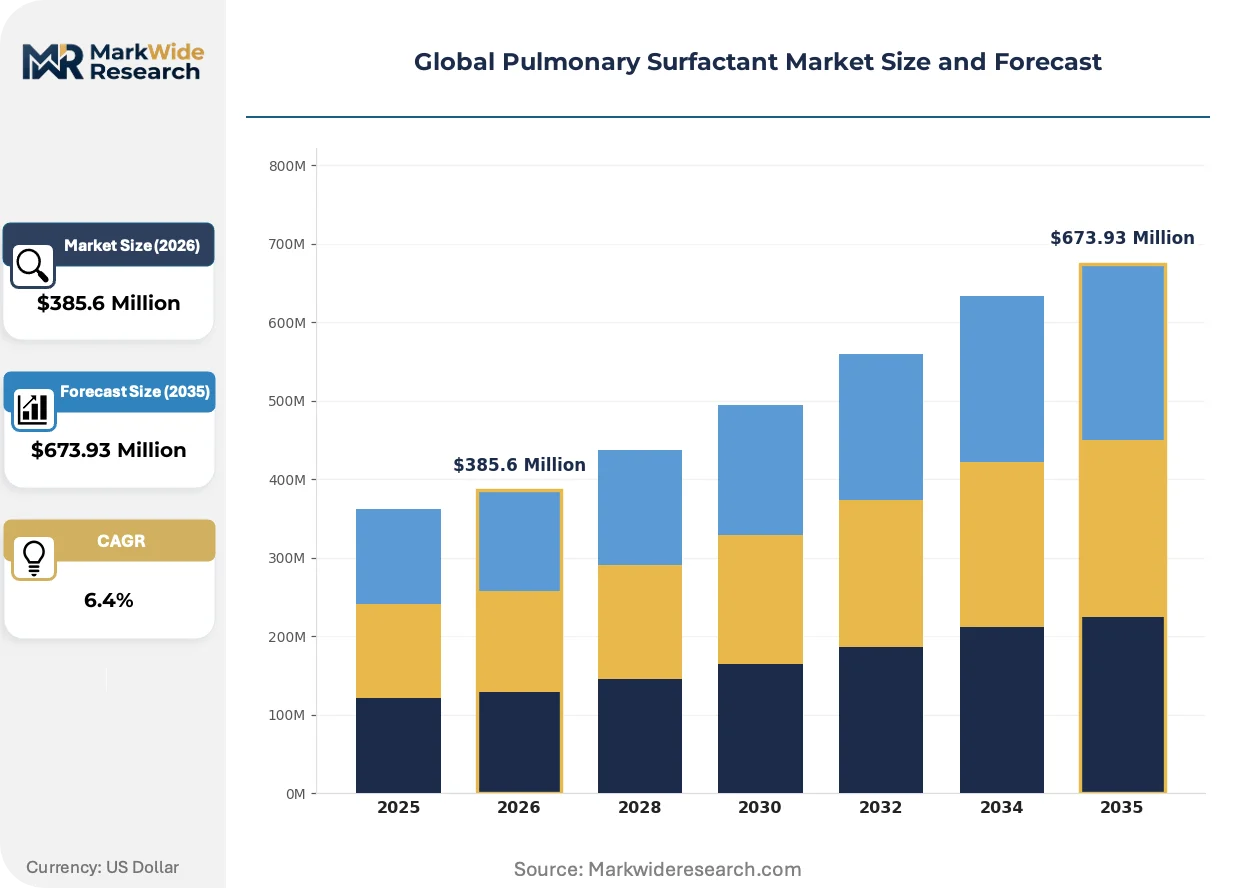
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Surfactant, Synthetic Surfactant, Modified Synthetic Surfactant, Recombinant Surfactant Therapy Area: Neonatal Respiratory Distress Syndrome, Acute Respiratory Distress Syndrome, Meconium Aspiration Syndrome, Pulmonary Alveolar Proteinosis End User: Neonatal Intensive Care Units, Pediatric Clinics, Pulmonology Departments, Specialized Respiratory Centers Delivery Mode: Intratracheal Instillation, Aerosolized Inhalation, Liquid Bolus, Nebulization |
| Companies Covered | Chiesi Farmaceutici, ONY Biotech Inc., AbbVie Inc., Boehringer Ingelheim, Lyomark Pharma, Windtree Therapeutics, Aviva Systems Biology Corporation, Abbott, Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pulmonary Surfactant Market Shifts & Advancements
Recombinant and modified synthetic surfactant platforms are compressing the traditional natural-to-synthetic transition timeline, while regulatory convergence across North America and Europe is rewriting manufacturer compliance architectures.
Next-generation surfactant formulations are hybridizing phospholipid matrices with engineered surfactant protein analogs to replicate natural surface-tension dynamics without porcine tissue dependencies. Level IV NICU procurement committees in the United States and Germany are accelerating pilot evaluations of these hybridized candidates. The technology is hybridizing competitive positioning by enabling manufacturers without animal-source infrastructure to enter premium segments previously locked by clinical efficacy data.
The EMA's MDR framework now requires prospective clinical evidence for neonatal respiratory indications, eliminating grandfathered approvals that sustained legacy natural surfactant portfolios for decades. Manufacturers must now maintain active pharmacovigilance systems capable of detecting rare adverse events in preterm populations below 1,500 grams. Synthetic and recombinant product categories face disproportionate scrutiny as health technology assessment bodies in France and the United Kingdom recalibrate reimbursement thresholds against cost-effectiveness benchmarks.
Service unbundling is reversing across the surfactant value chain as manufacturers absorb reconstitution training and ventilation protocol consulting into direct procurement contracts. Aftermarket revenue streams that previously sustained specialized clinical education firms are collapsing into bundled pricing models. This consolidation is most visible in United States Level III NICU networks, where group purchasing organizations now mandate turnkey implementation support as a contract precondition.
Global Pulmonary Surfactant Market Segmentation
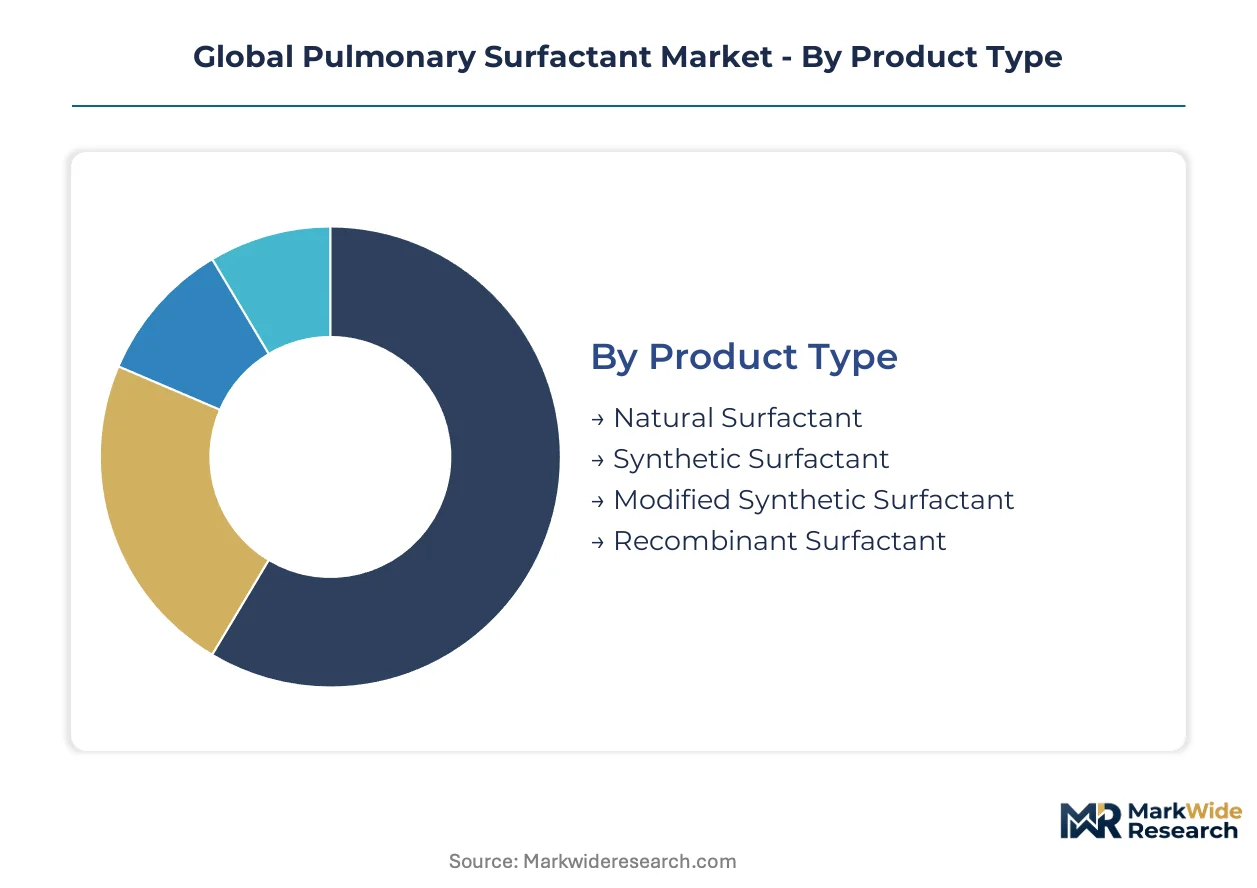
Pulmonary surfactant procurement patterns diverge sharply across product origin, clinical indication, and care setting. Manufacturers configure supply chains and regulatory submissions around these divisions because reimbursement pathways and technical specifications vary substantially between segments.
Product Type:
Cost tier differentiation separates mature extraction-based formulations from engineered alternatives with complex manufacturing economics.
- Natural Surfactant:Controlled organic extraction from porcine lung tissue yields phospholipid-protein complexes with established surface-tension dynamics. Procurement concentrates in United States Level III and IV NICU networks where prophylactic protocols below 28 weeks gestation sustain volume commitments.
- Recombinant Surfactant:Mammalian cell culture expression of surfactant proteins B and C enables protein engineering that reduces immunogenicity profiles. German and Japanese respiratory centers are piloting these formulations as EMA MDR frameworks intensify post-market surveillance of biologic sources.
- Synthetic Surfactant:Dipalmitoylphosphatidylcholine-based formulations without protein components serve cost-sensitive procurement channels in lower-resource settings.
- Modified Synthetic Surfactant:Hybrid phospholipid matrices incorporate peptide analogs to replicate natural surface activity without animal tissue dependencies.
Natural surfactant commands the established base. The steepest expansion runs through recombinant surfactant.
Therapy Area:
Application severity determines dosing protocols, reimbursement thresholds, and the competitive intensity of clinical evidence requirements.
- Neonatal Respiratory Distress Syndrome:Preterm infants below 1,500 grams birth weight require immediate intratracheal administration to prevent alveolar collapse. United States and German NICU networks now mandate prophylactic administration protocols that institutionalize procurement volumes.
- Acute Respiratory Distress Syndrome:Adult critical-care populations with COVID-19, sepsis, or trauma-induced lung injury present dosing challenges due to larger pulmonary surface area requirements. Specialized respiratory centers in Australia and Japan are evaluating aerosolized delivery protocols for this indication.
- Meconium Aspiration Syndrome:Term infants with compromised airways require rescue surfactant therapy following failed ventilation support.
- Pulmonary Alveolar Proteinosis:Rare autoimmune presentations necessitate whole-lung lavage adjuncts with surfactant supplementation.
Neonatal respiratory distress syndrome anchors procurement volume. Acute respiratory distress syndrome is climbing the fastest as adult critical-care applications expand.
End User:
Customer type shapes service bundling requirements, training intensity, and contract consolidation leverage.
- Neonatal Intensive Care Units:Level III and IV facilities in the United States operate under group purchasing organization contracts that mandate turnkey implementation support including reconstitution training and ventilation protocol consulting.
- Specialized Respiratory Centers:Tertiary facilities in Japan and Australia pilot aerosolized inhalation delivery and non-invasive administration protocols that extend therapy beyond intubated populations.
- Pediatric Clinics:Outpatient follow-up settings manage post-discharge respiratory monitoring for surfactant-treated infants.
- Pulmonology Departments:General hospital divisions handle acute respiratory distress syndrome presentations with standardized intratracheal protocols.
Neonatal intensive care units dominate procurement concentration. Specialized respiratory centers are gaining share fastest through delivery innovation.
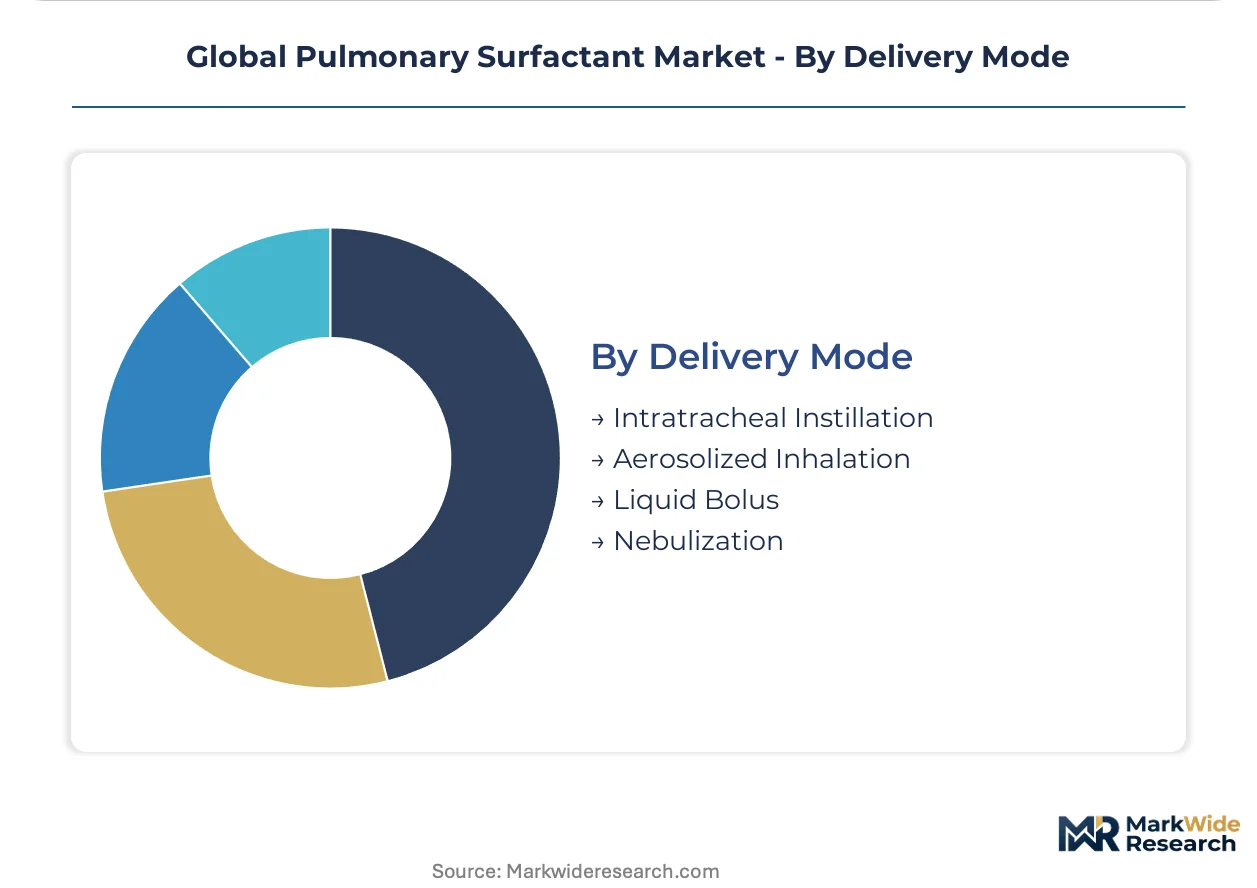
Delivery Mode:
Volume and invasiveness trade-offs define technology adoption curves across care settings with varying ventilation infrastructure.
- Intratracheal Instillation:Direct instillation via endotracheal tube remains the standard for preterm infants requiring immediate alveolar stabilization. United States Level III NICU networks maintain this as the default protocol for gestational ages below 32 weeks.
- Aerosolized Inhalation:Nebulized phospholipid suspensions enable non-invasive administration for patients with intact respiratory drive. Japanese specialized respiratory centers are advancing clinical evaluations of this modality for acute lung injury populations.
- Liquid Bolus:Rapid instillation techniques reduce administration time in emergency neonatal resuscitation scenarios.
- Nebulization:Continuous aerosol generation systems support prolonged therapy in adult critical-care ventilator circuits.
Intratracheal instillation commands the established base. Aerosolized inhalation shows the steepest expansion trajectory as minimally invasive protocols advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States and Germany institutionalize prophylactic surfactant protocols in Level III and IV NICU networks, while Japan and Australia pioneer aerosolized delivery alternatives, and India expands access through WHO prequalification pathways.
United States
Level III and IV NICU networks in Texas, California, and the Northeast Corridor mandate prophylactic surfactant administration below 28 weeks gestation, locking in procurement volumes through group purchasing organization contracts. FDA lot-release testing requirements extend production cycles by 4-6 weeks, compressing inventory flexibility for critical-care applications. The Boston-Cambridge biotech corridor hosts recombinant protein engineering facilities advancing surfactant protein B and C expression systems.
Germany
Specialized respiratory centers in Bavaria and North Rhine-Westphalia pilot hybrid phospholipid-peptide formulations as EMA MDR frameworks eliminate grandfathered approvals for legacy natural surfactants. The country's national pharmaceutical regulator now requires prospective clinical evidence for neonatal respiratory indications, forcing portfolio rationalization toward robust pharmacovigilance infrastructure. Berlin-Brandenburg hosts contract manufacturers with ISO 13485 certification for biologic processing and sterile fill-finish capabilities.
Japan
Tertiary facilities in the Kanto and Kansai regions advance clinical evaluations of aerosolized inhalation delivery for acute lung injury populations, extending surfactant therapy beyond intubated patients. METI supports domestic recombinant protein production initiatives to reduce import dependency for neonatal intensive care inputs. The Tokyo-Osaka medical device corridor concentrates specialized respiratory centers piloting non-invasive administration protocols.
Australia
Specialized respiratory centers in New South Wales and Victoria evaluate nebulized phospholipid suspensions for adult critical-care ventilator circuits, targeting acute respiratory distress syndrome presentations. TGA post-market surveillance aligns with FDA-EMA synchronization timelines, accelerating manufacturer compliance investments. The Sydney-Melbourne hospital network serves as a clinical trial hub for minimally invasive surfactant delivery technologies.
India
National health systems in Maharashtra and Karnataka adopt WHO prequalification pathways for neonatal respiratory interventions, opening procurement channels previously restricted by quality benchmarks. CDSCO streamlined approval processes for recombinant biologics reduce entry timelines for synthetic surfactant alternatives. The Hyderabad-Bengaluru pharmaceutical manufacturing belt hosts contract facilities seeking ISO 13485 certification to serve export markets.
Global Pulmonary Surfactant Market Competitive Landscape
Capability concentration sits with manufacturers possessing mammalian cell culture expertise; scale advantage sits with incumbents leveraging decades of natural surfactant extraction infrastructure. The market structures around three tiers: porcine-derived natural formulators with established clinical efficacy data, recombinant protein engineers reducing immunogenicity profiles, and synthetic phospholipid producers serving cost-sensitive channels. Dominant competitive moves include backward integration into phospholipid supply chains and captive supply of surfactant protein expression systems.
Within the natural surfactant tier, ONY Biotech Inc. and Chiesi Farmaceutici occupy positions anchored by controlled organic extraction capabilities and multi-jurisdictional regulatory submissions. Boehringer Ingelheim sits within the respiratory portfolio bundling archetype, extending critical-care presence through adjacent ventilation and hemodynamic monitoring integration. These three represent the competitive core: ONY Biotech Inc. exemplifies specialized porcine-derived production, Chiesi Farmaceutici represents European manufacturing base leverage, and Boehringer Ingelheim anchors multi-product respiratory suite consolidation.
| Leading Market Players |
|---|
| Chiesi Farmaceutici |
| ONY Biotech Inc. |
| AbbVie Inc. |
| Boehringer Ingelheim |
| Lyomark Pharma |
| Windtree Therapeutics |
| Aviva Systems Biology Corporation |
| Abbott |
| Baxter International Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in mammalian cell culture facilities across Germany and Japan is compressing supplier flexibility and hardening pricing postures for recombinant surfactant formulations. Contract manufacturers with ISO 13485 certification for biologic processing command premium positioning as FDA lot-release testing extends production cycles and locks buyers into longer commitment windows.
Pricing Analysis
Long-term offtake agreements dominate procurement between United States Level III NICU networks and natural surfactant suppliers, insulating incumbents from spot-market volatility while compressing margins for synthetic alternatives. Three-tier pricing structure across premium recombinant, standard natural, and economy synthetic levels reflects certification grade and pharmacovigilance infrastructure investment. Cost compression in synthetic phospholipid sourcing is intensifying because dipalmitoylphosphatidylcholine supply reconfiguration demands dual-qualified egg yolk and synthetic route suppliers. Group purchasing organizations in the United States exhibit lowest price sensitivity due to bundled service mandates, while Indian national health systems adopting WHO prequalification pathways drive hardest volume negotiations.
Supply Chain Analysis
Tariff exposure between United States and European Union pharmaceutical inputs complicates phospholipid sourcing strategies for manufacturers serving both FDA and EMA jurisdictions. Manufacturing concentrates in Italy, Germany, and the United States for natural surfactant extraction, with recombinant production anchored in Japanese and German mammalian cell culture facilities. Raw material dependencies center on porcine lung tissue from controlled slaughterhouse supply chains, egg yolk phospholipid fractions, and engineered surfactant protein expression systems. Single-source vulnerability in porcine-derived inputs creates exposure to livestock disease outbreaks. Distribution runs through hospital system group purchasing organizations in developed markets and WHO prequalification procurement channels in lower-resource settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant surfactant adoption sits at early-cycle expansion as EMA MDR frameworks eliminate grandfathered approvals and force clinical evidence regeneration across legacy portfolios. Penetration tailwinds concentrate in specialized respiratory centers piloting aerosolized delivery protocols beyond traditional intubated populations.
For Market Incumbents: Insulate natural surfactant revenue streams through captive supply of porcine tissue processing capacity and backward integration into phospholipid extraction infrastructure. Accelerate pharmacovigilance system upgrades to meet EMA prospective clinical evidence requirements before competitor portfolios rationalize. The recombinant protein engineering threat from mammalian cell culture specialists demands defensive patent positioning around surfactant protein B and C analog formulations. For New Entrants and Emerging Players: Indian national health systems and sub-Saharan African procurement channels represent the most penetrable entry points for synthetic and modified synthetic surfactant alternatives lacking legacy clinical data. Specialized respiratory centers in Japan and Australia offer white-space access through aerosolized delivery platform partnerships bypassing established intratracheal instillation incumbents. A go-to-market angle anchored to WHO prequalification pathway navigation and turnkey clinical training bundling unlocks volume commitments from quality-constrained buyers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recombinant surfactant manufacturing as mammalian cell culture yield optimization and sterile fill-finish capability scarcity concentrate investment requirements. Long-term viability over the next decade favors manufacturers with hybrid natural-recombinant portfolios capable of serving both prophylactic NICU protocols and emerging adult critical-care indications. Acquisition target archetypes include ISO 13485-certified contract manufacturers with biologic processing capabilities and specialized respiratory centers with aerosolized delivery clinical data repositories. The signal to watch is EMA MDR enforcement velocity against legacy natural surfactant portfolios as a trigger for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Protein Engineering Scale-Up | Mammalian cell culture yield advances reduce immunogenicity profiles below natural formulation parity. |
| EMA MDR Compliance Pathway Investment | Prospective clinical evidence generation secures neonatal indication continuity under tightened frameworks. |
| Aerosolized Delivery Platform Development | Japanese specialized respiratory centers pilot non-invasive protocols extending therapy beyond intubated populations. |
| WHO Prequalification Procurement Channel Entry | Indian and sub-Saharan African national health systems unlock volume through quality benchmark adoption. |
| Phospholipid Supply Backward Integration | Captive dipalmitoylphosphatidylcholine sourcing insulates against egg yolk and synthetic route volatility. |
Research Methodology
Desk research of FDA lot-release testing documentation, EMA MDR framework guidance, and WHO prequalification pathway specifications preceded structured interviews with neonatal intensive care unit procurement managers, regulatory affairs leads at surfactant manufacturers, and formulary directors at United States group purchasing organizations. Secondary validation drew from ClinicalTrials.gov surfactant therapy registrations, hospital procurement database extracts, and CMS Medicare neonatal respiratory intervention reimbursement schedules. Bottom-up demand modeling across product type, therapy area, and end-user segments triangulated against top-down pharmaceutical market sizing from trade data and SEC pharmaceutical segment disclosures.
Assumption sets held regulatory enforcement timelines and prophylactic protocol adoption rates fixed while varying recombinant protein engineering yield trajectories and aerosolized delivery clinical trial outcomes across the projection horizon. Segmentation dimensions modeled included product origin tier, clinical indication severity, NICU facility level, and regional regulatory cluster. CAGRs derived from volume-weighted average price projections and indication-specific dosing protocol penetration curves. Industry-specific forecast inputs incorporated porcine tissue supply chain stability indices and mammalian cell culture capacity utilization surveys.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement austerity measures or livestock disease outbreak frequency would shift the trajectory. Forecasts reflect documented assumptions regarding EMA MDR grandfathering elimination schedules and WHO prequalification expansion velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Asia Pacific Respiratory Therapeutic Devices Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Global Oxygen Therapy Market
Respiratory Therapy
Emphysema Treatment Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Human Respiratory Syncytial Virus (RSV) Treatment Market