
 Bronchopulmonary Dysplasia Treatment Market | 2026-2036
Bronchopulmonary Dysplasia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bronchopulmonary Dysplasia Treatment Market Analysis
Palivizumab is broadening prophylactic options for respiratory syncytial virus in premature infants at BPD risk. Chiesi Farmaceutici S.p.A. leverages its European neonatology franchise to sustain leadership in surfactant therapies across high-volume NICUs. AbbVie Inc. anchors its position through immunomodulatory pipelines that address inflammatory lung injury in preterm neonates.
Bronchopulmonary Dysplasia Treatment encompasses pharmacologic and supportive interventions targeting alveolar and vascular development arrest in premature infants, typically administered via mechanical ventilation or non-invasive respiratory support with supplemental oxygen titration. The primary purpose is to reduce mortality and long-term pulmonary morbidity in neonates born before 32 weeks gestation. Medications command the largest revenue share as diuretics, bronchodilators, and corticosteroids constitute chronic maintenance protocols. Inhalation delivery dominates clinical practice because nebulized and intratracheal instillation routes achieve direct pulmonary deposition while minimizing systemic exposure in low-birth-weight patients.
The FDA oversees orphan drug exclusivity and pediatric investigation plans that shape development economics for BPD therapeutics, while the EMA's Paediatric Regulation mandates juvenile study requirements for products seeking European market authorization. These frameworks elevate R&D costs but extend market protection periods for sponsors that complete mandated trials. Stakeholders must monitor evolving neonatal ventilation protocols and surfactant biosimilar entries that could redistribute value across the treatment continuum.
Market Dynamics
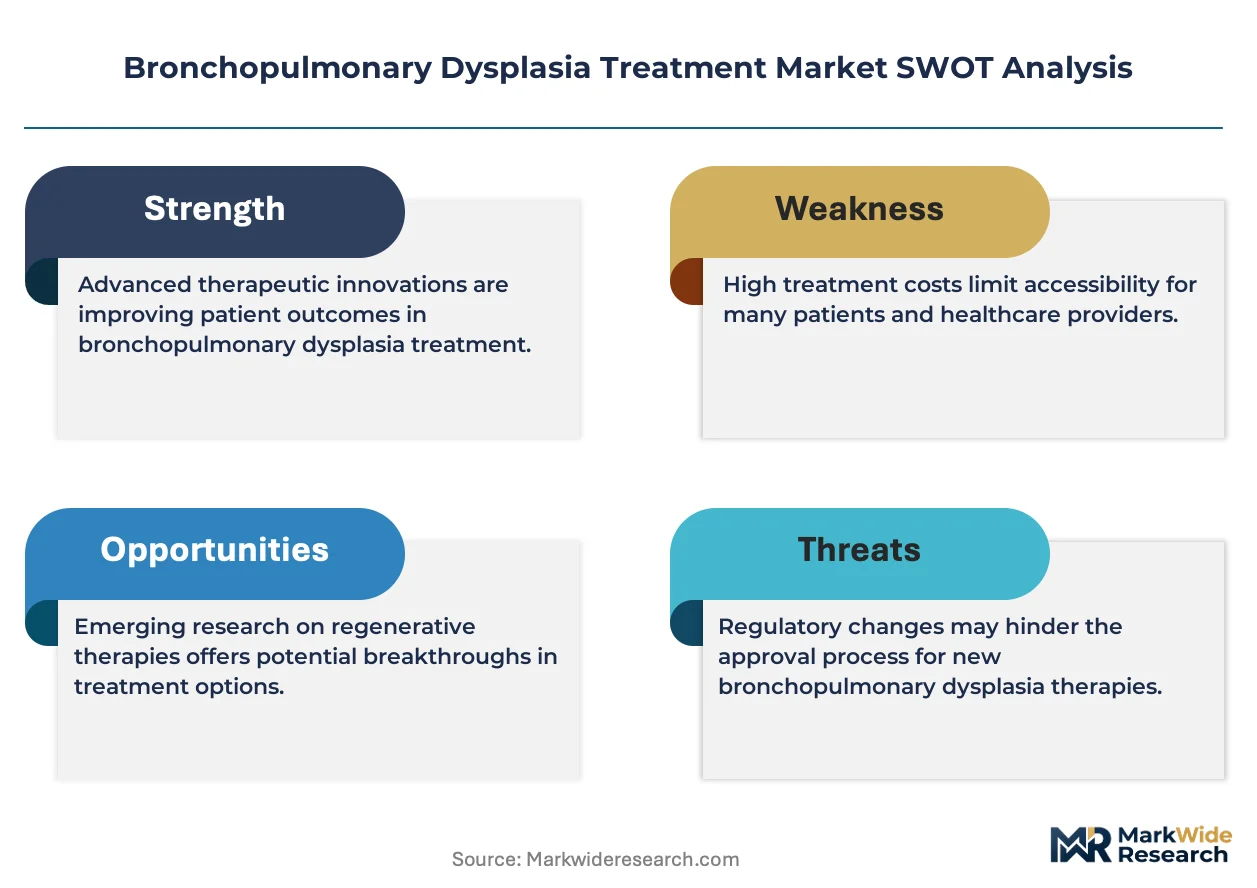
FDA orphan drug exclusivity rules are compressing development timelines for BPD-specific therapeutics while surfactant biosimilar entries threaten to redistribute value across the neonatal respiratory care continuum.
Growth Catalysts
- Orphan Drug Designation:The FDA's accelerated approval pathway extends market protection periods for sponsors completing pediatric investigation plans, incentivizing R&D for neonatal indications.
- NICU Infrastructure Expansion:Pediatric hospitals in the United States are commissioning additional neonatal intensive care units to address premature birth caseloads.
- Surfactant Replacement Protocols:Intratracheal instillation methods achieve direct pulmonary deposition in low-birth-weight patients, driving clinical adoption of nebulized delivery systems.
Market Restraints
- Juvenile Study Mandates:The EMA's Paediatric Regulation imposes mandatory juvenile toxicity requirements that elevate R&D costs for European market authorization.
- Surfactant Supply Concentration:European manufacturers dominate porcine-derived surfactant raw material sourcing, creating geographic dependency for biosimilar developers.
- Mechanical Ventilation Limitations:Prolonged invasive respiratory support causes ventilator-induced lung injury, constraining therapeutic windows for pharmacologic intervention.
Strategic Opportunities
- Non-Invasive Respiratory Support:Continuous positive airway pressure devices and high-flow nasal cannula systems are displacing mechanical ventilation in Level II NICUs.
- Immunomodulatory Pipelines:Corticosteroid-sparing anti-inflammatory agents target alveolar development arrest without the neurodevelopmental risks of systemic dexamethasone.
- Regional NICU Networks:Telemedicine-integrated transport systems connect community birth centers with tertiary pediatric hospitals in rural United States counties.
Industry Challenges
- Neonatal Pharmacology Expertise:Pediatric formulation scientists and neonatal clinical pharmacologists remain scarce relative to adult therapeutic development programs.
- Longitudinal Outcome Tracking:Pulmonary function assessment protocols for preterm infants lack standardization across multicenter trial networks, complicating endpoint validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bronchopulmonary Dysplasia Treatment Market |
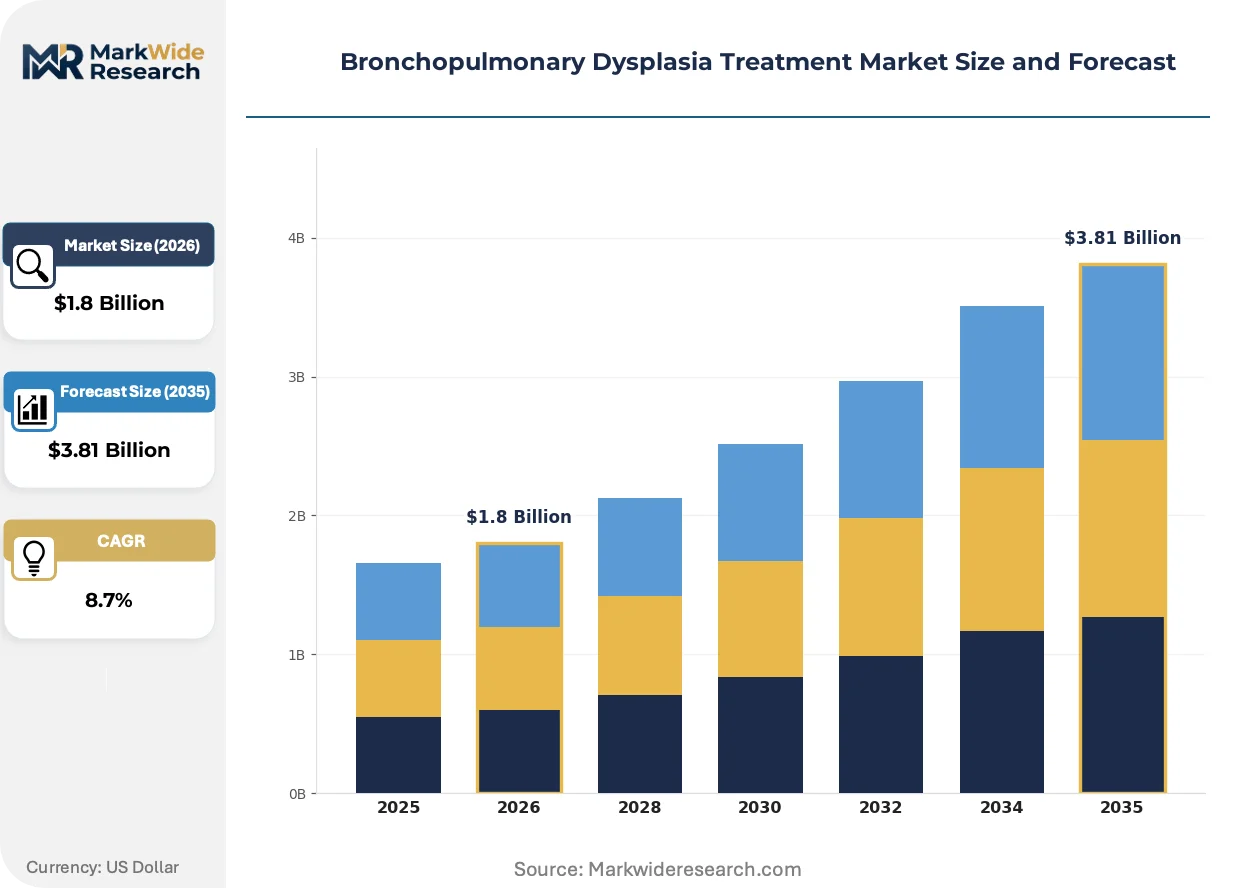
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Therapies, Devices, Nutritional Support Delivery Mode: Inhalation, Oral, Intravenous, Sublingual End User: Pediatric Hospitals, Clinics, Home Care, Rehabilitation Centers Age Group: Neonates, Infants, Toddlers, Children |
| Companies Covered | Chiesi Farmaceutici S.p.A., Airway Therapeutics, MediPost, Therabron Therapeutics, AbbVie Inc., Oak Hill Bio, Insmed Inc., GlaxoSmithKline plc, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bronchopulmonary Dysplasia Treatment Market Emerging Trajectories
Neonatal respiratory care is pivoting from facility-based mechanical ventilation toward distributed monitoring and home-based oxygen weaning protocols that extend therapeutic oversight beyond hospital walls.
Point-of-care lung ultrasound is decentralizing pulmonary assessment in NICU settings. Neonatology teams at tertiary pediatric centers are adopting bedside imaging to reduce radiation exposure from serial chest radiographs. This modality is decentralizing diagnostic workflow from radiology suites to patient bays, compressing turnaround times for treatment adjustment decisions.
The FDA's pediatric investigation plan requirements are mandating juvenile toxicology studies for all new molecular entities with potential neonatal indications. Drug sponsors must complete age-appropriate pharmacokinetic trials before labeling claims for preterm populations. Small-molecule developers targeting inflammatory lung injury are responding by embedding neonatal cohorts into Phase II adaptive trial designs.
Home oxygen weaning programs are restructuring post-discharge respiratory care for BPD survivors. Regional perinatal networks in the United States are deploying pulse oximetry telemetry and home nursing visits to accelerate ventilator liberation. Texas and California Medicaid programs now reimburse remote monitoring for chronic supplemental oxygen dependence, shifting cost accountability from inpatient facilities to outpatient management entities.
Bronchopulmonary Dysplasia Treatment Market Segmentation
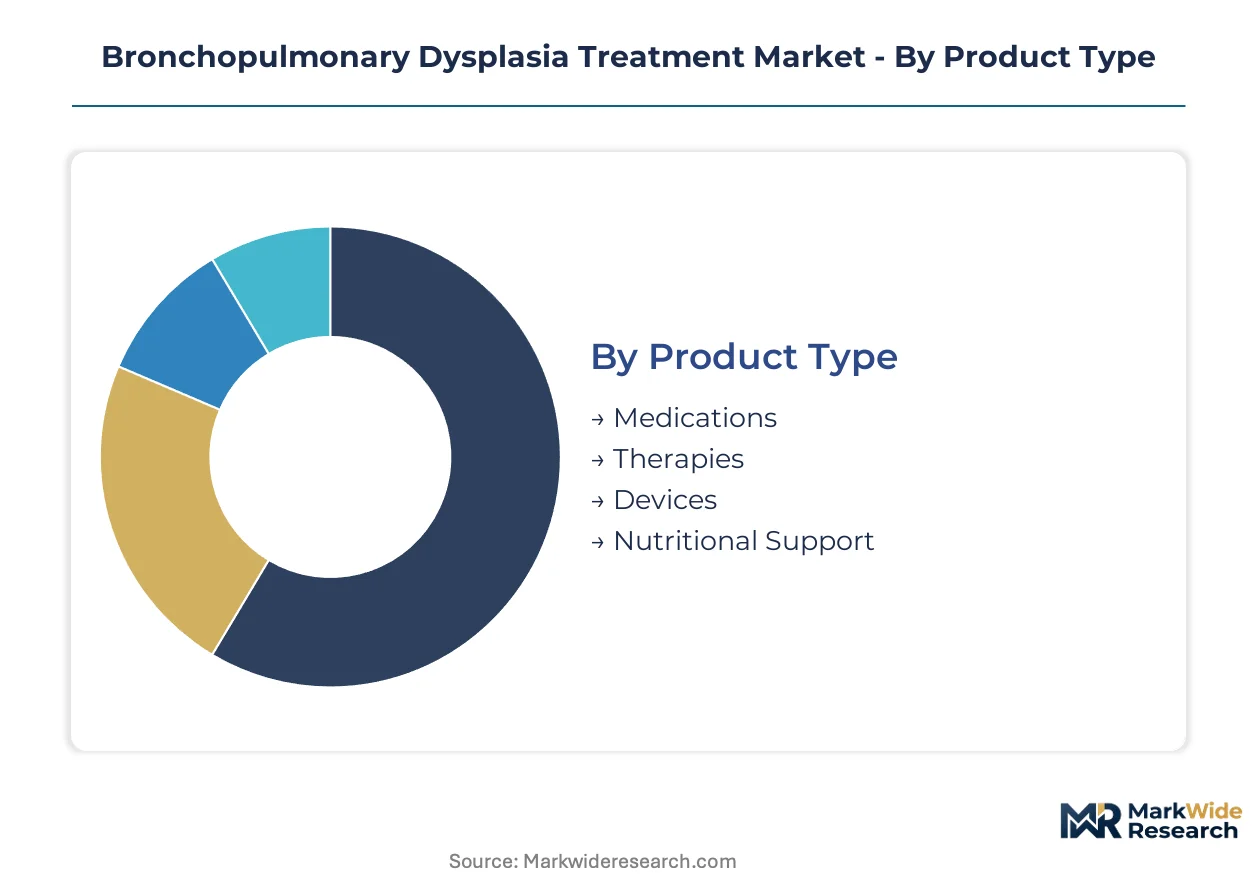
Segmentation in the Bronchopulmonary Dysplasia Treatment Market reveals distinct procurement patterns across product categories and care settings. Manufacturers configure development pipelines around delivery constraints in low-birth-weight populations while reimbursement frameworks shape adoption velocity across institutional tiers.
Product Type:
Supply concentration in surfactant manufacturing elevates strategic importance for formulations addressing alveolar development arrest in preterm neonates.
- Medications:Diuretics, bronchodilators, and corticosteroids constitute chronic maintenance protocols administered via nebulized or intratracheal routes. Demand concentrates in Level III NICUs within the United States where prolonged ventilation protocols drive pharmaceutical dependency for inflammatory lung injury management.
- Therapies:Surfactant replacement interventions achieve direct pulmonary deposition through intratracheal instillation methods. European manufacturers dominate porcine-derived raw material sourcing, creating geographic concentration for biosimilar developers targeting cost-sensitive procurement committees.
- Devices:Continuous positive airway pressure systems and high-flow nasal cannula hardware enable non-invasive respiratory support. FDA 510(k) clearance pathways govern market entry for neonatal ventilation equipment.
- Nutritional Support:Specialized enteral formulations address growth failure in BPD survivors requiring caloric density optimization. Home care discharge planning drives post-NICU demand for feeding protocols.
Today's leader: Medications. Tomorrow's challenger: Therapies.
Delivery Mode:
Cost tier differentiation separates premium nebulized systems from commodity oral administration in reimbursement-sensitive neonatal populations.
- Inhalation:Nebulized and intratracheal instillation routes achieve direct pulmonary deposition while minimizing systemic exposure in low-birth-weight patients. This mode dominates clinical practice across tertiary pediatric centers in the United States.
- Oral:Enteral administration of diuretics and bronchodilators supports chronic maintenance after ventilator weaning. Medicaid reimbursement frameworks in Texas and California shape formulary positioning for outpatient protocols.
- Intravenous:Systemic corticosteroid delivery addresses acute inflammatory exacerbations in NICU settings. FDA pediatric investigation plans mandate juvenile pharmacokinetic studies for IV formulations.
- Sublingual:Emerging absorption technologies target rapid onset without respiratory tract instrumentation. Limited clinical validation constrains adoption in standard-of-care protocols.
Inhalation commands current volume. Sublingual formats are climbing the fastest in development pipelines.
End User:
Application concentration in tertiary pediatric centers creates procurement leverage for integrated device-pharmaceutical bundles.
- Pediatric Hospitals:Level III and IV NICUs anchor demand for surfactant replacement and mechanical ventilation systems. Commissioning of additional neonatal intensive care units across the United States sustains infrastructure expansion.
- Clinics:Outpatient pulmonary follow-up for BPD survivors drives bronchodilator prescribing and growth monitoring. Regional perinatal networks connect community settings with tertiary referral pathways.
- Home Care:Remote pulse oximetry telemetry and nursing visits accelerate ventilator liberation for chronic oxygen-dependent infants. Texas and California Medicaid programs now reimburse home monitoring services.
- Rehabilitation Centers:Post-acute respiratory therapy addresses neurodevelopmental sequelae in severe BPD cases. Limited penetration reflects reimbursement fragmentation across state-level programs.
Pediatric hospitals dominate current spend. Home care infrastructure represents the steepest expansion trajectory in post-discharge models.
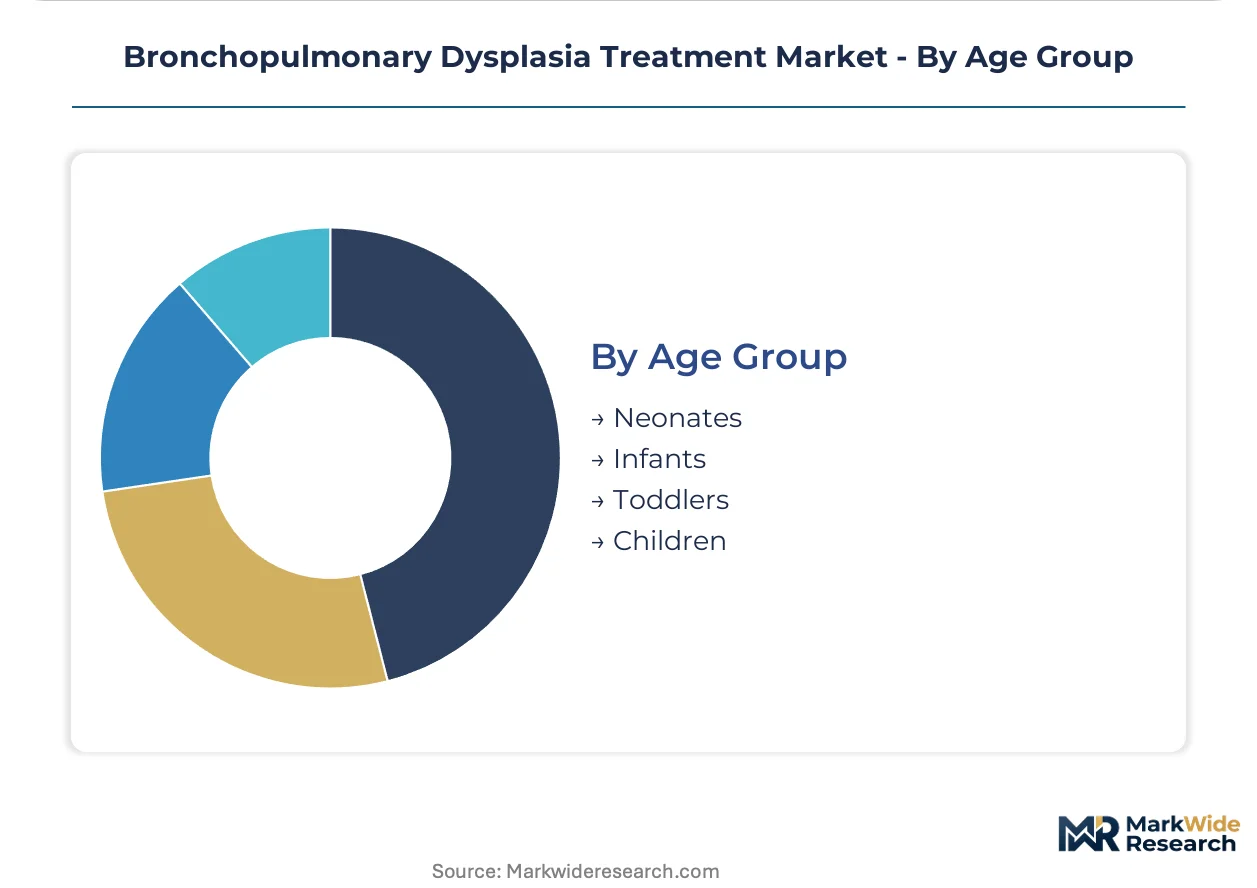
Age Group:
Volume concentration in neonatal populations constrains formulation development economics relative to broader pediatric indications.
- Neonates:Infants born before 32 weeks gestation constitute the primary addressable population for surfactant replacement and preventive corticosteroid protocols. FDA orphan drug designation pathways accelerate development timelines for this cohort.
- Infants:Post-discharge respiratory management addresses chronic oxygen dependence and reactive airway disease. Home oxygen weaning programs in the United States target this transition window.
- Toddlers:Long-term pulmonary morbidity surveillance captures airway reactivity and growth restriction sequelae. EMA Paediatric Regulation mandates juvenile toxicity requirements that elevate study costs for European authorization.
- Children:School-age respiratory function assessment protocols lack standardization across multicenter networks, complicating endpoint validation for late-intervention trials.
Neonates anchor therapeutic development. Infants are gaining share fastest as home-based monitoring extends intervention windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric hospitals in the United States anchor demand for surfactant replacement therapies and mechanical ventilation systems, while regulatory frameworks in Europe and Asia-Pacific shape development economics for neonatal indications.
United States
Level III and IV NICUs in Texas and California commission additional neonatal intensive care units to address premature birth caseloads. FDA orphan drug designation pathways accelerate approval timelines for BPD-specific therapeutics. Tertiary pediatric centers in the Boston and Houston metro areas deploy point-of-care lung ultrasound to reduce radiation exposure from serial chest radiographs.
Germany
EMA Paediatric Regulation mandates juvenile toxicity studies that elevate R&D costs for neonatal formulations seeking European authorization. German neonatology departments in Bavaria and North Rhine-Westphalia adopt non-invasive respiratory support protocols using high-flow nasal cannula systems. The country's national pharmaceutical regulator enforces post-market surveillance requirements for surfactant biosimilars entering procurement channels.
Japan
PMDA pediatric investigation plans require age-appropriate pharmacokinetic trials before labeling claims for preterm populations. Tokyo and Osaka metropolitan hospitals concentrate demand for surfactant replacement therapies among low-birth-weight infants. METI funding programs support domestic development of corticosteroid-sparing anti-inflammatory agents.
United Kingdom
NHS England reimbursement frameworks shape formulary positioning for chronic maintenance medications in outpatient pulmonary follow-up. London and Southeast England tertiary centers lead adoption of telemedicine-integrated transport systems connecting community birth centers with pediatric hospitals. The country's national pharmaceutical regulator aligns pediatric study requirements with EMA Paediatric Regulation standards.
India
CDSCO pediatric investigation plans govern market authorization for surfactant formulations targeting preterm neonates. Maharashtra and Karnataka state health systems expand Level II NICU capacity in Mumbai and Bangalore metro corridors. The national pharmaceutical regulator mandates stability testing for temperature-sensitive biologic products distributed through regional cold chain networks.
Bronchopulmonary Dysplasia Treatment Market Vendor Landscape
Global majors compete with regional champions across surfactant manufacturing and neonatal respiratory device categories, producing a tiered structure where European manufacturers dominate porcine-derived raw material sourcing. The vendor base separates into three archetypes: integrated pharmaceutical conglomerates with neonatology franchises, mid-cap biotech developers pursuing orphan indications, and device specialists focused on non-invasive ventilation hardware. Competitive moves concentrate on strategic partnerships for biosimilar development and geographic expansion into Medicaid-reimbursed home care markets.
Within the integrated pharmaceutical tier, Chiesi Farmaceutici S.p.A. and GlaxoSmithKline plc represent established neonatology franchises with European manufacturing footprints. AbbVie Inc. anchors the immunomodulatory development vector through corticosteroid-sparing pipeline positioning. Among biotech specialists, Airway Therapeutics and Therabron Therapeutics exemplify the orphan-drug-focused archetype targeting inflammatory lung injury mechanisms. Insmed Inc. and Oak Hill Bio occupy positions in the inhaled therapy development segment.
| Leading Market Players |
|---|
| Chiesi Farmaceutici S.p.A. |
| Airway Therapeutics |
| MediPost |
| Therabron Therapeutics |
| AbbVie Inc. |
| Oak Hill Bio |
| Insmed Inc. |
| GlaxoSmithKline plc |
| Medtronic plc |
| Others |
Supply Flow & Price Mechanics
FDA pediatric investigation plan requirements gate qualified supply for neonatal formulations while simultaneously anchoring premium-tier pricing access for sponsors completing mandated juvenile toxicology studies. Biosimilar developers face compressed margins unless they secure European porcine-derived raw material sourcing agreements that satisfy regulatory scrutiny.
Pricing Analysis
Input-cost pass-through from porcine-derived surfactant raw materials drives contract-based long-term offtake pricing for neonatal respiratory therapies. Three-tier pricing structure across premium, standard, and economy levels separates originator biologics from biosimilars and compounded alternatives, with FDA orphan drug exclusivity and EMA Paediatric Regulation certification tiers commanding substantial brand premiums. Cost compression in the standard tier is intensifying because European manufacturers dominate raw material sourcing, forcing biosimilar sponsors to absorb margin pressure or exit procurement committees. Medicaid-reimbursed home care programs in Texas and California exhibit highest price sensitivity, while Level III NICUs in Boston and Houston metro areas demonstrate lowest sensitivity due to bundled device-pharmaceutical contracts.
Supply Chain Analysis
Regional distribution centers in Italy, Spain, and the Netherlands anchor hub-and-spoke patterns for temperature-sensitive surfactant biologics requiring validated cold chain integrity. Manufacturing concentration in these European markets draws from porcine lung tissue extraction, pharmaceutical-grade lipid processing, and sterile fill-finish capacity as critical input dependencies. Single-source vulnerability permeates the upstream tier because Italian manufacturers control over half of global porcine-derived surfactant precursor supply. Distribution runs through specialty pharmaceutical wholesalers with neonatal intensive care unit direct-to-site delivery capabilities, bypassing general hospital procurement channels to preserve product stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in European manufacturing footprint expansion, where EMA Paediatric Regulation compliance costs are offset by raw material proximity advantages unavailable to US-based competitors facing FDA pediatric investigation plan mandates.
For Market Incumbents: Acquire surfactant biosimilar development pipelines to preempt margin erosion from European raw material concentration. Chiesi Farmaceutici S.p.A. and GlaxoSmithKline plc should secure captive supply agreements with Italian porcine tissue processors before contract manufacturing capacity tightens. Backward integration into neonatal ventilation device portfolios defends against integrated bundle competition from Medtronic plc in Level III NICU procurement. For New Entrants and Emerging Players: FDA orphan drug designation in the United States opens a window for corticosteroid-sparing anti-inflammatory agents targeting inflammatory lung injury without neurodevelopmental liability. Home oxygen weaning programs in Texas and California Medicaid represent the most penetrable white-space segment, with remote pulse oximetry telemetry creating service-based revenue models beyond pharmaceutical sales. Partnership with regional perinatal networks accelerates formulary access without requiring tertiary pediatric hospital infrastructure investment. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap biotech developers with orphan-drug-focused pipelines because FDA market exclusivity periods extend effective patent life beyond standard pharmaceutical benchmarks. Platform consolidation targets should possess completed Phase II neonatal cohort data and active pediatric investigation plans. The signal to watch is surfactant biosimilar interchangeability determinations, which would trigger accelerated margin compression and force strategic repositioning across the neonatal respiratory care continuum.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA exclusivity periods extend market protection for sponsors completing pediatric investigation plans. |
| Surfactant Biosimilar Development | European raw material proximity reduces cost structure versus US-based manufacturing competitors. |
| Home Care Monitoring Integration | Texas and California Medicaid reimbursement creates service-based revenue beyond pharmaceutical sales. |
| Non-Invasive Ventilation Partnership | Continuous positive airway pressure bundling with surfactant therapies strengthens NICU procurement position. |
| Regional Perinatal Network Alliance | Telemedicine-integrated transport systems connect community birth centers with tertiary referral pathways. |
Methodological Framework
Direct dialogue with neonatology department heads, pediatric hospital procurement managers, regulatory affairs specialists, and surfactant manufacturing executives grounded qualitative findings in operational reality. Secondary validation drew from FDA orphan drug designation filings, EMA Paediatric Regulation submission databases, ClinicalTrials.gov neonatal respiratory intervention records, and CMS Medicaid reimbursement policy documents. Bottom-up patient volume modeling across gestational age cohorts triangulated against top-down pharmaceutical revenue estimates from institutional formulary databases.
Segment-level outputs across medications, therapies, devices, and nutritional support categories fed into administration route and end-user stratification throughout the projection horizon. Treatment line positioning, dosage form differentiation, and regional regulatory cluster adoption curves shaped analytical framework construction. CAGRs emerged from weighted average of historical volume trends, patent expiry impact assessment, and biosimilar entry probability modeling for surfactant replacement therapies.
Revisions become necessary when FDA pediatric investigation plan requirements expand, surfactant biosimilar interchangeability standards materialize, or Medicaid home care reimbursement frameworks shift across state-level programs. Forecasts reflect documented assumptions regarding premature birth rate trajectories and NICU infrastructure commissioning schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Emphysema Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Global Respiratory Care Devices Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Lung Injury Market
Respiratory Care
Global Respiratory Heaters Market