
 North America Fetal and Neonatal Care Equipment Market | 2026-2036
North America Fetal and Neonatal Care Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fetal and Neonatal Care Equipment Market Analytics
Aftermarket service revenue is reshaping profitability for incumbent vendors. GE Healthcare leverages its installed base of fetal monitors to secure multi-year service contracts across integrated delivery networks. Drägerwerk AG & Co. KGaA anchors its neonatal ventilation franchise through direct field engineering teams positioned in major metropolitan corridors. Koninklijke Philips N.V. competes by bundling incubators with enterprise-wide patient monitoring architectures.
North America fetal and neonatal care equipment encompasses thermoregulation, cardiorespiratory monitoring, and resuscitation systems engineered for infants below 44 weeks gestational age, typically operating within precision ranges of 0.5°C thermal stability and 1 bpm heart-rate resolution. These devices serve the clinical imperative of reducing neonatal mortality and morbidity in acute care settings. Fetal monitors and incubators command the deepest margin pools due to recurring sensor and disposable attach rates, while resuscitation devices face commoditization pressures from regional distributors. End-user concentration in level III and IV neonatal units creates procurement consolidation that favors vendors with comprehensive monitoring-to-therapeutic portfolios.
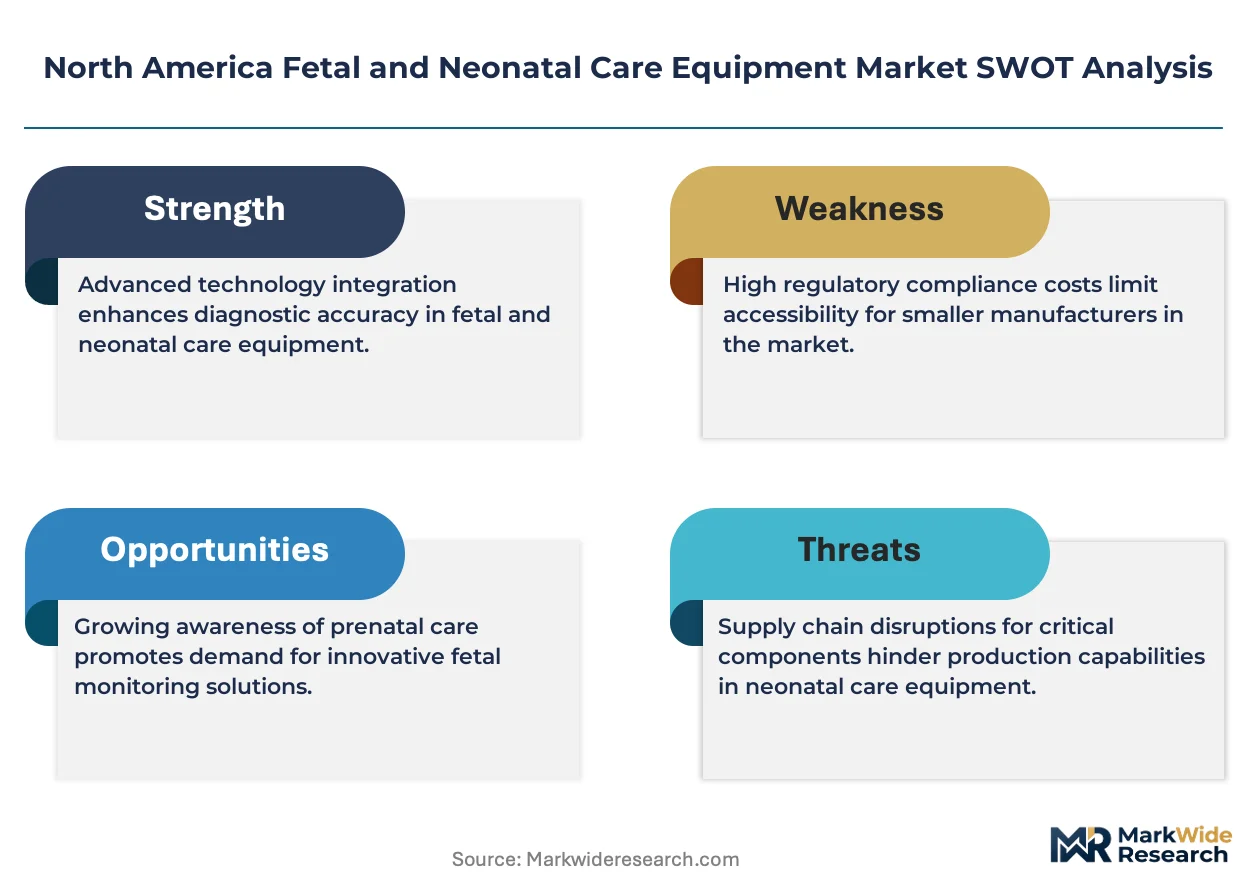
FDA premarket notification requirements and Joint Commission accreditation standards govern device safety, cybersecurity, and alarm management across US facilities, while Health Canada and the Canadian Standards Association maintain parallel but non-identical approval pathways that fragment product registration timelines. The FDA's evolving software-as-medical-device guidance particularly constrains AI-enabled fetal interpretation tools. Stakeholders must weigh the capital efficiency of platform upgrades against the regulatory burden of validating interoperable systems across heterogeneous hospital IT environments.
Market Dynamics
Consolidation of neonatal intensive care units into academic medical centers is compressing vendor access points while amplifying procurement power, forcing equipment suppliers to restructure go-to-market models around integrated delivery network contracting rather than individual hospital sales.
Growth Catalysts
- Level IV NICU expansion:Tertiary hospitals in Texas and California are consolidating perinatal services into centralized hubs, concentrating demand for multi-parameter monitoring systems and creating captive markets for vendors with full-stack portfolios.
- FDA 510(k) pathway evolution:Tightened premarket requirements for neonatal devices are elevating barriers for new entrants, entrenching incumbents with established quality management systems and predicate device libraries.
- AI-enabled fetal surveillance:Machine learning interpretation of cardiotocography traces is penetrating academic medical centers, driving replacement cycles for legacy monitor fleets and creating attach-rate opportunities for software modules.
Market Restraints
- Capital equipment replacement cycles:Extended depreciation schedules for incubators and warmers—typically 10-12 years—suppress recurring revenue streams and compress addressable market velocity in mature installed bases.
- Sensor supply concentration:Precision thermistors and pulse oximetry emitters for neonatal applications source predominantly from East Asian component suppliers, exposing manufacturers to geopolitical friction and customs processing delays.
- Interoperability fragmentation:Proprietary data protocols between competing patient monitoring architectures prevent seamless integration, forcing hospitals into single-vendor lock-in that limits price competition and innovation diffusion.
Strategic Opportunities
- Remote NICU telemetry:Cloud-connected monitoring platforms enable centralized surveillance of satellite level II units from academic hubs, opening subscription revenue models in rural Ontario and interior California markets.
- Health Canada parallel pathway optimization:Streamlined registration procedures for FDA-cleared devices create first-mover advantages for US manufacturers expanding into Canadian perinatal centers clustered around Toronto and Vancouver.
- Disposable resuscitation circuits:Single-use ventilation interfaces for neonatal transport are displacing reusable assemblies in emergency medical services channels, capturing margin pools outside traditional hospital procurement.
Industry Challenges
- Biomedical engineering specialization:Scarce technicians trained in neonatal device calibration and alarm management limit field service scalability, constraining vendor expansion into secondary markets.
- Joint Commission alarm fatigue compliance:Accreditation standards for alarm customization and escalation protocols demand software revalidation cycles that extend product development timelines and strain regulatory affairs bandwidth.
- Cybersecurity validation burden:FDA guidance on networked medical device security requires penetration testing and threat modeling that adds 6-9 months to clearance timelines for WiFi-enabled monitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fetal and Neonatal Care Equipment Market |
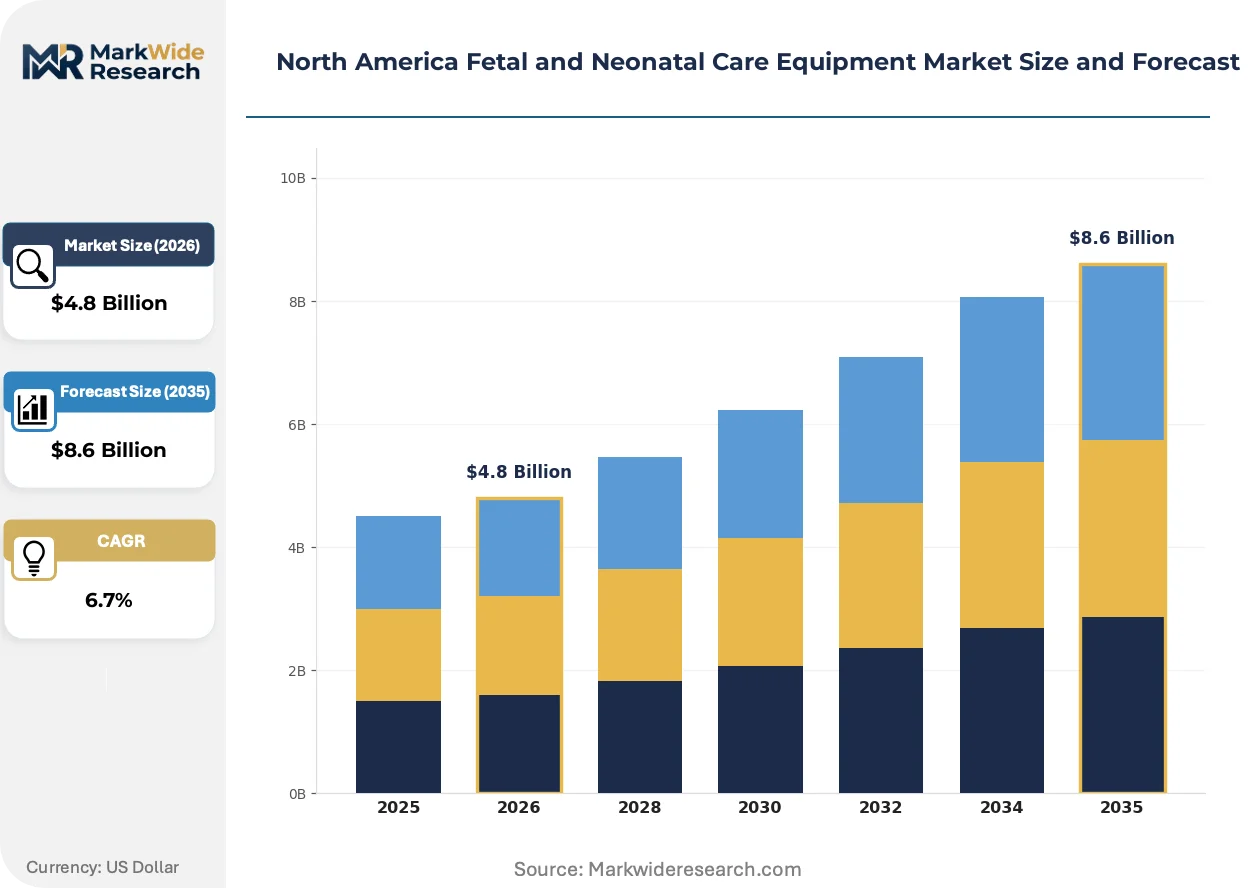
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incubators, Radiant Warmers, Fetal Monitors, Resuscitation Devices End User: Hospitals, Clinics, Homecare, Neonatal Units Technology: Monitoring, Imaging, Therapeutic, Supportive Application: Prenatal Care, Delivery, ICU Care, Postnatal Care |
| Companies Covered | Becton, Dickinson and Company, Drägerwerk AG & Co. KGaA, GE Healthcare, Cardinal Health, Masimo, Medtronic PLC, Siemens Healthineers AG, Fisher & Paykel Healthcare, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fetal and Neonatal Care Equipment Market Evolving Landscape
Digital integration of fetal surveillance with maternal electronic health records is dissolving traditional boundaries between obstetric and neonatal data systems, compelling vendors to architect platform solutions rather than standalone devices.
Wireless cardiotocography patches with adhesive electrode arrays are eliminating belt-based transducer systems from labor and delivery floors. Hospital systems in California and Texas are piloting these platforms for ambulatory antenatal monitoring. Continuous data streaming is rendering obsolete the episodic snapshot model of conventional fetal monitoring.
Health Canada's alignment with FDA cybersecurity guidance through the Medical Device Single Audit Program is harmonizing premarket documentation requirements. Canadian manufacturers with MDSAP certification now access US markets through streamlined 510(k) review. Neonatal ventilation platforms with embedded software controls face the steepest compliance burden under this convergence.
Outcome-based contracting for NICU equipment is penetrating integrated delivery networks in Ontario and the US Midwest. Risk-sharing arrangements tie vendor payments to reductions in hypothermia incidence or ventilation days rather than capital purchase price. Academic medical centers with robust clinical data infrastructure are the primary adopters of this model.
North America Fetal and Neonatal Care Equipment Market Segmentation
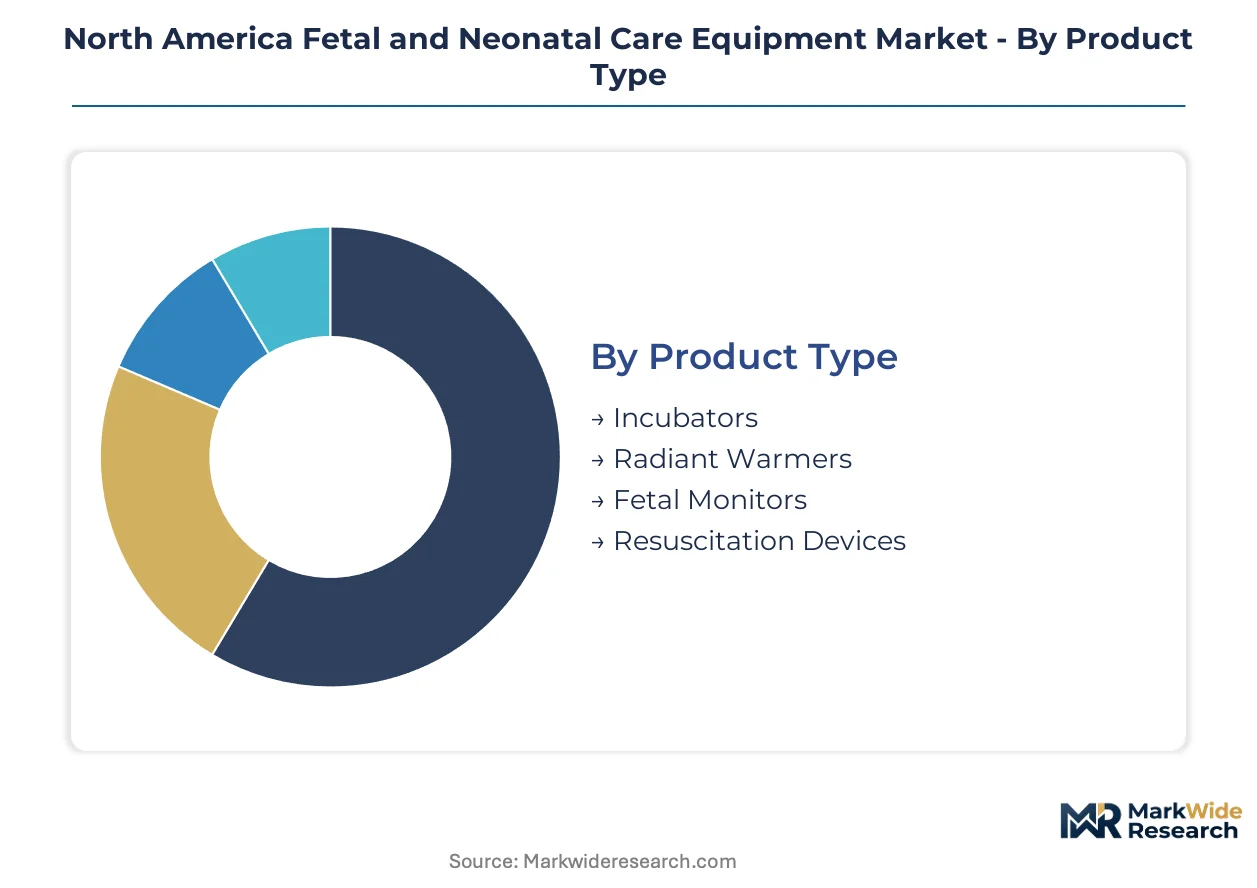
Equipment replacement cycles vary dramatically across fetal and neonatal care categories, with sensor-dependent devices turning over every 3-5 years while capital-intensive platforms depreciate over decades. Understanding these velocity differentials shapes vendor portfolio strategy and service contract architecture across North American perinatal centers.
Product Type:
Replacement velocity separates high-turnover consumable-adjacent devices from capital platforms locked into 10-15 year depreciation schedules.
- Incubators:Double-walled servo-controlled thermal environments maintaining 36.5°C neutral thermal zone with humidity modulation. Demand concentrates in level III and IV NICUs across Texas and California academic medical centers, where Joint Commission thermal stability requirements drive upgrade cycles.
- Fetal Monitors:Cardiotocography systems capturing fetal heart rate and uterine contraction patterns at 1 bpm resolution with AI-enabled trace interpretation. Texas perinatal centers are replacing legacy fleets with wireless patch-based systems, creating attach-rate opportunities for disposable electrode arrays.
- Radiant Warmers:Overhead infrared heating platforms for delivery room resuscitation with servo-controlled skin temperature feedback.
- Resuscitation Devices:T-piece ventilators and positive pressure delivery systems for initial stabilization.
Fetal monitors anchor the volume base while incubators gain share at the steepest rate through NICU centralization.
End User:
Procurement authority concentrates differently across settings, with integrated delivery networks consolidating purchasing for hospitals while homecare remains fragmented.
- Hospitals:Tertiary academic medical centers with level III and IV NICU designations commanding multi-parameter monitoring suites through enterprise-wide contracts. California and Ontario systems are bundling fetal surveillance with maternal EHR integration.
- Neonatal Units:Dedicated perinatal centers within hospital systems requiring specialized thermoregulation and ventilation platforms. These units in Texas are piloting remote telemetry to satellite facilities, opening subscription revenue models.
- Clinics:Outpatient antenatal settings with limited resuscitation capabilities.
- Homecare:Post-discharge monitoring for high-risk infants with apnea detection systems.
Hospitals dominate absolute spend while neonatal units are expanding most quickly through service line consolidation.
Technology:
Margin structure follows regulatory burden, with software-enabled monitoring technologies commanding premium pricing over mechanical support systems.
- Monitoring:Continuous cardiorespiratory surveillance with networked alarm management and cybersecurity-hardened data transmission. FDA 510(k) software-as-medical-device guidance is extending clearance timelines for AI-enabled fetal interpretation tools.
- Therapeutic:Active intervention systems including mechanical ventilation and precise thermal regulation.
- Imaging:Point-of-care ultrasound for fetal assessment and procedural guidance.
- Supportive:Auxiliary equipment including phototherapy and transport incubators.
Monitoring technologies capture the deepest margin pools while therapeutic systems face commoditization from regional distributors.
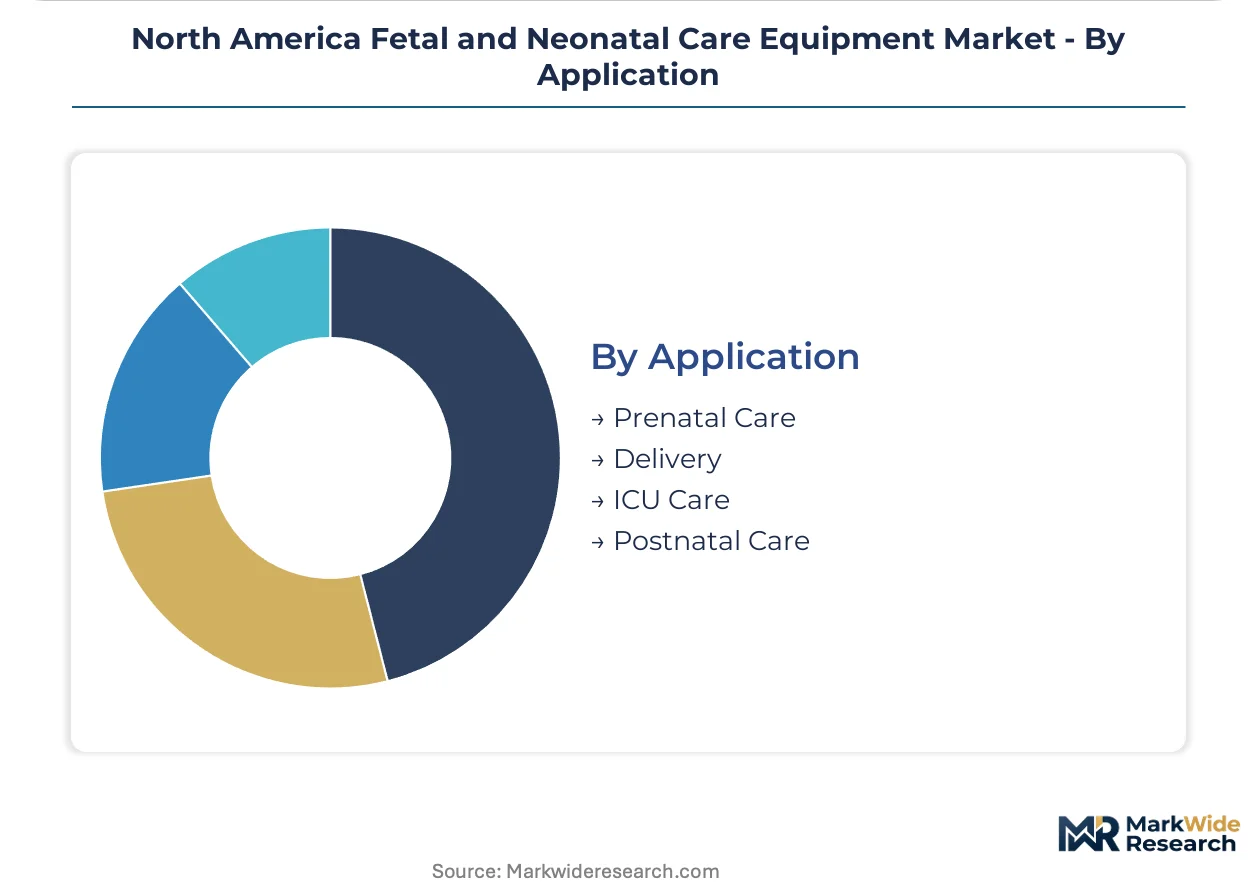
Application:
Clinical workflow integration determines interoperability requirements, with delivery-to-NICU handoffs demanding seamless data continuity.
- ICU Care:Extended mechanical ventilation and multi-organ support for premature infants below 32 weeks gestation. Ontario academic centers are adopting outcome-based contracting tied to ventilation day reductions.
- Delivery:Immediate resuscitation and stabilization in labor and delivery suites. California hospitals are displacing belt-based transducers with wireless cardiotocography patches for ambulatory intrapartum monitoring.
- Prenatal Care:Antenatal fetal surveillance and risk stratification.
- Postnatal Care:Transition monitoring and discharge preparation.
ICU care anchors the revenue base while delivery applications are climbing the fastest through wireless platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing for neonatal thermistors and pulse oximetry emitters clusters in East Asian supplier networks, exposing North American equipment vendors to customs friction and inventory volatility. FDA and Health Canada regulatory divergence fragments product registration timelines across the continent. Procurement authority concentrates in metropolitan perinatal corridors where academic medical centers anchor integrated delivery networks.
United States
Texas and California academic medical centers are consolidating perinatal services into centralized level IV NICU hubs, concentrating demand for multi-parameter monitoring systems. FDA 510(k) clearance pathways for neonatal devices are tightening premarket requirements through enhanced software-as-medical-device guidance. The Dallas-Fort Worth and Houston corridors host dense clusters of tertiary hospitals piloting AI-enabled fetal surveillance platforms.
Canada
Ontario perinatal centers around Toronto are adopting outcome-based contracting models tied to hypothermia incidence reductions. Health Canada's alignment with FDA cybersecurity guidance through the Medical Device Single Audit Program is harmonizing premarket documentation for neonatal ventilation platforms. Vancouver and Montreal academic hospitals are expanding remote telemetry capabilities to satellite level II units in rural British Columbia and Quebec.
Mexico
Mexico City metropolitan hospitals are upgrading neonatal resuscitation capabilities through public health infrastructure investments targeting maternal mortality reduction. COFEPRIS regulatory pathways for imported medical devices require local representation and Spanish-language labeling compliance. Guadalajara and Monterrey medical device distributors are establishing service partnerships with US-based incubator and monitor manufacturers.
North America Fetal and Neonatal Care Equipment Market Competitive Landscape
Full-stack platform vendors and specialized monitoring technology providers split the market between integrated enterprise contracts and point-solution deployments. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with comprehensive perinatal portfolios, respiratory and ventilation specialists with deep neonatal expertise, and sensor technology innovators driving disposable attach-rate economics. Consolidation pressures favor vendors with predicate device libraries and established FDA quality management systems, while interoperability fragmentation limits price competition.
Within the diversified technology tier, GE Healthcare and Koninklijke Philips N.V. exemplify platform-centric positioning through enterprise-wide patient monitoring architectures. Drägerwerk AG & Co. KGaA represents the specialized respiratory archetype with dedicated neonatal ventilation expertise. These three entities anchor the competitive structure by occupying positions that span capital equipment, software modules, and multi-year service contracts across integrated delivery networks in Texas, California, and Ontario.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Drägerwerk AG & Co. KGaA |
| GE Healthcare |
| Cardinal Health |
| Masimo |
| Medtronic PLC |
| Siemens Healthineers AG |
| Fisher & Paykel Healthcare |
| Koninklijke Philips N.V. |
| Others |
Value Network & Pricing Analysis
Undercapacity in precision thermistor manufacturing across East Asian supplier networks is compressing component availability while amplifying pricing power for incumbent equipment vendors with captive inventory positions. This utilization squeeze feeds directly into extended lead times for neonatal pulse oximetry emitters, forcing US and Canadian manufacturers to absorb cost escalation or push price adjustments through integrated delivery network contracts.
Pricing Analysis
Multi-year service contracts with disposable sensor attach rates drive lifetime value more than capital equipment margins. Three-tier pricing structure across premium AI-enabled monitoring suites, standard cardiotocography platforms, and economy resuscitation devices separates vendors by software certification grade and FDA predicate device libraries. Cost compression in economy-tier warmers is intensifying because regional distributors are importing non-MDSAP-certified alternatives. Homecare apnea detection systems exhibit highest price sensitivity, while level IV NICU academic centers prioritize interoperability over unit cost.
Supply Chain Analysis
Extended payment terms from East Asian component suppliers to North American OEMs are tightening working capital requirements across the vendor base. Precision thermistors, pulse oximetry emitters, and servo-control sensors draw predominantly from China, Taiwan, and South Korea, exposing manufacturers to customs processing friction and tariff exposure. Single-source vulnerability concentrates in neonatal-grade thermistor production. Distribution runs through GPO contracts and direct field service teams anchored in Texas and California metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue layers are expanding faster than hardware sales as integrated delivery networks consolidate procurement around multi-year monitoring platform contracts. This service-attach dynamic reorients vendor strategy toward recurring revenue capture rather than episodic capital equipment transactions.
For Market Incumbents: Entrench market position by securing exclusive sensor supply agreements with East Asian thermistor manufacturers and expanding direct biomedical engineering field teams across Ontario and Texas level IV NICU clusters. AI-enabled fetal interpretation software faces regulatory headwinds from FDA software-as-medical-device guidance, making predicate device libraries and established quality management systems critical defensive assets. Backward integration into disposable electrode array production protects margin pools from commoditization.
For New Entrants and Emerging Players: Rural level II NICU units in interior California and British Columbia represent the most penetrable entry point for cloud-connected remote telemetry platforms with subscription pricing models. Mid-market community hospitals in Mexico City metropolitan corridors offer secondary expansion targets through COFEPRIS-registered distribution partnerships. A software-first go-to-market angle bypasses capital-intensive incubator manufacturing while capturing attach-rate economics.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled monitoring sub-segments as FDA cybersecurity validation requirements extend development timelines. Acquisition targets should emphasize vendors with MDSAP certification spanning US and Canadian regulatory pathways, robust clinical data infrastructure for outcome-based contracting pilots, and established service attach rates above hardware depreciation cycles. Watch Health Canada-FDA regulatory convergence velocity as an inflection indicator for cross-border expansion economics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Submission | AI-enabled fetal trace interpretation tools face extended clearance timelines under evolving guidance. |
| MDSAP Certification Pathway | Harmonized audit program streamlines US-Canada regulatory access for ventilation platform vendors. |
| Hospital System Partnership | Enterprise-wide monitoring architecture contracts consolidate procurement across Texas academic medical centers. |
| Software Companion Development | Wireless cardiotocography patches require continuous data streaming platforms for ambulatory antenatal monitoring. |
| Reimbursement Strategy | Outcome-based contracting ties vendor payments to hypothermia incidence reductions in Ontario NICUs. |
Research Methodology
Operator-level perspectives from NICU clinical directors, biomedical engineering managers, GPO contracts specialists, and neonatal ventilation technicians anchored the qualitative base for this analysis. Primary interviews with hospital purchasing committees and integrated delivery network procurement executives combined with secondary validation from FDA 510(k) clearance databases, Health Canada medical device licenses, hospital capital expenditure disclosures, and GPO contract repositories. Bottom-up equipment unit economics and top-down perinatal center spending patterns were triangulated to establish market sizing boundaries.
Scenario-bracketing around regulatory pathway evolution, NICU centralization velocity, and AI adoption curves structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type replacement velocity, end-user procurement authority concentration, technology regulatory burden tiers, and application workflow integration requirements. CAGRs derived from installed base turnover rates, sensor attach-rate expansion, and service contract renewal patterns. Forecast inputs incorporated FDA software guidance timeline uncertainty and Health Canada MDSAP alignment progress.
Practitioners should monitor FDA cybersecurity guidance implementation pace, East Asian component supplier utilization rates, and integrated delivery network consolidation announcements for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Neonatal Dialysis Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Preterm Birth Prevention and Management Market
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market