
 Global Preterm Birth and PROM Testing Market | 2026-2036
Global Preterm Birth and PROM Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Preterm Birth and PROM Testing Market Foresight
CE marking under the EU Medical Device Regulation is hardening the cost-of-entry calculus for preterm birth diagnostics entering European markets. QIAGEN leverages its molecular test portfolio to sustain leadership in nucleic acid-based preterm labor prediction across multiple continents. Hologic, Inc. anchors its position through dominant manufacturing scale in fetal fibronectin immunoassays. Abbott competes by extending its diagnostics distribution into maternity clinic networks in emerging markets.
Preterm birth and PROM testing encompasses biochemical, immunoassay, and molecular diagnostic platforms designed to detect biomarkers predictive of spontaneous preterm delivery or premature rupture of membranes, typically operating with sensitivity thresholds above 80 percent for clinical utility. These systems serve obstetricians by enabling intervention before cervical change or membrane rupture progresses to irreversible labor. Molecular tests and proteomic assays command the fastest expansion as laboratories adopt multiplexed biomarker panels over single-analyte methods. Biochemical markers remain the largest volume category due to established reimbursement and lower per-test cost structures. Specimen collection kits concentrate margin pools at manufacturers with integrated kit-test workflows.
FDA premarket review pathways and EMA companion diagnostic guidelines shape product development timelines and evidence requirements for preterm birth assays in their respective jurisdictions. ISO 13485 quality management standards govern manufacturing consistency across all major supply bases. WHO prequalification programs influence procurement decisions in low-resource settings where preterm mortality burdens are highest. Stakeholders must monitor how evolving regulatory science on predictive biomarker validation reshapes competitive moats between established immunoassay platforms and emerging molecular diagnostics.
Market Dynamics
Multiplexed biomarker panels are compressing the competitive moat between single-analyte immunoassay incumbents and molecular diagnostic entrants by collapsing cost-per-data-point economics in laboratory workflows.
Growth Catalysts
- Integrated health systems in the United States:Standardized risk-stratification protocols for high-risk pregnancies are institutionalizing biomarker testing into routine antenatal care pathways.
- EU Medical Device Regulation CE marking requirements:Hardening clinical evidence standards are filtering out marginal competitors and consolidating market share among validated manufacturers.
- Point-of-care testing expansion:Maternity clinics across Germany and the United Kingdom are deploying decentralized diagnostic platforms to reduce time-to-intervention for threatened preterm labor.
Market Restraints
- Reimbursement volatility for novel molecular assays:Payers in multiple jurisdictions impose prior authorization requirements that extend revenue recognition timelines for proteomic panel developers.
- Specimen collection kit supply concentration:Integrated kit-test workflow manufacturers control margin pools, creating dependency risks for standalone assay producers.
- Technical sensitivity floor:Clinical utility thresholds above 80 percent sensitivity create validation cost barriers that exclude smaller diagnostic developers from commercialization.
Strategic Opportunities
- WHO prequalification procurement channels:Low-resource settings with highest preterm mortality burdens represent underserved demand for affordable, thermostable testing formats.
- Convergence of digital health platforms with biomarker data:Remote patient monitoring systems in the Netherlands and Sweden are integrating predictive algorithms with real-time cervical length and biochemical marker inputs.
- FDA biomarker validation protocol evolution:Ongoing regulatory science development on predictive biomarker standards creates first-mover advantage for manufacturers with robust prospective cohort data.
Industry Challenges
- ISO 13485 quality management system implementation:Manufacturing consistency requirements demand specialized regulatory affairs and quality assurance talent pools that command premium compensation.
- EMA companion diagnostic guideline alignment:Product development timelines extend as developers reconcile divergent evidence requirements across FDA premarket review and European notified body pathways.
- Legacy immunoassay infrastructure integration:Hospital laboratories face capital allocation decisions between retrofitting existing fetal fibronectin analyzers and migrating to multiplexed molecular platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Preterm Birth and PROM Testing Market |
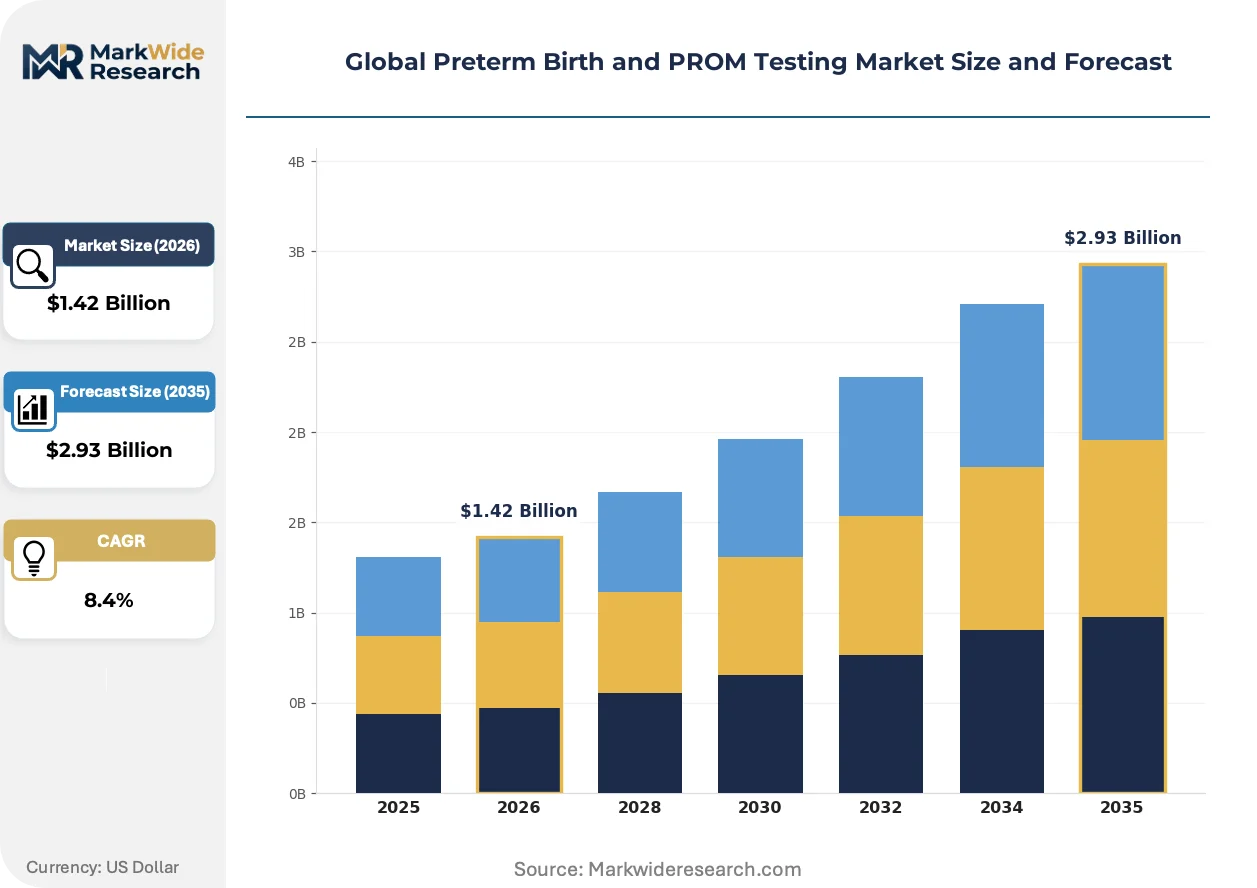
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biochemical Markers, Immunoassays, Molecular Tests, Ultrasound Devices, Specimen Collection Kits Testing Method: Proteomic Assays, Genetic Profiling, Cytokine Analysis, Fetal Fibronectin, Nitric Oxide Detection End User: Diagnostic Laboratories, Maternity Clinics, Research Institutes, Home Testing Providers Application: Preterm Labor Prediction, Membrane Rupture Confirmation, Infection Diagnosis, Risk Stratification |
| Companies Covered | QIAGEN, Hologic, Inc., CooperSurgical Inc., Abbott, Sera Prognostics, Biosynex SA, NX Prenatal Inc., Medix Biochemica, IQ Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Preterm Birth and PROM Testing Market Shifts & Advancements
Diagnostic platforms are converging around predictive analytics architectures that transform discrete biomarker readouts into continuous risk probability scores for obstetric decision support.
Next-generation sequencing-based preterm labor prediction is unifying transcriptomic, proteomic, and metabolomic signals into single-workflow assessments. Academic medical centers in the United States and university hospitals in France are piloting these platforms for high-risk pregnancy clinics. This convergence is unifying previously siloed laboratory disciplines and compressing the competitive differentiation of standalone biochemical or immunoassay specialists.
CE marking under the EU Medical Device Regulation is hardening post-market surveillance obligations and clinical evidence renewal cycles for preterm birth diagnostics. Manufacturers must maintain prospective registry data or face certificate suspension. In vitro diagnostic firms with established European notified body relationships are accelerating regulatory dossier preparation to secure transitional provisions before 2028 deadlines.
Integrated health systems are consolidating procurement decisions for preterm birth testing under centralized laboratory medicine committees. Independent maternity clinics and smaller hospital obstetric units lose negotiating leverage as purchasing authority migrates to regional laboratory networks. This concentration is most visible in the United States, where IDN-affiliated hospitals now account for the majority of fetal fibronectin test volume.
Global Preterm Birth and PROM Testing Market Segmentation
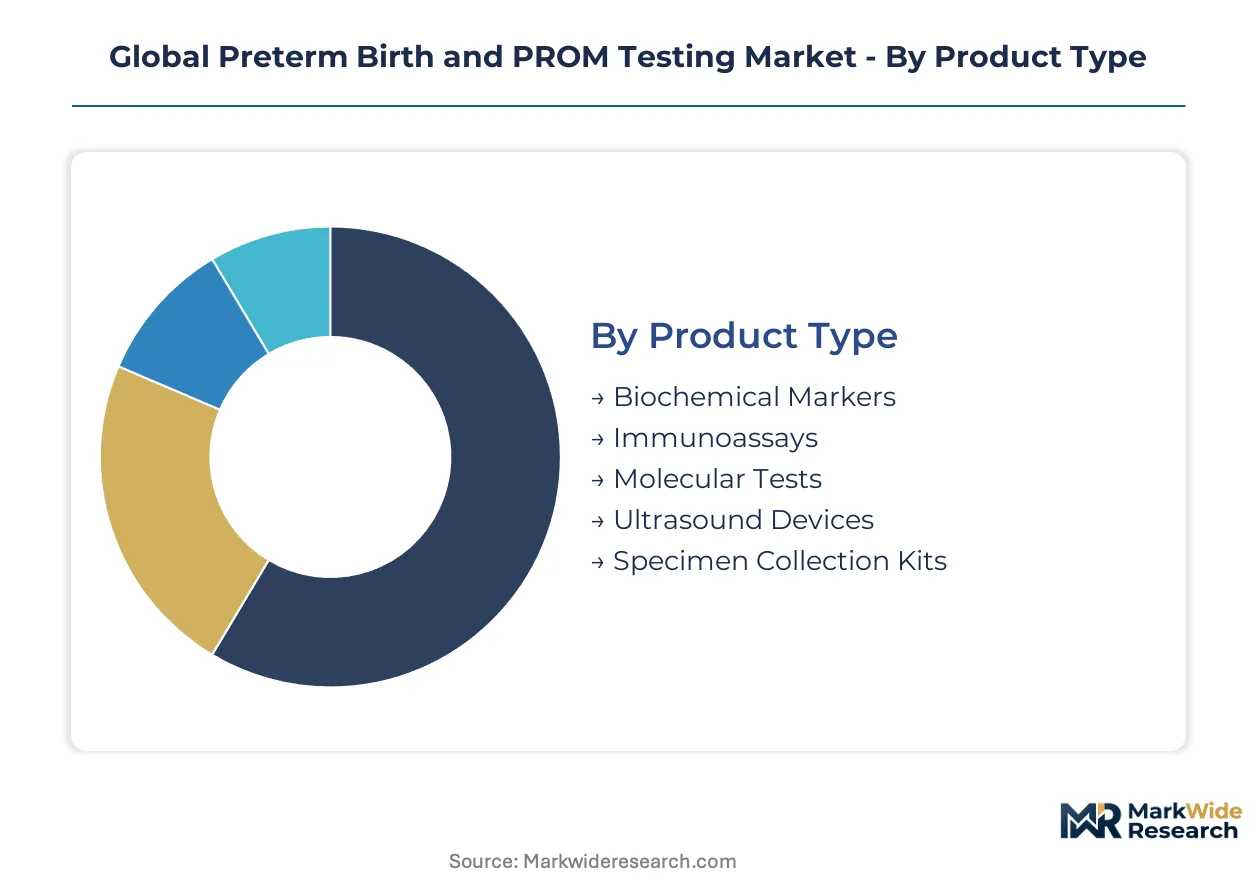
Preterm birth and PROM testing markets fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and regulatory pathways. Understanding these segment boundaries clarifies where capital deployment yields the highest returns and where competitive moats are most defensible.
Product Type:
Replacement cycles vary dramatically across product categories, with legacy immunoassay platforms facing displacement pressure from multiplexed molecular systems while specimen collection kits enjoy recurring revenue stability.
- Biochemical Markers:Enzyme-based detection systems measuring salivary estriol, corticotropin-releasing hormone, and other metabolic intermediates. Hospital laboratories in Germany and the United Kingdom retain these systems for cost-sensitive screening protocols despite sensitivity limitations.
- Immunoassays:Antibody-mediated detection platforms, predominantly fetal fibronectin ELISAs, that dominated clinical practice for two decades. Integrated health systems in the United States now face capital allocation decisions between retrofitting existing analyzers and migrating to molecular alternatives.
- Molecular Tests:Nucleic acid amplification platforms detecting mRNA signatures and microbial DNA. Academic medical centers in France and university hospitals in Sweden pilot these for high-risk pregnancy clinics.
- Ultrasound Devices:Transvaginal and transabdominal imaging systems for cervical length measurement. Maternity clinics across North America deploy these as first-line screening tools.
- Specimen Collection Kits:Integrated sampling and transport systems that concentrate margin pools at manufacturers with captive kit-test workflows. Standalone assay producers face dependency risks.
Biochemical markers sit at the top of the volume ranking, with molecular tests climbing the fastest.
Testing Method:
Cost tier stratification separates proteomic panels commanding premium reimbursement from single-analyte methods competing on per-test economics.
- Proteomic Assays:Multiplexed protein detection panels measuring interleukin-6, interleukin-8, tumor necrosis factor-alpha, and matrix metalloproteinases simultaneously. Laboratories in the Netherlands adopt these to collapse cost-per-data-point economics.
- Genetic Profiling:SNP arrays and targeted sequencing assessing maternal and fetal genetic variants associated with preterm delivery risk. Research institutes in the United States leverage these for prospective cohort studies.
- Cytokine Analysis:Inflammatory mediator quantification for infection-associated preterm labor. Maternity clinics in the United Kingdom integrate these with antimicrobial stewardship protocols.
- Fetal Fibronectin:Single-analyte immunoassay for glycoprotein detection in cervical-vaginal secretions. The method retains entrenched reimbursement codes across US commercial payers.
- Nitric Oxide Detection:Exhaled breath and biological fluid analysis for oxidative stress markers. Emerging applications concentrate in Swiss and Austrian university hospital research programs.
Fetal fibronectin commands the highest procedure volume, while proteomic assays gain share fastest.
End User:
Customer type determines purchasing authority concentration, with diagnostic laboratories consolidating procurement decisions while home testing remains fragmented.
- Diagnostic Laboratories:Centralized testing facilities processing high-throughput biomarker panels. Regional laboratory networks in the United States now control the majority of fetal fibronectin test volume.
- Maternity Clinics:Decentralized obstetric units deploying point-of-care platforms. Clinics across Germany expand rapid testing programs to reduce time-to-intervention.
- Research Institutes:Academic and government facilities conducting biomarker validation studies. French INSERM units and US NIH-funded centers drive prospective cohort data generation.
- Home Testing Providers:Direct-to-consumer and remote monitoring services. Regulatory frameworks in most jurisdictions limit commercial penetration.
Diagnostic laboratories sit at the top of the volume ranking, with maternity clinics climbing the fastest.
Application:
Application maturity separates established membrane rupture confirmation protocols from emerging risk stratification algorithms requiring prospective validation.
- Preterm Labor Prediction:Biomarker-based forecasting of spontaneous delivery before 37 weeks gestation. FDA biomarker validation protocol evolution shapes evidence requirements.
- Membrane Rupture Confirmation:Definitive diagnosis of premature rupture of membranes using biochemical or immunoassay methods. Established reimbursement supports stable procedure volumes.
- Infection Diagnosis:Detection of intra-amniotic infection and chorioamnionitis. WHO prequalification programs influence procurement in low-resource settings.
- Risk Stratification:Continuous probability scoring integrating multiple biomarker inputs with clinical variables. Digital health platforms in Sweden and the Netherlands pilot algorithmic decision support.
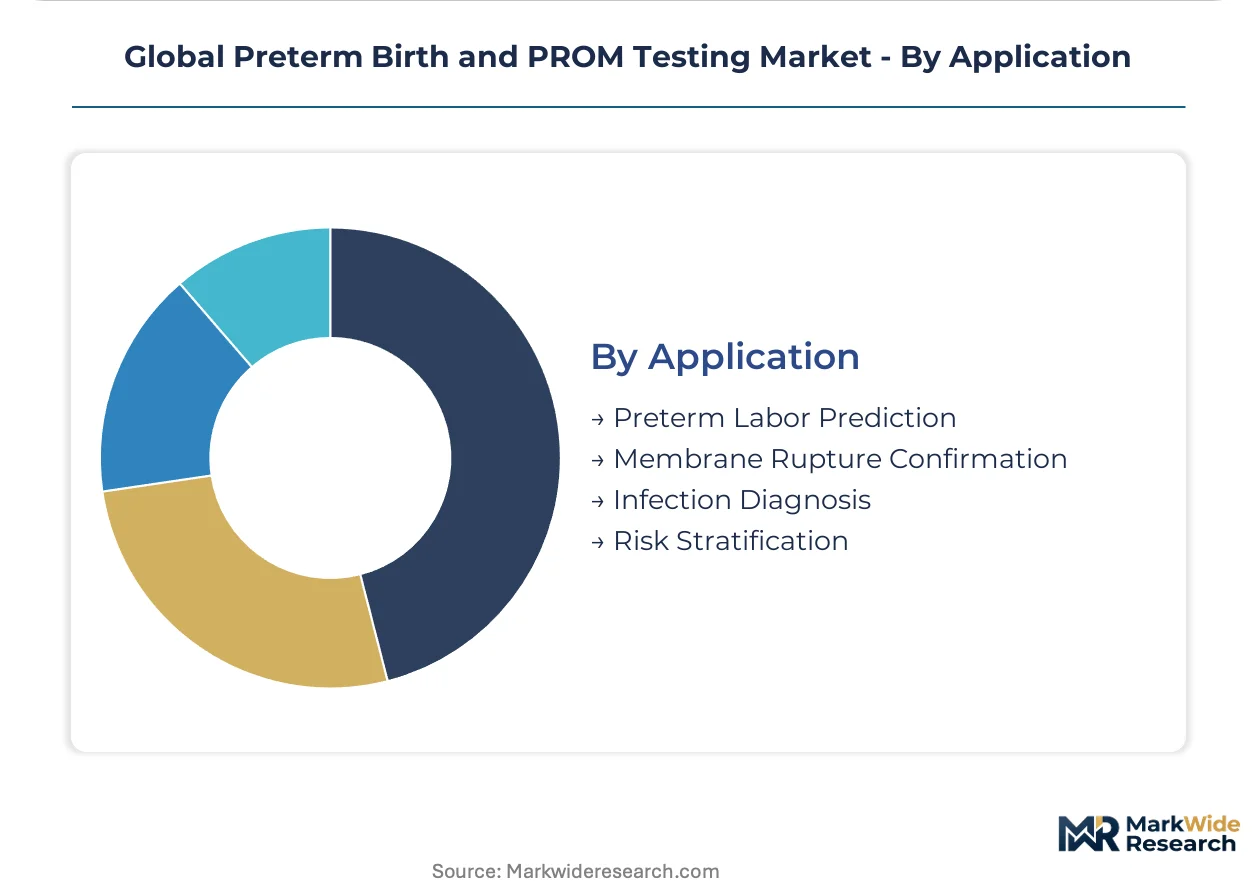
Membrane rupture confirmation sits at the top of the volume ranking, with risk stratification climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized obstetric diagnostic talent pools concentrate in university hospital clusters across five countries that shape preterm birth testing adoption patterns and regulatory evidence generation.
United States
Integrated delivery networks in Texas and California standardize fetal fibronectin protocols across affiliated maternity units. FDA premarket review pathways for predictive biomarker validation extend development timelines for molecular assay developers. Academic medical centers in Boston and the Research Triangle generate prospective cohort data that anchors FDA submission packages.
Germany
Maternity clinics in Bavaria and North Rhine-Westphalia deploy point-of-care platforms to compress time-to-intervention for threatened preterm labor. CE marking under the EU Medical Device Regulation hardens clinical evidence requirements for notified body conformity assessments. The Heidelberg and Munich university hospital clusters pilot next-generation sequencing integration into high-risk pregnancy workflows.
France
INSERM-funded research institutes in Paris and Lyon drive biomarker validation studies for proteomic panel developers. ANSM post-market surveillance obligations require manufacturers to maintain prospective registry data for certificate renewal. The Île-de-France region concentrates molecular diagnostic R&D talent for nucleic acid amplification platform advancement.
United Kingdom
NHS England maternity transformation programs institutionalize risk-stratification protocols in Greater London and Manchester clinic networks. MHRA recognition of EU MDR certificates streamlines market access for CE-marked diagnostics during transitional arrangements. Cambridge and Oxford research corridors anchor transcriptomic biomarker discovery collaborations.
Sweden
Digital health platforms in Stockholm and Gothenburg integrate predictive algorithms with real-time cervical length and biochemical marker inputs. The Swedish Medical Products Agency enforces ISO 13485 quality management standards for manufacturing consistency certification. University hospitals in Uppsala pilot continuous probability scoring systems for obstetric decision support.
Global Preterm Birth and PROM Testing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Consolidation pressure intensifies as integrated health systems centralize procurement authority under regional laboratory medicine committees. Three strategic archetypes dominate: multinational diagnostic platforms with captive distribution networks, molecular assay specialists with nucleic acid amplification expertise, and specimen collection kit manufacturers with integrated workflow control. Competitive moves concentrate on strategic partnerships with academic medical centers for prospective cohort data generation and regulatory dossier co-development.
Among molecular diagnostic specialists, QIAGEN and Sera Prognostics occupy positions defined by nucleic acid-based preterm labor prediction capabilities. Hologic, Inc. anchors the immunoassay incumbent tier through manufacturing scale in fetal fibronectin platforms. Abbott exemplifies the diversified conglomerate archetype with diagnostics distribution extension into emerging market maternity clinic networks.
| Leading Market Players |
|---|
| QIAGEN |
| Hologic, Inc. |
| CooperSurgical Inc. |
| Abbott |
| Sera Prognostics |
| Biosynex SA |
| NX Prenatal Inc. |
| Medix Biochemica |
| IQ Products |
| Others |
Supply & Pricing Matrix
Specialized regulatory affairs talent pools in Massachusetts and Basel command compensation premiums that compress margin spreads between premium molecular platforms and standard immunoassay tiers. Labor-cost differentials between ISO 13485-certified manufacturing regions and emerging production hubs feed directly into pricing-tier spreads for specimen collection kits and integrated test workflows.
Pricing Analysis
Bundled kit-test workflows versus unbundled standalone assays split pricing models across the market. Three-tier pricing structure across premium molecular panels, standard fetal fibronectin platforms, and economy biochemical markers reflects certification grade and volume scale differentiation. Pricing pressure stems from integrated health systems consolidating procurement under regional laboratory medicine committees. Home testing providers exhibit highest price sensitivity due to limited reimbursement frameworks, while academic medical centers demonstrate lowest sensitivity given research budget flexibility.
Supply Chain Analysis
Monoclonal antibody supply rests on specialized bioreactor facilities in the United States, Germany, and Switzerland for fetal fibronectin immunoassay production. Nucleic acid amplification reagents draw from precision chemical synthesis operations in the Netherlands and Japan. Single-source vulnerability concentrates in specimen collection kit manufacturing where integrated workflow producers control captive supply. Distribution runs through diagnostic laboratory networks and maternity clinic procurement committees with consolidated purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory validation milestones, with FDA biomarker protocol evolution institutionalizing evidence requirements that favor manufacturers with prospective cohort data.
For Market Incumbents: Deploy backward integration into specimen collection kit manufacturing to defend margin pools against standalone assay producers. Molecular diagnostic specialists must accelerate CE marking dossier preparation under EU MDR transitional provisions before certificate deadlines. Incumbents face displacement pressure from multiplexed proteomic panels collapsing cost-per-data-point economics in laboratory workflows. For New Entrants and Emerging Players: Low-resource maternity clinics in WHO prequalification procurement channels represent the most penetrable buyer archetype for affordable thermostable testing formats. Digital health platform partnerships in Sweden and the Netherlands offer white-space entry for algorithmic risk stratification tools. Go-to-market positioning should emphasize point-of-care deployment to compress time-to-intervention metrics. For Investors and Strategic Acquirers: Diversified diagnostic conglomerates with captive distribution networks are the most active acquirer in this space, consolidating molecular assay specialists for nucleic acid amplification capabilities. Long-term viability centers on regulatory dossier co-development partnerships with academic medical centers generating FDA submission-grade prospective data. Watch FDA premarket review pathway decisions on predictive biomarker standards as inflection indicators for molecular platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Biomarker Validation Submission | FDA premarket review pathways institutionalize evidence requirements for predictive assay developers. |
| CE Marking Pathway Acceleration | EU MDR transitional provisions before 2028 deadlines filter marginal competitors from European markets. |
| Hospital System Partnership | Integrated health systems in Texas and California consolidate fetal fibronectin protocol standardization. |
| Software Companion Development | Digital health platforms in Stockholm integrate predictive algorithms with real-time biomarker inputs. |
| Reimbursement Strategy | Prior authorization requirements from US commercial payers extend revenue recognition timelines for proteomic panels. |
Research Methodology
Multiple input streams — regulatory affairs directors at IVD manufacturers, hospital laboratory medicine committee chairs, biomedical engineers at academic medical centers, and GPO contracts managers — were reconciled against secondary validation from FDA 510(k) filings, EMA companion diagnostic guidelines, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up test volume modeling across product type, testing method, end user, and application segments was triangulated with top-down market sizing from manufacturer revenue disclosures.
Data-stream reconciliation anchored analytical framework development across the projection horizon. Segmentation dimensions modeled include product platform maturity, biomarker panel complexity, purchasing authority concentration, and regional regulatory cluster. CAGRs were derived from test volume trajectories and pricing evolution assumptions. Industry-specific forecast inputs incorporated FDA biomarker validation protocol timelines and EU MDR certificate renewal cycles.
Underlying measurement precision varies by segment; molecular test and proteomic assay categories carry tighter precision than biochemical marker and home testing segments due to manufacturer disclosure granularity. Forecasts reflect assumptions on regulatory approval velocity, reimbursement code stability, and integrated health system consolidation patterns. A small set of triggers — FDA predictive biomarker guidance finalization, EU MDR transitional provision deadlines, and WHO prequalification program expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Neonatal Infant Care Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Perinatal Software Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market
Neonatal Care
Neonatal Dialysis Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal and Infant Care Equipment Market
Neonatal Care
Neonatal Phototherapy Devices Market