
 Global Fixed Wing Air Ambulance Service Market | 2026-2036
Global Fixed Wing Air Ambulance Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fixed Wing Air Ambulance Service Market Intelligence
Hospital systems and government agencies are unwinding their historical reliance on ad hoc charter arrangements for long-distance patient evacuation. AirMed International leverages its dedicated fleet of medically configured jets to dominate transoceanic routes. Falck Danmark A/S anchors European coverage through its integrated ground-air network. REVA Air Ambulance specializes in Caribbean and Latin American corridors where island geography demands fixed wing range.
Fixed wing air ambulance service denotes aeromedical transport using pressurized aircraft capable of sustained cruise above weather systems, typically configured with ICU-grade ventilators, multi-parameter monitors, and isolation chambers for infectious disease cases. These platforms serve primary commercial purposes spanning inter-hospital transfer of hemodynamically unstable patients and evacuation from remote regions lacking tertiary care capacity. Jet aircraft models command premium positioning due to speed and altitude capabilities that reduce physiological stress during critical care transport. Emergency medical transport generates the highest per-mission revenue but faces capacity constraints from crew rest regulations. Medical tourism applications are maturing in corridors linking Middle Eastern and South Asian origin markets with European and North American destination hospitals.
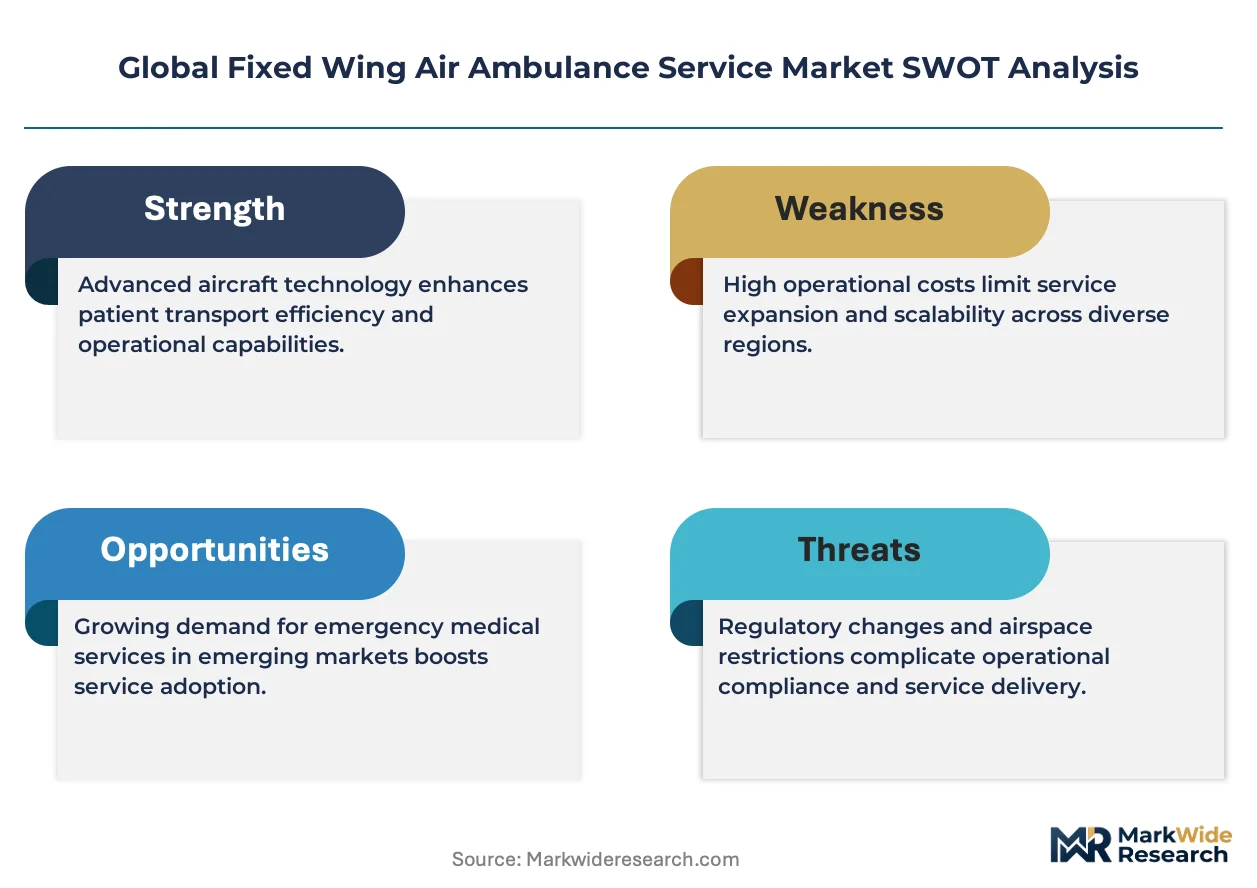
FAA Part 135 operating certificates, EASA SPA.MED specifications, and ICAO aeromedical evacuation standards collectively govern aircraft configuration, crew training minima, and patient care documentation across jurisdictions. These frameworks elevate capital requirements for market entry while creating compliance moats for established certificate holders. Stakeholders must monitor evolving carbon offset mandates and sustainable aviation fuel obligations that will reshape fleet replacement timelines and route economics.
Market Dynamics
Fleet operators face mounting pressure from FAA Part 135 recertification timelines and EASA SPA.MED configuration mandates that compress aircraft availability windows. Certificate holders with established aeromedical approvals capture disproportionate mission volume as new entrants confront 18-24 month compliance horizons.
Growth Catalysts
- ICAO Aeromedical Evacuation Standards:Harmonized patient care documentation protocols reduce cross-border transfer friction. Gulf Cooperation Council health ministries align procurement specifications with these frameworks.
- Hub-and-Spoke Hospital Consolidation:United States health systems centralize tertiary capacity in metropolitan clusters. Rural facilities increasingly contract dedicated fixed wing services rather than maintaining in-house rotary assets.
- Isolation Chamber Retrofits:Infectious disease transport capability expands addressable mission types. German air ambulance operators report elevated contract values for biocontainment-configured aircraft.
Market Restraints
- Pilot-Medical Crew Pairing Requirements:FAA crew rest regulations constrain daily mission throughput. Certificate holders absorb fixed labor costs across fewer billable flight hours.
- Specialized Airframe Scarcity:Factory-new medically configured jets face 24-month delivery backlogs. Secondary market conversions of commercial airframes require extensive STC certification.
- Jet-A Fuel Price Volatility:Fuel represents 35-40% of variable mission costs. Long-haul transoceanic routes bear disproportionate margin compression from supply shocks.
Strategic Opportunities
- Medical Tourism Corridors:South Asian origin markets generate sustained demand for European and North American destination transfers. Fixed wing operators capture premium pricing on hemodynamically stable elective transport.
- Sustainable Aviation Fuel Mandates:EU Green Deal obligations accelerate fleet renewal timelines. Early adopters of SAF-compatible airframes secure preferential airport slot access.
- Telemedicine Integration:Real-time specialist consultation during transport reduces diversion rates. Satellite connectivity upgrades differentiate service tiers.
Industry Challenges
- Critical Care Paramedic Shortages:Aeromedical certification programs produce insufficient qualified personnel. Training pipelines require 18-24 months from recruitment to mission-ready status.
- Multi-Jurisdiction Documentation:Patient handoff protocols vary across national regulators. Mission planners allocate non-billable hours to compliance verification.
- Legacy Avionics Integration:Newer patient monitoring systems interface poorly with aging aircraft electrical architectures. Retrofit costs compete with airframe replacement capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fixed Wing Air Ambulance Service Market |
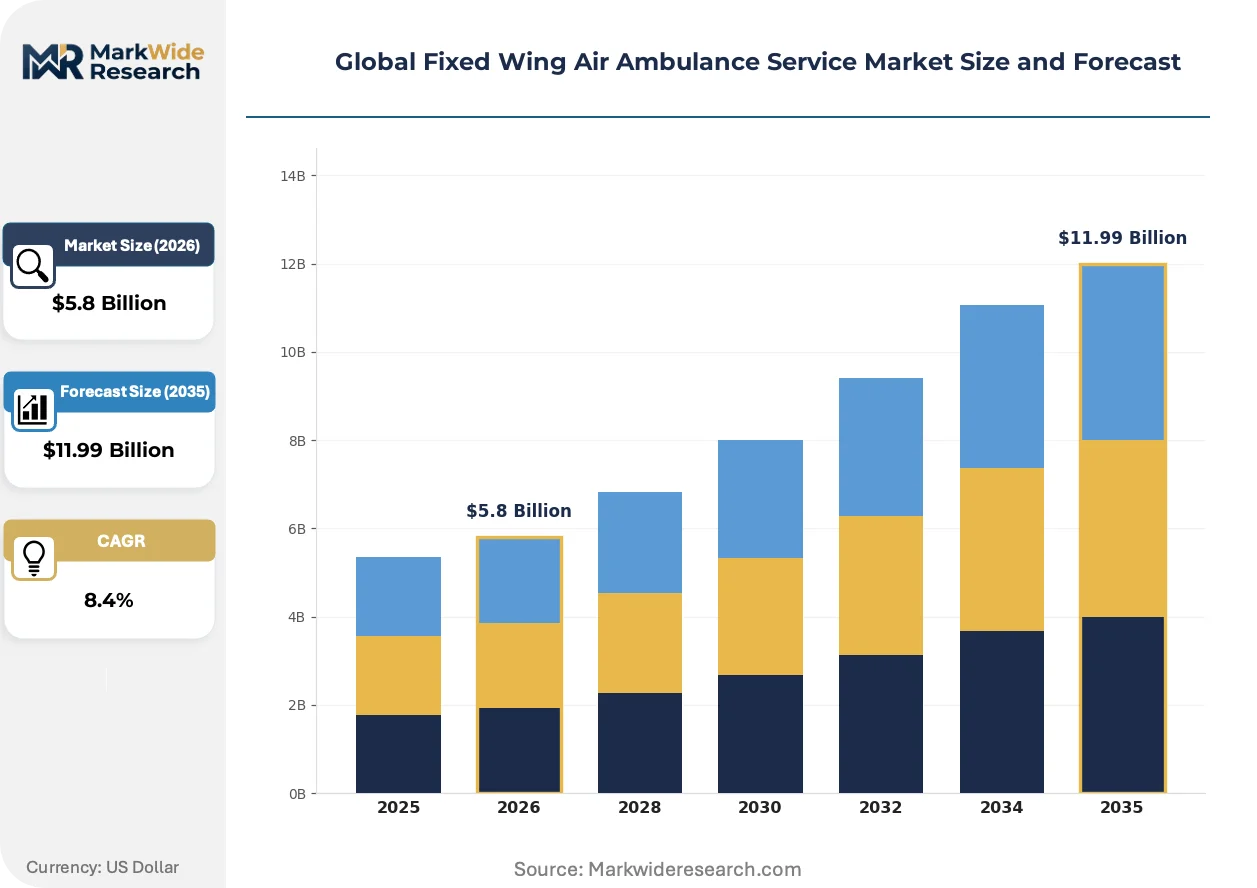
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Medical Transport, Non-Emergency Medical Transfer, Organ Transport, Neonatal Transport, Critical Care Transfer Aircraft Model: Turboprop, Jet, Twin Engine, Single Engine, Converted Commercial Customer Category: Healthcare Providers, Insurance Firms, Corporate Clients, Government Agencies, Military Units Application: Inter-Hospital Transfer, Disaster Response, Medical Tourism, Remote Area Access, Search and Rescue |
| Companies Covered | AirMed International, PHI Air Medical, AirCARE1, Envision Healthcare Companies, Air Methods Corporation, Air Ambulance 1, Angel MedFlight, Falck Danmark A/S, REVA Air Ambulance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fixed Wing Air Ambulance Service Market Strategic Shifts & Innovations
Telemedicine infrastructure and sustainable aviation commitments are restructuring fleet investment priorities. Operators differentiate through connectivity capabilities and emissions profiles rather than speed alone.
Portable ECMO systems are fragmenting the traditional inter-hospital transfer model. Previously ground-bound extracorporeal support now travels with patients above weather systems. German university hospitals deploy these units on transcontinental routes. The technology is fragmenting service boundaries between fixed wing operators and tertiary cardiac centers.
EASA SPA.MED specifications now mandate standardized patient data transmission protocols. Aircraft configuration approvals require demonstrated interoperability with receiving hospital EMR systems. European certificate holders face compressed recertification cycles. German and Swiss operators lead compliance investments.
Subscription-based membership programs displace per-mission billing for frequent travelers. Snowbird populations in Arizona and Florida purchase annual evacuation coverage. AirMed International and REVA structure pricing around anticipated utilization bands. United States retiree corridors show highest penetration.
Global Fixed Wing Air Ambulance Service Market Segmentation
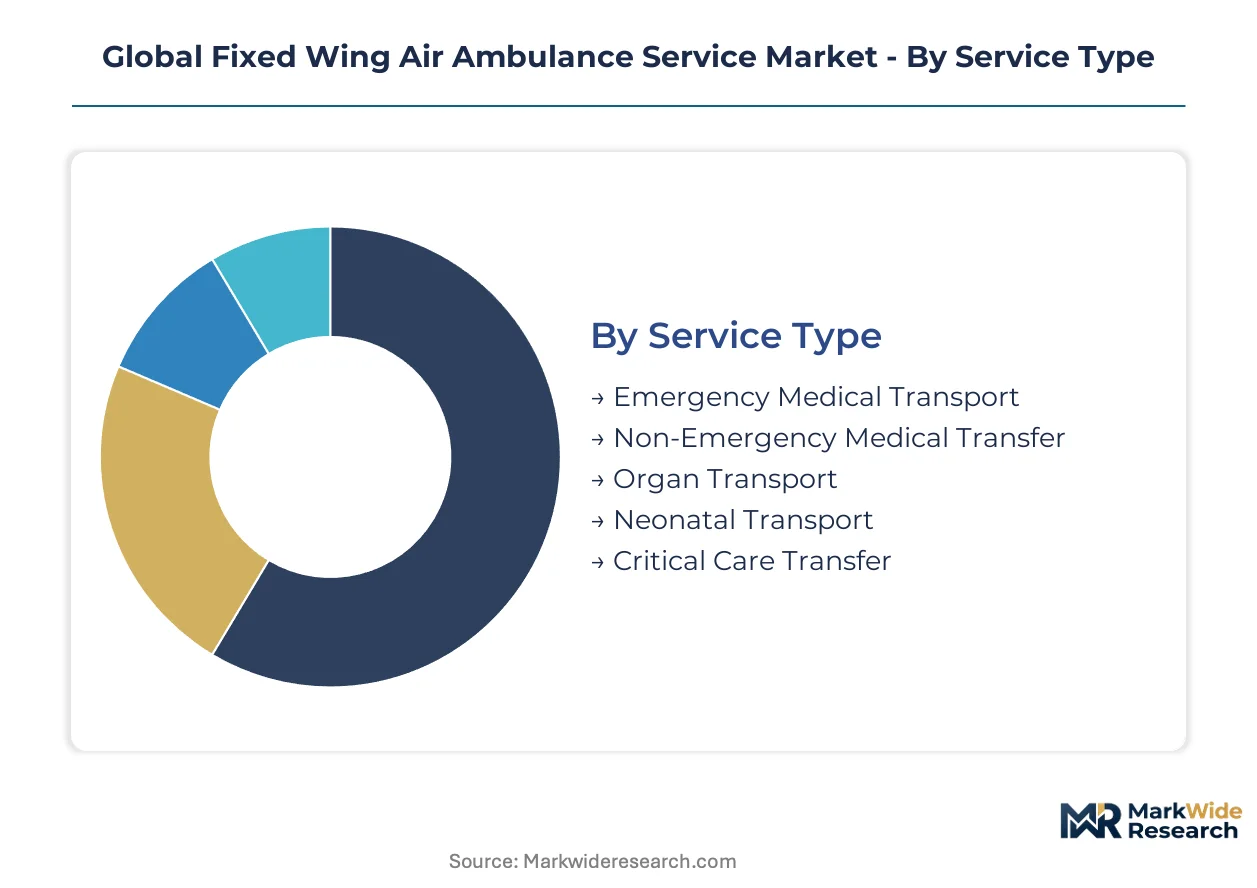
Fixed wing air ambulance service segmentation reveals distinct margin architectures across service intensity tiers and aircraft capital profiles. Each dimension carries specific regulatory compliance burdens and crew certification requirements that reshape competitive economics.
Service Type:
Emergency medical transport commands premium pricing multiples due to immediate dispatch requirements and specialized crew standby costs. Neonatal and organ transport segments concentrate margin pools in metropolitan hospital clusters with transplant center density.
- Emergency Medical Transport:Immediate-response missions requiring dedicated crew standby and ICU-grade equipment configuration. Demand concentrates in United States tertiary hospital networks facing rural access gaps, constrained by FAA crew rest regulations that limit daily mission throughput.
- Non-Emergency Medical Transfer:Scheduled inter-hospital transport for hemodynamically stable patients with lower per-mile pricing but higher asset utilization rates. German and Swiss operators capture volume through hub-and-spoke consolidation of tertiary capacity.
- Organ Transport:Time-critical missions with specialized cold-chain protocols and priority air traffic clearance. United States transplant center density drives corridor concentration between procurement and implantation sites.
- Neonatal Transport:Incubator-equipped aircraft with dedicated neonatal intensive care teams. Gulf Cooperation Council health ministries expand fleet procurement for maternity hospital network coverage.
- Critical Care Transfer:ECMO-capable platforms serving cardiac and respiratory failure patients. German university hospitals deploy these units on transcontinental routes with portable life support systems.
Emergency medical transport holds installed capacity. Critical care transfer is rotating up the share rankings.
Aircraft Model:
Jet configurations absorb disproportionate capital allocation despite smaller fleet share due to transoceanic range requirements and speed premiums. Turboprop economics dominate secondary market conversions where acquisition cost sensitivity shapes procurement decisions.
- Turboprop:Cost-efficient platforms for regional missions under 800 nautical miles with lower fuel burn and runway flexibility. Caribbean and Latin American corridors favor these airframes for island-hopping routes with limited infrastructure.
- Jet:Pressurized cabins cruising above weather systems reduce physiological stress on unstable patients. United States and United Arab Emirates operators deploy these for intercontinental medical tourism corridors demanding speed premiums.
- Twin Engine:Redundancy requirements for over-water and mountainous terrain operations. EASA SPA.MED mandates drive European certificate holder preferences for this configuration class.
- Single Engine:Limited to short-haul missions with minimal equipment payload. Cost-sensitive operators in remote area access applications favor these for basic patient evacuation.
- Converted Commercial:Secondary market airframes retrofitted with medical interiors and STC certification. Factory-new delivery backlogs extending 24 months push demand toward this capital-efficient alternative.
Jet configurations dominate transoceanic revenue. Converted commercial airframes are climbing the fastest in annual procurement volume.
Customer Category:
Healthcare providers and government agencies generate recurring contract streams with predictable utilization patterns. Insurance firms and corporate clients shift toward subscription models that reshape operator cash flow timing.
- Healthcare Providers:Hospital systems contracting dedicated fleet access for inter-hospital transfer networks. United States health system consolidation centralizes procurement through metropolitan hub facilities.
- Insurance Firms:Underwriters embedding evacuation coverage in travel and health policies. Arizona and Florida snowbird corridors show highest penetration of annual membership programs.
- Corporate Clients:Energy and mining operations requiring remote site medical evacuation capability. Gulf Cooperation Council infrastructure projects drive fleet deployment to labor camp locations.
- Government Agencies:Civilian health ministries procuring aeromedical services for public health emergency response. German federal states contract integrated ground-air networks.
- Military Units:Defense departments acquiring dedicated aeromedical evacuation capability. FAA Part 135 certificate requirements govern civilian-registered military auxiliary fleets.
Government agencies hold installed capacity. Insurance firms are gaining share fastest in contract volume growth.
Application:
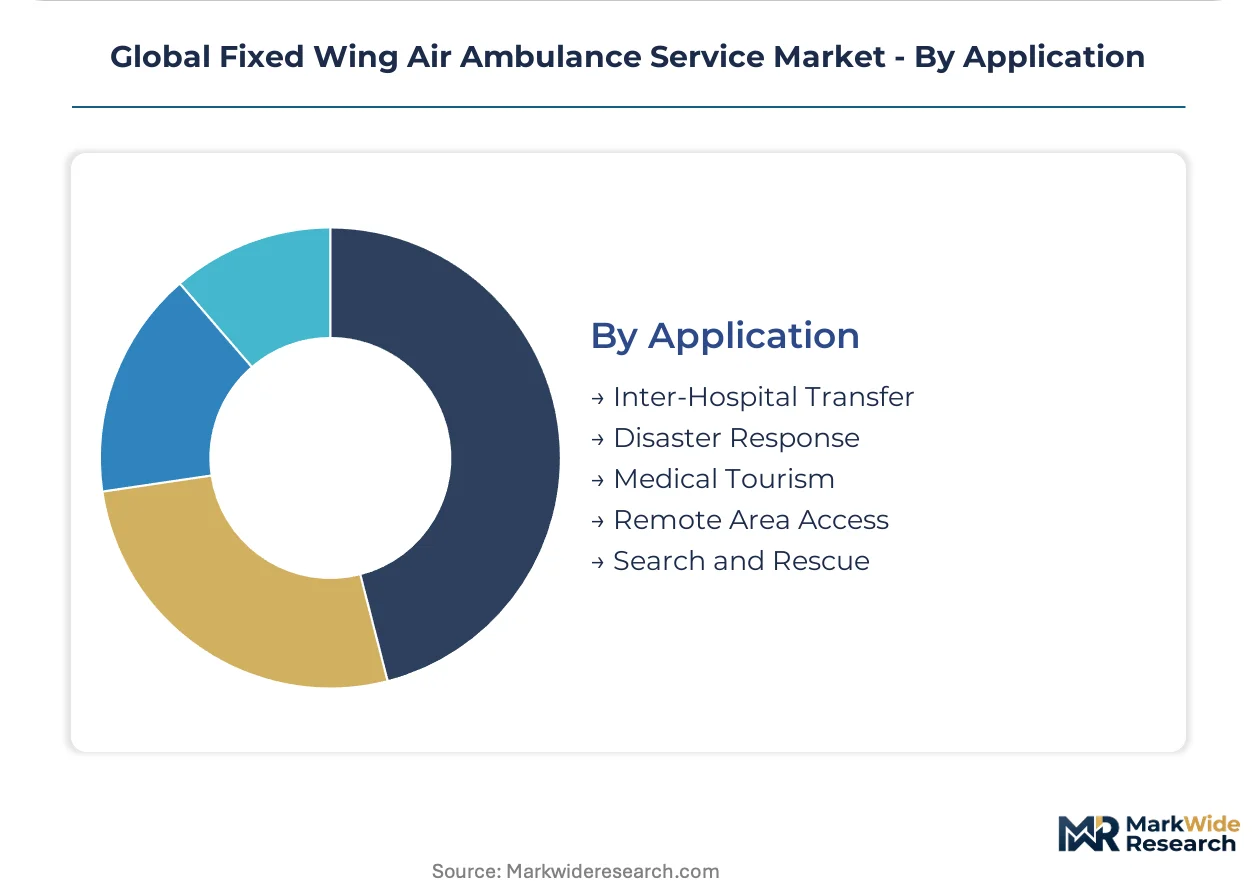
Inter-hospital transfer generates baseline revenue stability while medical tourism applications mature with premium pricing potential. Disaster response missions carry activation uncertainty but elevated per-mission economics.
- Inter-Hospital Transfer:Routine scheduled transport between tertiary and secondary facilities. United States rural hospital closures accelerate reliance on fixed wing services for patient access.
- Disaster Response:Mass casualty evacuation and medical supply distribution during natural disasters. Caribbean hurricane corridors demand surge capacity with biocontainment-configured aircraft.
- Medical Tourism:Elective transport of stable patients to destination hospitals. South Asian origin markets generate sustained demand for European and North American destination transfers.
- Remote Area Access:Mining, maritime, and expedition medical support requiring extended range capability. Australian and Canadian operators specialize in these low-frequency, high-yield missions.
- Search and Rescue:Coordinated operations with coast guard and mountain rescue services. Swiss and Austrian alpine corridors demand specialized high-altitude performance specifications.
Inter-hospital transfer holds installed capacity. Medical tourism is expanding most quickly in revenue contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports fixed wing air ambulance capacity to neighboring EU member states and Middle Eastern health ministries seeking European-standard aeromedical evacuation protocols. Transatlantic corridors from the United States serve Caribbean and Latin American destinations. Gulf Cooperation Council nations import Swiss and German-operated services for maternity hospital network coverage.
United States
Rural hospital closures and metropolitan tertiary consolidation drive inter-hospital transfer demand across Arizona, Florida, and Texas retiree corridors. FAA Part 135 certificate requirements govern civilian-registered military auxiliary fleets and commercial operators alike. Arizona snowbird populations purchase annual evacuation coverage through subscription membership programs.
Germany
Federal states contract integrated ground-air networks while university hospitals deploy ECMO-capable platforms on transcontinental routes. EASA SPA.MED specifications mandate standardized patient data transmission protocols and compressed recertification cycles. Bavaria and North Rhine-Westphalia anchor biocontainment-configured fleet procurement for infectious disease transport capability.
United Arab Emirates
Hub-and-spoke hospital networks rely on fixed wing coverage for intercontinental transfers linking Dubai and Abu Dhabi with European and North American destination hospitals. MOHAP procurement specifications align with ICAO aeromedical evacuation standards. Infrastructure projects in labor camp locations drive fleet deployment to remote site medical evacuation contracts.
Switzerland
Alpine corridors demand specialized high-altitude performance specifications for coordinated search and rescue operations with mountain rescue services. Swissmedic regulates aircraft configuration approvals requiring demonstrated interoperability with receiving hospital EMR systems. Geneva and Zurich clusters lead European compliance investments for EASA SPA.MED configuration mandates.
Australia
Mining and maritime operations require extended range capability for remote area access missions across Western Australia and Queensland. The country's national aviation regulator enforces crew rest regulations that constrain daily mission throughput. Perth and Brisbane operators specialize in low-frequency, high-yield missions serving expedition medical support contracts.
Global Fixed Wing Air Ambulance Service Market Key Industry Players
Player mix skews toward integrated medical transport networks with dedicated fleet ownership rather than ad hoc charter arrangements. Certificate holders with established aeromedical approvals capture disproportionate mission volume as new entrants confront extended compliance horizons. Two strategic archetypes dominate: vertically integrated hospital system contractors and specialized intercontinental evacuation operators. Competitive moves concentrate on fleet renewal timelines and sustainable aviation fuel compatibility upgrades.
Within the integrated network tier, Falck Danmark A/S and Air Methods Corporation exemplify operators combining ground ambulance infrastructure with fixed wing assets. AirMed International occupies a position among intercontinental specialists leveraging dedicated medically configured jet fleets. REVA Air Ambulance represents the regional corridor specialist archetype with Caribbean and Latin American geographic concentration. These three companies anchor the competitive structure without exhaustively representing all market participants.
| Leading Market Players |
|---|
| AirMed International |
| PHI Air Medical |
| AirCARE1 |
| Envision Healthcare Companies |
| Air Methods Corporation |
| Air Ambulance 1 |
| Angel MedFlight |
| Falck Danmark A/S |
| REVA Air Ambulance |
| Others |
Cost & Logistics Intelligence
Twenty-four-month delivery backlogs for factory-new medically configured jets concentrate pricing power with established certificate holders while compressing margins for operators dependent on secondary market conversions. FAA Part 135 and EASA SPA.MED compliance timelines further tighten supply availability, allowing incumbent fleet owners to command premium positioning on intercontinental routes where speed and altitude capabilities justify rate multiples.
Pricing Analysis
Next-generation jet configurations with SAF-compatible airframes command substantial premiums over prior-generation turboprop platforms and aging converted commercial airframes. Pricing stratifies across premium, standard, and economy tiers based on certification grade and equipment payload capacity. Cost compression in the turboprop segment is intensifying because fuel price volatility disproportionately impacts regional operators with thinner margin structures. Insurance firms and corporate subscription clients demonstrate highest price sensitivity, while government agencies and tertiary hospital systems absorb premium rates for guaranteed response capacity.
Supply Chain Analysis
Container availability constraints on transatlantic trade lanes from Germany and the United States inflate inbound logistics costs for specialized medical equipment and avionics components. Manufacturing concentration for pressurized cabin modifications and ICU-grade life support systems centers on the United States, Germany, and Switzerland. Raw material dependencies include aerospace-grade aluminum alloys, satellite connectivity hardware, and portable ECMO systems. Single-source vulnerability for STC-certified medical interior configurations creates supply chain risk. Distribution runs through integrated ground-air network operators rather than discrete equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed wing air ambulance operators face substitution pressure from advancing portable ECMO systems that enable ground-bound cardiac centers to retain patients previously requiring aerial transfer. Incumbents must navigate this capability migration while defending certificate-based competitive moats.
For Market Incumbents: Compound fleet renewal investments with SAF-compatible airframe procurement to secure preferential airport slot access under EU Green Deal obligations. Deepen backward integration into ground ambulance infrastructure to capture integrated network economics. Defend against emerging telemedicine-enabled competitors by embedding real-time specialist consultation as a standard service tier.
For New Entrants and Emerging Players: EASA SPA.MED fast-track certification programs offer accelerated market entry pathways for biocontainment-configured aircraft operators. White-space targets concentrate in Caribbean hurricane corridors and South Asian medical tourism origin markets where established certificate holder coverage remains thin. Pursue subscription-based membership models in Arizona and Florida retiree corridors to displace per-mission billing structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from hospital system auxiliary fleets seeking to monetize non-core aeromedical assets. Long-term viability hinges on regulatory compliance scalability rather than fleet size alone. Monitor ICAO aeromedical evacuation standard harmonization progress as an inflection indicator for cross-border contract expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF-Compatible Fleet Renewal | EU Green Deal slot preferences reward early adopters with airport access advantages. |
| Telemedicine Infrastructure Deployment | Satellite connectivity upgrades reduce diversion rates and differentiate service tiers. |
| Biocontainment Configuration Investment | EASA SPA.MED mandates expand addressable mission types for infectious disease transport. |
| Subscription Membership Program Launch | Snowbird corridors in Arizona and Florida show highest annual coverage penetration. |
| Integrated Ground-Air Network Expansion | German federal states contract consolidated services rather than discrete operators. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aeromedical fleet managers, FAA Part 135 certificate holders, EASA compliance officers, hospital procurement committees, and insurance underwriters. Secondary validation drew from FAA certification databases, EASA SPA.MED regulatory filings, ICAO aeromedical evacuation standards documentation, and hospital procurement contract registries. Bottom-up mission volume estimates triangulated against top-down fleet capacity assessments.
Across the analysis window, the forecasting framework modeled service type intensity tiers, aircraft capital profiles, customer category contract structures, and application corridor economics. CAGRs were derived from segmented mission volume projections and per-mile pricing trajectories. Industry-specific inputs included crew rest regulation constraints, fuel cost pass-through assumptions, and certificate holder concentration dynamics.
Underlying assumptions cover stable regulatory compliance timelines and sustained tertiary hospital consolidation, with deviation risk concentrated in carbon offset mandate acceleration and sustainable aviation fuel supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Emergency Medical Supplies Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
Air Ambulance Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
Europe Air Ambulance Services Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
First Aid Market