
 Needle-Free Injectors Market | 2026-2036
Needle-Free Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Needle-Free Injectors Market Intelligence
Project finance partnerships between device manufacturers and pharmaceutical distributors is rewriting competitive entry barriers in needle-free delivery. PharmaJet leverages its vertical integration into spring-loaded device production to sustain cost advantages across hospital procurement cycles. Antares Pharma anchors its position through specialized insulin delivery platforms that dominate home care channels. Portal Instruments competes via electromechanical precision systems that extend its reach into allergy treatment protocols.
Needle-free injectors are drug delivery devices that propel liquid or powdered formulations through the skin using high-pressure jets, laser pores, or bio-microneedle arrays without penetrating metal needles, typically operating at pressures between 100 and 3000 psi to achieve consistent intradermal or intramuscular deposition. Spring-loaded injectors lead unit shipments due to mechanical simplicity and lower per-dose cost, while jet injection systems capture premium margins in emergency services where speed and sterility override price sensitivity. Home care adoption of vibration-driven devices is accelerating fastest as patient self-administration protocols expand beyond traditional clinical settings.
FDA premarket notification pathways and ISO 11608-6 standards for needle-free injectors shape product development timelines and interoperability requirements for manufacturers targeting US commercialization. The EPA regulates propellant gas formulations in pressurized delivery systems, constraining material choices for gas-driven injector architectures. Stakeholders must monitor evolving CMS reimbursement codes for home-based needle-free administration, as coverage determinations will dictate which end-user segments justify sustained R&D investment.
Market Dynamics
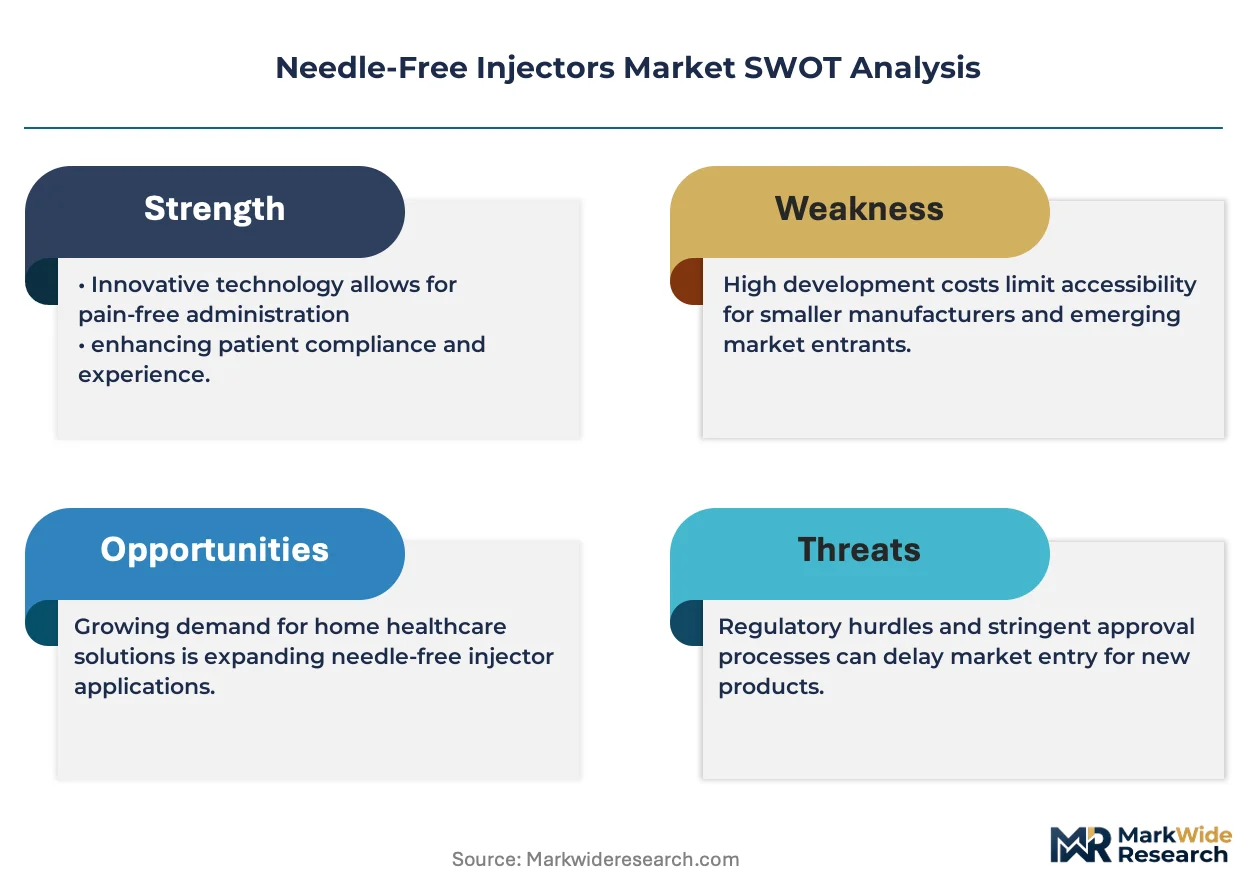
Hospital procurement networks in the United States are consolidating purchasing authority for mass immunization campaigns, forcing device manufacturers to redesign go-to-market strategies around centralized tender processes rather than decentralized clinical sales.
Growth Catalysts
- Pediatric vaccination mandates:School-entry immunization requirements in multiple US states are expanding the addressable population for child-friendly delivery systems.
- ISO 11608-6 harmonization:Standardized testing protocols for needle-free injectors are reducing regulatory friction for cross-border device approvals.
- Spring-loaded mechanical platforms:Simplified engineering architectures are cutting per-unit production costs below electromechanical alternatives.
Market Restraints
- Propellant gas constraints:EPA regulations on fluorinated gas formulations are limiting material options for pressurized delivery architectures.
- Spring steel supply concentration:Specialty alloy sourcing clusters in East Asian forging operations create input vulnerability.
- Jet injection depth variability:Subcutaneous tissue density differences across patient populations produce inconsistent deposition profiles.
Strategic Opportunities
- Home care insulin protocols:Self-administration training programs for diabetic patients are opening direct-to-consumer channels outside clinical settings.
- EMA MDR transition timelines:Extended conformity assessment periods for Class IIa devices create temporary competitive windows for early filers.
- Vibration-driven microneedle convergence:Hybrid mechanical-piezoelectric systems are merging pain reduction with precision dosing.
Industry Challenges
- Biocompatibility certification delays:ISO 10993 testing backlogs for novel polymer nozzles are stretching product launch timelines.
- Legacy EMR integration complexity:Dose-tracking software must map to hospital information systems with incompatible data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Needle-Free Injectors Market |
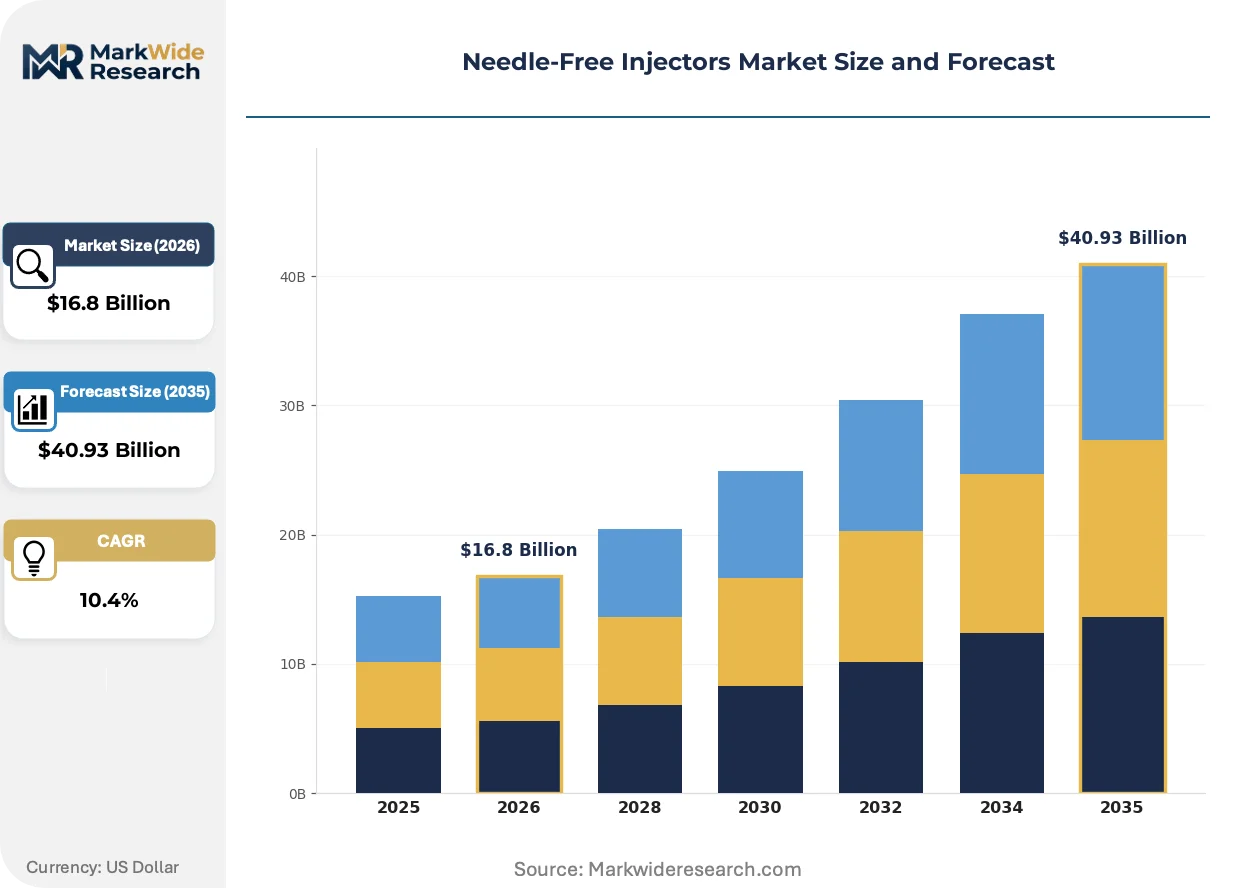
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $40.93 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring-Loaded Injectors, Gas-Driven Injectors, Vibration-Driven Injectors, Hybrid Injectors Application: Vaccination, Insulin Delivery, Allergy Treatment, Pain Management End User: Hospitals, Clinics, Home Care, Emergency Services Technology: Electromechanical Systems, Jet Injection Systems, Powders, Bio-Microneedle Systems |
| Companies Covered | PharmaJet, Antares Pharma, Portal Instruments, Medical International Technology (MIT), Crossject, NuGen Medical Devices, Inovio Pharmaceuticals, Bioject Medical Technologies, Zogenix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Needle-Free Injectors Market Strategic Shifts & Innovations
Device architectures are fragmenting across three parallel development tracks. Electromechanical precision, mechanical simplicity, and hybrid vibration systems are each capturing distinct use-case clusters without consolidating around a dominant design.
Jet injection technology is migrating from emergency services deployment into routine outpatient protocols. Ambulatory surgery centers are adopting high-pressure liquid systems for local anesthetic delivery. The shift is compressing price premiums that previously separated hospital-grade from field-grade equipment.
FDA updated guidance on needle-free delivery systems is restructuring 510(k) submission requirements for combination products. Manufacturers must now demonstrate drug-device interaction stability across temperature ranges. Prefilled cartridge developers are responding with accelerated stability testing protocols.
Patient self-administration training is displacing clinician-supervised injection as the default onboarding model. Pharmacy chains are building certification programs for home-use device operation. Germany and Japan are seeing the fastest uptake of remote training platforms with virtual reality components.
Needle-Free Injectors Market Segmentation
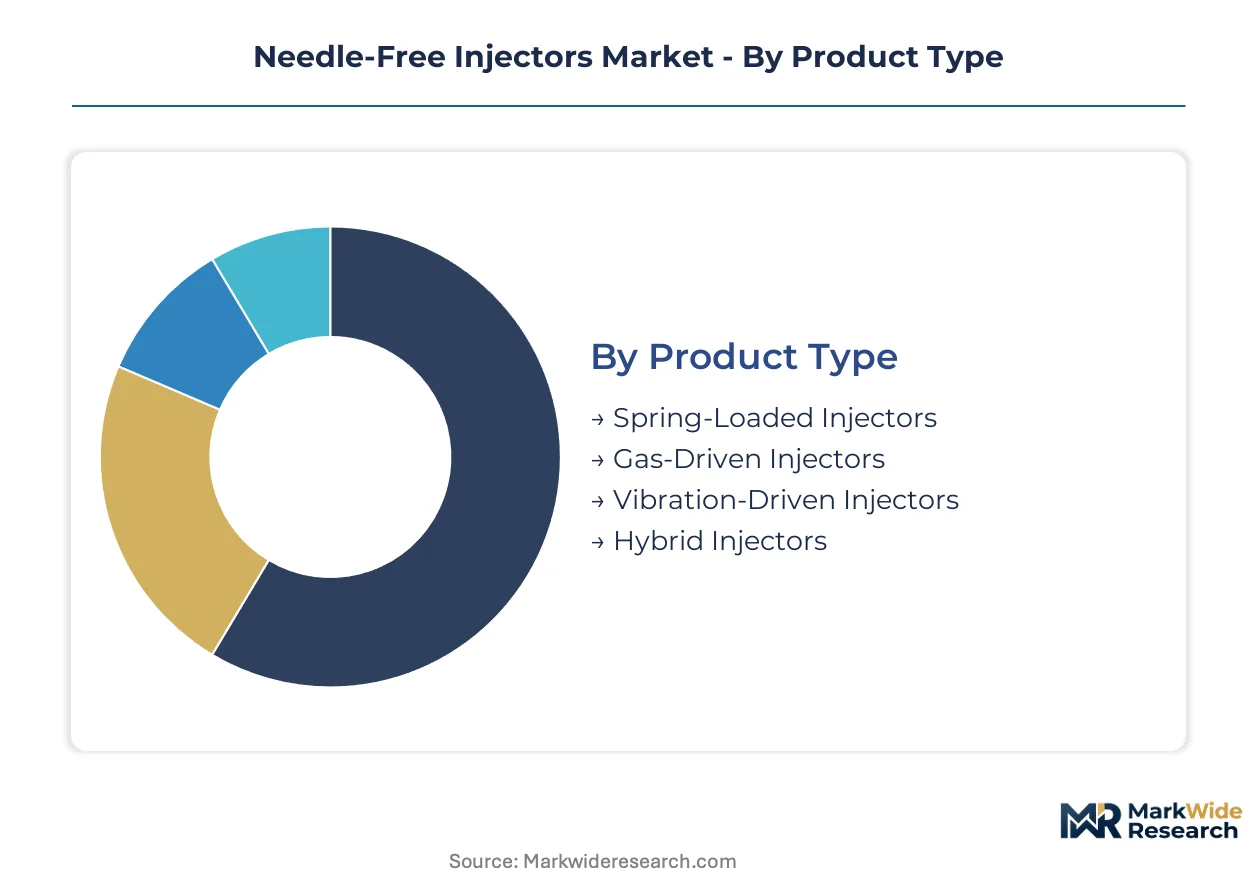
Segmentation in needle-free injectors reveals how device physics, clinical setting, and patient population interact to determine procurement patterns. Each dimension carries distinct regulatory footprints and margin structures that reshape competitive positioning across the value chain.
Product Type:
Cost tier determines manufacturing scale and per-dose economics across mechanical, pneumatic, and hybrid delivery architectures.
- Spring-Loaded Injectors:Mechanical energy stored in torsion springs propels drug formulations at 100-300 psi through precision nozzles. Hospital procurement networks in the United States favor these units for mass immunization campaigns due to lower per-dose costs and minimal maintenance requirements. Spring steel supply concentration in East Asian forging operations creates input vulnerability for manufacturers.
- Gas-Driven Injectors:Pressurized propellant systems generate higher velocity jets suitable for viscous biologics. Demand concentrates in emergency services where speed and sterility override price sensitivity. EPA regulations on fluorinated gas formulations constrain material choices and compress margins for device developers.
- Vibration-Driven Injectors:Piezoelectric oscillation reduces tissue trauma through controlled frequency modulation. Home care adoption is climbing the fastest as patient self-administration protocols expand beyond traditional clinical settings.
- Hybrid Injectors:Combined mechanical-piezoelectric systems merge pain reduction with precision dosing for pediatric populations.
Spring-Loaded Injectors hold installed capacity. Vibration-Driven Injectors is rotating up the share rankings.
Application:
Clinical use case dictates pressure requirements, dosing volume, and regulatory pathway complexity for device developers.
- Vaccination:High-volume, low-viscosity delivery demands rapid cycle times and multi-dose cartridges. School-entry immunization mandates in multiple US states are expanding the addressable population for child-friendly delivery systems. ISO 11608-6 harmonization is reducing regulatory friction for cross-border device approvals.
- Insulin Delivery:Chronic self-administration protocols prioritize portability, dose accuracy, and minimal training burden. Specialized insulin delivery platforms dominate home care channels through direct-to-consumer distribution models.
- Allergy Treatment:Precision intradermal deposition requires electromechanical control systems. Electromechanical precision systems extend reach into allergy treatment protocols with sub-millimeter depth control.
- Pain Management:Local anesthetic delivery in ambulatory surgery centers is compressing price premiums between hospital-grade and field-grade equipment.
Vaccination holds installed capacity. Insulin Delivery is rotating up the share rankings.
End User:
Customer type shapes purchasing authority, training requirements, and reimbursement pathway complexity.
- Hospitals:Centralized procurement networks consolidate purchasing authority for mass immunization campaigns, forcing manufacturers to redesign go-to-market strategies around tender processes rather than decentralized clinical sales. FDA premarket notification pathways and ISO 11608-6 standards shape product development timelines.
- Clinics:Outpatient settings favor mid-pressure jet systems for routine administration with moderate throughput requirements.
- Home Care:Self-administration training programs for diabetic patients are opening direct-to-consumer channels outside clinical settings. CMS reimbursement codes for home-based needle-free administration will dictate which end-user segments justify sustained R&D investment.
- Emergency Services:Field deployment demands ruggedized, single-use systems with instant readiness and no power dependency.
Hospitals hold installed capacity. Home Care is rotating up the share rankings.
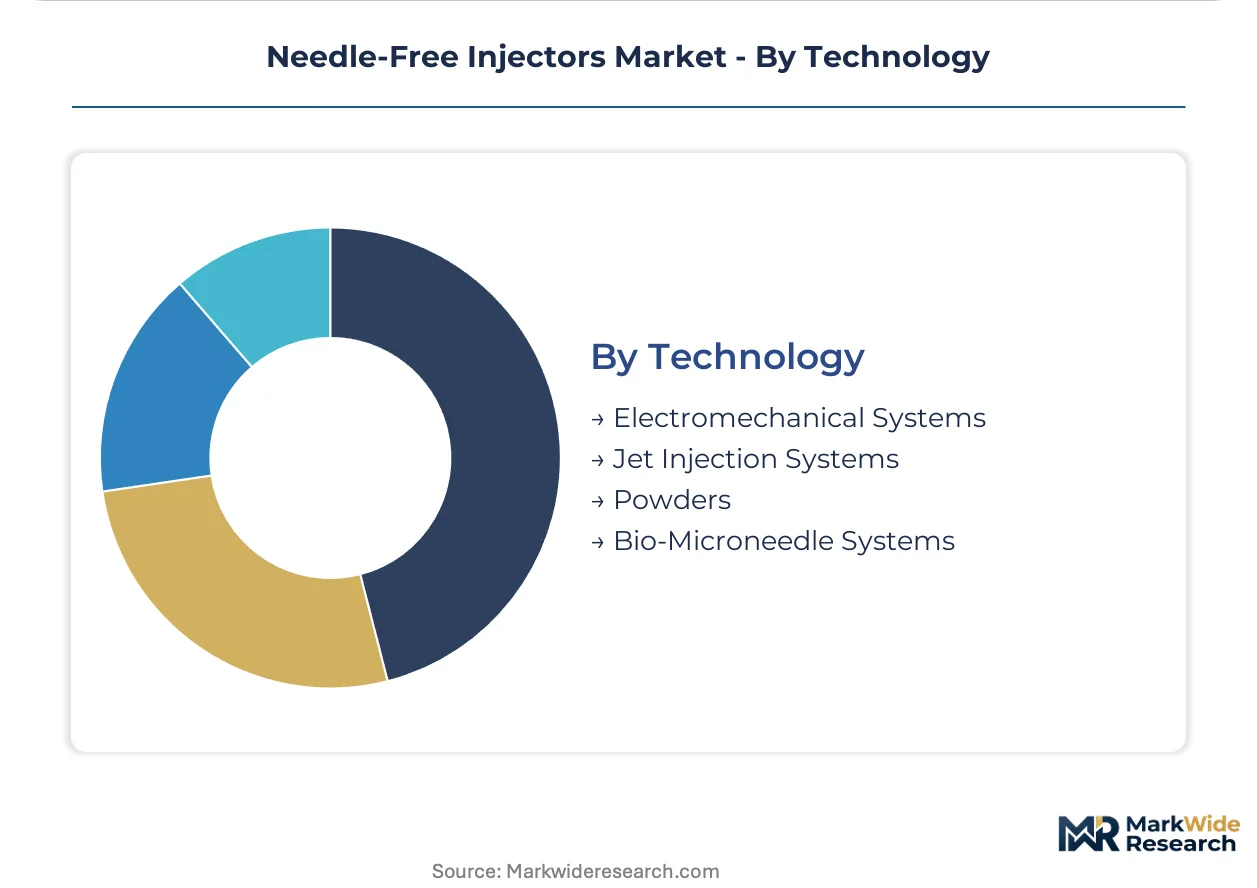
Technology:
Engineering maturity separates established platforms from emerging architectures competing on precision, payload flexibility, or biocompatibility.
- Electromechanical Systems:Programmable pressure profiles and real-time feedback sensors enable sub-millimeter deposition control. Specialized insulin delivery platforms and allergy treatment protocols anchor demand concentration.
- Jet Injection Systems:High-pressure liquid streams achieve consistent intradermal or intramuscular deposition without metal penetration. Emergency services and hospital mass immunization campaigns drive volume.
- Powders:Dry formulation delivery eliminates cold-chain requirements for thermally sensitive biologics. Thermostable vaccine presentations are gaining traction in resource-limited settings.
- Bio-Microneedle Systems:Dissolvable polymer arrays achieve painless transdermal delivery with controlled release kinetics. ISO 10993 testing backlogs for novel polymer nozzles are stretching product launch timelines.
Jet Injection Systems hold installed capacity. Bio-Microneedle Systems is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on needle-free delivery systems is accelerating hospital procurement standardization in the United States. Germany's EMA MDR transition timelines create temporary competitive windows for early device filers. Japan's PMDA is streamlining approval pathways for home-care self-administration platforms.
United States
School-entry immunization mandates in multiple states are expanding demand for pediatric-friendly delivery systems. FDA updated guidance on needle-free delivery systems is restructuring 510(k) submission requirements for combination products. Hospital procurement networks in Texas and California are consolidating purchasing authority for mass immunization campaigns around centralized tender processes.
Germany
EMA MDR transition timelines for Class IIa devices are creating temporary competitive windows for early conformity assessment filers. The country's national pharmaceutical regulator is harmonizing testing protocols with ISO 11608-6 standards for cross-border device approvals. Industrial clusters in Baden-Württemberg and Bavaria host precision engineering operations supplying spring-loaded mechanical platforms to European hospital networks.
Japan
Remote training platforms with virtual reality components are gaining fastest uptake among diabetic patients for home-care insulin protocols. METI is supporting domestic development of vibration-driven microneedle convergence technologies. The Kanto region around Tokyo anchors electromechanical precision system manufacturing for allergy treatment applications.
China
NMPA is accelerating review timelines for needle-free injectors targeting vaccination programs in provincial health systems. The country's national pharmaceutical regulator is aligning stability testing requirements with FDA temperature-range demonstration standards. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang are scaling production of spring steel components for mechanical injection platforms.
India
CDSCO is expanding prequalification pathways for needle-free devices in government immunization procurement. The country's national pharmaceutical regulator is adopting ISO 11608-6 testing protocols to reduce regulatory friction for imported device platforms. Maharashtra and Gujarat industrial corridors are attracting contract manufacturing for spring-loaded injectors serving South Asian hospital networks.
Needle-Free Injectors Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent go-to-market architectures. Hospital procurement network consolidation in the United States is favoring vendors with centralized tender capabilities over decentralized clinical sales organizations. Three archetypes dominate: vertically integrated device-drug combination developers, precision electromechanical specialists, and mechanical platform cost leaders. Strategic moves concentrate on backward integration into component supply and geographic expansion through regulatory early-filing in EMA MDR transition windows.
Among North American device developers, PharmaJet, Antares Pharma, and Portal Instruments occupy distinct positioning vectors. PharmaJet exemplifies the vertically integrated archetype through captive supply of spring-loaded mechanical platforms. Antares Pharma anchors the precision electromechanical tier with specialized insulin delivery positioning. Portal Instruments represents the convergence-focused segment targeting hybrid vibration-piezoelectric architectures for pediatric and allergy applications. These three entities collectively illustrate how divergent engineering philosophies can sustain parallel competitive positions without consolidation around a single dominant design.
| Leading Market Players |
|---|
| PharmaJet |
| Antares Pharma |
| Portal Instruments |
| Medical International Technology (MIT) |
| Crossject |
| NuGen Medical Devices |
| Inovio Pharmaceuticals |
| Bioject Medical Technologies |
| Zogenix |
| Others |
Cost & Logistics Intelligence
Underutilized spring steel forging capacity in Jiangsu and Zhejiang provinces is compressing input costs for mechanical injector platforms while simultaneously eroding pricing power for gas-driven architectures facing EPA propellant constraints. This divergence between component-level abundance and formulation-level scarcity is redistributing margin pools across the device value chain.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared combination products and economy-tier mechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels anchors hospital procurement negotiations, with ISO 11608-6 compliance serving as the threshold for standard-tier eligibility. Cost compression in spring-loaded segments is intensifying because East Asian component oversupply outpaces demand absorption. Emergency services demonstrate least price sensitivity due to sterility-critical procurement protocols, while provincial vaccination programs exhibit highest sensitivity to per-dose economics.
Supply Chain Analysis
Contract manufacturing concentrates among Yangtze River Delta precision engineering clusters and Baden-Württemberg medical device foundries. Specialty alloy sourcing draws from East Asian forging operations, piezoelectric ceramic supply rests on Japanese material science houses, and polymer nozzle production centers on German compounding specialists. Single-source vulnerability in spring steel supply creates exposure to regional logistics disruptions. Distribution runs through centralized hospital procurement networks in the United States and pharmaceutical distributor consignment models in European outpatient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Needle-free injectors represent an early-cycle expansion story as pediatric vaccination mandates and home-care insulin self-administration protocols penetrate previously clinician-dependent delivery settings.
For Market Incumbents: Entrench position through backward integration into spring steel component supply and captive production of ISO 11608-6 testing capacity. Gas-driven portfolio exposure to EPA fluorinated gas restrictions demands accelerated pivot toward mechanical and hybrid architectures. Channel control through GPO contract consolidation defends against emerging electromechanical specialists.
For New Entrants and Emerging Players: Southeast Asian hospital networks present the most penetrable geographic white space due to lagging EMA MDR alignment and reliance on imported device platforms. Vibration-driven home-care insulin delivery offers the fastest share rotation opportunity as CMS reimbursement codes mature. Partnership with pharmacy chain certification programs provides direct-to-consumer channel access without clinical sales infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across spring-loaded mechanical platforms due to component commoditization, while electromechanical precision systems require sustained R&D burn. Long-term viability favors vertically integrated device-drug combination developers with captive regulatory affairs capabilities. Watch for FDA 510(k) submission volume in hybrid vibration-piezoelectric architectures as inflection signal for platform convergence timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11608-6 Certification Investment | Harmonized testing protocols accelerate cross-border approvals for European and Asian hospital networks. |
| Spring Steel Backward Integration | Captive forging capacity insulates margin structure from East Asian supply concentration risks. |
| Home-Care Reimbursement Strategy | CMS coverage determination alignment unlocks direct-to-consumer channels for insulin delivery platforms. |
| Hybrid Vibration-Piezoelectric Development | Convergence technologies capture pediatric and allergy treatment protocols with precision dosing advantages. |
| Pharmacy Chain Partnership | Retail certification programs displace clinician-supervised onboarding for self-administration patient populations. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, regulatory affairs leads, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EMA MDR submission databases, ISO standard development records, and hospital procurement tender archives. Bottom-up device shipment modeling and top-down pharmaceutical delivery market sizing were triangulated to constrain estimate ranges.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology tier alongside regional regulatory cluster differentiation. CAGRs were derived from installed base evolution and replacement cycle analysis. Forecast inputs incorporated EMA MDR transition timeline assumptions and CMS reimbursement code development trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by spring-loaded mechanical specialists or accelerated FDA guidance revisions would shift outcomes. Forecasts reflect documented assumptions regarding regulatory harmonization pace and hospital procurement consolidation cadence. Quarterly review of FDA 510(k) submission volumes and East Asian spring steel spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pipetting Systems Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Global Wearable Skin Patch Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Global Ileostomy Market
Medical Devices
Organoids Kits Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Operating Room Integration Market