
 Prefilled Syringe Small Molecule Market | 2026-2036
Prefilled Syringe Small Molecule Market Size, Share, and Industry Trends Forecast 2026-2036
Prefilled Syringe Small Molecule Market Analytics
Hospital procurement of ready-to-administer injectables is rotating toward outpatient and homecare settings as payers push for site-of-care shifts. Pfizer Inc. leverages its sterile injectables portfolio to anchor positions in oncology and pain management prefilled formats. Sanofi sustains diabetes leadership through concentrated insulin glargine syringe supply chains. Becton Dickinson dominates delivery system manufacturing with integrated needle-syringe platforms that reduce contamination risk.
A prefilled syringe small molecule is a sterile, single-dose glass or polymer barrel preloaded with a synthetic low-molecular-weight drug, sealed with an elastomer plunger and bonded needle or luer lock, designed for immediate parenteral administration without compounding. Its primary purpose is eliminating dosing errors and contamination risks in acute and chronic therapy settings. Subcutaneous delivery mode captures the fastest structural expansion as biologic-naive small molecules migrate to self-administration formats. Oncology treatments command the deepest margin pools due to cytotoxic handling requirements and cold chain complexity. Homecare end users represent the emerging demand arc as reimbursement frameworks expand beyond institutional settings.
The FDA enforces container closure integrity and extractables-leachables profiles under combination product rules, while ISO 11040-6 governs prefilled syringe functional testing. The EMA's MDR migration in Europe and Japan's PMDA sterile product guidelines are raising barrier-to-entry thresholds for non-integrated manufacturers. Stakeholders must monitor regulatory divergence between glass-barrel and polymer-barrel acceptance criteria as material substitution accelerates.
Market Dynamics
Site-of-care migration from institutional settings to outpatient and home environments is compressing traditional hospital procurement cycles while demanding cold-chain infrastructure capable of supporting patient self-administration.
Growth Catalysts
- ISO 11040-6 Functional Testing Mandates:Updated syringe performance standards are eliminating marginal suppliers and consolidating demand around validated manufacturers with integrated quality systems.
- Diabetes Self-Injection Expansion:Concentrated insulin glargine formats are migrating from clinical supervision to homecare settings, expanding addressable patient populations beyond institutional capacity constraints.
- German Reimbursement Frameworks:Statutory health insurance coverage for ambulatory parenteral therapies is accelerating prefilled format adoption among chronic disease patients.
Market Restraints
- Borosilicate Glass Supply Concentration:Three European and Asian suppliers control pharmaceutical-grade barrel production, creating vulnerability to energy cost shocks and export restrictions.
- Extractables-Leachables Testing Burden:FDA combination product rules require extensive analytical validation for each drug-container pairing, extending development timelines for multi-product portfolios.
- Elastomer Plunger Compatibility Limits:Current rubber formulations face degradation risks with certain solvent-based small molecules, restricting formulation flexibility.
Strategic Opportunities
- Japan Homecare Reimbursement Expansion:METI and PMDA initiatives supporting patient-administered oncology therapies are opening premium-priced segments for cytotoxic-ready prefilled formats.
- Cyclic Olefin Polymer Substitution:Glass-barrel alternatives are penetrating moisture-sensitive small molecule categories previously excluded from polymer acceptance.
- United States 340B Program Evolution:Hospital outpatient department restructuring is creating direct-to-patient dispensing channels bypassing traditional wholesale distribution.
Industry Challenges
- Container Closure Integrity Validation:Demonstrating seal performance across temperature excursions requires specialized equipment and analytical expertise scarce outside integrated manufacturers.
- Legacy Fill-Finish Equipment Retrofit:Converting existing lines for ready-to-administer formats demands capital outlay for isolator technology and automated inspection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefilled Syringe Small Molecule Market |
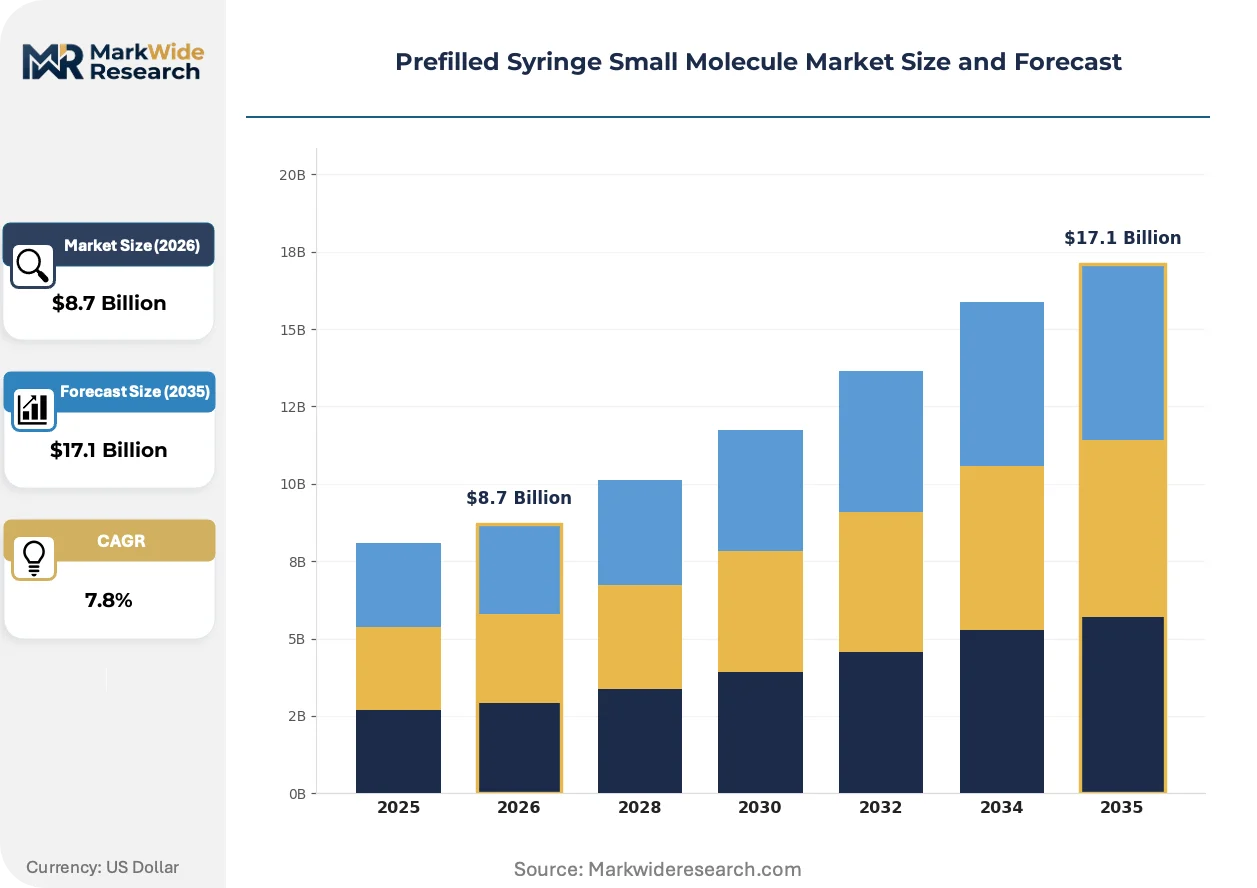
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Vaccines, Hormones, Antibodies Application: Diabetes Management, Oncology Treatments, Pain Management, Immunotherapy Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Intra-articular End User: Hospitals, Clinics, Homecare, Pharmacy |
| Companies Covered | Pfizer Inc., Sanofi, Viatris, F. Hoffmann-La Roche Ltd., AstraZeneca, Becton Dickinson, Gerresheimer, SCHOTT AG, West Pharmaceutical Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefilled Syringe Small Molecule Market Evolving Landscape
Material science advances and regulatory harmonization efforts are converging to redefine acceptable performance thresholds for parenteral delivery systems, with implications spanning manufacturing investment and competitive positioning.
Cyclic olefin polymer barrels are supplanting traditional glass formats in moisture-sensitive small molecule applications. Oncology and hormone therapy manufacturers are adopting these alternatives to reduce breakage rates during cold chain distribution. The shift is compressing quality-related rejection costs while enabling lighter shipping configurations.
EMA MDR migration is elevating technical documentation requirements for syringe-drug combination products. Manufacturers must now submit comprehensive clinical evidence of container interaction profiles prior to market authorization. European oncology and anticoagulant segments are responding by consolidating supplier relationships around notified body-preferred vendors.
Hospital purchasing cooperatives are unbundling traditional distribution contracts to secure direct manufacturer relationships for high-volume prefilled injectables. Group purchasing organizations are losing leverage as specialty pharmacy networks and ambulatory surgery centers negotiate standalone agreements. This fragmentation is most pronounced in United States cancer care settings where site-of-care economics dominate sourcing decisions.
Prefilled Syringe Small Molecule Market Segmentation
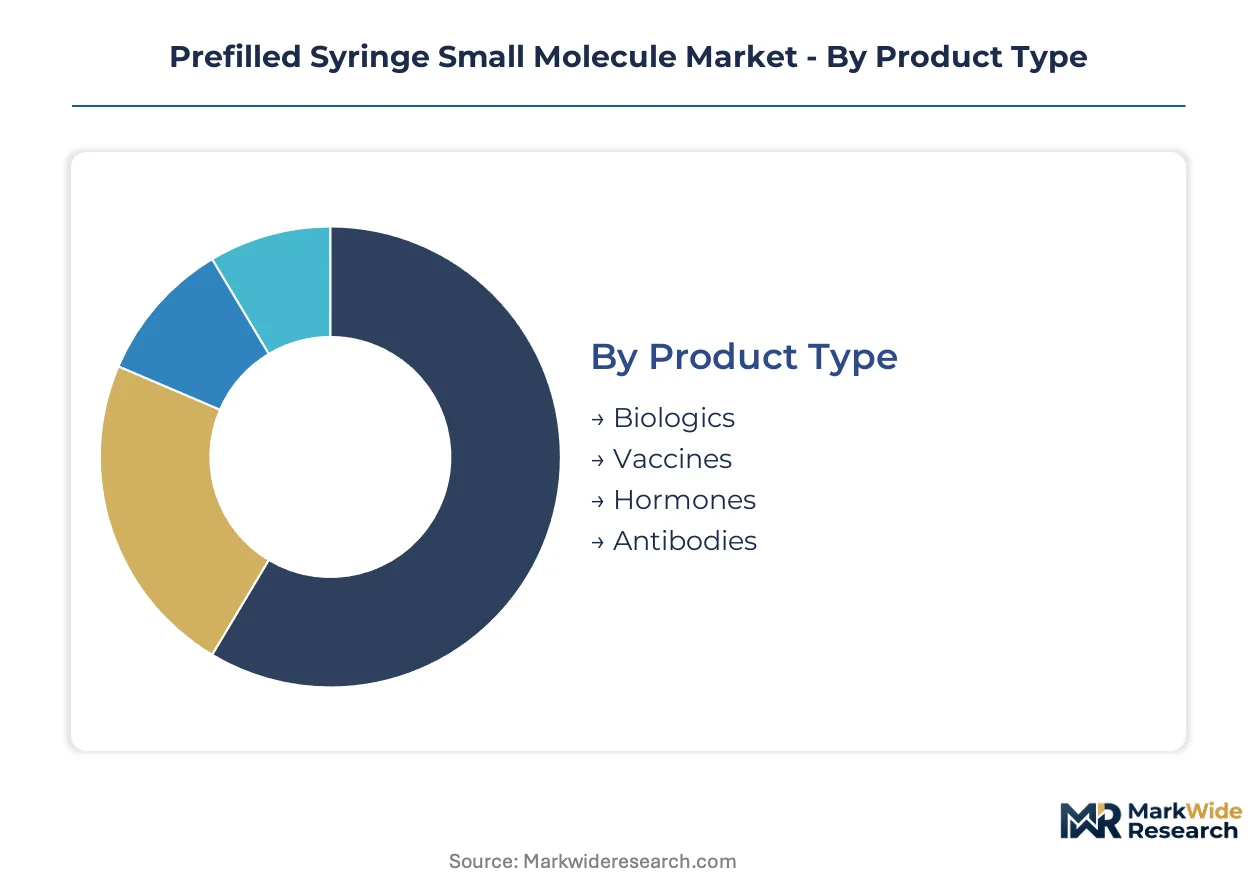
Segmentation in prefilled syringe small molecules reveals how regulatory pathways, site-of-care economics, and material compatibility requirements fragment addressable opportunities. Each dimension carries distinct compliance burdens and margin structures that reshape supplier selection criteria.
Product Type:
FDA combination product rules and ISO 11040-6 functional testing create divergent validation timelines across molecular categories, with biologics facing the most stringent extractables-leachables documentation.
- Biologics:Complex protein and peptide formulations requiring cold-chain stability and specialized barrier coatings. Demand concentrates in United States oncology centers where 340B program restructuring accelerates direct dispensing. EMA MDR migration in Europe is forcing consolidation around notified body-preferred vendors with integrated quality systems.
- Vaccines:Temperature-sensitive formulations with established adjuvant compatibility profiles. German statutory health insurance coverage for ambulatory immunization is expanding prefilled format procurement beyond traditional institutional procurement cycles.
- Hormones:Synthetic endocrine therapies with well-characterized elastomer interactions.
- Antibodies:Monoclonal fragment formats requiring pH-stable container systems.
Established volume favors biologics; emerging adoption favors vaccines.
Application:
Site-of-care migration and cytotoxic handling requirements are redistributing margin pools across therapeutic areas, with self-administration eligibility becoming the critical segmentation variable.
- Diabetes Management:Concentrated insulin glargine and rapid-acting analogs migrating from clinical supervision to homecare settings. Japan METI initiatives supporting patient-administered therapies are opening premium-priced segments previously confined to institutional reimbursement.
- Oncology Treatments:Cytotoxic small molecules with stringent containment and disposal protocols. United States cancer care settings are fragmenting procurement through specialty pharmacy networks negotiating standalone agreements outside group purchasing organizations.
- Pain Management:Opioid and non-opioid injectables with established abuse-deterrent requirements.
- Immunotherapy:Immune modulators with emerging container compatibility profiles.
Margin concentration sits with oncology; volume expansion is climbing the fastest in diabetes management.
Delivery Mode:
Injection depth and absorption kinetics determine container specification requirements, with subcutaneous formats driving the steepest material science innovation cycles.
- Subcutaneous:Shallow tissue delivery enabling self-administration with reduced needle gauge requirements. Cyclic olefin polymer barrels are penetrating moisture-sensitive categories previously excluded from polymer acceptance, compressing quality-related rejection costs during cold chain distribution.
- Intravenous:Direct vascular access requiring luer-lock compatibility and flush protocols. Hospital purchasing cooperatives are unbundling traditional distribution contracts to secure direct manufacturer relationships for high-volume institutional formats.
- Intramuscular:Deep tissue deposition with established needle length standards.
- Intra-articular:Joint space delivery with viscosity-matched plunger force specifications.
Technology investment clusters around subcutaneous; institutional procurement retains intravenous.
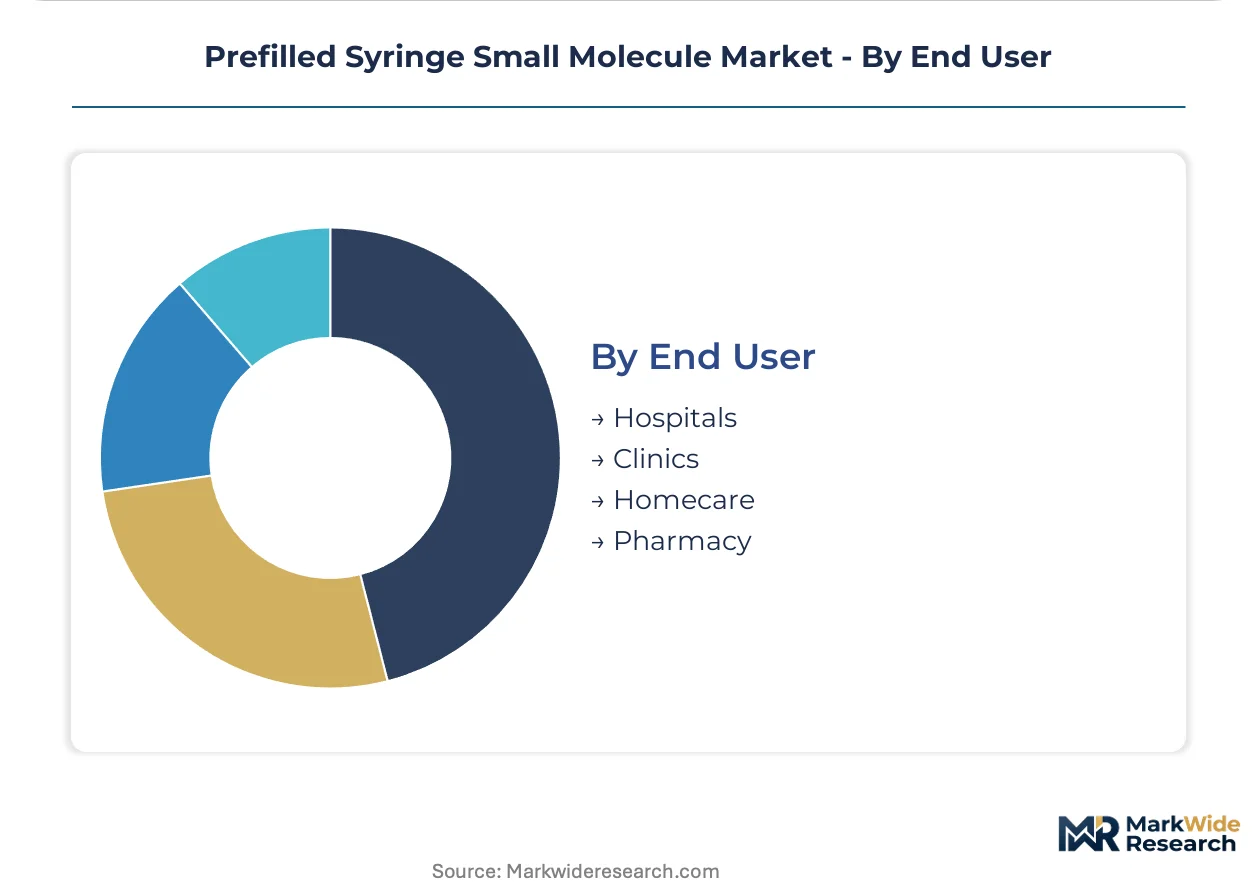
End User:
Reimbursement framework divergence between institutional and ambulatory settings is fragmenting demand patterns and reshaping distribution topology.
- Homecare:Patient-administered therapies requiring simplified handling instructions and disposal systems. PMDA sterile product guidelines in Japan and German ambulatory coverage expansions are raising barrier-to-entry thresholds for non-integrated manufacturers serving this channel.
- Hospitals:Acute care settings with established compounding pharmacy infrastructure and bulk procurement leverage. Legacy fill-finish equipment retrofit demands for isolator technology and automated inspection systems are compressing margins for traditional suppliers.
- Clinics:Outpatient facilities with intermediate volume requirements and mixed administration protocols.
- Pharmacy:Retail dispensing channels with direct-to-patient logistics and counseling obligations.
Procurement authority is shifting from hospitals to homecare; infrastructure investment lags in pharmacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export pharmaceutical-grade glass barrels to United States fill-finish facilities, anchoring transatlantic supply chains for ready-to-administer injectables. Japan and Switzerland serve as secondary precision-molding sources for polymer alternatives.
United States
Site-of-care migration and 340B program restructuring drive demand for outpatient oncology formats. FDA combination product rules tighten extractables-leachables documentation requirements. New Jersey and Massachusetts clusters concentrate sterile injectable fill-finish capacity for domestic distribution.
Germany
Statutory health insurance coverage for ambulatory parenteral therapies expands prefilled format procurement beyond hospitals. EMA MDR migration elevates technical documentation for syringe-drug combinations. Bavarian glassworks supply pharmaceutical-grade borosilicate barrels to European and Asian drug manufacturers.
Japan
METI and PMDA initiatives support patient-administered oncology therapies in homecare settings. Revised sterile product guidelines raise barrier-to-entry thresholds for non-integrated manufacturers. Kanto region hosts integrated delivery system production serving domestic chronic disease markets.
Switzerland
Swissmedic oversight of combination products attracts precision polymer molding investments for moisture-sensitive formulations. Basel and Zurich clusters concentrate specialty pharmaceutical packaging expertise serving global biopharma clients.
India
CDSCO regulatory alignment with ISO standards enables contract manufacturing expansion for export markets. Maharashtra and Gujarat house emerging fill-finish facilities targeting United States and European generic injectable demand.
Prefilled Syringe Small Molecule Market Competitive Landscape
Player mix skews toward integrated pharmaceutical-device combinations and specialized component suppliers. Tiered concentration separates large-cap drug manufacturers with captive syringe programs from independent delivery system fabricators. Dominant archetypes include sterile injectable portfolio owners, precision glass and polymer barrel specialists, and integrated needle-syringe platform manufacturers. Competitive moves cluster around M&A for fill-finish capacity and strategic partnerships for polymer substitution technology.
Among integrated pharmaceutical operators, Pfizer Inc. and Sanofi occupy positions exemplifying sterile injectable portfolio scale, while Becton Dickinson anchors the delivery system manufacturing tier with integrated platform capabilities. These named entities represent the structural division between drug sponsors controlling formulation-container pairings and component specialists supplying validated subsystems to multiple pharmaceutical clients.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi |
| Viatris |
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca |
| Becton Dickinson |
| Gerresheimer |
| SCHOTT AG |
| West Pharmaceutical Services |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for pharmaceutical-grade borosilicate glass barrels concentrate pricing power among German and Asian suppliers, while downstream fill-finish operators absorb cost volatility through long-term offtake commitments. This inventory compression tightens margins for non-integrated drug manufacturers while rewarding backward-integrated players with captive barrel supply.
Pricing Analysis
Glass-to-polymer technology-generation pricing gaps separate premium cyclic olefin polymer barrels from standard borosilicate formats and economy-grade soda-lime alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 11040-6 certification status, with FDA-validated combination products commanding substantial premia over generic injectable formats. Pricing pressure stems from concentrated insulin glargine volume procurement by United States specialty pharmacy networks. Hospital purchasing cooperatives exhibit highest price sensitivity; oncology biopharmas with cytotoxic handling requirements demonstrate lowest.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery of German-manufactured glass barrels to United States East Coast fill-finish facilities. Supply concentrates in Germany, Japan, and Switzerland for precision-molded components, with India emerging as contract manufacturing destination for generic injectable demand. Raw material dependencies include pharmaceutical-grade borosilicate glass, halobutyl elastomer formulations, and cyclic olefin polymer resin. Single-source vulnerability sits with European energy-intensive glassworks exposed to natural gas price volatility. Distribution runs through integrated pharmaceutical-device manufacturers and independent component suppliers serving multiple drug sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prefilled syringe small molecules sit in early-cycle expansion as site-of-care migration accelerates patient-administered therapy penetration beyond institutional capacity constraints.
For Market Incumbents: Shield market position by deepening backward integration into pharmaceutical-grade glass barrel production and accelerating ISO 11040-6 validation investments ahead of EMA MDR enforcement. Cyclic olefin polymer substitution threats from Swiss and Japanese precision molders demand preemptive capacity lockups with notified body-preferred vendors. For New Entrants and Emerging Players: Homecare reimbursement navigation services represent an underserved layer where incumbents under-serve chronic disease patients facing PMDA sterile product documentation burdens. Target Japan's patient-administered oncology segment through partnership with METI-authorized homecare nursing networks. Go-to-market leverage rests on direct-to-patient dispensing channel development bypassing traditional GPO contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents spinning non-core delivery system manufacturing units lacking combination product regulatory expertise. Long-term viability favors integrated platform owners with validated needle-syringe systems spanning multiple therapeutic franchises. Watch FDA extractables-leachables guidance revisions as inflection signal for multi-product portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11040-6 Validation Investment | Eliminates marginal suppliers and consolidates demand around integrated quality systems. |
| Cyclic Olefin Polymer Substitution | Enables moisture-sensitive small molecules to migrate from glass to polymer acceptance. |
| Homecare Reimbursement Strategy | Captures German statutory health insurance and Japan METI premium-priced segments. |
| Backward Integration into Glass Supply | Insulates against European energy cost shocks and export restriction vulnerability. |
| Specialty Pharmacy Network Partnership | Bypasses GPO consolidation and secures direct dispensing in United States oncology. |
Research Methodology
Initial hypotheses were tested against primary input from sterile injectable portfolio directors, regulatory affairs leads, hospital procurement managers, and GPO contracts specialists and refined through secondary validation against FDA combination product filings, EMA MDR technical documentation, ISO 11040 series standards, and hospital procurement database extracts. Bottom-up patient-volume modeling triangulated against top-down manufacturer capacity disclosures.
Variance decomposition across product type, delivery mode, therapeutic application, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and pricing band migration patterns. Forecast inputs included site-of-care shift velocity, reimbursement framework expansion timelines, and material substitution adoption curves for polymer barrel formats.
Forecasts assume regulatory continuity in FDA combination product rules, EMA MDR migration, and Japan PMDA sterile product guidelines; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as extractables-leachables testing requirements and energy-intensive glass supply stability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wireless Neurostimulator Market
Medical Devices
Patient Lift Slings Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Heat Therapy Units Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Facial Pumps Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Global Catheter Stabilization Devices Market