
 Intradermal Injections Market | 2026-2036
Intradermal Injections Market Size, Share, and Industry Trends Forecast 2026-2036
Intradermal Injections Market Analytics
Specialized nursing expertise in intradermal administration is bifurcating, with trained clinical staff concentrated in academic medical centers while community settings face persistent capability gaps. Becton Dickinson leverages its integrated manufacturing footprint across multiple geographies to sustain consistent supply of precision syringes. West Pharmaceutical Services differentiates through advanced containment and delivery technologies that anchor its position in biologic-compatible formats.
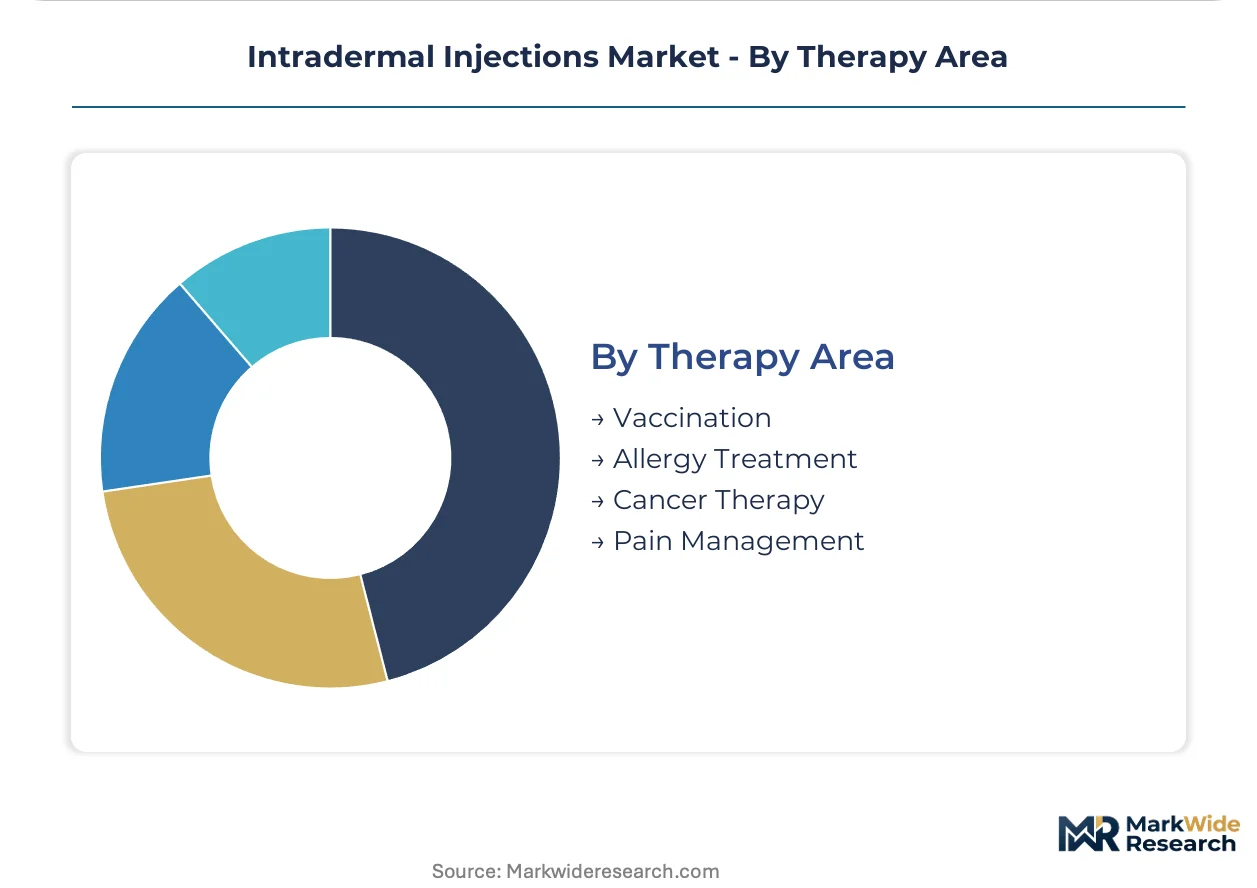
Intradermal injections deliver substances into the dermis layer at depths of 1.0 to 2.0 millimeters, utilizing 26-to-30 gauge needles or microneedle arrays for precise antigen presentation and enhanced immune response. The technique serves primary commercial purposes in vaccination protocols, allergy desensitization, and localized cancer immunotherapy where dermal dendritic cell activation proves clinically advantageous. Microneedles occupy the fastest-expanding product category as painless self-administration formats reshape homecare and clinic workflows. Vaccination retains the largest therapy area volume, though cancer therapy applications demonstrate the steepest growth trajectory in research laboratory and hospital settings.
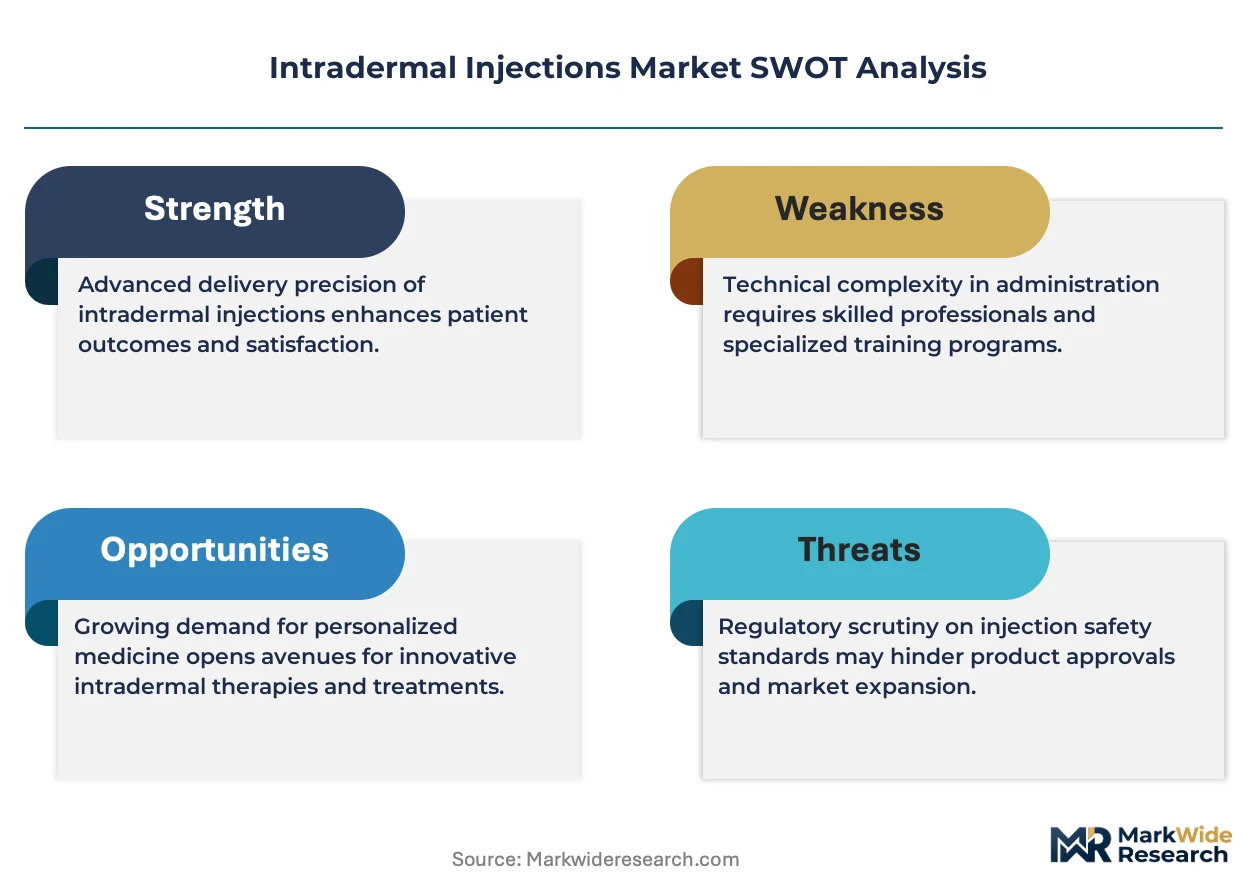
FDA biologics guidance, EMA medical device regulation under MDR, and WHO prequalification standards collectively govern device approval, clinical validation requirements, and cross-border procurement eligibility. These frameworks elevate barriers for novel delivery technologies while accelerating substitution of conventional syringes in regulated markets. Stakeholders must monitor evolving pharmacovigilance expectations for needle-free platforms and prefillable combination products as reimbursement pathways crystallize.
Market Dynamics
Microneedle array technology is compressing the boundary between professional administration and patient self-care, forcing device manufacturers to recalibrate clinical validation requirements against home-use safety profiles.
Growth Catalysts
- MDR harmonization:EMA medical device regulation under MDR creates streamlined prequalification pathways for combination products, reducing redundant clinical trials across EU member states.
- Allergy desensitization protocols:Expanded indication coverage for intradermal immunotherapy is pulling precision delivery systems into outpatient ENT and pulmonology practices.
- Japan's specialized training infrastructure:METI-funded certification programs for microneedle administration are expanding the addressable clinician pool faster than general injection training.
Market Restraints
- Silicon wafer supply concentration:Solid-state microneedle fabrication depends on semiconductor-grade substrate suppliers concentrated in Taiwan and South Korea.
- FDA biologics guidance friction:Updated qualification pathways for needle-free platforms impose extended stability testing timelines that delay commercialization.
- Glass prefillable syringe input costs:Borosilicate tubing price volatility directly compresses margins for conventional intradermal delivery formats.
Strategic Opportunities
- Pediatric vaccination in India:CDSCO accelerated approval pathways for painless delivery formats address caregiver compliance barriers in immunization programs.
- Localized cancer immunotherapy:Intradermal checkpoint inhibitor delivery is opening addressable white space in melanoma and non-melanoma skin cancer protocols.
- Retail pharmacy channel expansion:CVS Health and Walgreens pilot programs for supervised self-administration are creating new point-of-care revenue streams.
Industry Challenges
- Microneedle array sterility assurance:Terminal sterilization of polymeric or dissolvable arrays without compromising structural integrity requires validated aseptic processing infrastructure that few contract manufacturers possess.
- Cross-functional training deficits:Clinical staff must simultaneously master dermal anatomy navigation, device troubleshooting, and adverse event documentation, creating capability bottlenecks in community health settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intradermal Injections Market |
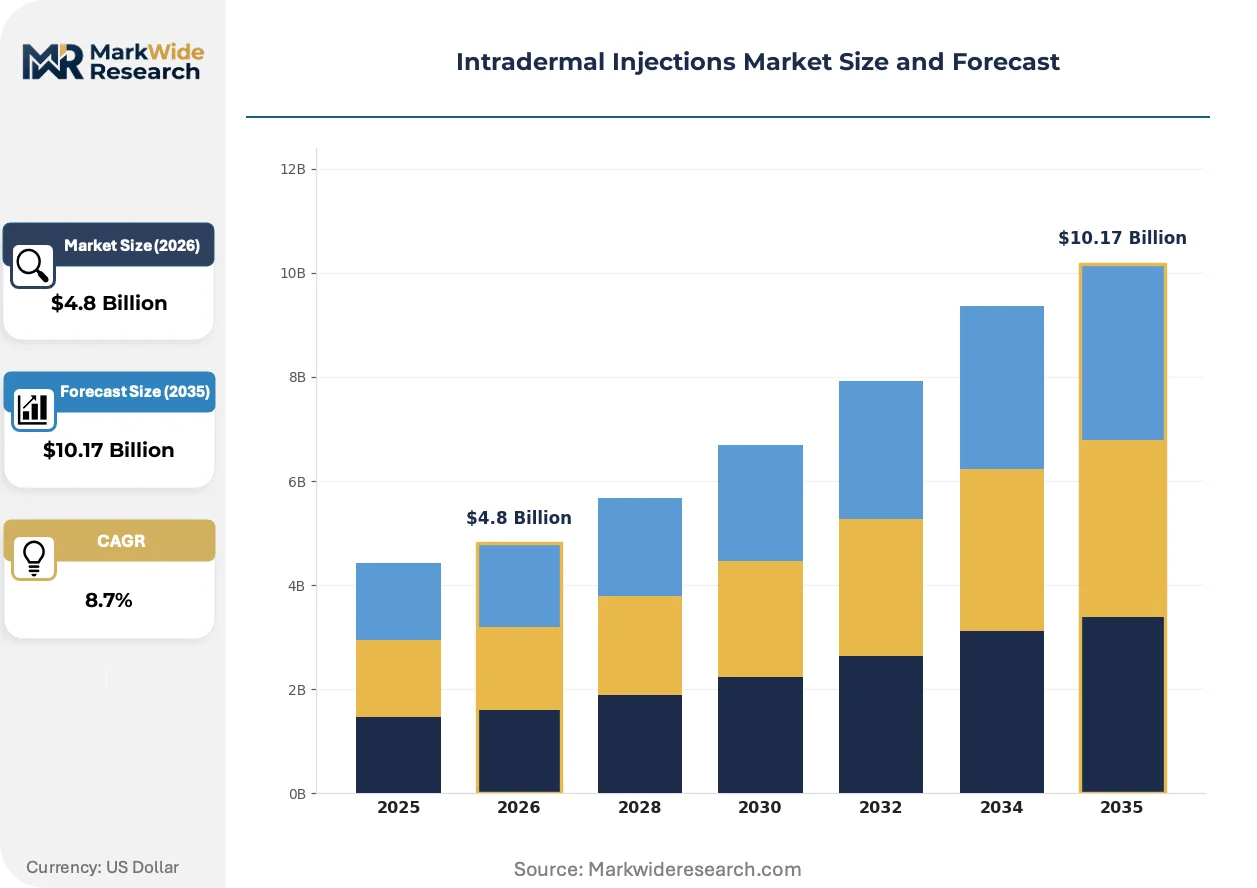
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle-less Injectors, Microneedles, Conventional Syringes, Auto-Injectors Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Topical End User: Hospitals, Clinics, Homecare Settings, Research Laboratories Therapy Area: Vaccination, Allergy Treatment, Cancer Therapy, Pain Management |
| Companies Covered | Becton Dickinson, Cardinal Health, West Pharmaceutical Services, Terumo Corporation, Nanopass, PharmaJet, Idevax, Crossject, Hindustan Syringes and Medical Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intradermal Injections Market Evolving Landscape
Device architecture is converging toward disposable, single-use formats that eliminate reprocessing validation burdens while integrating passive safety mechanisms mandated across major regulatory jurisdictions.
Hollow metallic microneedles are miniaturizing to sub-millimeter lengths that penetrate only the papillary dermis, enabling consistent antigen deposition without vascular engagement. Dermatology clinics in Germany and academic medical centers in the United States are adopting these formats for tuberculosis screening and yellow fever vaccination at replacement rates exceeding conventional 27-gauge needles. The structural consequence is compressing the addressable market for traditional Mantoux technique training and reusable injection equipment.
EMA's updated guidance on clinical evidence requirements for drug-device combination products is elevating bench-to-bedside validation standards for microneedle platforms. Manufacturers must now demonstrate human factors usability across age-diverse populations before CE marking, extending development timelines by twelve to eighteen months. Oncology applications face the steepest compliance burden due to cytotoxic payload handling requirements.
Institutional procurement is consolidating vendor relationships around full-service delivery system providers capable of integrating device, primary packaging, and secondary containment. Hospital systems in Japan and integrated delivery networks in the United States are disintermediating standalone syringe suppliers in favor of prequalified combination product platforms. This behavioral shift is most visible in cancer therapy settings where cold chain integrity and dose traceability requirements dominate supplier selection criteria.
Intradermal Injections Market Segmentation
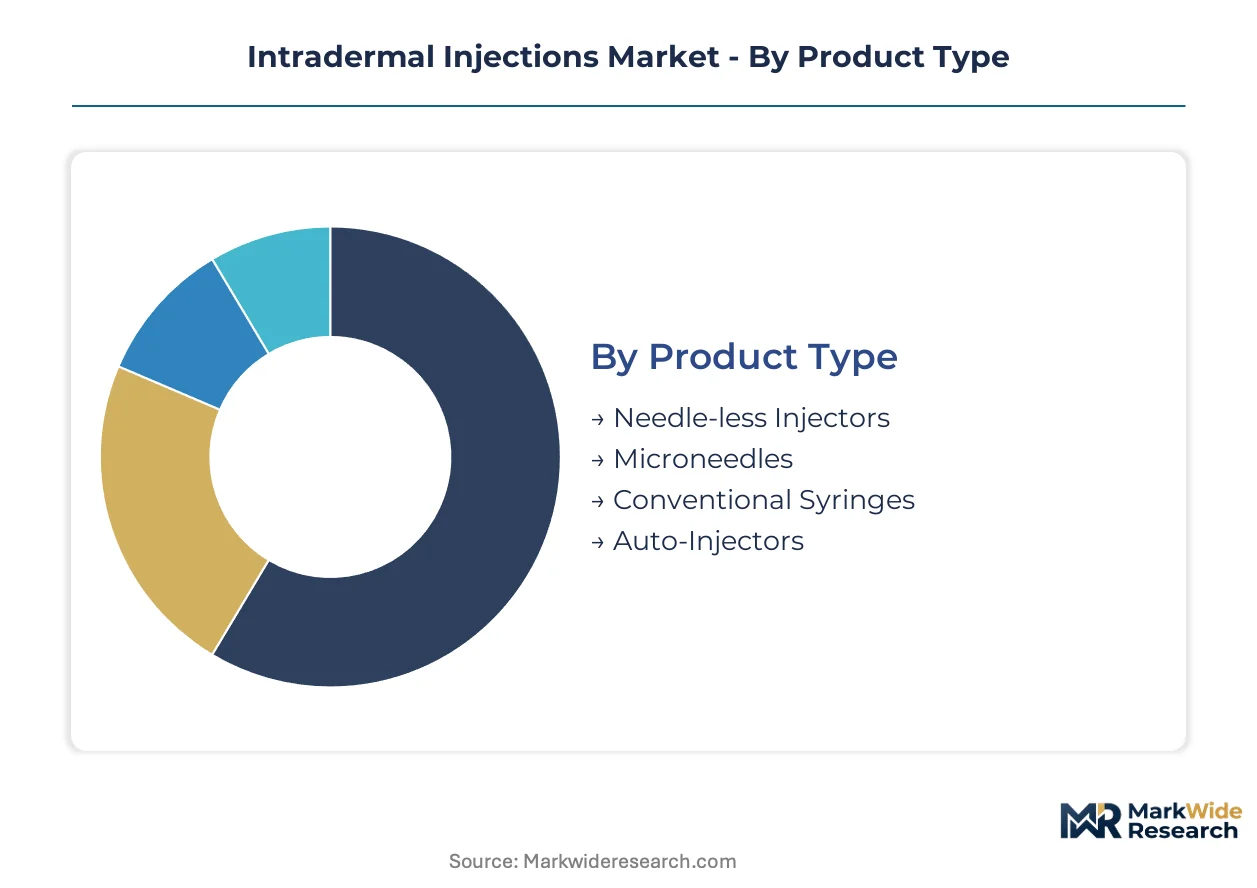
Intradermal injection formats fragment sharply across administration settings and payload requirements. Product architecture, delivery mechanics, and end-user capability constraints create distinct competitive arenas with diverging regulatory and reimbursement pathways.
Product Type:
Domestic production clusters in Germany and Japan supply precision metallic microneedles for regional hospital networks, while needle-free platforms depend heavily on US-based device engineering and Taiwanese semiconductor-grade substrate inputs for solid-state array fabrication.
- Microneedles:Arrays of hollow or solid projections measuring 150-1500 micrometers penetrate the stratum corneum without reaching nerve endings. Demand concentrates in Japanese dermatology clinics and German academic medical centers where METI-funded certification programs and MDR harmonization accelerate clinical adoption. Pain-free administration drives substitution of conventional Mantoux technique in tuberculosis screening protocols.
- Needle-less Injectors:Gas-propelled or spring-driven systems generate high-velocity liquid jets that breach the dermis without mechanical penetration. US outpatient ENT practices deploy these formats for allergy desensitization where patient compliance barriers justify premium device costs.
- Conventional Syringes:26-to-30 gauge needles with angled bevel designs remain the workhorse for vaccination programs in resource-constrained settings where cold chain infrastructure and device cost sensitivity dominate procurement criteria.
- Auto-Injectors:Spring-loaded, prefillable devices with integrated needle shields address homecare safety requirements. FDA biologics guidance friction extends stability testing timelines for these combination products.
Conventional syringes command the established base. The steepest expansion runs through microneedle platforms.
Delivery Mode:
Cost tier stratification separates premium precision systems from commodity administration formats, with reimbursement codes in the United States and Japan creating distinct pricing bands for professional versus self-administered delivery.
- Intravenous:Direct vascular access enables rapid systemic distribution of high-volume biologics. Cancer therapy applications in US hospital infusion centers leverage this mode for checkpoint inhibitor protocols where dose intensity governs efficacy.
- Subcutaneous:Adipose tissue deposition supports sustained-release formulations and patient self-administration. Homecare demand in Germany and Japan favors this mode for chronic immunotherapy regimens.
- Intramuscular:Deep tissue deposition triggers robust immune responses for adjuvanted vaccines. Mass immunization programs retain this cost-optimized approach despite patient discomfort.
- Topical:Surface application without penetration serves placebo controls and dermatological conditioning. Research laboratories utilize this mode for comparative efficacy studies in allergy desensitization protocols.
Intramuscular delivery retains volume leadership. Subcutaneous administration gains share fastest in reimbursed homecare settings.
End User:
Customer capability maturity creates segmentation boundaries, with specialized training infrastructure concentrating in academic medical centers while community settings face persistent administration skill gaps.
- Hospitals:Integrated delivery networks in the United States and Japan consolidate procurement around full-service combination product platforms with cold chain integrity and dose traceability. Oncology units drive demand for cytotoxic-compatible containment systems.
- Clinics:Dermatology and ENT outpatient facilities in Germany adopt hollow metallic microneedles for tuberculosis screening and yellow fever vaccination at replacement rates exceeding conventional needles.
- Homecare Settings:Supervised self-administration pilots at CVS Health and Walgreens create new point-of-care revenue streams. Patient handling of dissolvable microneedle arrays requires validated aseptic processing that few contract manufacturers possess.
- Research Laboratories:Phase I immunogenicity studies and device validation protocols consume precision delivery systems. EMA clinical evidence requirements extend development timelines for novel platforms.
Hospitals anchor procurement volume. Homecare settings climb the fastest as microneedle technology compresses the boundary between professional and patient-controlled administration.
Therapy Area:
Application-specific payload requirements dictate device selection, with cytotoxic handling constraints in oncology creating the steepest compliance burden and sterile assurance demands.
- Vaccination:Dermal dendritic cell activation enhances immune response for tuberculosis, yellow fever, and emerging infectious disease prophylaxis. CDSCO accelerated approval pathways in India address caregiver compliance barriers through painless delivery formats.
- Cancer Therapy:Intradermal checkpoint inhibitor delivery opens addressable white space in melanoma protocols. US academic medical centers pilot localized immunotherapy to reduce systemic toxicity.
- Allergy Treatment:Extended desensitization protocols pull precision delivery systems into outpatient ENT and pulmonology practices. German clinics lead European adoption of metered intradermal allergen deposition.
- Pain Management:Local anesthetic delivery for dermal procedures and chronic neuropathic conditions utilizes conventional syringe formats where cost minimization dominates procurement.
Vaccination retains the volume base. Cancer therapy applications demonstrate the steepest growth trajectory in research laboratory and hospital settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. Japanese clinics prioritize microneedle-based painless administration for tuberculosis screening, while Indian immunization programs emphasize cost-minimized conventional formats. German dermatology centers occupy a middle ground, adopting precision metallic arrays for both vaccination and allergy protocols.
United States
FDA biologics guidance is reshaping device qualification timelines for needle-free platforms, extending stability testing requirements. Academic medical centers in Boston and the Research Triangle pilot intradermal checkpoint inhibitor delivery for melanoma protocols. CVS Health and Walgreens pilot programs for supervised self-administration create new point-of-care revenue streams in retail pharmacy channels.
Germany
EMA medical device regulation under MDR harmonizes prequalification pathways for combination products across EU member states. Dermatology clinics in Munich and Heidelberg adopt hollow metallic microneedles for yellow fever vaccination at replacement rates exceeding conventional needles. Baden-Württemberg's precision engineering clusters supply semiconductor-grade substrates for solid-state array fabrication.
Japan
METI-funded certification programs for microneedle administration expand the addressable clinician pool faster than general injection training. PMDA guidance on drug-device combination products elevates human factors usability requirements before market authorization. Kanto region hospitals consolidate procurement around full-service delivery platforms with integrated cold chain integrity systems.
India
CDSCO accelerated approval pathways for painless delivery formats address caregiver compliance barriers in national immunization programs. Domestic production clusters in Gujarat and Maharashtra manufacture conventional syringes for resource-constrained settings. Government procurement preferences for indigenous medical devices strengthen local manufacturing ecosystems against import dependency.
South Korea
MFDS regulatory frameworks align with international standards for microneedle sterility assurance and aseptic processing validation. Seoul-based device engineering firms leverage proximity to Taiwanese semiconductor substrate suppliers for solid-state array development. Bioclusters in Songdo and Osong attract contract manufacturing investment for polymeric microneedle platforms targeting export markets.
Intradermal Injections Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated procurement power in hospital systems favoring full-service providers over standalone component suppliers. The competitive terrain splits between precision device manufacturers with captive substrate supply and contract manufacturers competing on sterilization validation capabilities. Strategic archetypes include integrated delivery system providers, semiconductor-grade substrate specialists, and regional syringe fabricators. Dominant competitive moves center on backward integration into borosilicate tubing supply and technology licensing partnerships for dissolvable array formats.
Among US-based integrated leaders, Becton Dickinson and West Pharmaceutical Services exemplify the full-service archetype, anchoring positions through combination product platforms that merge device engineering with primary packaging expertise. Japanese precision manufacturers Terumo Corporation and specialized microneedle developers Nanopass occupy distinct competitive spaces, with the former representing scale-driven hospital supply relationships and the latter exemplifying technology-forward formats for painless administration. Needle-free platform developers PharmaJet and Idevax sit within the innovation-tier, their market presence contingent on navigating extended FDA qualification timelines.
| Leading Market Players |
|---|
| Becton Dickinson |
| Cardinal Health |
| West Pharmaceutical Services |
| Terumo Corporation |
| Nanopass |
| PharmaJet |
| Idevax |
| Crossject |
| Hindustan Syringes and Medical Devices |
| Others |
Value Network & Pricing Analysis
Polymeric microneedle arrays displacing hollow metallic formats are redrawing procurement geography toward Taiwanese semiconductor substrate suppliers while compressing price premiums for precision injection devices. This substitution dynamic simultaneously elevates input cost volatility for solid-state fabrication and erodes margin buffers for conventional syringe manufacturers dependent on borosilicate glass supply.
Pricing Analysis
Long-term offtake contracts dominate hospital system procurement in the United States and Japan, locking in volume commitments for combination product platforms with integrated cold chain integrity. Price differentiation rests on FDA biologics qualification tier and METI certification status, with qualified platforms commanding substantial premiums over unvalidated alternatives. Pricing pressure stems from CDSCO accelerated approval pathways in India driving cost-minimized conventional syringe volumes. Government procurement programs exhibit highest price sensitivity, while academic medical centers prioritize qualification status over unit cost.
Supply Chain Analysis
Strategic stockpiling of semiconductor-grade silicon wafers characterizes device manufacturer inventory posture given Taiwan and South Korea supply concentration. Raw material dependencies center on borosilicate tubing from Germany, polymeric substrates from Japanese precision chemical suppliers, and spring mechanisms from Swiss component specialists. Single-source vulnerability in Taiwanese wafer fabrication creates exposure to geopolitical disruption. Distribution runs through consolidated GPO contracts in US hospital systems and direct procurement relationships in German clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device architecture fragmentation creates specialized niche opportunities as microneedle technology splinters addressable demand across painless self-administration, clinical precision formats, and conventional vaccination workhorses.
For Market Incumbents: Secure captive supply of semiconductor-grade substrates through backward integration or exclusive offtake arrangements with Taiwanese wafer suppliers. Lock in hospital system GPO contracts with bundled cold chain and traceability services before emerging platform developers achieve FDA biologics qualification. Threat substitution from needle-free jet injectors demands preemptive certification investment in combination product pathways. For New Entrants and Emerging Players: Differentiate on pediatric painless administration protocols where caregiver compliance barriers justify premium positioning and regulatory pathways remain less congested than oncology applications. White space concentrates in Indian immunization program tenders and German ENT clinic networks seeking metered allergen deposition systems. Go-to-market leverage rests on CDSCO accelerated approval navigation and METI certification partnership. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers possessing validated aseptic processing infrastructure for polymeric microneedle arrays. Five-to-ten year viability hinges on successful navigation of EMA MDR harmonization and FDA biologics guidance friction for combination products. Acquisition target archetype: sterilization-validated manufacturers with installed aseptic capacity and existing pharmaceutical customer relationships. Signal to watch: first commercial-scale dissolvable microneedle platform achieving WHO prequalification status.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Biologics Qualification Pathway | Accelerated stability testing protocols reduce needle-free platform commercialization timelines for US hospital adoption. |
| CE Marking Pathway under MDR | Harmonized prequalification across EU member states streamlines combination product market access for German manufacturers. |
| Hospital System Partnership | Integrated delivery network consolidation favors full-service providers with cold chain and dose traceability capabilities. |
| Backward Integration into Substrate Supply | Captive semiconductor-grade wafer sourcing mitigates Taiwan supply concentration risk for solid-state microneedle fabrication. |
| Reimbursement Strategy | Distinct coding for professional versus self-administered delivery creates pricing band separation in Japanese and US markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with device engineering executives, regulatory affairs specialists, hospital GPO contract managers, and dermatology clinic procurement leads; and secondary validation against FDA 510(k) filings, EMA MDR submission databases, CDSCO approval registries, and METI certification records. Bottom-up demand modeling triangulated against top-down market sizing across product type, delivery mode, end user, and therapy area segmentation dimensions.
Across the analysis window, forecasts applied a segmented growth framework incorporating administration setting migration from clinical to homecare, regulatory pathway evolution under FDA biologics guidance and EMA MDR harmonization, and therapy area expansion from vaccination into localized cancer immunotherapy. CAGRs derived from regression analysis of historical adoption curves adjusted for qualification timeline delays and procurement consolidation patterns. Industry-specific inputs included microneedle array sterility assurance validation rates and semiconductor substrate supply elasticity.
The analysis sits within stated boundaries; outcomes outside continued regulatory pathway convergence or sustained Taiwanese wafer supply stability would require recalibration. Forecasts reflect documented assumptions regarding METI certification program expansion rates and CDSCO accelerated approval pathway integrity. Revision becomes warranted when FDA biologics guidance friction crosses thresholds that materially extend combination product commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Infant Incubator Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
North America Ablation Devices Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Allografts Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Vaginal Specula Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Trial Prostheses Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Global Colposcopy Devices Market