
 South America Ultrasound Devices Market | 2026-2036
South America Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South America Ultrasound Devices Market Analytics
Software-based beamforming is narrowing the performance gap between premium cart-based systems and mid-tier portable units across South American healthcare networks. GE HealthCare leverages its established service infrastructure to sustain long-term contracts with Brazil's public hospital federations. Koninklijke Philips NV anchors its regional position through localized manufacturing partnerships that reduce import duty exposure. Siemens Healthineers differentiates via AI-integrated cardiac imaging workflows that address cardiologist shortages in secondary cities.
Ultrasound devices generate acoustic images through piezoelectric transducer arrays operating at frequencies between 2 and 18 megahertz, with beamforming processors reconstructing real-time anatomical visualization for non-invasive diagnostic intervention. Diagnostic ultrasound systems occupy the dominant revenue position given their deployment across obstetrics and cardiology departments where procedure volumes remain structurally high. Portable ultrasound represents the fastest-expanding product category as Colombian and Peruvian clinics adopt handheld units for rural outreach programs where fixed imaging infrastructure proves economically unviable.
ANVISA, Brazil's national health surveillance agency, enforces electromagnetic compatibility and clinical safety standards that shape product registration timelines and technical documentation requirements for imported devices. Argentina's national administration of medications, foods and medical technology applies parallel conformity assessment protocols that extend market access complexity for manufacturers without localized regulatory affairs capacity. Stakeholders must monitor evolving Mercosur technical harmonization negotiations that could either consolidate or fragment device approval pathways across the customs union.
Market Dynamics
Software-based beamforming is collapsing the traditional price-performance hierarchy between cart-based and portable ultrasound systems across South American healthcare networks, forcing incumbent manufacturers to defend installed bases through service bundling rather than hardware differentiation.
Growth Catalysts
- Maternal health infrastructure mandates:Brazil's national health system reforms prioritize obstetric imaging procurement across public hospital federations, creating sustained demand for mid-tier diagnostic systems.
- Rural outreach program expansion:Colombian and Peruvian clinics deploy handheld ultrasound units for mobile diagnostic services where fixed imaging infrastructure remains economically unviable.
- AI-integrated cardiac workflows:Machine learning-powered image analysis addresses structural cardiologist shortages in Brazil's secondary cities, accelerating adoption of automated measurement tools.
Market Restraints
- Import duty exposure:Mercosur's fragmented customs protocols impose variable tariff burdens on imaging equipment, disadvantaging manufacturers without localized assembly partnerships.
- Electromagnetic compliance costs:ANVISA's technical documentation requirements extend product registration timelines, delaying market entry for new device categories.
- Disposable probe economics:Single-use transducer covers and sterilization consumables inflate per-procedure costs, limiting penetration in price-sensitive outpatient settings.
Strategic Opportunities
- Telemedicine integration:Cloud-connected portable units enable remote diagnostic consultation across Amazon basin communities, opening previously inaccessible patient populations.
- Point-of-care emergency deployment:Argentine trauma centers and Colombian pre-hospital services adopt handheld systems for rapid triage where radiology department access is constrained.
- Regulatory harmonization tailwinds:Ongoing Mercosur technical alignment negotiations could consolidate approval pathways, reducing compliance duplication across Brazil, Argentina, and Uruguay.
Industry Challenges
- Sonographer training pipelines:Brazil's accredited ultrasound technician programs graduate insufficient practitioners to match public hospital expansion targets, creating operational bottlenecks.
- Legacy system interoperability:DICOM connectivity standards vary across hospital information systems, complicating integration of new devices with existing PACS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Ultrasound Devices Market |
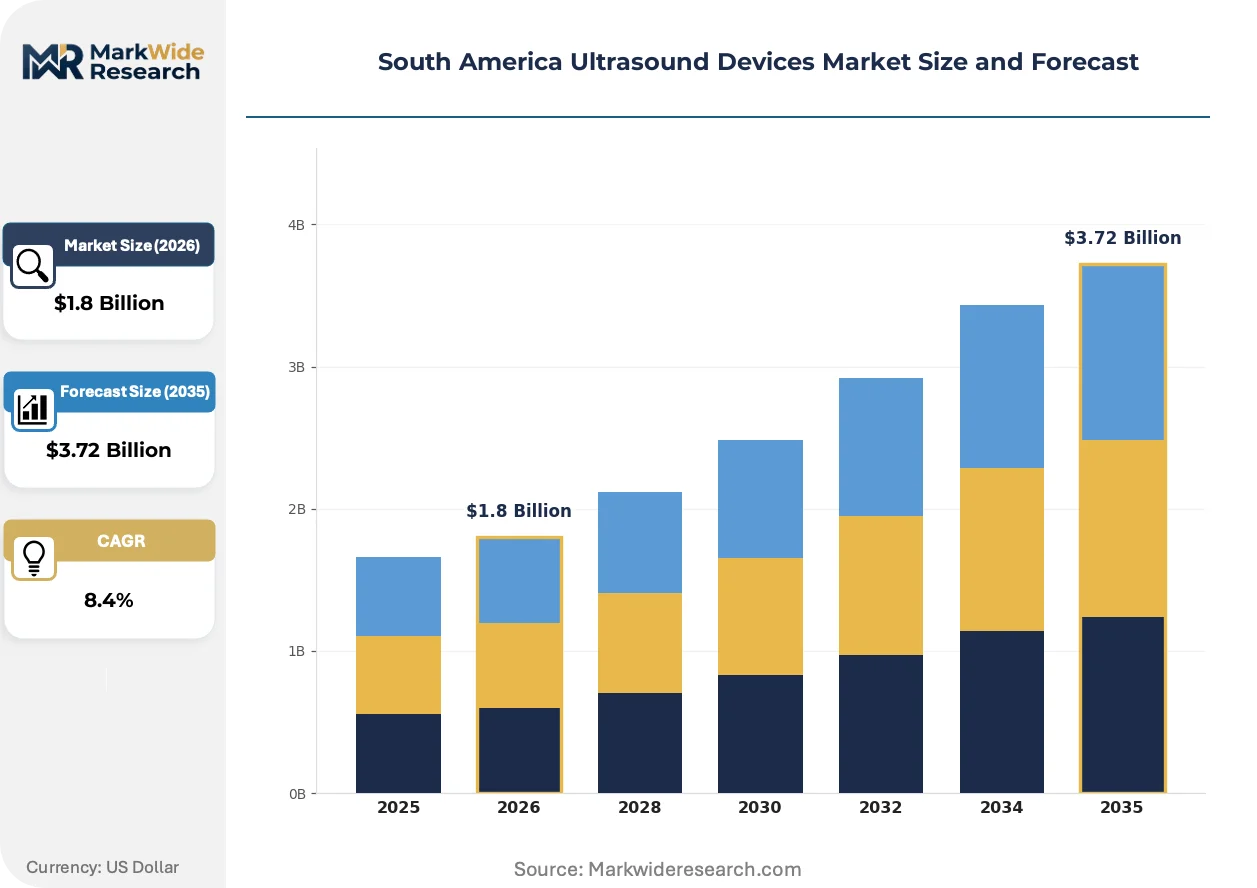
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, 3D Ultrasound, Portable Ultrasound End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: Analog Ultrasound, Digital Ultrasound, Software-based Ultrasound, Automated Ultrasound Application: Obstetrics, Cardiology, Abdominal Imaging, Musculoskeletal |
| Companies Covered | GE HealthCare, Koninklijke Philips NV, Siemens Healthineers, Mindray Medical International, Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Samsung Electronics, Esaote, Hitachi, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Ultrasound Devices Market Evolving Landscape
Capacitive micromachined ultrasound transducers are actively reconfiguring component supply chains, while artificial intelligence inference engines embedded at the edge of imaging systems are compressing diagnostic workflow timelines.
CMUT technology is collapsing the manufacturing cost structure for high-frequency transducer arrays, enabling single-chip integration that previously required discrete piezoelectric crystal assemblies. Colombian diagnostic center networks are adopting CMUT-based handheld units at twice the rate of traditional probe systems. The structural consequence is a compression of premium-tier pricing power as mid-range devices achieve comparable image resolution.
ANVISA's updated electromagnetic compatibility standards now mandate pre-market testing against IEC 60601-1-2 fourth edition protocols, extending technical documentation requirements for imported devices. Manufacturers without Brazilian regulatory affairs capacity face six-to-nine month registration delays. Portable system categories bear disproportionate compliance burden due to their wireless transmission architectures.
After-sales service unbundling is disrupting traditional equipment financing models across Brazilian public hospital federations. Third-party technical service providers now compete for maintenance contracts previously captured by original equipment manufacturers, compressing multi-year service margins. This shift is most visible in São Paulo's state hospital network, where procurement offices separately tender hardware and technical support agreements.
South America Ultrasound Devices Market Segmentation
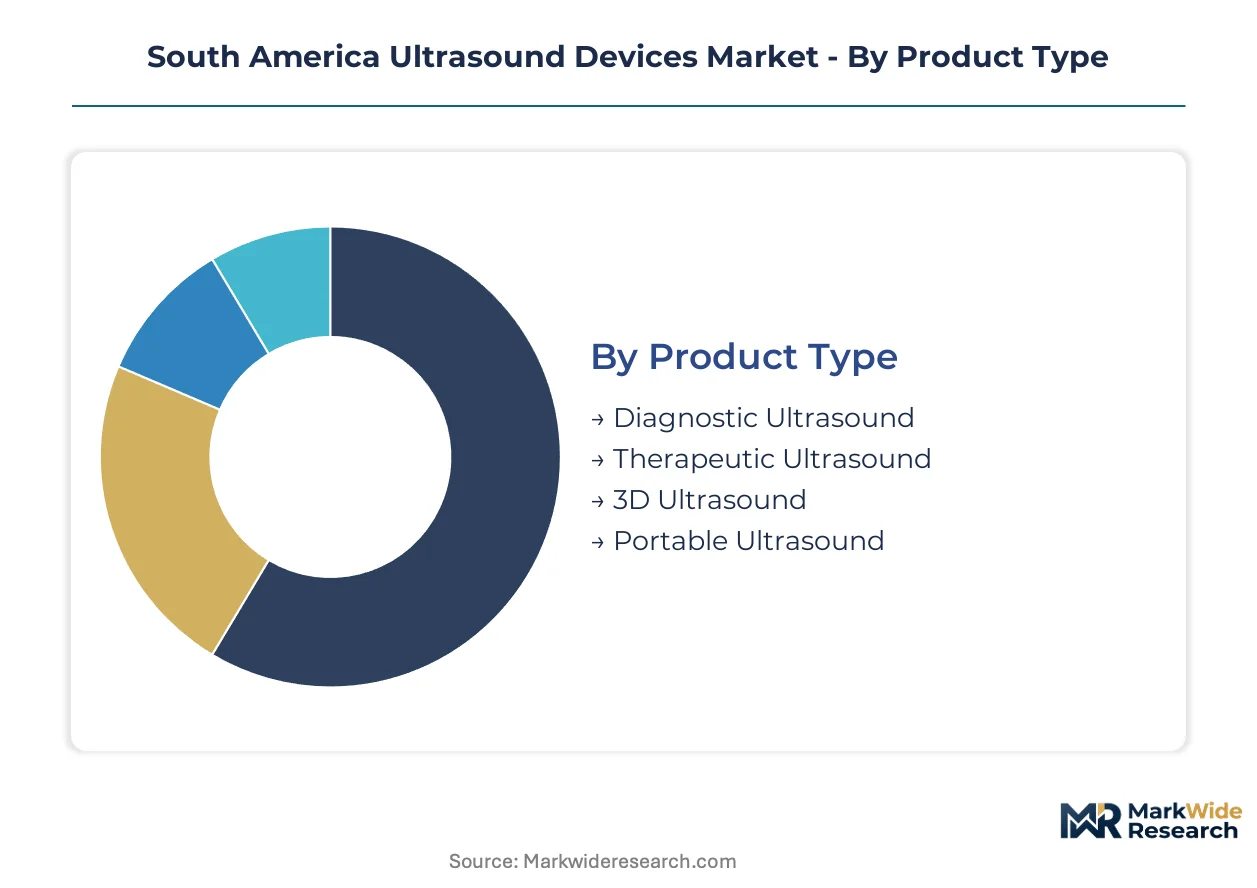
Segmentation in South America's ultrasound market reveals how procurement patterns split between centralized hospital systems and distributed point-of-care networks. Each dimension—product configuration, clinical setting, underlying technology, and anatomical focus—carries distinct margin profiles and regulatory pathways that shape manufacturer positioning strategies across Brazil, Colombia, and Argentina.
Product Type:
Clinical use-cases span from high-throughput departmental imaging to single-procedure handheld deployment, creating tiered hardware requirements across South American healthcare networks.
- Diagnostic Ultrasound:Cart-based systems with multi-frequency transducer arrays serve obstetrics and cardiology departments in Brazil's public hospital federations. Procurement concentrates in São Paulo and Minas Gerais state networks where maternal health infrastructure mandates sustain volume.
- Portable Ultrasound:Battery-powered handheld units with wireless DICOM transmission enable Colombian rural outreach programs and Argentine pre-hospital trauma services. These systems are expanding most quickly where fixed imaging infrastructure remains economically unviable.
- Therapeutic Ultrasound:Focused acoustic delivery systems target physiotherapy and rehabilitation clinics in urban Brazilian centers.
- 3D Ultrasound:Volume-rendering systems with specialized transducers serve high-complexity fetal medicine units in Buenos Aires and Santiago.
Established volume favors Diagnostic Ultrasound; emerging adoption favors Portable Ultrasound.
End User:
Customer economics range from centralized public procurement with multi-year service contracts to fragmented private purchases with minimal technical support.
- Hospitals:Brazil's SUS-affiliated institutions dominate equipment absorption, with ANVISA-registered devices required for electromagnetic compliance. Procurement offices in São Paulo state separately tender hardware and maintenance agreements, compressing OEM service margins.
- Diagnostic Centers:Colombian emerging networks adopt CMUT-based handheld units at accelerated rates, prioritizing rapid patient throughput over premium image resolution.
- Clinics:Peruvian outpatient facilities face disposable probe economics constraints that limit per-procedure profitability.
- Research Institutions:Academic medical centers in Argentina and Chile drive protocol development for AI-integrated imaging workflows.
Revenue concentration sits with Hospitals; margin expansion potential concentrates in Diagnostic Centers.
Technology:
Signal processing architectures determine price-performance positioning and regulatory documentation burden across import-dependent markets.
- Software-based Ultrasound:Beamforming algorithms executed on general-purpose processors narrow the gap between cart-based and portable hardware categories. Colombian clinics deploy these systems for cost-optimized rural networks.
- Digital Ultrasound:Fully digitized signal chains with FPGA-based processing dominate mid-tier installations in Brazilian secondary cities.
- Analog Ultrasound:Legacy discrete component systems persist in price-sensitive Argentine provincial hospitals.
- Automated Ultrasound:Machine learning inference engines embedded at the edge address structural cardiologist shortages through automated measurement tools.
Hardware differentiation favors Software-based Ultrasound; workflow compression favors Automated Ultrasound.
Application:
Anatomical focus areas align with epidemiological burden and specialist availability gaps across South American healthcare systems.
- Obstetrics:Fetal biometry and anomaly screening protocols drive sustained procurement under Brazil's national maternal health reforms. Procedure volumes remain structurally high across public hospital federations.
- Cardiology:Echocardiography workflows face practitioner shortages in secondary Brazilian cities, accelerating demand for AI-assisted image acquisition and measurement.
- Abdominal Imaging:Generalist applications in Colombian and Peruvian clinics support broad diagnostic screening programs.
- Musculoskeletal:Sports medicine and rheumatology applications concentrate in private Brazilian and Argentine urban centers.
Structural demand depth favors Obstetrics; automation opportunity favors Cardiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian manufacturers export ultrasound components to Colombian diagnostic networks through established Andean trade corridors. Argentine assembly operations supply handheld units to Chilean emergency services. Peruvian distributors channel portable systems into Amazon basin telemedicine programs.
Brazil
São Paulo state hospital networks drive cart-based system procurement under SUS maternal health mandates. ANVISA enforces IEC 60601-1-2 fourth edition electromagnetic compatibility testing, extending registration timelines for wireless-enabled portable categories. Minas Gerais diagnostic centers adopt CMUT-based handheld units for rural outreach expansion.
Colombia
Emerging diagnostic center networks concentrate demand for point-of-care systems in Bogotá and Medellín clusters. The national health regulator applies pre-market conformity assessment protocols that parallel Mercosur technical standards. Pacific coast clinics deploy battery-powered units for mobile services in Valle del Cauca agricultural zones.
Argentina
Buenos Aires fetal medicine units absorb premium 3D volume-rendering systems for high-complexity obstetric screening. The national administration of medications, foods and medical technology mandates parallel documentation requirements that complicate import pathways. Córdoba trauma centers integrate handheld ultrasound into pre-hospital emergency protocols.
Peru
Lima outpatient facilities face disposable probe economics constraints that limit per-procedure profitability in price-sensitive settings. The country's national health surveillance agency applies electromagnetic safety standards shaping product registration requirements. Amazon basin communities adopt cloud-connected portable units for remote diagnostic consultation via telemedicine integration.
Chile
Santiago academic medical centers drive protocol development for AI-integrated cardiac imaging workflows. The national pharmaceutical regulator enforces clinical safety documentation that extends market access timelines for automated measurement tools. Antofagasta mining corridor clinics deploy portable systems for occupational health screening in remote extraction sites.
South America Ultrasound Devices Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers defined by service infrastructure depth and regulatory affairs capacity. Premium cart-based manufacturers defend installed bases through multi-year maintenance bundling rather than hardware differentiation. Mid-tier portable specialists exploit software-based beamforming to narrow performance gaps. Emerging Asian fabricators compete on CMUT component cost structures. Dominant competitive moves include localized assembly partnerships that reduce import duty exposure and after-sales service unbundling that compresses OEM margin capture.
Within the premium-tier service infrastructure archetype, GE HealthCare leverages its established Brazilian technical support networks to sustain long-term public hospital contracts. Koninklijke Philips NV anchors regional positioning through manufacturing partnerships that minimize Mercosur tariff burdens. Siemens Healthineers exemplifies the AI-integrated workflow differentiation strategy addressing cardiologist shortages in secondary Brazilian cities.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips NV |
| Siemens Healthineers |
| Mindray Medical International |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Samsung Electronics |
| Esaote |
| Hitachi |
| Others |
Value Network & Pricing Analysis
Andean freight corridors connecting São Paulo manufacturing zones to Colombian diagnostic networks impose variable logistics burdens that compress margins on portable ultrasound categories while amplifying price differentiation between cart-based systems and handheld units. These transportation cost dynamics concentrate supply chain leverage with manufacturers maintaining Brazilian assembly partnerships, forcing import-dependent competitors to absorb tariff exposure or concede pricing power in public hospital tenders.
Pricing Analysis
Next-generation CMUT-based portable systems command premium positioning against prior-generation piezoelectric cart-based platforms, while current-generation software-beamforming mid-tier devices erode the traditional performance-price hierarchy. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling rather than hardware capability alone. Cost compression in standard-tier categories is intensifying because third-party technical service providers unbundle maintenance contracts previously captured by original equipment manufacturers. Public hospital procurement offices in Brazil's SUS network exhibit highest price sensitivity due to separately tendered hardware and support agreements, while private fetal medicine units in Buenos Aires demonstrate lowest sensitivity given premium 3D volume-rendering requirements.
Supply Chain Analysis
Extended payment terms from Brazilian public hospital federations and supply-chain finance facilities anchored in São Paulo state procurement cycles strain working capital for component importers. Manufacturing concentration centers on China for CMUT wafer fabrication, South Korea for FPGA-based signal processing modules, and domestic Brazilian assembly for finished system integration to minimize Mercosur tariff exposure. Raw material dependencies encompass piezoelectric ceramic substrates, high-frequency transducer arrays, and lithium-ion battery cells for portable power architectures. Single-source vulnerability sits with CMUT wafer suppliers given limited qualified fabrication capacity outside East Asian production hubs. Distribution runs through authorized medical device distributors with ANVISA regulatory affairs capacity, channeling systems into state hospital networks and emerging Colombian diagnostic center clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's accredited sonographer training programs graduate insufficient practitioners to match public hospital expansion targets, creating operational bottlenecks that constrain equipment utilization rates regardless of procurement volume. This capability scarcity rewards stakeholders who secure clinical workforce access or automate image acquisition workflows.
For Market Incumbents: Entrench service infrastructure depth through multi-year technical support contracts with São Paulo and Minas Gerais state hospital networks, exploiting third-party service unbundling threats to capture maintenance revenue streams. Deepen backward integration into CMUT component supply through Asian fabrication partnerships, reducing exposure to single-source wafer suppliers while defending margin position against emerging portable specialists. For New Entrants and Emerging Players: Amazon basin telemedicine programs in Peru and Pacific coast mobile diagnostic services in Colombia's Valle del Cauca agricultural zones represent the most penetrable entry points for cloud-connected portable units where fixed infrastructure remains economically unviable. Prioritize ANVISA regulatory affairs capacity building to circumvent six-to-nine month registration delays that disadvantage import-dependent competitors in Brazilian public tenders. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized medical device divisions lacking localized South American regulatory affairs infrastructure. Long-term viability hinges on exposure to software-based beamforming and AI-integrated workflow automation rather than legacy hardware differentiation. Monitor Mercosur technical harmonization negotiation outcomes as inflection indicators for approval pathway consolidation that would reduce compliance duplication costs across Brazil, Argentina, and Uruguay.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway Acceleration | Reduces six-to-nine month delays that disadvantage import-dependent manufacturers in Brazilian public tenders. |
| CMUT Component Supply Agreement | Secures wafer fabrication capacity from East Asian suppliers amid single-source vulnerability in transducer arrays. |
| Hospital System Partnership | Locks in multi-year maintenance bundling with São Paulo state networks against third-party service unbundling. |
| Software Companion Development | Enables AI-integrated cardiac measurement tools addressing structural sonographer shortages in secondary Brazilian cities. |
| Reimbursement Strategy | Aligns portable system pricing with Colombia's emerging diagnostic center network procurement thresholds. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at ANVISA-registered device importers, then refined through secondary validation against hospital procurement databases, GPO contract repositories, ANVISA registration filings, and customs import records. Bottom-up equipment installation tracking across Brazilian state hospital networks was triangulated with top-down manufacturer shipment data to reconcile volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions spanning product configuration, clinical setting, signal processing architecture, and anatomical application focus. CAGRs were derived from procedure volume trajectories in obstetrics and cardiology departments, public health infrastructure investment schedules, and technology substitution rates from cart-based to portable categories. Forecast inputs incorporated ANVISA registration timeline assumptions and Mercosur tariff exposure scenarios.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Colombian peso volatility, or public health budget allocation priorities would shift the trajectory of equipment procurement cycles. Forecasts reflect documented assumptions regarding regulatory harmonization progress and CMUT manufacturing cost reduction curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hormonal Implants Market
Medical Devices
Cervical Spine System Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market
Medical Devices
Knee Braces Market
Medical Devices
Biliary Catheters Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Thrombectomy System Market