
 Cat Allergy in Humans Market | 2026-2036
Cat Allergy in Humans Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Allergy in Humans Market Analysis
A shortage of board-certified allergists and immunotherapy technicians is unwinding access constraints across outpatient networks. GlaxoSmithKline plc leverages its respiratory portfolio depth to sustain dominance in antihistamine distribution. Regeneron Pharmaceuticals, Inc anchors its position through biologic R&D intensity in IgE-mediated pathways. Sanofi competes via global manufacturing scale for corticosteroid nasal spray formulations.
Cat allergy in humans denotes a type I hypersensitivity reaction triggered by Fel d 1 glycoprotein shed in saliva, sebaceous secretions, and dander, typically quantified by serum-specific IgE levels exceeding 0.35 kU/L or positive skin-prick wheal diameters. The condition drives commercial demand for symptomatic blockade and disease-modifying immunotherapy across outpatient and self-administered settings. Allergen immunotherapy commands the deepest margin pools due to multi-year treatment protocols and specialized extraction manufacturing, while sublingual tablet delivery is gaining fastest as patients seek needle-free alternatives to injection regimens. Respiratory allergies occupy the largest addressable base, though anaphylaxis management commands premium pricing through epinephrine auto-injector adjacency.
FDA oversight of biologics through the Center for Drug Evaluation and Research shapes clinical trial requirements and label expansion pathways for novel Fel d 1-neutralizing antibodies. EMA's MDR and pharmacovigilance frameworks in Europe impose post-market surveillance obligations that filter which manufacturers sustain cross-border registration. Stakeholders must monitor how FDA accelerated approval designations for biologic therapies reshape competitive entry timelines and payer negotiation leverage.
Market Dynamics
Fel d 1-neutralizing biologics are compressing development timelines through FDA accelerated approval pathways, while sublingual tablet formats displace injection regimens across outpatient networks. This dual shift is reconfiguring margin pools toward disease-modifying therapies and away from symptomatic blockade.
Growth Catalysts
- FDA Accelerated Approval:The Center for Drug Evaluation and Research's streamlined pathways for biologics are shortening clinical trial-to-commercialization intervals for IgE-targeting therapies.
- Sublingual Delivery Adoption:Needle-free immunotherapy formats are capturing patient preference in pediatric allergy clinics and self-administered settings.
- Specialist Network Expansion:Board-certified allergist training programs in the United States are gradually unwinding workforce shortages constraining treatment access.
Market Restraints
- Extraction Manufacturing Concentration:Allergen immunotherapy production relies on specialized Fel d 1 extraction facilities concentrated in limited geographies, creating supply vulnerability.
- EMA Post-Market Surveillance:The Medical Device Regulation and pharmacovigilance frameworks impose ongoing compliance burdens that filter cross-border registration sustainability.
- Antihistamine Substitution:Over-the-counter symptomatic blockade remains a low-cost alternative compressing payer willingness to reimburse premium biologics.
Strategic Opportunities
- Pediatric Underpenetration:Allergy immunotherapy protocols remain underutilized in children despite rising diagnostic rates in United States specialist networks.
- Biologic-Device Convergence:Combination products pairing Fel d 1-neutralizing antibodies with auto-injector delivery systems are opening new reimbursement categories.
- IRA Price Negotiation Exclusions:Certain biologic categories remain shielded from Medicare price controls, preserving premium pricing windows for novel entrants.
Industry Challenges
- Immunotherapy Technician Scarcity:Specialized extraction handling and dose-escalation protocols require certified personnel in short supply across outpatient networks.
- Multi-Year Protocol Adherence:Allergen immunotherapy's extended treatment duration creates patient dropout risk that compresses realized revenue per initiated course.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Allergy in Humans Market |
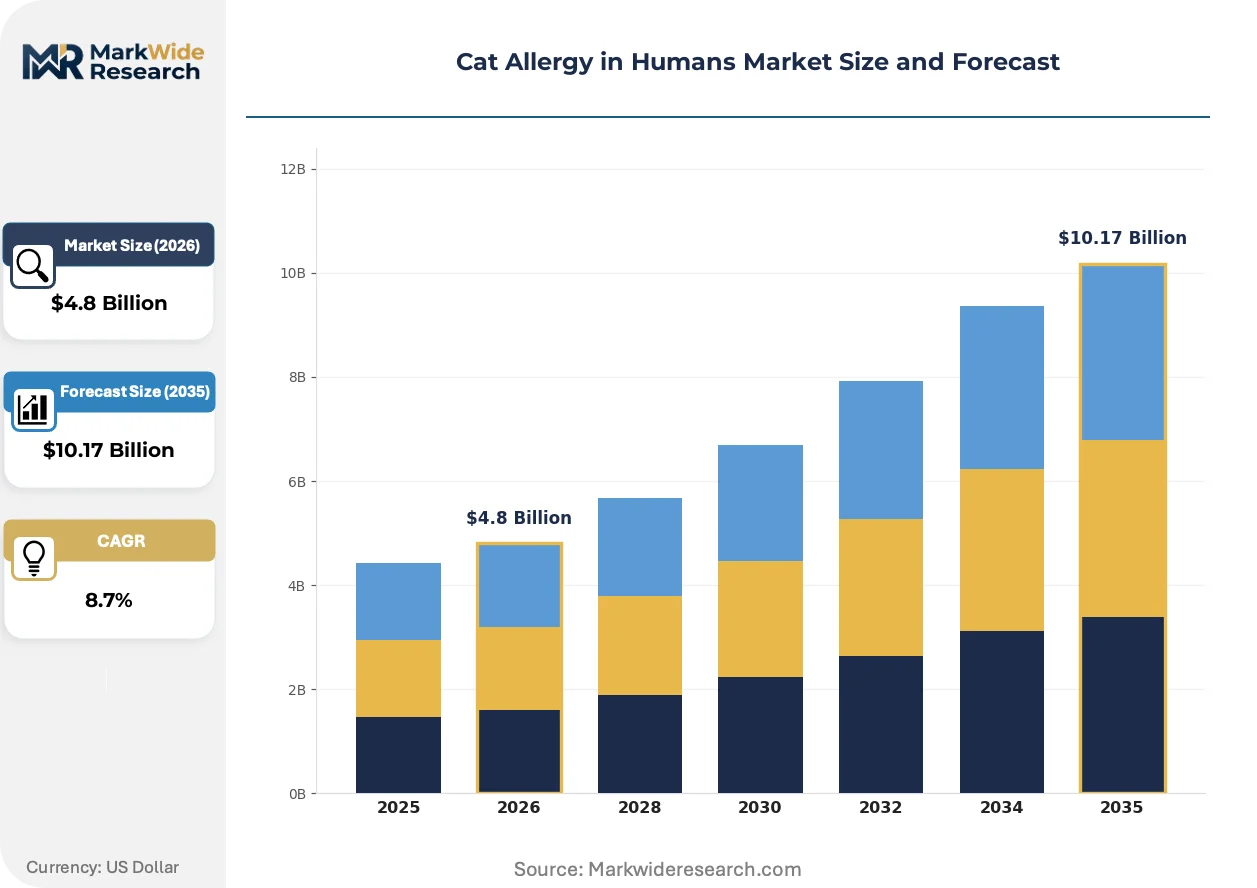
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Allergen Immunotherapy, Antihistamines, Corticosteroids, Decongestants Delivery Mode: Injection, Sublingual Tablet, Nasal Spray, Oral Solution End User: Hospitals, Clinics, Homecare Settings, Specialty Pharmacies Therapy Area: Respiratory Allergies, Eye Allergies, Skin Allergies, Anaphylaxis |
| Companies Covered | Bayer AG, GlaxoSmithKline plc, Merck & Co., Inc, Sanofi, Regeneron Pharmaceuticals, Inc, AstraZeneca, Boehringer Ingelheim, Novartis, Cipla Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Allergy in Humans Market Emerging Trajectories
Biologic engineering and patient-administered delivery formats are converging to reshape competitive positioning in hypersensitivity management. These developments are compressing the gap between clinical efficacy and real-world adherence.
Recombinant Fel d 1 hypoallergens are advancing through clinical pipelines as next-generation immunotherapy substrates. Pediatric allergy clinics in the United States are prioritizing these candidates for their improved safety profiles during dose escalation. This protein engineering trajectory is miniaturizing the risk-benefit calculus that previously limited immunotherapy expansion into younger demographics.
The FDA's breakthrough therapy designation framework is creating differentiated regulatory channels for novel biologics targeting IgE-mediated pathways. Manufacturers are responding by front-loading clinical investment to secure priority review vouchers and accelerated label expansions. Subcutaneous biologic formats for cat allergy are experiencing compressed approval timelines relative to historical immunotherapy benchmarks.
Patients are consolidating therapy decisions around needle-free alternatives that reduce clinic visit burden. Sublingual tablet regimens are displacing subcutaneous injection protocols in self-administered settings, particularly among working-age adults seeking treatment flexibility. This preference rotation is most visible in United States metropolitan markets where specialist density supports hybrid care models combining initial supervision with remote adherence monitoring.
Cat Allergy in Humans Market Segmentation
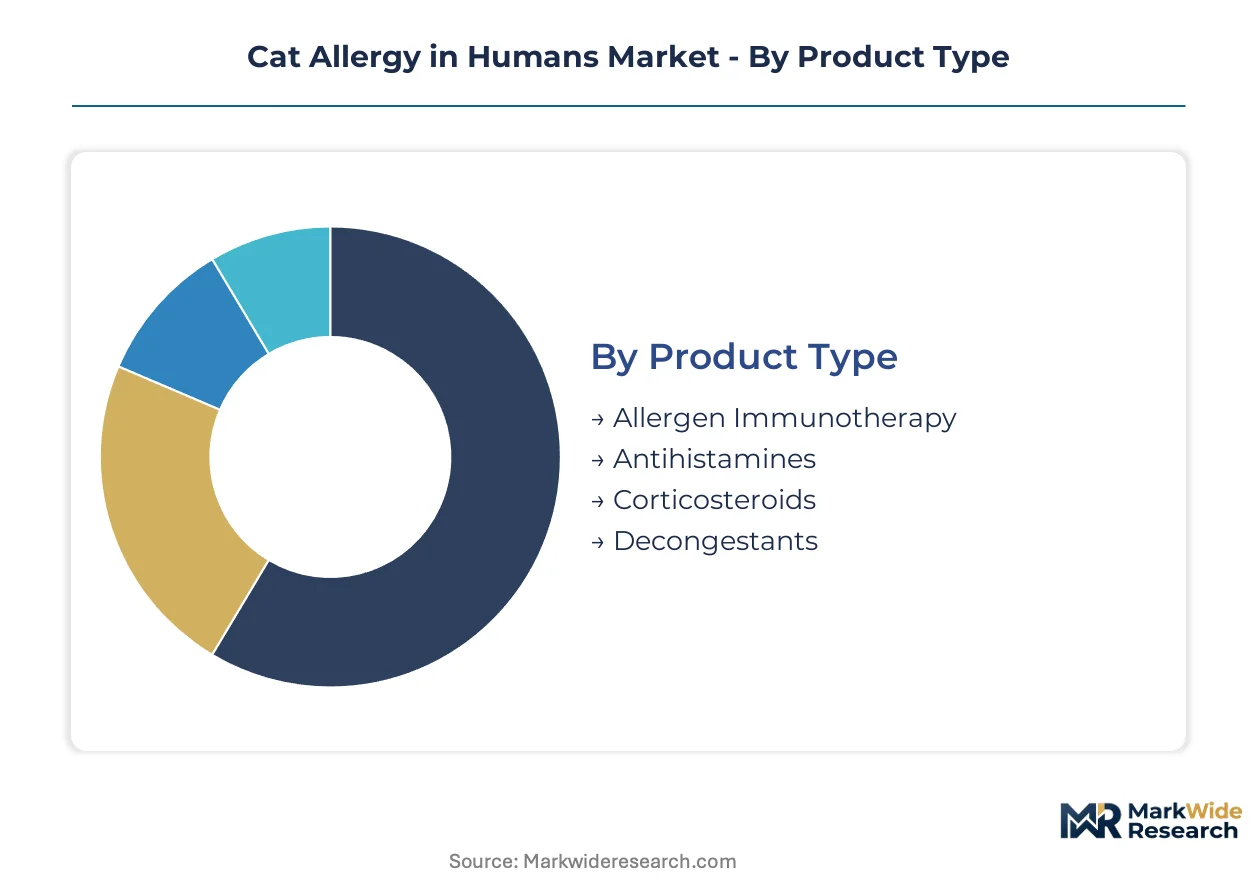
Cat allergy therapeutics flow through distinct channel configurations shaped by regulatory oversight, patient acuity, and reimbursement stratification. Segment boundaries reflect where Fel d 1-neutralizing biologics command premium access versus where symptomatic blockade commoditizes.
Product Type:
Channel mix splits sharply between disease-modifying protocols requiring specialist supervision and self-administered symptomatic agents distributed through retail pharmacy networks.
- Allergen Immunotherapy:Multi-year desensitization protocols utilizing Fel d 1 extracts or recombinant hypoallergens demand allergist oversight and specialized compounding infrastructure. Pediatric allergy clinics in the United States prioritize these treatments for durable disease modification despite extended course durations.
- Antihistamines:H1-receptor antagonists dominate over-the-counter channels with oral and ophthalmic formats saturating retail pharmacy shelves. Payer substitution pressure compresses margins as patients self-select against prescription pathways.
- Corticosteroids:Intranasal and inhaled glucocorticoid formulations serve moderate-to-severe rhinitis through prescription channels requiring physician diagnosis.
- Decongestants:Sympathomimetic agents address acute nasal congestion through limited-duration protocols constrained by cardiovascular safety warnings.
By volume, antihistamines lead. By growth pace, allergen immunotherapy is expanding most quickly.
Delivery Mode:
Patient preference for reduced clinic burden is reconfiguring format adoption curves across age and employment status demographics.
- Sublingual Tablet:Needle-free immunotherapy formats capture working-age adults seeking treatment flexibility without injection-site reactions. United States metropolitan markets with hybrid care models show strongest uptake.
- Injection:Subcutaneous biologics and depot allergen extracts maintain dominance in pediatric populations and severe phenotypes requiring supervised dose escalation.
- Nasal Spray:Topical corticosteroid and antihistamine delivery serves rhinitis-dominant patients through rapid symptom relief with minimal systemic exposure.
- Oral Solution:Liquid formulations address pediatric swallowing limitations and geriatric polypharmacy compliance challenges in homecare settings.
Injection formats retain revenue concentration. Sublingual tablets are gaining share fastest among new treatment initiations.
End User:
Site-of-care decisions hinge on therapy risk profile, with biologic administration concentrated where adverse event management capabilities reside.
- Specialty Pharmacies:Hub-and-spoke distribution models for biologic therapies coordinate prior authorization, patient assistance programs, and cold-chain logistics for IgE-targeting agents.
- Clinics:Board-certified allergist practices control immunotherapy initiation and dose-escalation protocols, creating bottleneck capacity constraints.
- Hospitals:Academic medical centers anchor clinical trial recruitment for novel Fel d 1-neutralizing antibodies and manage anaphylaxis emergencies.
- Homecare Settings:Self-administered sublingual tablets and second-generation antihistamites shift volume toward direct-to-patient channels with remote adherence monitoring.
Specialty pharmacies capture the highest revenue per patient. Homecare settings are expanding most quickly as needle-free formats proliferate.
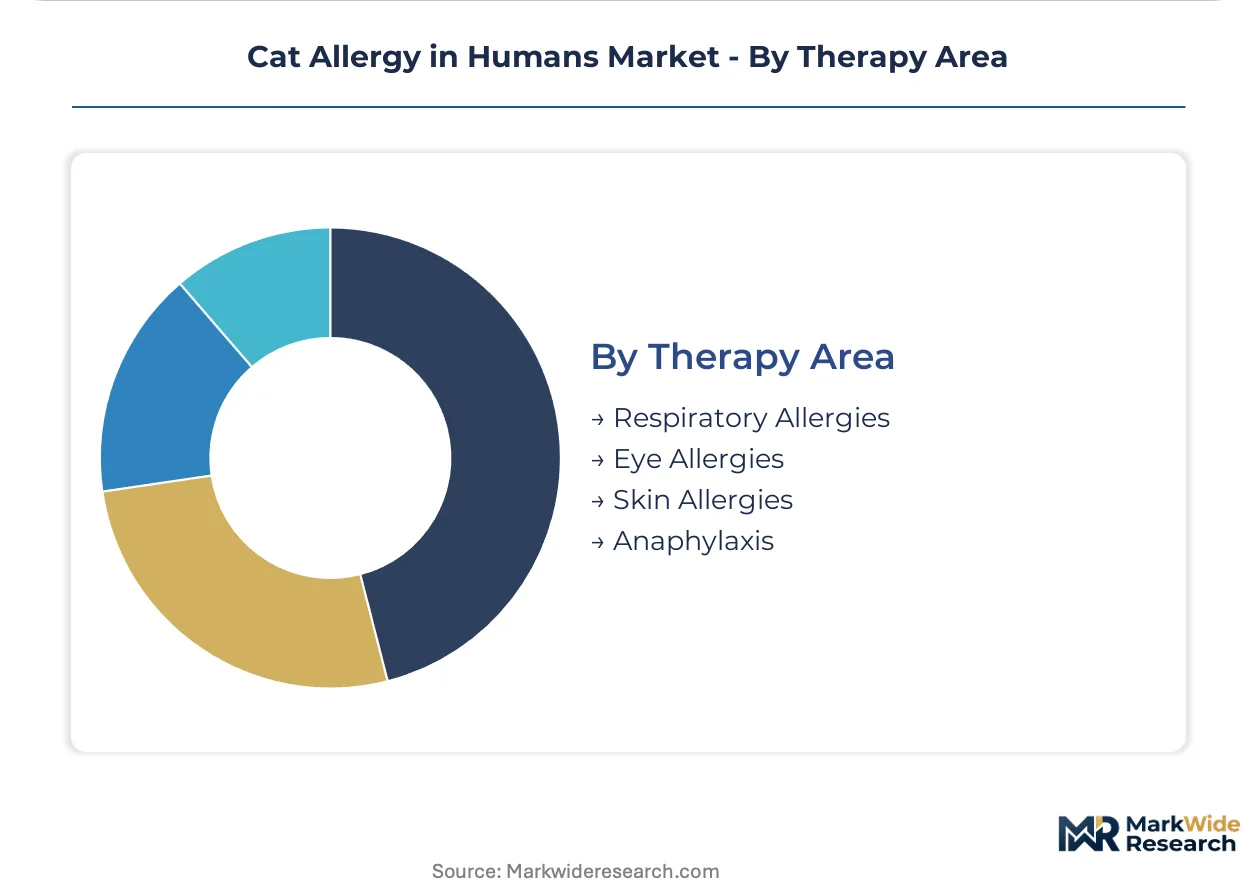
Therapy Area:
Clinical presentation determines whether patients enter specialist referral pathways or self-treat through retail channels.
- Respiratory Allergies:Rhinitis and asthma phenotypes constitute the deepest addressable base, with biologic eligibility screening concentrating in United States immunology networks.
- Anaphylaxis:Systemic reactions command premium pricing through epinephrine auto-injector adjacency and emergency preparedness protocols despite smaller incident prevalence.
- Eye Allergies:Allergic conjunctivitis drives ophthalmic antihistamine and mast cell stabilizer demand through optometry and primary care channels.
- Skin Allergies:Urticaria and atopic dermatitis manifestations extend treatment into dermatology practices with topical and systemic therapeutic overlap.
Respiratory allergies dominate patient volume. Anaphylaxis management delivers the steepest expansion trajectory through biologic-device convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for cat allergy therapeutics diverge sharply across geographies, with the United States prioritizing biologic interventions while European markets emphasize sublingual immunotherapy protocols and Asian markets concentrate on symptomatic blockade through retail pharmacy networks.
United States
Pediatric allergy clinics and specialist immunology networks drive biologic adoption, with the FDA's accelerated approval pathways compressing development timelines for IgE-targeting therapies. The Inflation Reduction Act shields certain biologic categories from Medicare price negotiations, preserving premium pricing windows. Boston and New York metropolitan areas anchor clinical trial recruitment for novel Fel d 1-neutralizing antibodies.
Germany
Allergen immunotherapy protocols achieve deeper penetration through statutory health insurance reimbursement structures that favor disease-modifying treatments. The EMA's Medical Device Regulation imposes post-market surveillance obligations that filter cross-border registration sustainability for extraction-based manufacturers. The Rhine-Ruhr corridor concentrates specialized Fel d 1 extraction facilities serving central European distribution networks.
Japan
Self-administered sublingual tablet formats capture working-age adults seeking treatment flexibility without clinic visit burdens. PMDA oversight of biologics shapes clinical trial requirements for novel hypersensitivity interventions. The Kanto region around Tokyo anchors specialist allergist practices controlling immunotherapy initiation protocols.
United Kingdom
NHS commissioning frameworks prioritize cost-effective symptomatic blockade, compressing payer willingness to reimburse premium biologics outside severe phenotypes. NICE technology appraisals determine reimbursement eligibility for sublingual immunotherapy formats. The Greater London area concentrates academic medical centers managing anaphylaxis emergencies and clinical trial recruitment.
India
Generic antihistamine manufacturing scales through domestic formulation capabilities serving price-sensitive retail pharmacy networks. CDSCO regulatory pathways for biologics remain less streamlined than FDA or EMA equivalents, extending commercialization intervals. Maharashtra and Gujarat host corticosteroid nasal spray production facilities supplying South Asian export markets.
Cat Allergy in Humans Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the cat allergy therapeutics market. Respiratory portfolio depth and biologic R&D intensity separate the upper tier from mid-scale manufacturers concentrated in symptomatic blockade. Three archetypes dominate: pharmaceutical conglomerates with respiratory franchise breadth, biotech specialists in IgE-mediated pathways, and generic manufacturers competing on antihistamine commoditization. Consolidation through acquisition of sublingual delivery platforms and strategic partnerships for Fel d 1 extraction capacity represent the dominant competitive moves reshaping market structure.
Within the integrated pharmaceutical tier, GlaxoSmithKline plc and Sanofi exemplify scale-driven positions anchored in respiratory portfolio breadth and global manufacturing infrastructure. Regeneron Pharmaceuticals, Inc occupies a distinct position within the biologic specialist archetype, representing R&D intensity in IgE-targeting pathways. These three companies collectively illustrate how competitive positioning diverges between symptomatic blockade commoditization and disease-modifying therapy premium capture.
| Leading Market Players |
|---|
| Bayer AG |
| GlaxoSmithKline plc |
| Merck & Co., Inc |
| Sanofi |
| Regeneron Pharmaceuticals, Inc |
| AstraZeneca |
| Boehringer Ingelheim |
| Novartis |
| Cipla Limited |
| Others |
Supply Flow & Price Mechanics
FDA Center for Drug Evaluation and Research oversight gates both biologic manufacturing qualification and premium pricing tiers for Fel d 1-neutralizing therapies, compressing margin dispersion between certified extraction facilities and commodity antihistamine producers.
Pricing Analysis
Long-term offtake agreements dominate allergen immunotherapy procurement, while spot purchasing prevails in retail antihistamine channels. Pricing stratifies across premium biologics, standard sublingual tablets, and economy OTC generics based on FDA certification tier and administration complexity. Cost compression in the generic antihistamine tier intensifies due to Indian and Chinese formulation exports. Pediatric allergy clinics exhibit lowest price sensitivity; self-paying retail consumers show highest.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain Fel d 1 extract shipments from German and Austrian compounding facilities to United States distribution hubs. Raw material supply draws from specific-pathogen-free cat colonies in the Netherlands, recombinant protein fermentation capacity in Switzerland, and nasal spray device manufacturing in Ireland. Single-source vulnerability concentrates in specialized allergen extraction infrastructure. Distribution runs through specialty pharmacy hub-and-spoke networks coordinating cold-chain biologic delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cat allergy therapeutics market is entering a cyclical recovery phase as FDA accelerated approval pathways compress development timelines and specialist network expansion unwinds prior access constraints.
For Market Incumbents: Compound respiratory portfolio depth with biologic R&D intensity to defend against sublingual tablet substitution. Secure backward integration into Fel d 1 extraction capacity in the Rhine-Ruhr corridor to mitigate supply concentration risk. Prioritize pediatric allergy clinic relationships where protocol adherence generates multi-year revenue visibility.
For New Entrants and Emerging Players: Remote adherence monitoring services represent an underdeveloped layer where incumbents under-serve working-age adults seeking treatment flexibility. Target United States metropolitan markets with hybrid care models for sublingual tablet launches. Pursue strategic partnerships with telehealth platforms to bypass specialist capacity bottlenecks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across recombinant hypoallergen manufacturing as protein engineering advances reduce fermentation scale requirements. Platform biotech specialists with validated IgE-targeting mechanisms offer strongest acquisition profiles. Monitor FDA breakthrough therapy designation grants as inflection signals for competitive entry timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Fel d 1-neutralizing biologics secure FDA accelerated approval pathways through IgE-mediated pathway validation. |
| Manufacturing Scale-Up | Recombinant hypoallergen production expands in Swiss and German facilities to serve European immunotherapy demand. |
| Regulatory Approval Pathway | EMA MDR compliance investments filter cross-border registration sustainability for extraction-based manufacturers. |
| Strategic Partnership | Telehealth platforms ally with sublingual tablet developers to bypass board-certified allergist capacity constraints. |
| Pipeline Diversification | Pediatric formulation development captures underpenetrated demographic despite extended dose-escalation protocols. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with board-certified allergists, specialty pharmacy procurement managers, biologic manufacturing executives, and payer formulary directors. Secondary validation drew from FDA biologics license applications, EMA marketing authorization submissions, ClinicalTrials.gov protocol registries, and United States immunology network capacity surveys. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Across the analysis window, forecasts deploy a segmented analytical framework spanning product type, delivery mode, end user site-of-care, and therapy area severity tier. CAGRs derive from patient initiation rate projections, protocol adherence decay curves, and pricing tier evolution assumptions. Fel d 1 diagnostic testing penetration and biologic eligibility screening criteria serve as key demand-side inputs.
Material uncertainties — regulatory pathway delays, extraction facility contamination events, and IRA price negotiation scope expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions about specialist workforce growth and sublingual tablet reimbursement parity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
AI-Powered Formulary Management Market
Health Informatics
Laboratory Informatics Market
Health Informatics
Global Healthcare Informatics Market
Health Informatics
Healthcare Operational Analytics Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
Global Laboratory Information Management System (LIMS) Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
EHR EMR Market
Health Informatics
Healthcare BI Market
Health Informatics
Allergy Care Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
US Healthcare Payer Analytics Market