
 Global Operating Microscopes Market | 2026-2036
Global Operating Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Operating Microscopes Market Foresight
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape between established optical manufacturers and emerging digital entrants. Carl Zeiss Meditec leverages its vertically integrated lens production to sustain premium positioning across European teaching hospitals. Leica Microsystems anchors its presence through proprietary FusionOptics technology, while Alcon competes aggressively in the ophthalmic surgical segment with integrated visualization platforms.
Operating microscopes are precision optical instruments combining stereoscopic magnification, coaxial illumination, and motorized positioning to enable real-time visualization during delicate surgical procedures, with modern systems achieving resolution below one micrometer and integrating 4K-8K digital image capture. Digital operating microscopes are capturing margin pools as hospitals replace conventional platforms to support fluorescence-guided neurosurgery and intraoperative OCT, while robotic assistance represents the fastest-growing technology dimension as Intuitive Surgical and KARL STORZ navigate regulatory pathways for autonomous positioning. The application landscape sees neurosurgery and ophthalmic surgery commanding the highest equipment values, with ENT and plastic surgery representing volume expansion corridors in ambulatory settings.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements are extending product development cycles and raising barriers for new entrants seeking hospital procurement contracts. Japan's PMDA and China's NMPA are converging toward ISO 13485 quality management standards, creating compliance efficiencies for multinationals but complicating regional specialist strategies. Stakeholders must monitor the interplay between optical hardware refresh cycles and software-enabled service revenue models as purchasing committees shift capital allocation toward platforms with validated AI-assisted image analysis modules.
Market Dynamics
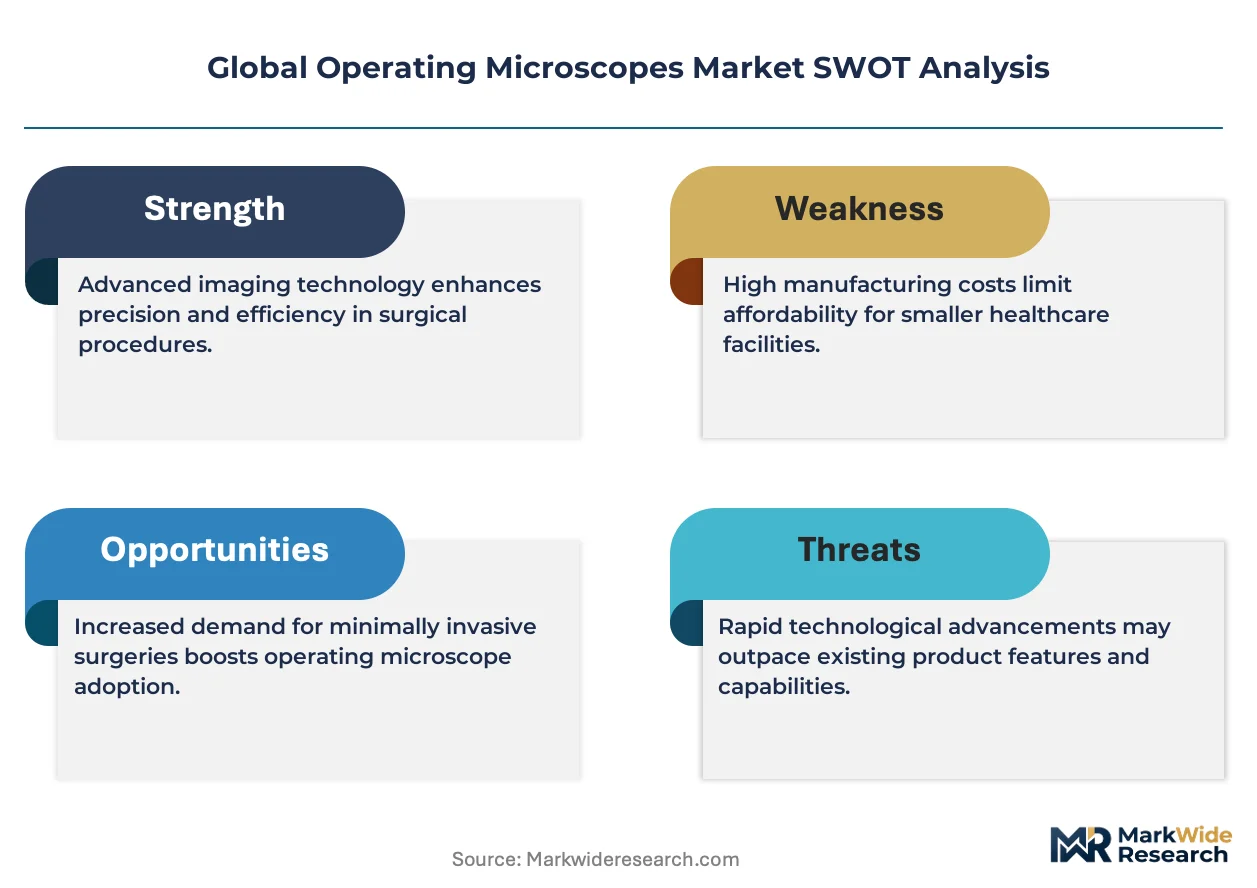
Robotic-assisted positioning systems are compressing replacement cycles for conventional optical platforms as hospital procurement committees prioritize autonomous navigation capabilities over incremental lens upgrades.
Growth Catalysts
- EU MDR optical performance mandates:Tightened illumination and resolution standards under CE marking are forcing hospital system upgrades across Germany, France, and Italy.
- Fluorescence-guided neurosurgery:Real-time tumor margin visualization using indocyanine green dye is expanding addressable procedure volumes in cranial and spinal suites.
- Ambulatory surgical center expansion:ENT and plastic surgery volumes in United States outpatient settings are creating secondary equipment demand below hospital price tiers.
Market Restraints
- Precision glass supply concentration:German and Japanese optical glass manufacturers control critical substrate supply for apochromatic objectives, creating input vulnerability.
- FDA 510(k) timeline extension:Digital imaging module submissions now average 18-24 months versus 12-15 months for purely optical predecessors.
- Intraoperative OCT cost barriers:Spectral-domain optical coherence tomography add-ons price 40-60% above base microscope configurations, limiting penetration outside academic medical centers.
Strategic Opportunities
- India's CDSCO fast-track pathway:Streamlined approval for fluorescence-capable systems creates first-mover positioning in underpenetrated tier-2 city hospital networks.
- AI-assisted image analysis modules:Machine learning algorithms for real-time vessel mapping and tissue classification enable recurring software revenue streams.
- Veterinary ophthalmology crossover:Adapted neurosurgical platforms for companion animal cataract and retinal procedures open price-accessible volume segments.
Industry Challenges
- Mechatronics engineering scarcity:Integration of precision optics, motorized positioning, and digital capture requires hybrid skill sets concentrated in Stuttgart, Rochester, and Tokyo metropolitan clusters.
- Legacy OR integration complexity:New platforms must interface with existing surgical navigation systems from Brainlab, Medtronic, and Stryker without proprietary lock-in.
- ISO 13485 documentation burden:Software-as-a-medical-device classifications for AI modules extend quality management system audits and corrective action timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Operating Microscopes Market |
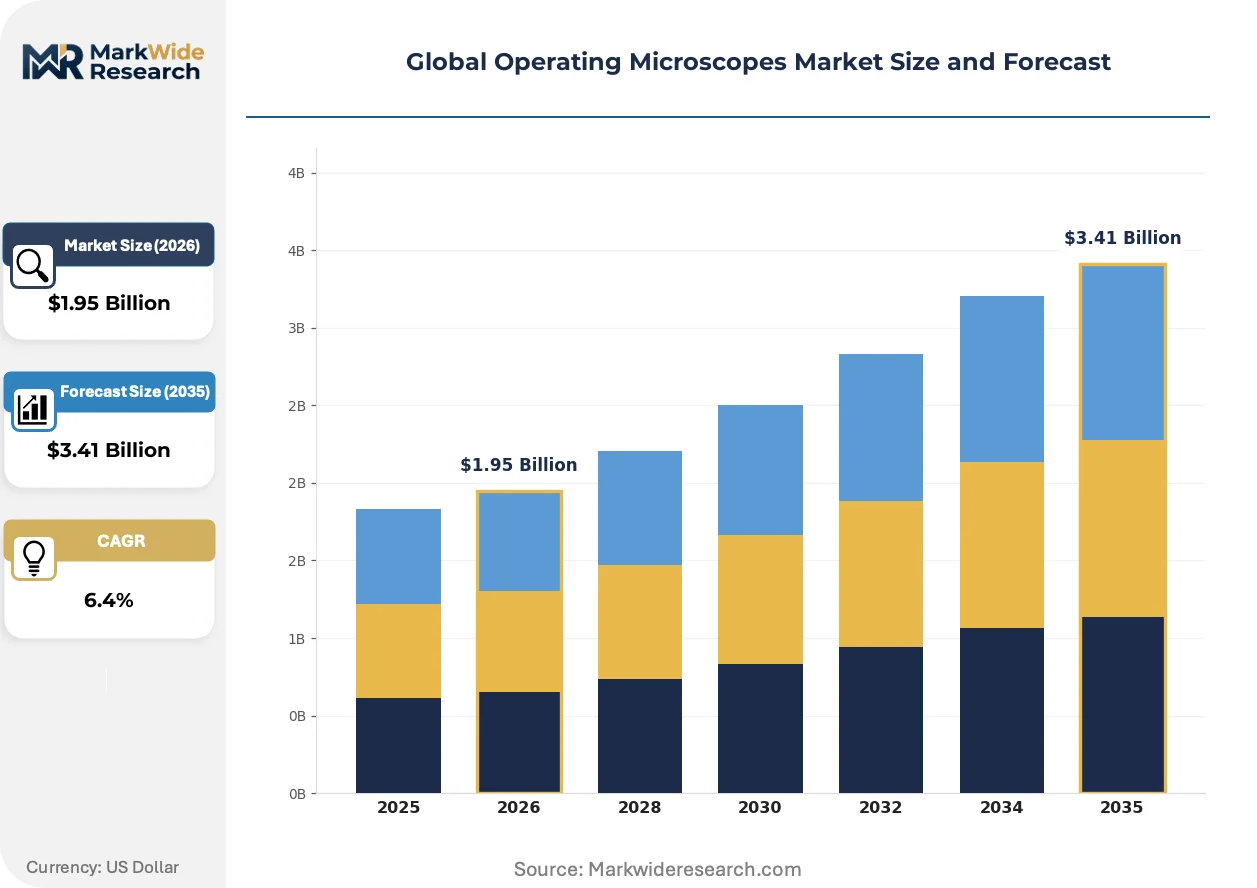
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Operating Microscopes, Compact Operating Microscopes, Stereo Operating Microscopes, Digital Operating Microscopes, Conventional Operating Microscopes Technology: Optical Zoom, Robotic Assistance, 3D Visualization, Fluorescence Imaging, Laser Integration Application: Neurosurgery, Ophthalmic Surgery, ENT Surgery, Dental Surgery, Plastic Surgery, Orthopedic Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes, Academic Medical Centers |
| Companies Covered | Carl Zeiss Meditec, Leica Microsystems, Alcon, Topcon Corporation, Olympus Corporation, Haag-Streit Group, KARL STORZ, Nikon Corporation, Intuitive Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Operating Microscopes Market Shifts & Advancements
Digital image sensors and computational optics are displacing purely mechanical light paths, compressing the traditional hierarchy between premium optical manufacturers and semiconductor imaging specialists.
CMOS sensors with backside illumination are miniaturizing camera heads mounted on microscope bodies, enabling surgeons to operate without ocular eyepieces. Academic medical centers in Boston and Heidelberg are piloting these heads-up displays for complex vascular neurosurgery. The technology is compressing equipment footprints and enabling parallel observation by entire surgical teams rather than individual operators.
Japan's PMDA has aligned its software medical device guidance with FDA's predetermined change control plans, allowing manufacturers to deploy AI algorithm updates without full resubmission. This regulatory convergence reduces validation costs for multinationals operating across both markets. Neurosurgical suites with validated AI modules are capturing preference in hospital procurement evaluations.
Buying committees now unbundle after-sales service contracts from capital equipment purchases, pitting independent service organizations against manufacturer captive service arms. United States hospital systems with centralized biomedical engineering departments are driving this disintermediation most aggressively. The shift compresses manufacturer margin pools while expanding third-party calibration and preventive maintenance markets.
Global Operating Microscopes Market Segmentation
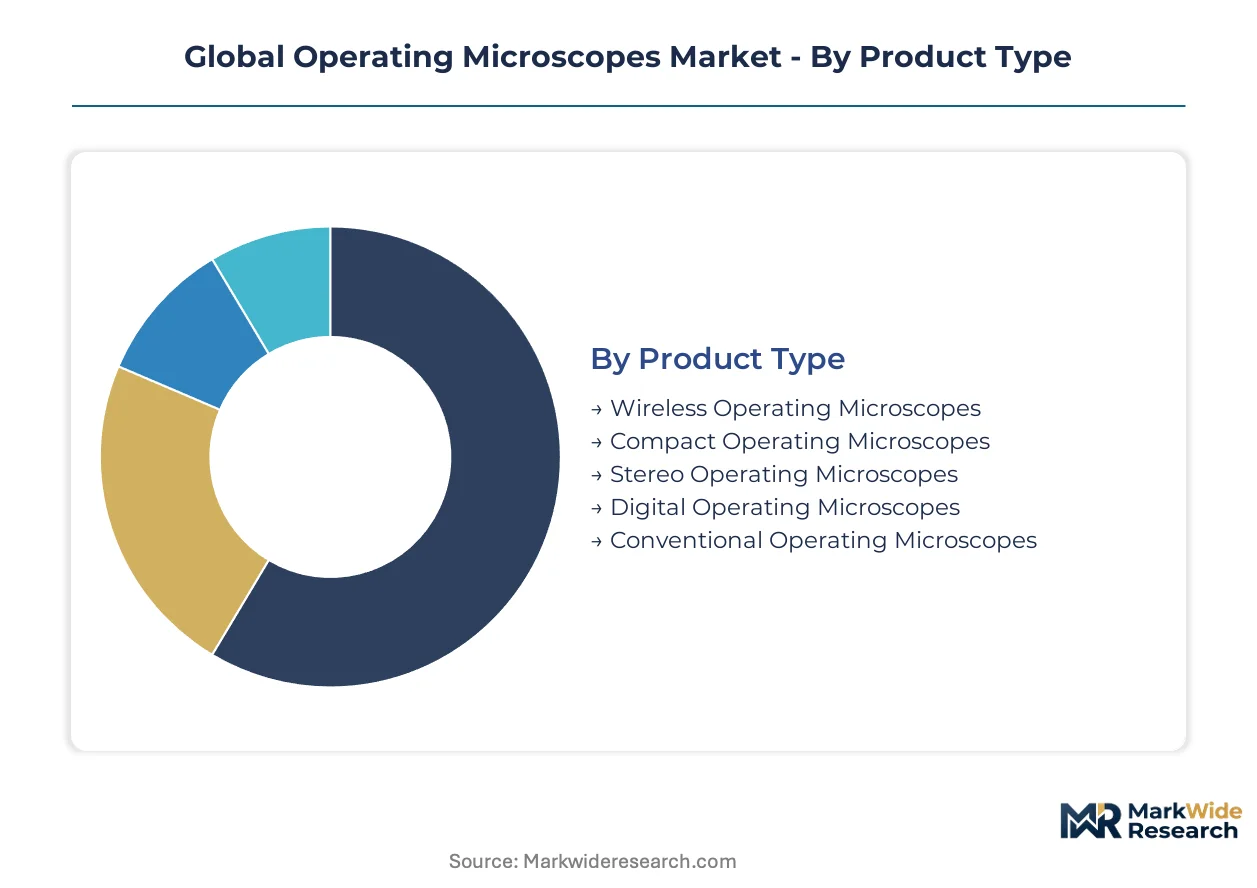
Operating microscope segmentation reveals how margin pools concentrate in digitally integrated platforms versus conventional optical systems. Procurement committees now weight fluorescence capability and robotic positioning above legacy magnification specifications.
Product Type:
Margin pools sit heaviest in systems combining digital capture with fluorescence-ready optical paths, while compact platforms serve price-sensitive ambulatory expansion.
- Digital Operating Microscopes:These platforms integrate CMOS sensors with 4K-8K video output and real-time image processing for heads-up surgical displays. Demand concentrates in German and United States academic medical centers upgrading neurosurgical suites for fluorescence-guided tumor resection.
- Conventional Operating Microscopes:Purely optical mechanical systems with binocular eyepieces and halogen or LED coaxial illumination remain prevalent in India's tier-2 city hospitals and Latin American secondary markets where capital constraints limit digital migration.
- Compact Operating Microscopes:Footprint-reduced designs for ENT and dental outpatient procedures in Japan's clinic-dense urban corridors.
- Stereo Operating Microscopes:Binocular optical paths with adjustable interpupillary distance for plastic surgery suites in South Korea's cosmetic surgery clusters.
- Wireless Operating Microscopes:Battery-powered mobility for field surgical units and military medical detachments with limited infrastructure.
The dominant share belongs to Conventional Operating Microscopes, while Digital Operating Microscopes is closing the gap fastest.
Technology:
Cost tiers separate premium robotic platforms from standard optical zoom configurations, with fluorescence imaging commanding mid-tier positioning.
- Robotic Assistance:Motorized positioning arms with autonomous navigation algorithms enable sub-millimeter instrument placement without manual adjustment. United States hospital procurement committees prioritize FDA 510(k)-cleared platforms from KARL STORZ and Intuitive Surgical for complex spinal procedures.
- Fluorescence Imaging:Indocyanine green dye excitation systems for real-time vascular and tumor margin visualization. Adoption clusters in Heidelberg and Boston academic centers performing awake craniotomies.
- 3D Visualization:Stereoscopic display systems for ophthalmic vitreoretinal surgery in Japan's aging cataract market.
- Optical Zoom:Continuous magnification adjustment through apochromatic objective turrets, the baseline specification for India's CDSCO-registered hospital tenders.
- Laser Integration:Coupled photocoagulation or cutting beams for retinal and glaucoma procedures in German university hospitals.
Optical Zoom retains the largest installed base, though Robotic Assistance is expanding most quickly through replacement cycles in United States health systems.
Application:
Application segmentation tracks where procedure reimbursement rates justify capital equipment investment versus volume-driven outpatient settings.
- Neurosurgery:Cranial and spinal procedures requiring sub-micrometer resolution for vessel dissection and tumor resection. German neurosurgical suites at Charité Berlin and Heidelberg University Hospital anchor European demand for integrated navigation platforms.
- Ophthalmic Surgery:Cataract extraction and vitreoretinal procedures driving the highest unit volumes globally. Japan's aging demographic sustains replacement demand for optical coherence tomography-compatible systems.
- ENT Surgery:Otologic and skull base procedures in United States ambulatory surgical centers with same-day discharge protocols.
- Plastic Surgery:Microvascular anastomosis and reconstructive procedures in South Korea and Brazil's cosmetic surgery corridors.
- Dental Surgery:Endodontic and implant procedures with compact microscope requirements in European private practice networks.
- Orthopedic Surgery:Hand and peripheral nerve surgery in specialized microsurgery units at Mayo Clinic and Hospital for Special Surgery.
Neurosurgery commands the highest equipment values per unit, yet Ophthalmic Surgery delivers the steepest expansion trajectory through demographic-driven volume.
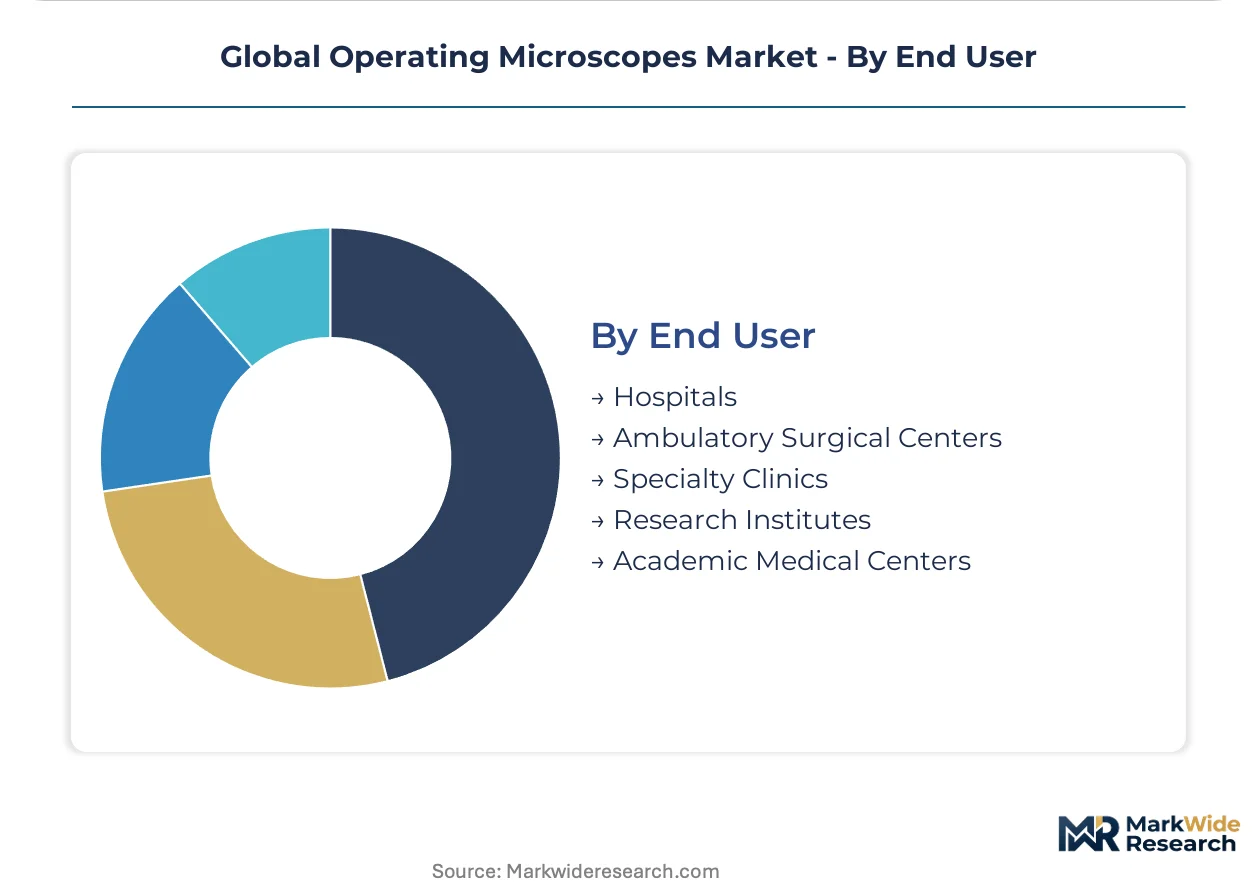
End User:
Customer type determines service contract structures, with academic medical centers demanding AI module integration unavailable in ambulatory price tiers.
- Hospitals:Integrated health systems with centralized procurement negotiating enterprise pricing for multi-suite installations. United States IDNs like HCA Healthcare and CommonSpirit Health standardize on single-vendor platforms to reduce training complexity.
- Ambulatory Surgical Centers:Outpatient-focused facilities in United States markets where Medicare reimbursement shifts favor same-day procedures. ENT and plastic surgery volumes drive secondary equipment demand below hospital price tiers.
- Academic Medical Centers:Research-active institutions in Boston, Heidelberg, and Tokyo piloting heads-up display and AI-assisted image analysis before commercial deployment.
- Specialty Clinics:Ophthalmology and dental single-specialty practices in India's tier-1 cities adopting finance-leased compact systems.
- Research Institutes:Preclinical and translational surgery laboratories at Max Planck Institute and RIKEN requiring ultra-high magnification for microsurgical technique development.
Hospitals maintain the dominant procurement volume, though Ambulatory Surgical Centers is gaining share fastest through United States reimbursement policy shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany, the United States, and Japan concentrate the highest equipment values, while India's tier-2 expansion and China's localization mandates reshape volume distribution.
United States
Integrated delivery networks at HCA Healthcare and CommonSpirit Health drive enterprise standardization for multi-suite neurosurgical installations. FDA 510(k) timelines for digital imaging modules now stretch 18-24 months, compressing upgrade windows. Academic medical centers in Boston pilot heads-up display systems before commercial deployment.
Germany
Charité Berlin and Heidelberg University Hospital anchor European demand for fluorescence-capable cranial platforms. EU MDR optical performance mandates force hospital system upgrades across Bavaria and Baden-Württemberg. Stuttgart's mechatronics engineering cluster concentrates precision optics and motorized positioning integration expertise.
Japan
Aging demographics sustain replacement demand for OCT-compatible ophthalmic systems in Tokyo and Osaka metropolitan corridors. PMDA alignment with FDA predetermined change control plans reduces AI algorithm validation costs for multinationals. Clinic-dense urban networks in Kanto drive compact platform adoption for outpatient ENT procedures.
India
Tier-2 city hospital networks in Maharashtra and Karnataka create first-mover positioning through CDSCO fast-track pathways for fluorescence-capable systems. Central government production-linked incentive schemes for medical devices accelerate local assembly partnerships. Delhi-NCR specialty clinics adopt finance-leased compact systems for ophthalmology and dental practices.
China
NMPA convergence toward ISO 13485 quality management standards creates compliance efficiencies for multinationals while complicating regional specialist strategies. Domestic substitution policies in the Yangtze River Delta favor local optical component sourcing for hospital tenders. Beijing-Tianjin-Hebei academic medical centers pilot robotic-assisted positioning before broader procurement rollout.
Global Operating Microscopes Market Competitive Landscape
Player mix skews toward vertically integrated optical specialists with captive lens production and diversified imaging conglomerates with semiconductor sensor capabilities. Market structure concentrates around three archetypes: precision optics manufacturers controlling apochromatic objective supply, integrated visualization platform vendors bundling surgical navigation, and robotic assistance developers compressing replacement cycles through autonomous positioning. Dominant competitive moves include strategic partnerships with surgical navigation system vendors and geographic expansion through regulatory fast-track pathways in underpenetrated hospital networks.
Among German-based precision optics manufacturers, Carl Zeiss Meditec and Leica Microsystems occupy positions exemplifying vertically integrated production control over critical substrate supply. Alcon represents the integrated visualization platform archetype, sitting within the ophthalmic surgical segment where bundled equipment and consumable strategies predominate. KARL STORZ anchors the robotic assistance development tier alongside Intuitive Surgical, both navigating FDA clearance pathways for autonomous positioning capabilities.
| Leading Market Players |
|---|
| Carl Zeiss Meditec |
| Leica Microsystems |
| Alcon |
| Topcon Corporation |
| Olympus Corporation |
| Haag-Streit Group |
| KARL STORZ |
| Nikon Corporation |
| Intuitive Surgical |
| Others |
Supply & Pricing Matrix
CMOS sensor substitution for optical-mechanical light paths is redrawing procurement geography toward semiconductor fabrication hubs while compressing price premiums previously commanded by German and Japanese precision optics manufacturers. Hospital procurement committees now weight digital imaging specifications above apochromatic lens pedigree, forcing established suppliers to absorb sensor sourcing costs or surrender tier-one positioning.
Pricing Analysis
Cost-plus contracts with German optical glass indexation dominate multi-suite hospital installations, particularly across United States integrated delivery networks. Price differentiation rests on FDA 510(k) clearance tier and bundled AI module validation, with academic medical centers least sensitive and Indian tier-2 city hospitals most responsive to capital constraints. Pricing pressure stems from ambulatory surgical center procurement committees demanding compact configurations below hospital price tiers.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery of Japanese optical glass substrates to Stuttgart assembly facilities. Critical inputs draw from German precision glass manufacturers, Japanese CMOS sensor foundries, and Chinese rare-earth magnet suppliers for motorized positioning systems. Single-source vulnerability concentrates in apochromatic objective lens supply. Distribution runs through manufacturer-direct hospital contracting with captive service arms or independent biomedical engineering organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through United States integrated delivery network consolidation, with HCA Healthcare and CommonSpirit Health standardizing enterprise procurement to extract volume pricing and unified service terms.
For Market Incumbents: Consolidate control over apochromatic objective supply through backward integration into precision glass substrate production or long-term offtake agreements with Schott and Hoya. Defend against emerging digital entrants by embedding AI-assisted image analysis modules into standard configurations before CDSCO fast-track pathways enable competitor penetration in Indian tier-2 networks.
For New Entrants and Emerging Players: After-sales service disintermediation presents white-space opportunity where Carl Zeiss Meditec and Leica Microsystems maintain captive service arm structures. Target United States ambulatory surgical centers with independent calibration and preventive maintenance contracts priced below manufacturer service tiers. Pursue finance-leased compact platform deployment through India's specialty clinic networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision optics specialists possessing captive lens production but limited digital imaging capabilities. Five-to-ten year viability hinges on successful software-as-a-medical-device transition and AI module recurring revenue capture. Monitor PMDA-FDA predetermined change control plan alignment as signal for reduced validation cost trajectories enabling multinational scale.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR optical performance mandates force hospital system upgrades across German teaching hospitals. |
| Hospital System Partnership | Enterprise standardization contracts with United States IDNs reduce training complexity and lock replacement cycles. |
| Software Companion Development | AI-assisted vessel mapping modules enable recurring revenue streams beyond capital equipment sales. |
| Backward Integration | Captive apochromatic objective production insulates margin pools from German-Japanese glass supply concentration. |
| Reimbursement Strategy | Fluorescence-guided neurosurgery coding alignment with Medicare and commercial payers accelerates adoption. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, biomedical engineering directors, neurosurgical suite managers, and GPO contracts managers, then refined against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up equipment shipment tracking and top-down health system capital expenditure analysis were triangulated to resolve variance.
Variance decomposition across product type, technology tier, application specialty, and end-user facility class informed analytical framework construction over the projection horizon. CAGRs were derived from replacement cycle compression rates and ambulatory surgical center expansion trajectories, with fluorescence-capable system adoption curves and robotic assistance penetration assumptions as key inputs.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR optical performance mandates; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disposable Lancets Market
Medical Devices
Micro Syringes Market
Medical Devices
Pulmonology Devices Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Coronary Angiography Devices Market
Medical Devices
Global Microcatheter Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Global Breast Implants Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Implantable Port Market
Medical Devices
Batteries for Skin Patches Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Unilateral Biportal Endoscopy Market