
 Medical Pediatric Bed Market | 2026-2036
Medical Pediatric Bed Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Pediatric Bed Market Insights
Hospital procurement consortia is reconfiguring how pediatric bed manufacturers access large-volume contracts in North America and Western Europe. Stryker Corporation leverages its installed base of acute-care platforms to cross-sell pediatric configurations. Linet anchors Central European demand through direct hospital relationships and localized assembly. Saikang Medical competes aggressively on specification flexibility for Asian public tenders.
A medical pediatric bed is a height-adjustable patient support platform engineered for neonatal through adolescent populations, typically incorporating siderail systems with gap standards under 60 mm and weight capacities calibrated to 80–180 kg depending on age bracket; its primary purpose is to deliver safe positioning, caregiver access, and fall prevention during inpatient observation or recovery. Electric beds command premium positioning in the product-type hierarchy due to motorization demands from pediatric intensive care workflows, while manual beds retain volume dominance in price-sensitive developing markets. Home care providers represent the fastest-expanding end-user channel as post-acute pediatric monitoring shifts beyond hospital walls.
The FDA enforces 21 CFR 880.5125 classification for hospital beds, mandating entrapment-risk testing that shapes design priorities for US-bound manufacturers; in Europe, the MDR and F-Gas Regulation jointly pressure suppliers to document biocompatibility and eliminate certain foam-blowing agents from mattress assemblies. China's NMPA now requires domestic clinical validation for imported pediatric beds, extending registration timelines for foreign brands. Stakeholders must decide whether to absorb compliance costs through premium positioning or cede share to regional competitors with faster certification pathways.
Market Dynamics
Hospital procurement consortia are consolidating purchasing power across Germany and the United States, forcing pediatric bed manufacturers to restructure their sales organizations around multi-hospital contract vehicles rather than individual facility negotiations.
Growth Catalysts
- Neonatal ICU expansion:Pediatric hospitals in Germany and the United States are adding dedicated neonatal intensive care units, creating immediate demand for specialized bed configurations with integrated monitoring capabilities.
- FDA entrapment-risk mandates:The FDA's 21 CFR 880.5125 classification is accelerating replacement cycles as hospitals upgrade to compliant siderail systems with sub-60 mm gap standards.
- China's tier-one hospital construction:Pediatric specialty hospitals are multiplying rapidly in Beijing, Shanghai, and Guangzhou, concentrating demand for imported and domestic bed platforms.
Market Restraints
- Aluminum and steel input volatility:Electric bed frame production depends on precision-machined aluminum extrusions and stainless steel tubing, with price swings compressing margin buffers for mid-tier suppliers.
- European foam-blowing agent restrictions:The EU F-Gas Regulation is eliminating certain blowing agents from mattress assemblies, forcing reformulation investments without corresponding price recovery mechanisms.
- Manual bed substitution in price-sensitive markets:Developing regions in Southeast Asia and Latin America continue specifying manual crank beds for general pediatric wards, limiting electric bed penetration.
Strategic Opportunities
- Home care channel development:Post-acute pediatric monitoring is shifting beyond hospital walls, creating demand for lightweight, collapsible bed platforms with battery backup systems.
- NMPA domestic clinical validation pathways:Foreign manufacturers establishing local testing partnerships can compress China's extended registration timelines and defend share against regional competitors.
- Integrated sensor convergence:Combining pressure-mapping arrays with existing nurse-call infrastructure enables predictive fall-alert systems that differentiate premium offerings.
Industry Challenges
- Biomedical technician specialization gaps:Electric bed maintenance requires expertise in motor control systems and embedded diagnostics that general hospital engineering staff rarely possess.
- Legacy fleet integration complexity:New electric beds must interface with existing building management systems and electronic health record platforms, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Pediatric Bed Market |
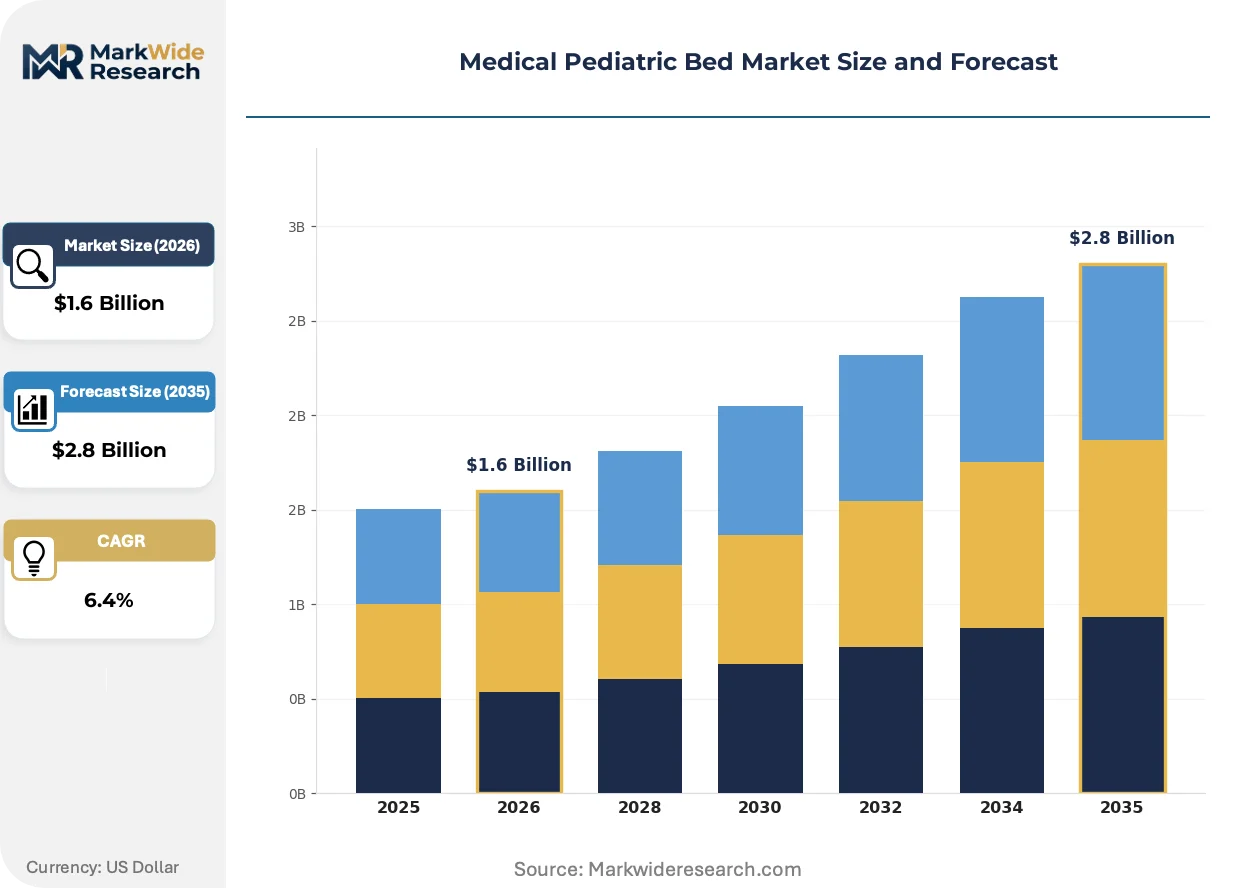
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Beds, Electric Beds, Convertible Beds, Specialty Beds Care Setting: Pediatric Units, Home Care, Rehabilitation Centers, Long-Term Care Material: Metal, Plastic, Foam, Wood End User: Hospitals, Clinics, Home Care Providers, Nursing Homes |
| Companies Covered | Linet, Stiegelmeyer GmbH & Co. KG, Stryker Corporation, Saikang Medical, Schröder Health Projects, Medline Industries Inc., Paramount Bed Co., Ltd., Savion Industries, Invacare Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Pediatric Bed Market Trends and Innovations
Digital integration and regulatory stringency are converging to reshape how pediatric beds are specified, purchased, and maintained across acute and post-acute settings.
Embedded pressure-sensing arrays are digitizing patient positioning data for automated turn-schedule alerts and pressure-ulcer risk scoring. Pediatric intensive care units in the United States are adopting these systems fastest, with some German university hospitals following within 18-24 month lag patterns. The technology is digitizing how nursing staff allocate attention, compressing response times for immobility complications while generating workflow data that feeds into staffing optimization software.
The EU Medical Device Regulation is mandating enhanced biocompatibility documentation for all patient-contact surfaces, including mattress covers and siderail coatings. Manufacturers must now submit extended clinical evidence packages to notified bodies, extending time-to-market by 8-14 months for platform refreshes. Pediatric bed suppliers with existing MDR certificates are capturing share from competitors still navigating the transition, particularly in Benelux and Nordic hospital systems with strict tender compliance requirements.
Consortium purchasing is consolidating decision-making authority into regional procurement bodies that negotiate multi-year, multi-facility agreements. Independent community hospitals in the United States are losing autonomy to systems like Vizient and Premier, while German hospital associations centralize specifications through state-level purchasing cooperatives. This concentration is most visible in California and Texas, where integrated delivery networks now control over half of pediatric bed procurement volume and demand standardized fleet configurations for maintenance efficiency.
Medical Pediatric Bed Market Segmentation
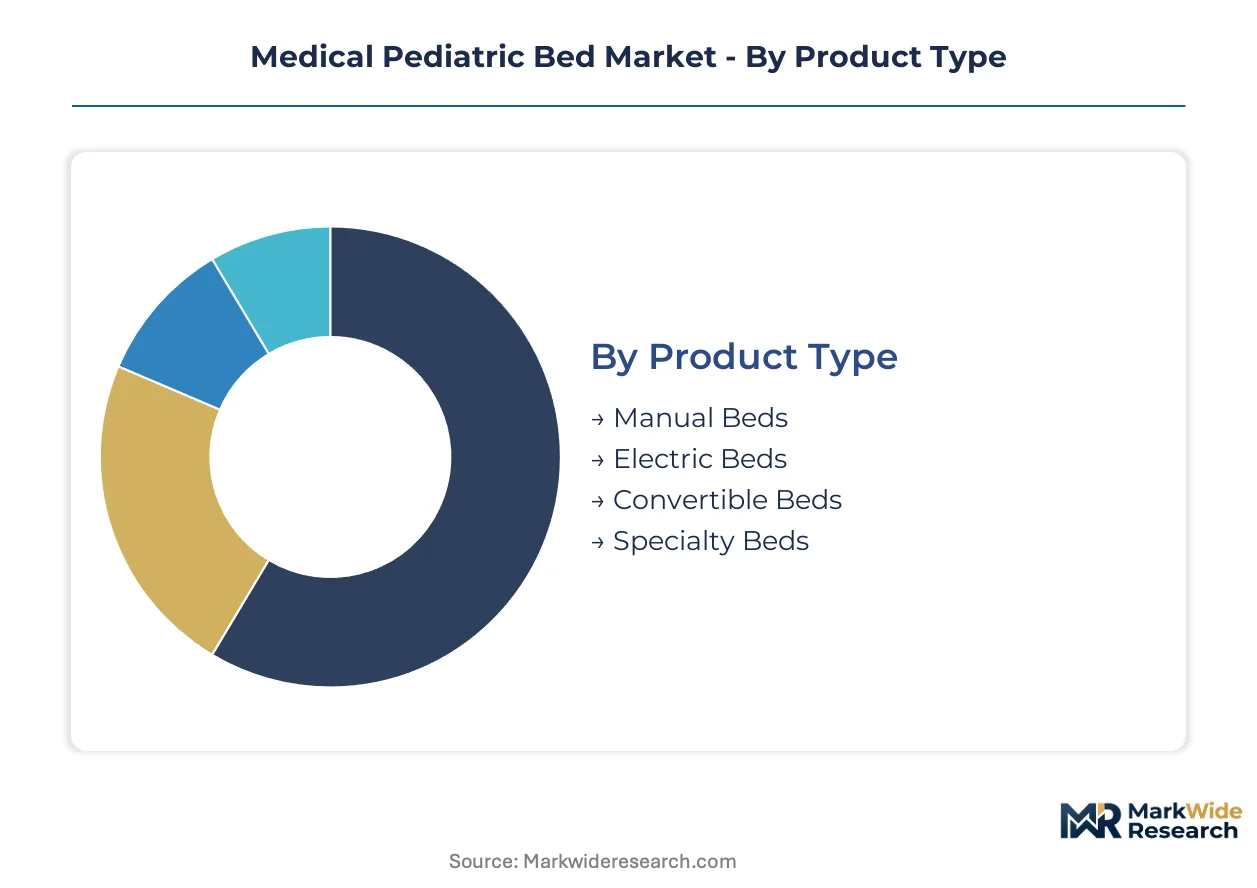
Pediatric bed procurement varies sharply by clinical intensity and reimbursement environment. Manufacturers must configure motorization, materials, and distribution channels to match distinct buyer economics across acute hospitals versus post-acute settings.
Product Type:
Cost tier differentiation separates premium motorization from basic mechanical platforms, with reimbursement ceilings determining viable specifications in each market.
- Manual Beds:Crank-actuated height and positioning systems dominate price-sensitive developing markets where electricity reliability remains inconsistent. Southeast Asian public tenders specify these configurations for general pediatric wards, capping supplier margins but preserving volume throughput.
- Electric Beds:Motorized platforms with embedded control systems command premium positioning in pediatric intensive care workflows across Germany and the United States. FDA entrapment-risk mandates are accelerating replacement cycles toward compliant siderail architectures with sub-60 mm gap standards.
- Convertible Beds:Modular frames transition between crib and adolescent configurations, extending product lifecycle for growing patients. These platforms concentrate in multi-age pediatric units within academic medical centers.
- Specialty Beds:Bariatric, trendelenburg, and isolation-specific variants serve niche clinical requirements. Demand clusters in tertiary referral hospitals managing complex congenital conditions.
Electric beds hold installed capacity across North American and Western European acute care networks. Convertible configurations are rotating up the share rankings as hospitals seek fleet standardization.
Care Setting:
Application intensity dictates specification rigor, with sickest patients requiring integrated monitoring and safest patients accepting simplified platforms.
- Pediatric Units:Acute-care beds incorporate pressure-mapping arrays and nurse-call integration for automated fall-alert systems. German university hospitals and US children's hospitals are adopting these digitized positioning platforms fastest.
- Home Care:Lightweight, collapsible platforms with battery backup systems serve post-acute monitoring beyond hospital walls. China's tier-one cities are seeing rapid channel expansion as pediatric specialty hospitals discharge patients earlier.
- Rehabilitation Centers:Intermediate motorization supports graduated mobility protocols for post-surgical recovery. These settings prioritize durability over advanced sensor integration.
- Long-Term Care:Basic electric or manual configurations serve stable chronic conditions. Procurement concentrates in consolidated nursing home chains seeking maintenance standardization.
Pediatric units retain the deepest installed base of premium platforms. Home care is gaining share fastest as reimbursement shifts toward community-based recovery models.
Material:
Supply concentration and regulatory chemistry determine viable material combinations for frame, surface, and cushioning components.
- Metal:Precision-machined aluminum extrusions and stainless steel tubing provide structural integrity for electric bed frames. Input price volatility from aluminum and steel markets compresses margin buffers for mid-tier suppliers.
- Plastic:High-impact polymers form siderail coatings and housing components requiring biocompatibility documentation under EU MDR. Extended clinical evidence packages are extending time-to-market by 8-14 months for platform refreshes.
- Foam:Mattress assemblies face reformulation pressure from EU F-Gas Regulation eliminating certain blowing agents. Manufacturers absorb compliance costs without corresponding price recovery mechanisms.
- Wood:Limited to decorative elements and non-clinical furniture in select premium configurations. Marginal presence in core bed platforms.
Metal dominates structural capacity across electric bed production. Foam is rotating up regulatory scrutiny as environmental chemistry standards tighten.
End User:
Customer scale and procurement sophistication create divergent channel economics, from consortium-negotiated hospital systems to fragmented home care agencies.
- Hospitals:Integrated delivery networks in California and Texas now control over half of pediatric bed procurement volume, demanding standardized fleet configurations. Vizient and Premier consortiums consolidate multi-year, multi-facility agreements that reshape manufacturer sales organizations.
- Clinics:Outpatient surgical and diagnostic settings require limited positioning capability. These buyers prioritize capital efficiency over advanced feature sets.
- Home Care Providers:Durable medical equipment distributors serve dispersed pediatric patients with rental and purchase options. Channel fragmentation complicates manufacturer direct relationships.
- Nursing Homes:Geriatric-pediatric hybrid facilities represent marginal demand concentration. Procurement aligns with adult long-term care specifications.
Hospitals command the deepest installed fleet across acute care networks. Home care providers are climbing the fastest as post-acute discharge protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Central European distribution for precision-machined aluminum bed frames, while the Port of Long Beach handles Pacific Rim component flows into North American assembly networks.
United States
Pediatric intensive care units in Texas and California are retrofitting siderail systems to meet FDA 21 CFR 880.5125 entrapment-risk standards. The Centers for Medicare & Medicaid Services reimbursement schedules favor electric bed platforms in acute settings. Houston's Texas Medical Center and Boston's Longwood Medical Area concentrate procurement volume for integrated delivery networks.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are expanding neonatal ICU capacity with embedded pressure-sensing arrays. The EU Medical Device Regulation and F-Gas Regulation jointly mandate biocompatibility documentation and foam-blowing agent reformulation. Berlin-Brandenburg hosts notified bodies that extend certification timelines for platform refreshes by 8-14 months.
China
Pediatric specialty hospitals in Beijing, Shanghai, and Guangzhou are multiplying rapidly, concentrating demand for domestic and imported bed platforms. The National Medical Products Administration now requires domestic clinical validation for imported pediatric beds, extending registration timelines. The Yangtze River Delta manufacturing corridor supplies precision-machined components for regional assembly.
Japan
Academic medical centers in Tokyo and Osaka are adopting digitized positioning platforms with automated turn-schedule alerts. The Ministry of Health, Labour and Welfare reimbursement frameworks prioritize integrated sensor convergence in pediatric wards. The Kansai region's medical device cluster supports localized maintenance networks for electric bed fleets.
United Kingdom
NHS England procurement frameworks are consolidating pediatric bed purchasing through regional supply chains. The Medicines and Healthcare products Regulatory Agency enforces MDR-aligned biocompatibility standards for patient-contact surfaces. London's Great Ormond Street Hospital and Manchester's Royal Manchester Children's Hospital anchor specification-setting for consortium-negotiated contracts.
Medical Pediatric Bed Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-machined aluminum extrusions and embedded control modules. The vendor base organizes into three tiers: multinational acute-care platforms with cross-selling capabilities, regional fabricators with direct hospital relationships, and emerging Asian suppliers competing on specification flexibility. Consolidation pressures intensify as procurement consortia demand standardized fleet configurations and multi-year service agreements.
Among European fabricators, Linet and Stiegelmeyer GmbH & Co. KG exemplify the regional direct-relationship archetype, while Stryker Corporation represents the installed-base cross-selling model. These three occupy positions that illustrate how geographic anchoring and sales organization structure determine access to large-volume contracts in North America and Western Europe.
| Leading Market Players |
|---|
| Linet |
| Stiegelmeyer GmbH & Co. KG |
| Stryker Corporation |
| Saikang Medical |
| Schröder Health Projects |
| Medline Industries Inc. |
| Paramount Bed Co., Ltd. |
| Savion Industries |
| Invacare Corporation |
| Others |
Pricing and Supply Chain Analysis
Aluminum and steel input volatility compresses margin buffers for mid-tier pediatric bed suppliers while simultaneously determining the spread between premium electric configurations and economy manual platforms. This commodity exposure forces manufacturers to absorb cost swings in price-sensitive developing markets or push specification upgrades in reimbursed acute-care settings where buyers exhibit lower elasticity.
Pricing Analysis
Volume-discount tiering structures dominate pediatric bed procurement through hospital consortiums like Vizient and Premier in the United States and state-level purchasing cooperatives in Germany. Three-tier pricing separates premium electric platforms with embedded sensor arrays from standard motorized configurations and economy manual crank beds. Cost compression in the manual tier is intensifying because Southeast Asian public tenders cap specifications without corresponding feature flexibility. Pediatric intensive care units in academic medical centers show the lowest price sensitivity due to bundled reimbursement schedules, while home care distributors face acute margin pressure from fragmented rental markets.
Supply Chain Analysis
Upstream feedstock flows for precision-machined aluminum extrusions and stainless steel tubing center on Germany's Ruhr industrial corridor and China's Yangtze River Delta manufacturing belt. Electric motor assemblies and embedded control modules draw from Japanese and South Korean component specialists. Single-source vulnerability concentrates in high-grade aluminum alloys for ICU-grade bed frames, where qualified smelter capacity spans fewer than six global facilities. Distribution runs through regional medical device distributors in North America and direct hospital relationships in Central Europe, with port consolidation at Hamburg and Long Beach anchoring intercontinental component flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical pediatric bed market demands substitution defense against refurbished equipment channels and rental-as-a-service models that threaten new-unit sales in post-acute settings. Incumbents must architect durable competitive moats before capital-light entrants capture home care migration.
For Market Incumbents: Build certification moats through accelerated MDR documentation and NMPA domestic clinical validation partnerships that extend lead times for followers. Capture backward integration into precision-machined aluminum extrusions to insulate margin buffers from commodity volatility. Lock multi-year fleet standardization agreements with integrated delivery networks in California and Texas before regional fabricators consolidate service capabilities.
For New Entrants and Emerging Players: Establish a beachhead in China's tier-one home care channel where pediatric specialty hospitals discharge patients earlier and rental infrastructure remains fragmented. Target lightweight collapsible platforms with battery backup systems for post-acute monitoring beyond hospital walls. Pursue specification flexibility in Asian public tenders where incumbent rigidity creates procurement gaps.
For Investors and Strategic Acquirers: EU MDR enforcement reshapes the acquisition landscape by privileging notified-body relationships and existing certificate holders over technology assets alone. Long-term viability hinges on software-enabled service revenue streams from predictive fall-alert systems and staffing optimization data feeds. Monitor FDA 21 CFR 880.5125 entrapment-risk compliance deadlines as inflection indicators for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certificate Acceleration | Existing notified-body relationships capture share from competitors navigating 8-14 month extension timelines. |
| NMPA Domestic Validation Partnership | Local testing compresses registration timelines for foreign brands defending position against regional competitors. |
| Sensor Convergence Development | Pressure-mapping arrays integrated with nurse-call infrastructure differentiate premium offerings in pediatric ICUs. |
| Home Care Channel Expansion | Lightweight collapsible platforms with battery backup capture post-acute discharge migration beyond hospital walls. |
| Consortium Contract Standardization | Multi-year fleet agreements with Vizient and Premier reshape sales organizations around volume-discount structures. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and pediatric intensive care clinicians and refined through secondary validation against FDA 510(k) filings, EU MDR notified-body documentation, CMS Medicare reimbursement schedules, and hospital procurement database extracts. Bottom-up demand modeling across product type, care setting, material composition, and end-user channel triangulated against top-down macroeconomic indicators.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning motorization tier, clinical intensity setting, frame material chemistry, and customer procurement sophistication. CAGRs were derived from installed base replacement cycles, neonatal ICU expansion pipelines, and home care channel penetration curves. Forecast inputs incorporated aluminum and steel price trajectory assumptions alongside regulatory compliance timeline shifts.
Stress conditions across commodity input volatility, NMPA registration timeline extension, and consortium purchasing concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement schedule stability and entrapment-risk mandate enforcement consistency. Cross-checking against GPO contract award databases and notified-body certificate registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Auditory Brainstem Response Analyzers Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
US Radiotherapy Market