
 Laser Resurfacing Market | 2026-2036
Laser Resurfacing Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Resurfacing Market Outlook
Modular platform bundling is repositioning capital equipment procurement across aesthetic practices, with buyers favoring systems that combine CO2, erbium, and radiofrequency modalities in a single footprint. Alma Lasers leverages its multi-technology portfolio to anchor premium positioning in dermatology clinic chains. Lumenis sustains technology leadership through its fractional and CO2 laser specialization. Cynosure competes aggressively on channel control, building direct service networks that lock in recurring revenue from installed bases.
Laser resurfacing employs concentrated coherent light to selectively ablate or thermally remodel epidermal and dermal tissue, with wavelengths typically ranging from 10,600 nm for CO2 systems to 2,940 nm for erbium:YAG platforms, delivering controlled microthermal zones that trigger collagen neogenesis and tissue tightening. Fractional laser technology dominates current revenue pools due to its balance of efficacy and reduced downtime, while hybrid ablative-non-ablative systems represent the fastest-expanding configuration as manufacturers integrate multiple energy delivery modes. Medical spas capture disproportionate growth velocity among end users, capitalizing on consumer willingness to pay out-of-pocket for cosmetic procedures outside traditional hospital billing frameworks.
FDA 510(k) premarket notification requirements govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for laser systems marketed in Europe, extending certification timelines and elevating compliance costs. The EU AI Act introduces additional scrutiny for devices incorporating automated skin analysis or treatment planning algorithms, creating new regulatory boundaries for next-generation platforms. Stakeholders must monitor evolving reimbursement codes for aesthetic versus medically indicated procedures, as payer policy directly shapes addressable demand across hospital and clinic settings.
Market Dynamics
Modular platform architecture is compressing procurement cycles across aesthetic practices, as single-footprint systems displace standalone devices and force manufacturers to bundle CO2, erbium, and radiofrequency modalities under unified control interfaces.
Growth Catalysts
- FDA 510(k) Pathway Compression:Streamlined premarket notification for hybrid laser platforms accelerates commercialization timelines for device manufacturers targeting outpatient dermatology settings.
- Medical Spa Network Expansion:Capital expenditure from cosmetic surgery chains and medical spa franchises sustains recurring demand for multi-modality systems with service lock-in provisions.
- Fractional Technology Maturation:Microthermal zone delivery protocols balance clinical efficacy against reduced patient downtime, expanding addressable candidate pools beyond traditional ablative candidates.
Market Restraints
- EU MDR Compliance Burden:Stricter clinical evidence requirements for laser systems extend certification timelines and elevate compliance costs for European market entry.
- Input Concentration Risk:Specialized optical components and precision-manufactured laser rods concentrate supply among limited German and Japanese component suppliers.
- Substitute Modalality Threat:Radiofrequency microneedling and high-intensity focused ultrasound platforms capture price-sensitive segments seeking non-laser tissue remodeling.
Strategic Opportunities
- AI-Enabled Treatment Planning:Automated skin analysis algorithms integrated with laser platforms create differentiation, though EU AI Act scrutiny imposes additional validation requirements for European deployment.
- Men's Aesthetic Segment:Underpenetrated male patient demographics for skin rejuvenation procedures represent expansion potential for practices adapting marketing and treatment protocols.
- Subscription Service Models:Equipment-as-a-service arrangements with per-treatment revenue sharing restructure capital deployment for mid-scale dermatology clinics.
Industry Challenges
- Laser Safety Officer Certification:Qualified medical laser operator scarcity constrains clinic expansion velocity and creates wage inflation for certified technicians.
- Legacy System Integration:Hybrid platform adoption requires workflow reconfiguration and staff retraining, generating implementation friction and temporary productivity degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Resurfacing Market |
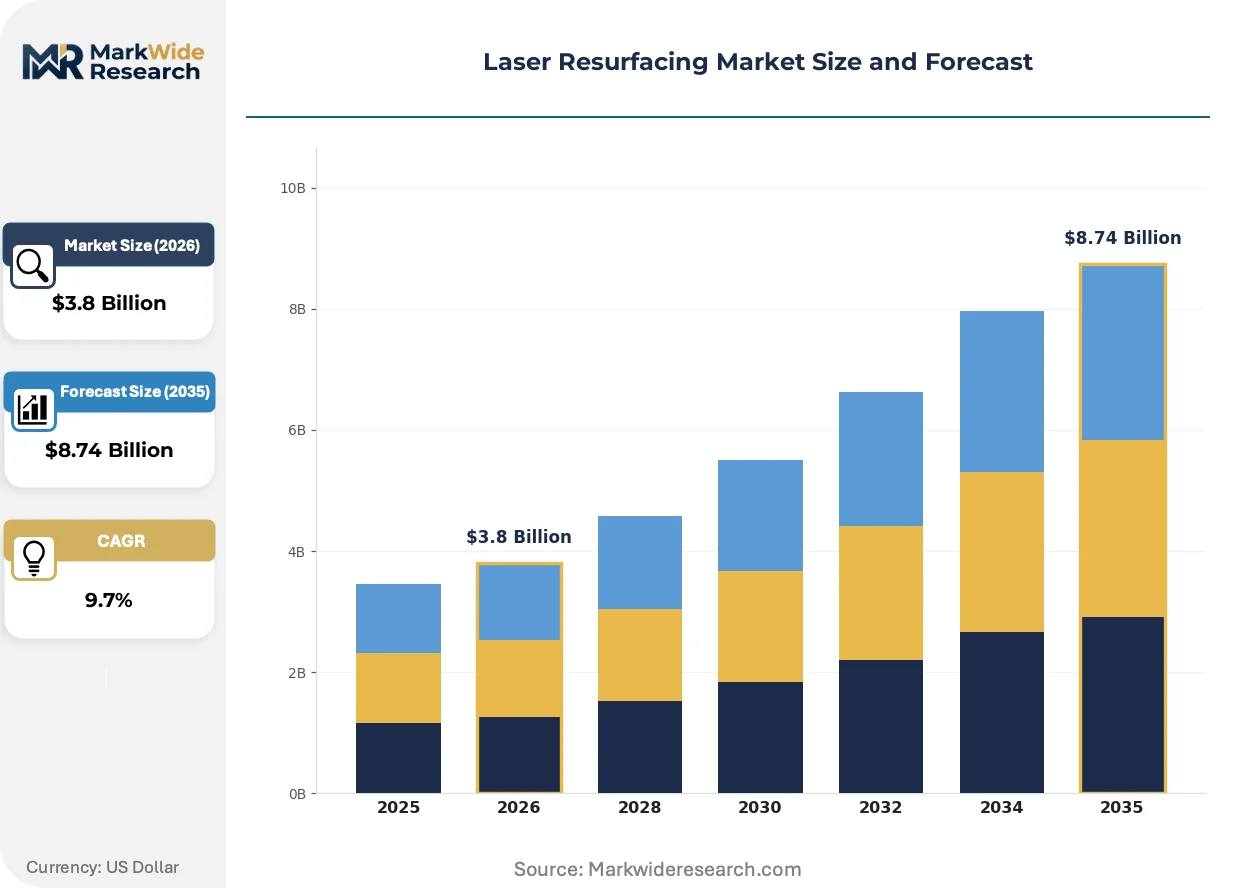
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Laser, Erbium Laser, Fractional Laser, Pulsed Dye Laser Technology: Non-Ablative, Ablative, Hybrid, Radiofrequency End User: Dermatology Clinics, Ambulatory Surgical Centers, Hospitals, Medical Spas Treatment Type: Acne Scars, Wrinkles, Sun Damage, Hyperpigmentation |
| Companies Covered | Lumenis, Cynosure, Alma Lasers, Candela Medical, Sciton, Cutera, Lutronic, Fotona, Quanta System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Resurfacing Market Strategic Shifts
Device architecture is pivoting from discrete modalities toward unified energy platforms, while regulatory frameworks evolve to address algorithmic treatment assistance and stricter clinical validation requirements.
Hybrid ablative-non-ablative systems are converging with radiofrequency delivery modules to enable sequential or simultaneous tissue treatment within single sessions. Medical spa chains and cosmetic surgery networks are standardizing procurement around these unified platforms to maximize utilization rates per square foot. This convergence is compressing the installed base of standalone devices and forcing pure-play manufacturers to partner or acquire complementary energy technologies.
The EU AI Act introduces algorithmic accountability requirements for laser platforms incorporating automated skin analysis or treatment parameter recommendation engines. Device manufacturers must now document training data provenance and establish human oversight protocols for AI-assisted treatment planning. European dermatology clinics face extended validation timelines for next-generation platforms, creating temporary competitive advantage for systems already holding MDR certification without algorithmic components.
After-sales service unbundling is fragmenting traditional vendor relationships, as third-party biomedical engineering firms capture maintenance contracts for mature laser platforms. Independent service organizations in the United States and Germany now hold ISO 13485 certification for laser repair, eroding manufacturer recurring revenue from installed bases. This disintermediation is most advanced in California and Texas, where medical spa density supports independent technician specialization.
Laser Resurfacing Market Segmentation
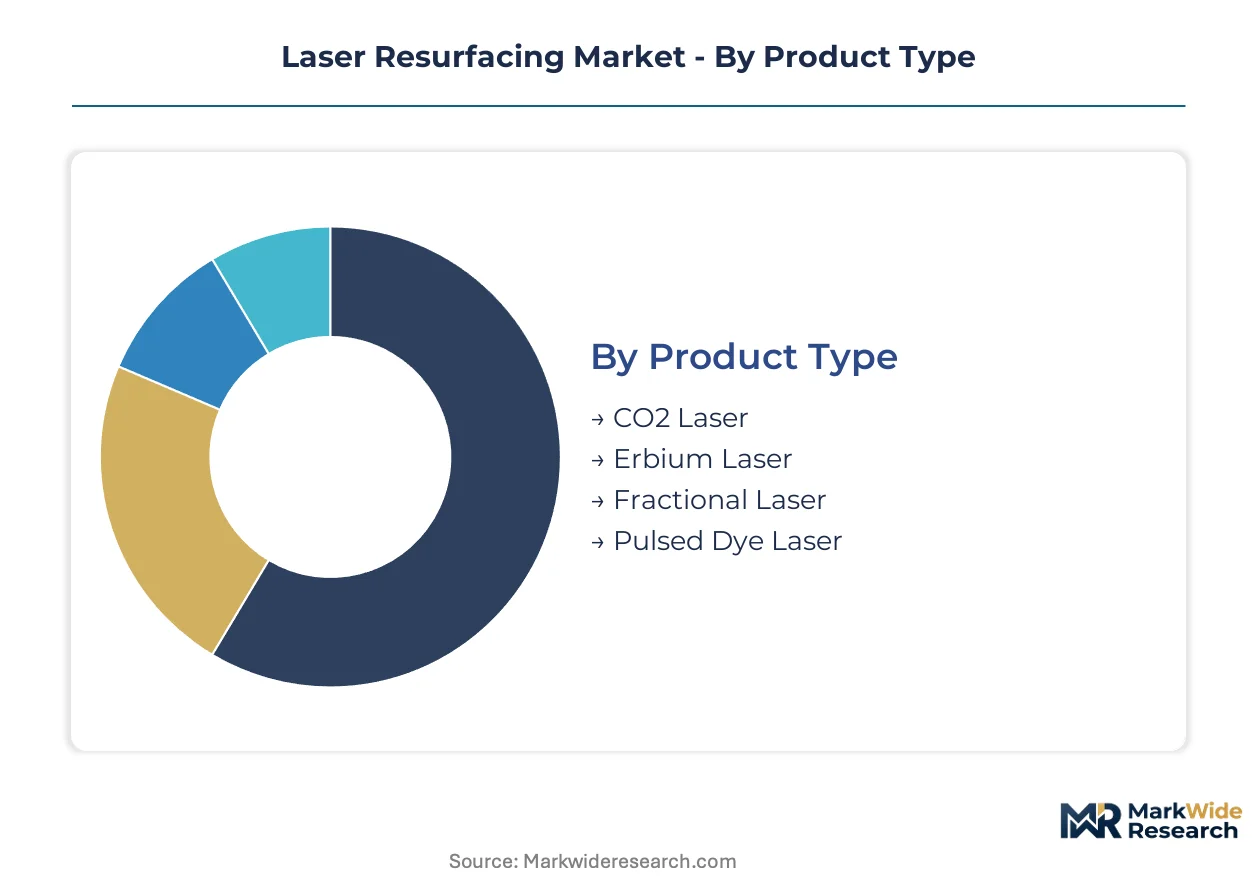
Laser resurfacing equipment segments by energy delivery mechanism, clinical setting, and anatomical indication. Procurement patterns diverge sharply between high-volume medical spa chains and precision-focused hospital dermatology departments.
Product Type:
Volume concentration favors fractional platforms, while premium positioning attaches to tunable ablative systems with advanced thermal control.
- CO2 Laser:These platforms deliver 10,600 nm wavelength energy for deep dermal remodeling and tissue ablation. Demand clusters in United States cosmetic surgery networks seeking maximum single-session efficacy for severe photodamage. Thermal injury risk and extended recovery periods constrain expansion into outpatient medical spa settings.
- Fractional Laser:Microthermal zone technology creates microscopic treatment columns surrounded by intact tissue. Medical spa chains in Texas and California deploy these systems for high-throughput skin rejuvenation with reduced downtime protocols. The balance of clinical results and patient convenience drives replacement cycles for older ablative installations.
- Erbium Laser:2,940 nm wavelength systems enable precise epidermal ablation with minimal thermal diffusion. Precision dermatology practices favor erbium platforms for periorbital and neck applications.
- Pulsed Dye Laser:Vascular-targeting 585-595 nm systems address erythema and vascular lesions rather than textural resurfacing. Pediatric and vascular dermatology specialists maintain niche demand.
Mature deployment sits with CO2 Laser. Newer deployment is concentrated in Fractional Laser.
Technology:
Application requirements dictate energy delivery selection, with cost tier separating capital-intensive hybrid platforms from single-modality alternatives.
- Hybrid:Sequential or simultaneous ablative-non-ablative energy delivery enables customized treatment protocols within single sessions. United States medical spa franchises standardize procurement around these unified platforms to maximize utilization per treatment room. FDA 510(k) pathway compression accelerates manufacturer commercialization timelines for new hybrid configurations.
- Non-Ablative:Subsurface heating without epidermal disruption targets collagen remodeling with minimal recovery. Urban medical spas in New York and Miami deploy these systems for maintenance-oriented patient protocols.
- Ablative:Complete epidermal removal with controlled dermal injury delivers maximum single-session correction. Academic medical centers retain ablative capacity for severe scar revision cases.
- Radiofrequency:Electrical energy delivery independent of chromophore absorption complements laser modalities for diverse skin types. Integration into hybrid platforms is climbing the fastest among technology configurations.
Established clinical workflows center on Ablative. Emerging adoption concentrates in Hybrid.
End User:
Customer type determines capital deployment scale, with medical spa networks driving volume and hospital systems prioritizing clinical versatility.
- Medical Spas:Consumer-facing aesthetic facilities operate outside traditional hospital billing frameworks. Chains across Florida and Arizona generate recurring demand for multi-modality systems with service lock-in provisions. Out-of-pocket payment structures enable rapid technology refresh cycles compared to capital-constrained institutional purchasers.
- Dermatology Clinics:Physician-directed facilities balance cosmetic and medically indicated procedures. Fractional laser adoption is expanding fastest among dermatology clinic chains seeking outpatient procedure volume.
- Hospitals:Academic and community hospital systems maintain laser capacity for scar revision and pre-cancerous lesion treatment. Reimbursement complexity constrains aesthetic procedure expansion.
- Ambulatory Surgical Centers:Same-day surgical facilities deploy laser platforms for procedural efficiency. Joint venture structures with cosmetic surgeons concentrate demand in metropolitan markets.
Traditional infrastructure investment sits with Hospitals. Accelerated capital expenditure is concentrated in Medical Spas.
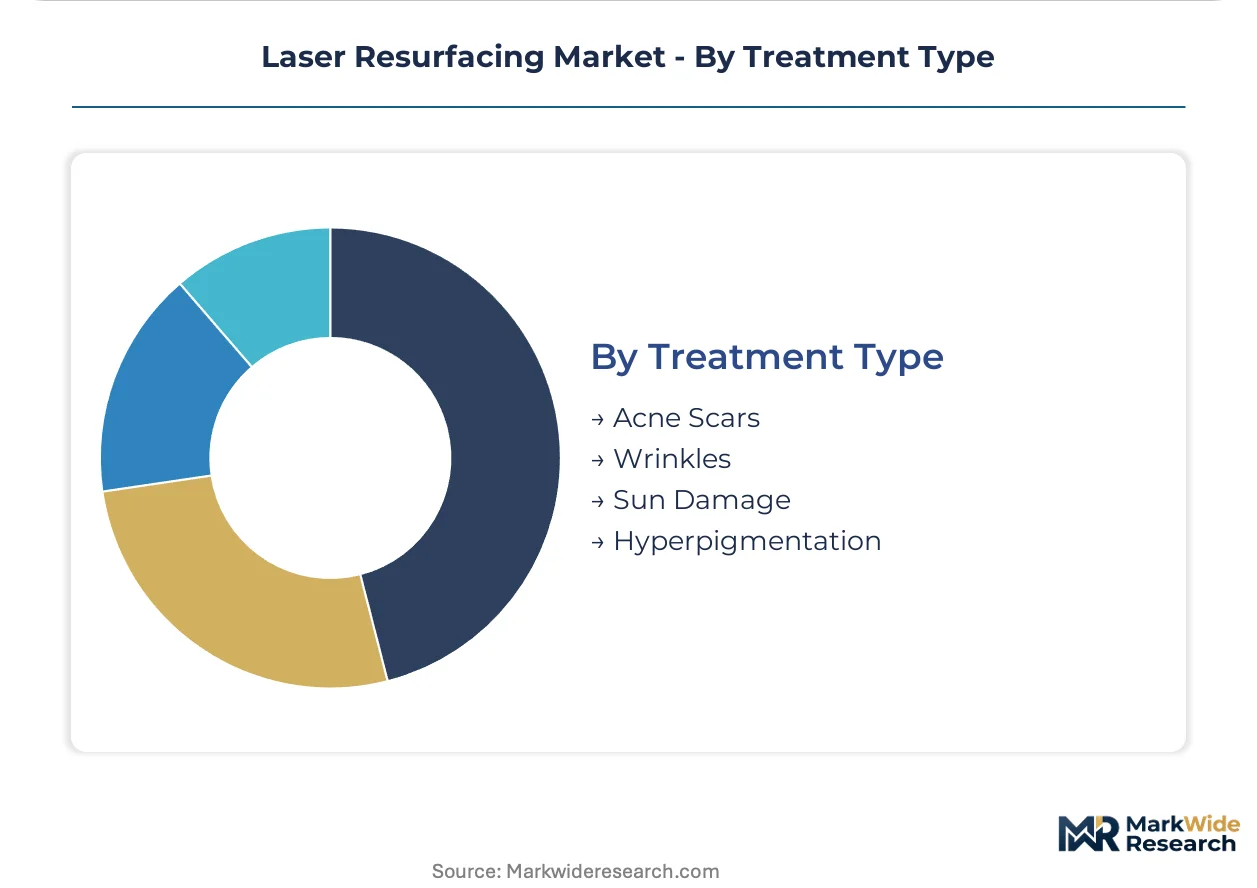
Treatment Type:
Anatomical indication drives wavelength and energy parameter selection, with margin differentiation between cosmetic and reconstructive applications.
- Wrinkles:Rhytid correction represents the largest addressable procedure category across all patient demographics. CO2 and fractional platforms compete for perioral and periorbital applications in United States coastal markets.
- Acne Scars:Atrophic and hypertrophic scar revision requires precise depth control and multiple treatment sessions. Subcision combination protocols are gaining share fastest among acne scar treatment approaches.
- Sun Damage:Photorejuvenation for actinic keratosis and dyschromia spans medical and cosmetic indications. Medicare reimbursement for actinic damage creates hybrid payment opportunities.
- Hyperpigmentation:Melasma and post-inflammatory hyperpigmentation present therapeutic challenges requiring conservative parameter selection. Fitzpatrick skin type IV-VI protocols demand specialized training and device calibration.
Longstanding procedural volume sits with Wrinkles. Emerging treatment expansion is concentrated in Acne Scars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Israel, Germany, and the United States, while procedural demand clusters in North American and European urban medical corridors. Consumption patterns diverge sharply between reimbursed hospital settings and cash-pay aesthetic facilities.
United States
Medical spa chains in Texas and Florida drive recurring capital expenditure on multi-modality systems with service lock-in provisions. FDA 510(k) premarket notification pathways compress commercialization timelines for hybrid laser platforms. Los Angeles and Miami anchor the highest density of fractional laser deployments for outpatient skin rejuvenation.
Germany
Precision optics suppliers in Jena and Munich concentrate global supply of specialized laser rods and beam delivery components. EU Medical Device Regulation imposes stricter clinical evidence standards, extending certification timelines for new platform introductions. Frankfurt and Hamburg host the largest dermatology clinic chains adopting hybrid ablative-non-ablative configurations.
Israel
Device manufacturers leverage deep photonics expertise to anchor premium positioning in fractional and CO2 laser segments. National export credit frameworks support international market penetration for capital equipment. Tel Aviv and Haifa concentrate R&D operations for next-generation hybrid platforms.
South Korea
Consumer beauty culture sustains high per-capita procedural volume for skin rejuvenation and acne scar revision. MFDS regulatory pathways align with international standards, enabling rapid technology transfer from Western manufacturers. Seoul Capital Area medical districts standardize procurement around unified energy platforms.
Brazil
ANVISA certification requirements create extended validation timelines for imported laser systems, favoring established manufacturers with regulatory infrastructure. São Paulo and Rio de Janeiro concentrate private dermatology practice networks investing in outpatient aesthetic capacity. Out-of-pocket payment structures enable faster technology refresh cycles than institutional purchasers.
Laser Resurfacing Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated vendor landscape. Market structure tilts toward consolidation as modular platform requirements force standalone manufacturers toward partnership or acquisition. Three archetypes dominate: multi-energy portfolio holders, fractional laser specialists, and radiofrequency-integrated hybrid developers. M&A activity concentrates on optical component suppliers and AI-enabled treatment planning capabilities.
Within the multi-technology portfolio tier, Lumenis and Alma Lasers exemplify diversified platform strategies spanning CO2, erbium, and radiofrequency modalities. Cynosure occupies a position emphasizing channel control through direct service networks. These three companies represent contrasting approaches to recurring revenue capture—through technology breadth, premium positioning, or installed-base lock-in.
| Leading Market Players |
|---|
| Lumenis |
| Cynosure |
| Alma Lasers |
| Candela Medical |
| Sciton |
| Cutera |
| Lutronic |
| Fotona |
| Quanta System |
| Others |
Value Chain & Pricing Dynamics
Certified laser safety officer scarcity in Israel and Germany widens pricing-tier spreads between premium hybrid platforms and economy fractional systems, as labor-cost differentials compound with optical component sourcing premiums to stratify procurement budgets across medical spa networks.
Pricing Analysis
Margin tightening in economy-tier fractional systems reflects third-party service organization encroachment on maintenance revenue. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared hybrid platforms from CE-marked single-modality devices and refurbished legacy installations. Cost-down pressure on standard-tier configurations accelerates because medical spa chains negotiate volume-based service bundling. Hospital dermatology departments exhibit lowest price sensitivity due to reimbursement complexity, while independent cosmetic surgery clinics face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from United States medical spa franchises, while specialized distributors serve mid-scale dermatology clinics in Germany and South Korea. Precision-manufactured laser rods and optical components concentrate supply among German and Japanese suppliers. Yttrium-aluminum-garnet crystals, germanium optics, and precision-machined handpieces anchor raw material dependencies. Single-source vulnerability for erbium-doped laser rods creates procurement risk. Distribution runs through manufacturer-direct service networks with ISO 13485-certified third-party repair alternatives in California and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
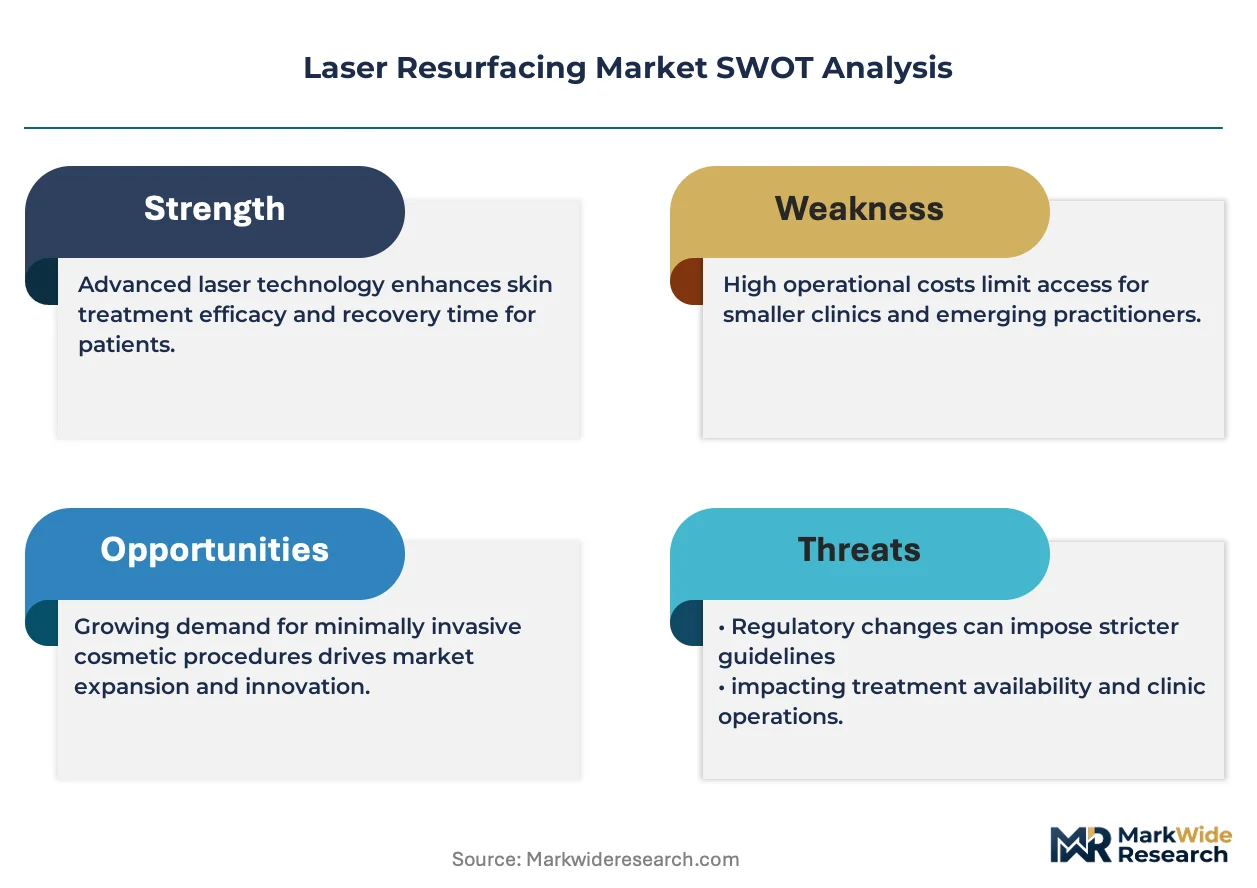
EU MDR compliance creates a cost-of-compliance moat for established manufacturers with clinical evidence infrastructure, elevating barrier-to-entry thresholds for new platform introductions and consolidating advantage around MDR-certified installed bases.
For Market Incumbents: Anchor technology leadership through backward integration into precision optics supply, securing captive supply of laser rods from German component specialists while building direct service networks that lock in recurring revenue against third-party biomedical engineering disintermediation. Radiofrequency microneedling substitution threat demands defensive patent positioning around hybrid energy delivery protocols. For New Entrants and Emerging Players: Begin with AI-enabled treatment planning capabilities targeting European dermatology clinics facing EU AI Act validation delays for algorithmic platforms, exploiting temporary competitive windows for systems without automated components. Men's aesthetic segments remain underpenetrated white-space targets. Subscription service models with per-treatment revenue sharing offer differentiated go-to-market positioning against capital-intensive procurement. For Investors and Strategic Acquirers: The window for entry favors optical component suppliers with ISO 13485 certification and AI-enabled software companions, as modular platform convergence forces technology bundling. Long-term viability centers on manufacturers with MDR certification and hybrid platform pipelines. Watch FDA 510(k) clearance velocity for hybrid configurations as inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Stricter clinical evidence requirements extend timelines but create compliance moats for prepared manufacturers. |
| Hybrid Platform Integration | Unified CO2-erbium-RF configurations maximize treatment room utilization for medical spa chains. |
| AI Companion Development | Automated skin analysis algorithms trigger EU AI Act scrutiny requiring validation investment. |
| Optical Component Backward Integration | Captive supply of precision laser rods from German suppliers mitigates input concentration risk. |
| Subscription Service Model | Equipment-as-a-service arrangements restructure capital deployment for mid-scale dermatology clinics. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across clinicians, hospital purchasing committees, biomedical engineers, GPO contracts managers, and medical spa operations directors. FDA 510(k) premarket notification databases, EU MDR certification registries, CMS Medicare reimbursement files, and import-export customs declarations supplied quantitative validation. Bottom-up equipment shipment analysis triangulated against top-down procedural volume estimates from dermatology clinic chains.
Granularity-level modeling captured product type, technology configuration, end-user setting, and treatment indication dimensions across the analysis window. CAGRs derived from equipment replacement cycle analysis, medical spa network expansion rates, and technology adoption S-curves. Procedural volume inputs incorporated Medicare reimbursement code utilization and out-of-pocket aesthetic procedure surveys.
Underlying measurement precision varies by segment; fractional laser deployment data carry tighter precision than emerging hybrid platform estimates due to reporting lag in medical spa procurement. Forecasts reflect assumptions regarding FDA clearance timelines, EU MDR certification velocity, and medical spa capital expenditure continuity. Periodic stress-testing of base assumptions is recommended against regulatory pathway delays and substitute modality competitive pressure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Laryngoscopes Market
Medical Devices
Cryoablation System Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Cytology Brush Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Midline Catheters Market