
 Catheter Securement Devices Market | 2026-2036
Catheter Securement Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Catheter Securement Devices Market Intelligence
The push for phthalate-free and PVC-free medical consumables, aligned with regulations like the EU's REACH, is broadening material science requirements for catheter securement devices. 3M leverages its portfolio in medical adhesives and polymer science to meet these specifications. BD competes on integrating securement products with its vascular access and infusion therapy systems. ConvaTec incorporates advanced wound care technologies into its adhesive offerings.
Catheter securement devices are medical appliances designed to hold catheters, tubes, or lines in place on a patient's body. They utilize mechanisms like sterile adhesives, sutures, or subcutaneous anchors to prevent catheter migration, dislodgement, and associated complications. Adhesive securement products command the largest market share due to their ease of use, while subcutaneous anchoring systems represent a high-growth, higher-margin category. Demand for devices securing intravenous catheters remains dominant, driven by high procedural volumes in hospital end-user settings.
Market access is governed by stringent regulatory approvals from bodies such as the US FDA, the European Union's MDR framework, and Japan's PMDA. These regulations mandate extensive clinical data on safety, efficacy, and biocompatibility, particularly concerning skin irritation and infection prevention. Future competitive advantage will hinge on demonstrating quantifiable reductions in catheter-related bloodstream infections and not just mechanical stability.
Market Dynamics
The central structural force shaping the market is the heightened focus on preventing hospital-acquired infections. Mandates from bodies like the CDC and ECDC compel healthcare providers to adopt advanced securement solutions that offer superior clinical outcomes over traditional methods.
Growth Catalysts
- EU MDR Compliance:The European Union's Medical Device Regulation (MDR) requires more extensive clinical evidence on device safety and performance, favoring manufacturers with robust data on infection reduction and skin integrity.
- Ambulatory Surgical Centers:The rising procedural volume in ambulatory surgical centers, particularly in the United States and Germany, creates demand for easy-to-use, single-use devices that support rapid patient turnover and minimize complication risks.
- Advanced Adhesives:Development of skin-friendly, breathable silicone and acrylic adhesives reduces the incidence of medical adhesive-related skin injuries (MARSI), encouraging use in patients with sensitive skin and for long-term home care applications.
Market Restraints
- Reimbursement Pressures:Cost-containment measures by public and private payers, including Medicare in the US, can limit the adoption of higher-priced, technologically advanced devices like subcutaneous anchoring systems in favor of lower-cost adhesive products.
- Material Biocompatibility:Concerns over skin sensitization and irritation from certain adhesives or plastic components create a restraint, especially for long-term catheterization, requiring extensive biocompatibility testing under frameworks like ISO 10993.
- Suture-Based Alternatives:The continued, albeit declining, use of sutures for catheter securement in some clinical settings, due to physician preference and low direct cost, represents a persistent source of substitution threat.
Strategic Opportunities
- Pediatric and Neonatal Niches:Developing securement devices specifically scaled and designed for neonatal and pediatric patients, featuring gentler adhesives and smaller form factors, addresses a significant unmet clinical need.
- Latin American Expansion:Markets such as Brazil and Mexico are investing in healthcare infrastructure modernization, creating new opportunities for market entry as hospitals upgrade their standards of care and infection control protocols.
- Smart Device Integration:Incorporating sensors to detect moisture, tension, or early signs of dislodgement can transform a passive device into an active monitoring tool, creating high-value data for clinical decision support systems.
Industry Challenges
- Clinician Application Training:Ensuring consistent and correct application of securement devices by a diverse and rotating hospital staff is a major operational challenge, as improper use can negate the device's benefits and cause skin damage.
- Sterilization Compatibility:Material selection is constrained by the need to withstand sterilization methods like ethylene oxide (EtO) or gamma radiation without degrading the adhesive's performance or leaching harmful substances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catheter Securement Devices Market |
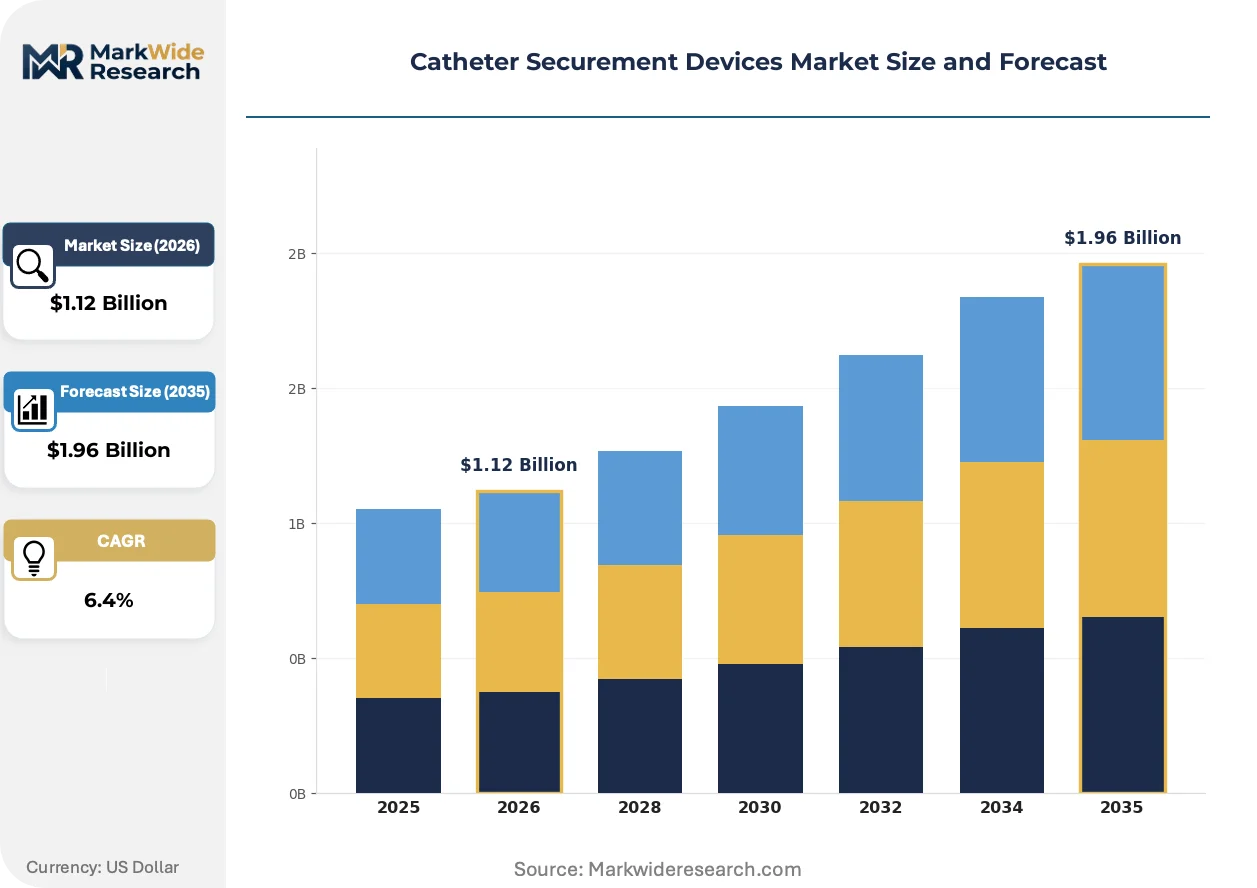
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Securement, Suture-Based Securement, Subcutaneous Anchoring, Stabilization Devices, Silicone Holsters Application: Intravenous Catheters, Epidural Catheters, Urinary Catheters, Peripherally Inserted Central Catheters, Hemodialysis Catheters End User: Hospitals, Ambulatory Surgical Centers, Long-Term Care Facilities, Specialty Clinics, Home Healthcare Providers Deployment: Disposable Devices, Reusable Devices, Single-Use, Multi-Use, Sterile Packaging |
| Companies Covered | 3M, B. Braun Melsungen AG, BD, C. R. Bard, Cardinal Health, ConvaTec, Merit Medical Systems, Baxter, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catheter Securement Devices Market Strategic Shifts & Innovations
Material science innovation is redefining the value proposition of catheter securement devices. The market is evolving from products that offer only mechanical stability to integrated systems that actively contribute to patient safety and infection prevention, meeting stricter clinical standards.
Antimicrobial-infused adhesives and polymer films are designed to inhibit microbial growth at the catheter insertion site. High-risk hospital units, including intensive care and oncology wards, are progressively adopting these technologies to combat catheter-related infections. This active infection-control capability is overtaking the purely passive mechanical stability that defined previous generations of securement products.
The US CDC guidelines for preventing intravascular catheter-related infections serve as a powerful policy driver. These recommendations compel hospitals to adopt superior securement technologies over basic tape or sutures to reduce complication rates and associated costs. Consequently, hospital infection control committees and value analysis teams now scrutinize products for clinical evidence of efficacy in reducing these adverse events.
A shift toward value-based purchasing is causing hospital systems to evaluate securement devices based on total cost of care, not just unit price. This model disrupts traditional volume-based procurement, favoring devices that demonstrably reduce costly complications like catheter-related bloodstream infections (CRBSIs). This trend is most prominent within large Integrated Delivery Networks (IDNs) in the United States and major hospital purchasing groups in Germany.
Catheter Securement Devices Market Segmentation
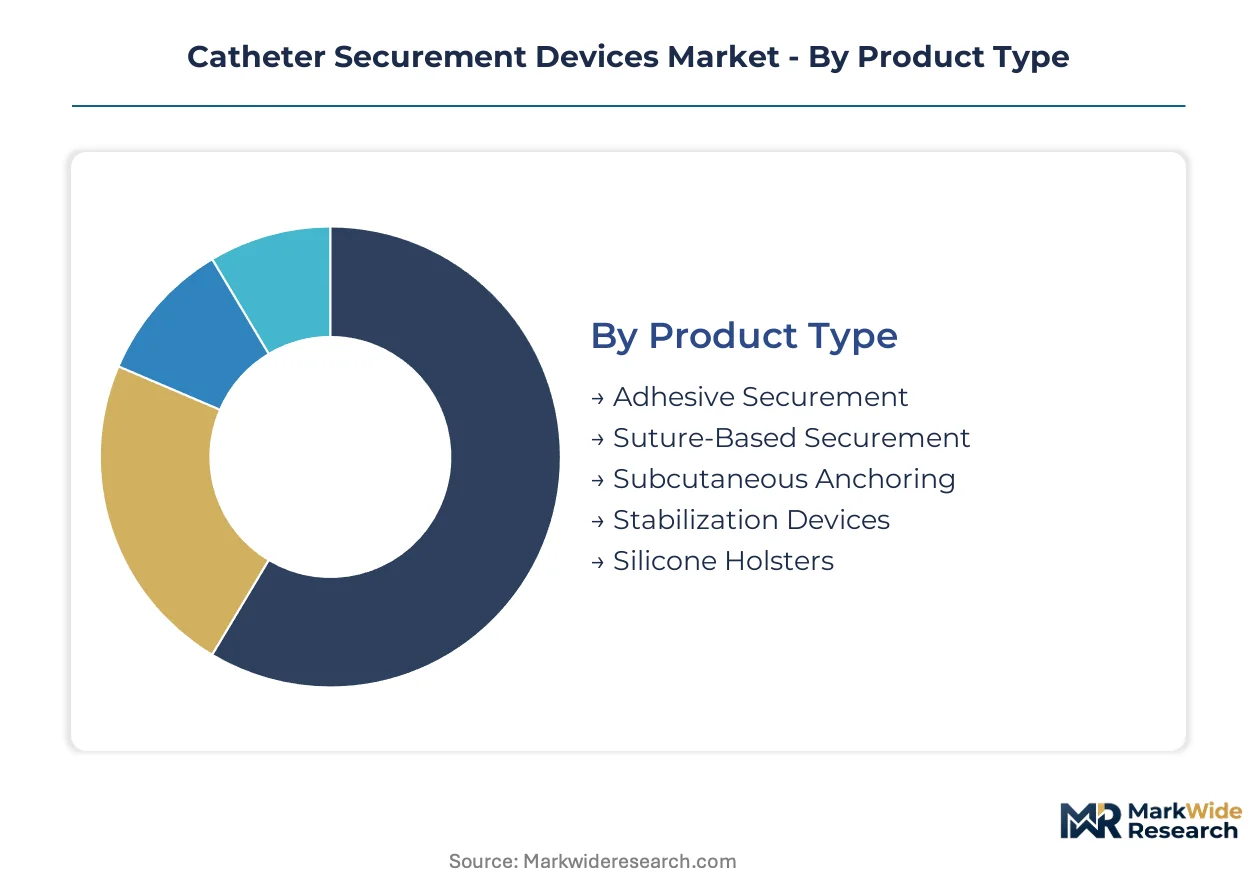
The Catheter Securement Devices Market exhibits distinct segmentation based on product characteristics, clinical application, end-user settings, and deployment models. Understanding these segments is crucial for manufacturers to align product development with specific clinical needs and for healthcare providers to optimize procurement strategies for patient safety and cost-effectiveness.
Product Type:
The capital intensity of manufacturing processes significantly influences competitive dynamics within this product category, particularly for advanced materials and complex designs.
- Adhesive Securement:These devices employ skin-friendly adhesives, often silicone or acrylic-based, to affix catheters externally to the patient's skin. They command the largest market share due to their non-invasive nature and ease of application in diverse clinical settings.
- Subcutaneous Anchoring:These systems involve a small, bio-compatible anchor inserted under the skin, providing robust internal securement for long-term catheterization. Demand is concentrating in high-risk patient populations requiring central venous access, driven by superior stability and infection prevention.
- Suture-Based Securement:This traditional method uses sutures to directly attach the catheter hub to the skin, offering strong mechanical stability.
- Stabilization Devices:Products in this segment provide external support and strain relief for catheters, preventing accidental dislodgement.
- Silicone Holsters:These devices are designed to cradle and secure catheter hubs or tubing, often used for patient comfort and mobility.
Most installed capacity flows through Adhesive Securement products. Expansion is steepest in Subcutaneous Anchoring systems.
Application:
Procedural volumes and the criticality of the catheter's function dictate the demand patterns across various applications for securement devices.
- Intravenous Catheters:This segment includes peripheral and central venous catheters, which are widely used for fluid administration, medication delivery, and blood sampling. High procedural volumes in hospital end-user settings drive dominant demand for securement solutions.
- Peripherally Inserted Central Catheters:PICC lines require securement for extended periods, often weeks or months, for long-term intravenous therapy or nutrition. Superior stability and infection control are paramount for these devices, especially in oncology and critical care.
- Epidural Catheters:These catheters deliver analgesia or anesthesia into the epidural space, requiring precise and secure placement to prevent migration.
- Urinary Catheters:Securement devices for urinary catheters prevent dislodgement and reduce the risk of catheter-associated urinary tract infections.
- Hemodialysis Catheters:Securement is vital for hemodialysis catheters, which are large-bore devices used for renal replacement therapy, ensuring patient safety during treatment.
High procedural volumes characterize demand in Intravenous Catheters. Innovation targets Peripherally Inserted Central Catheters for improved patient outcomes.
End User:
The type of healthcare facility and its operational model significantly influence the selection criteria and procurement of catheter securement devices.
- Hospitals:These institutions represent the primary end-users, driven by high patient acuity, diverse procedural needs, and stringent infection control protocols. Large hospital systems prioritize devices with proven clinical efficacy and cost-efficiency.
- Home Healthcare Providers:This segment encompasses services delivering medical care in patients' homes, requiring user-friendly and reliable securement devices for long-term management of chronic conditions. Rising utilization in home care settings drives demand.
- Ambulatory Surgical Centers:ASCs focus on outpatient procedures, demanding efficient, single-use securement solutions that support rapid patient turnover.
- Long-Term Care Facilities:These facilities require securement devices for residents with chronic illnesses, emphasizing comfort and ease of maintenance.
- Specialty Clinics:Clinics focusing on specific medical areas like oncology or pain management utilize securement devices tailored to their specialized catheter types.
Large institutional purchasers like Hospitals influence procurement standards. Emerging care models drive demand from Home Healthcare Providers.
Deployment:
Margin structures for securement devices are often influenced by the deployment model, with single-use, sterile products typically commanding higher pricing due to safety and convenience factors.
- Disposable Devices:These products are designed for single patient use and subsequent disposal, minimizing cross-contamination risks and simplifying hospital workflows. This category includes a broad range of adhesive and mechanical securement products.
- Single-Use:This sub-segment emphasizes products packaged for one-time application per patient, directly supporting infection prevention guidelines and reducing reprocessing needs. Demand is particularly high in ambulatory surgical centers for rapid patient turnover.
- Reusable Devices:These devices are designed for multiple uses after proper cleaning and sterilization, offering potential cost savings in some limited applications.
- Multi-Use:This refers to products designed for repeated application on the same patient over a defined period, such as certain stabilization devices.
- Sterile Packaging:This describes the packaging standard for securement devices, ensuring aseptic delivery to the point of care and compliance with regulatory requirements.
Infection prevention protocols favor Disposable Devices. Cost-efficiency considerations influence Reusable Devices adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The catheter securement devices industry scaled significantly in developed healthcare markets. Early innovations in medical device technology and infection control protocols originated in nations with advanced medical infrastructure. These regions continue to drive demand for superior securement solutions.
United States
The United States experiences high procedural volumes for intravenous catheters and a strong focus on reducing hospital-acquired infections. The US FDA mandates extensive clinical data for new device approvals, particularly concerning safety and efficacy. Major medical device hubs in California and Massachusetts drive innovation in advanced adhesive technologies and subcutaneous anchoring systems.
Germany
Germany's market sees rising procedural volumes in ambulatory surgical centers and stringent infection control guidelines. The EU's MDR framework requires robust clinical evidence for device safety and performance. Stuttgart and Munich host significant medical technology clusters focused on precision manufacturing and biocompatible materials for securement solutions.
Japan
An aging population in Japan necessitates long-term catheterization solutions and advanced home care devices. Japan's PMDA ensures rigorous safety and efficacy standards for medical appliances, influencing product design. The Kansai region, including Osaka, fosters research and development in innovative, skin-friendly securement materials for sensitive patients.
United Kingdom
National Health Service (NHS) initiatives in the United Kingdom prioritize infection prevention and cost-effective patient care. UK regulatory bodies align with European standards, emphasizing clinical outcomes and device performance data. London and Cambridge serve as centers for medical research and development, attracting investment in novel securement technologies.
Brazil
Healthcare infrastructure modernization and expanding access to medical services increase catheterization procedures across Brazil. ANVISA, the national health surveillance agency, is strengthening oversight for imported and domestically produced medical devices. São Paulo and Rio de Janeiro are emerging hubs for medical technology adoption, driven by public and private hospital investments.
Catheter Securement Devices Market Key Industry Players
Capital-heavy producers, often those with extensive manufacturing capabilities for advanced securement systems, compete with asset-light designers focusing on specialized adhesive formulations. The market structure exhibits a tiered consolidation, with large diversified medical device companies holding significant shares. Strategic archetypes include specialized adhesive technology providers and broad-portfolio medical consumables manufacturers. Dominant competitive moves involve portfolio diversification into adjacent medical technologies and strategic partnerships to expand market access and clinical reach.
On the premium-tier vector, 3M exemplifies a materials science-driven approach, leveraging its expertise in advanced adhesives and polymer science to meet evolving regulatory specifications. BD occupies a position as a comprehensive vascular access and infusion therapy systems provider, integrating securement products into broader solutions for hospital end-users. ConvaTec represents a specialist in advanced wound care technologies, applying this knowledge to adhesive offerings that enhance patient skin integrity. These companies collectively anchor innovation in biocompatibility and infection prevention within the market.
| Leading Market Players |
|---|
| 3M |
| B. Braun Melsungen AG |
| BD |
| C. R. Bard |
| Cardinal Health |
| ConvaTec |
| Merit Medical Systems |
| Baxter |
| Smiths Medical |
Cost & Logistics Intelligence
Captive production of specialized medical-grade adhesives anchors supply positions for major manufacturers, directly influencing their pricing power in the catheter securement market. This integration ensures material quality and intellectual property protection, allowing for premium pricing on advanced solutions.
Pricing Analysis
Value-based pricing models are gaining traction, especially for devices demonstrating quantifiable reductions in catheter-related bloodstream infections. Price differentiation stems from the level of clinical evidence supporting infection prevention claims and the sophistication of material science used. Pricing pressure stems from cost-containment measures by public and private payers like Medicare, favoring lower-cost adhesive products. Home healthcare providers exhibit higher price sensitivity compared to large hospital systems focused on clinical outcomes.
Supply Chain Analysis
Skilled workforce availability in precision manufacturing centers in the United States and Germany underpins the medical device supply chain. The industry relies heavily on specialized medical-grade polymers and biocompatible adhesives as key raw materials. Single-source vulnerability for certain advanced components, particularly for subcutaneous anchoring systems, represents a structural risk. Distribution runs through a tiered model, involving direct sales to large hospital systems and group purchasing organizations, alongside specialized medical distributors for smaller clinics and home healthcare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The catheter securement devices market functions as a stable compounder, driven by the persistent and intensifying focus on preventing hospital-acquired infections.
For Market Incumbents:Lock in long-term contracts with Integrated Delivery Networks (IDNs) by demonstrating superior clinical outcomes and total cost of care reductions. Invest heavily in R&D for antimicrobial-infused adhesives and smart device integration to counter the threat of new regulatory hurdles and emerging material science. Leverage existing channel control and regulatory expertise, particularly for US FDA and EU MDR compliance, to maintain market position.
For New Entrants and Emerging Players:The European Union's MDR framework opens a window for specialized innovators with robust clinical data on infection reduction. Target the pediatric and neonatal niches with gentler adhesives and smaller form factors, representing an unmet clinical need. A go-to-market angle focusing on advanced wound care integration for skin integrity in long-term care facilities offers differentiation.
For Investors and Strategic Acquirers:Roll-up economics work for specialized adhesive technology providers because market fragmentation exists in material science innovation. The long-term viability of this market remains strong over a 5-10 year window, driven by an aging population and increasing chronic disease management. A signal to watch for acquisition targets is quantifiable data on reductions in catheter-related bloodstream infections, beyond just mechanical stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Antimicrobial Coatings | Enhances infection prevention, aligning with CDC guidelines and strengthening product efficacy. |
| Form Strategic Partnerships with IDNs | Secures long-term procurement channels and validates clinical effectiveness within large hospital systems. |
| Develop Pediatric-Specific Devices | Addresses an underserved patient population with unique anatomical and skin sensitivity requirements. |
| Integrate Smart Sensor Technology | Transforms passive devices into active monitoring tools, providing high-value clinical data. |
| Strengthen EU MDR Compliance Efforts | Ensures market access and competitive advantage within the stringent European regulatory landscape. |
Research Approach
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core for this market analysis. This approach integrates primary interviews with clinicians, hospital purchasing committees, R&D leads, and GPO contract managers. Secondary validation draws from sources including US FDA filings, EU MDR documentation, CDC guidelines, and medical device industry association reports.
An input-output matrix frames the forecast across the analysis window, segmenting by product type, application, end-user, deployment model, and material science innovation. Compound annual growth rates are derived from historical data trends and projected changes in procedural volumes and regulatory compliance timelines. Key industry-specific forecast inputs include the adoption rate of advanced securement solutions and the prevalence of chronic conditions requiring long-term catheterization.
Revisions become necessary when significant shifts in infection control guidelines or reimbursement policies materialize. Forecasts reflect current assumptions regarding regulatory frameworks and technological advancements in medical adhesives. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Retinal Implant Market
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Sphincterotomes Market
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Total Artificial Heart Market
Medical Devices
Antimicrobial Coated Medical Devices Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Global Lenses for Myopia Control Market