
 Global Ileostomy Market | 2026-2036
Global Ileostomy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ileostomy Market Foresight
The ileostomy supply chain is pivoting between premium silicone-adhesive barriers with extended wear times and commodity-tier PVC pouch systems with shorter replacement cycles. Coloplast A/S dominates the premium segment through its proprietary Brava adhesive formulations and direct-to-patient subscription channels. Hollister Incorporated competes across both tiers, leveraging its integrated manufacturing footprint in the United States and Ireland to sustain margin flexibility. Marlen Manufacturing & Development Company specializes in custom-fit solutions for complex stoma anatomies, occupying a defensible niche below the multinational volume leaders.
An ileostomy is a surgical procedure creating an opening in the abdominal wall through which the distal ileum is exteriorized to divert intestinal waste, requiring a collection pouch system typically constructed from odor-resistant multilayer films with activated carbon filters and skin-protective hydrocolloid wafers rated for 3-7 day wear duration. Drainable bags lead volume due to their suitability for high-output stomas in Crohn's disease and ulcerative colitis patients, while closed-end bags command premium positioning in stable, low-output cases where discreet disposal matters. Home healthcare providers represent the fastest-growing end-user channel as reimbursement shifts favor outpatient management and telehealth-supported self-care protocols reduce hospital readmission exposure.
The FDA regulates ileostomy devices as Class II medical devices under 21 CFR 876.5900, requiring substantial equivalence demonstrations and biocompatibility testing per ISO 10993 standards for skin-contact materials. The EU MDR reclassification of ostomy products to higher-risk categories is forcing manufacturers to generate clinical performance data and strengthen post-market surveillance systems across notified body jurisdictions. Japan's PMDA maintains distinct stoma care reimbursement codes that influence product configuration decisions for entrants targeting the second-largest single-country market for advanced adhesive systems. Stakeholders must monitor evolving MDR transition timelines and national health technology assessment outcomes to calibrate portfolio investments between regulated premium platforms and price-sensitive emerging market offerings.
Market Dynamics
The EU Medical Device Regulation is compressing product development timelines as manufacturers must generate clinical performance data and strengthen post-market surveillance systems before notified body certification deadlines.
Growth Catalysts
- EU MDR Clinical Evidence Mandate:The reclassification of ostomy products to higher-risk categories under EU MDR is accelerating investment in biocompatibility testing infrastructure and post-market clinical follow-up systems across notified body jurisdictions.
- Home Healthcare Channel Expansion:Post-surgical care migration beyond hospital walls is pulling drainable pouch procurement toward outpatient management networks and telehealth-supported self-care protocols in the United States and Germany.
- Silicone-Adhesive Material Advances:Extended wear-time barriers rated for 7-day duration are displacing shorter-cycle PVC systems among Crohn's disease patients requiring high-output stoma management.
Market Restraints
- Medical-Grade Polymer Cost Volatility:Multilayer film substrates with activated carbon filter integration face input cost pressure from specialized odor-resistant polymer supply concentration in East Asian petrochemical corridors.
- Notified Body Capacity Bottleneck:EU MDR transition timelines have created certification queue congestion, extending time-to-market for new barrier formulations seeking CE marking across member states.
- Adhesive Skin Reaction Incidence:Hydrocolloid wafer dermatitis rates in sensitive patient populations limit universal applicability of standard wear-duration claims, forcing parallel development of hypoallergenic alternative lines.
Strategic Opportunities
- Japan PMDA Reimbursement Codes:Distinct stoma care reimbursement categories in the second-largest single-country market for advanced adhesive systems create entry pathways for premium barrier configurations.
- Direct-to-Patient Subscription Models:Digital channel integration is enabling recurring delivery protocols that bypass traditional durable medical equipment distributor markups and capture lifetime patient value.
- Telehealth-Integrated Adherence Monitoring:Remote stoma assessment platforms are converging with smart pouch sensors to reduce hospital readmission exposure and secure value-based care contracts with United States payers.
Industry Challenges
- ISO 10993 Biocompatibility Testing Backlog:Skin-contact material validation requirements under FDA and EU MDR jurisdictions are stretching specialized toxicology laboratory capacity and delaying submission timelines.
- Legacy ERP Integration with Track-and-Trace:Post-market surveillance data capture systems for unique device identification compliance are forcing mid-tier manufacturers into costly enterprise software upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ileostomy Market |
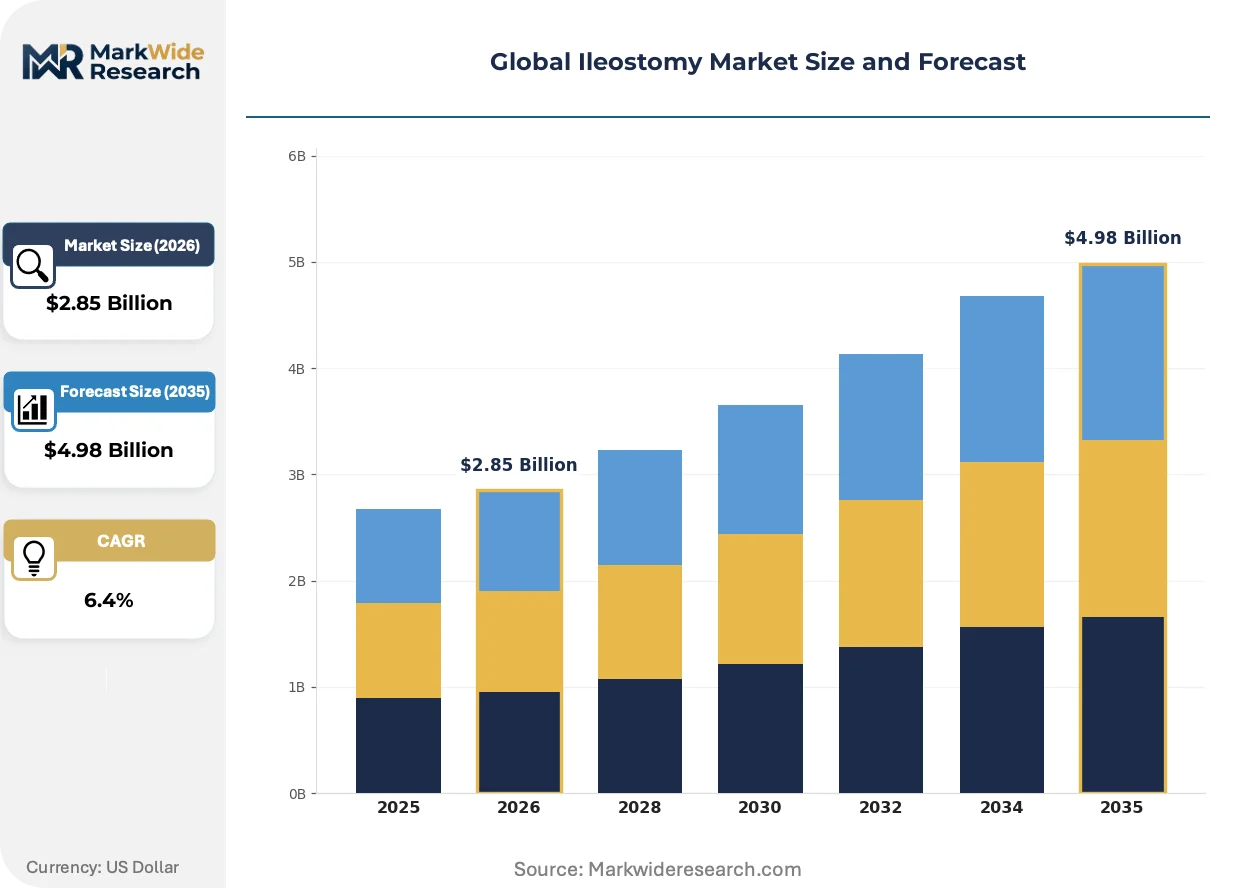
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Pouches, Reusable Pouches, Closed-End Bags, Drainable Bags, Dermatological Accessories Application: Colon Cancer, Crohn’s Disease, Ulcerative Colitis, Polyps, Diverticulitis End User: Hospitals, Ambulatory Care Centers, Specialized Clinics, Home Healthcare Providers Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Direct Sales |
| Companies Covered | Coloplast A/S, ConvaTec Group PLC, Hollister Incorporated, B. Braun Melsungen AG, 3M Health Care, Smith & Nephew PLC, ALCARE Co. Ltd., Marlen Manufacturing & Development Company, Flexicare Medical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ileostomy Market Shifts & Advancements
Active unification of sensor-enabled monitoring with traditional collection systems is compressing the boundary between medical device and digital health platform, while regulatory reclassification and channel disintermediation simultaneously reshape competitive entry points.
Smart barrier systems incorporating moisture detection and wear-time algorithms are unifying physical pouch function with real-time skin health monitoring. Home healthcare providers in Germany and the United States are piloting these integrated platforms for high-risk post-surgical patients. The technology is unifying hardware margins with recurring software service revenue, forcing traditional manufacturers to build digital capabilities or cede platform control to health technology entrants.
EU MDR Article 10 clinical evaluation requirements are mandating prospective performance studies for ostomy products previously cleared through predicate equivalence. Manufacturers must now generate primary evidence on wear-time durability and skin-adhesion safety for barrier formulations seeking CE marking. Small and mid-tier suppliers without established clinical affairs infrastructure face exclusion from premium segment participation across notified body jurisdictions.
Patient-directed purchasing through specialty pharmacy and direct-to-patient channels is fragmenting traditional durable medical equipment distributor dominance. United States Medicare Advantage plans and German statutory health insurance funds are expanding reimbursement for home-delivered supplies, compressing the role of regional medical supply houses. This pattern is most visible in urban corridors with established telehealth infrastructure and aging population density.
Global Ileostomy Market Segmentation
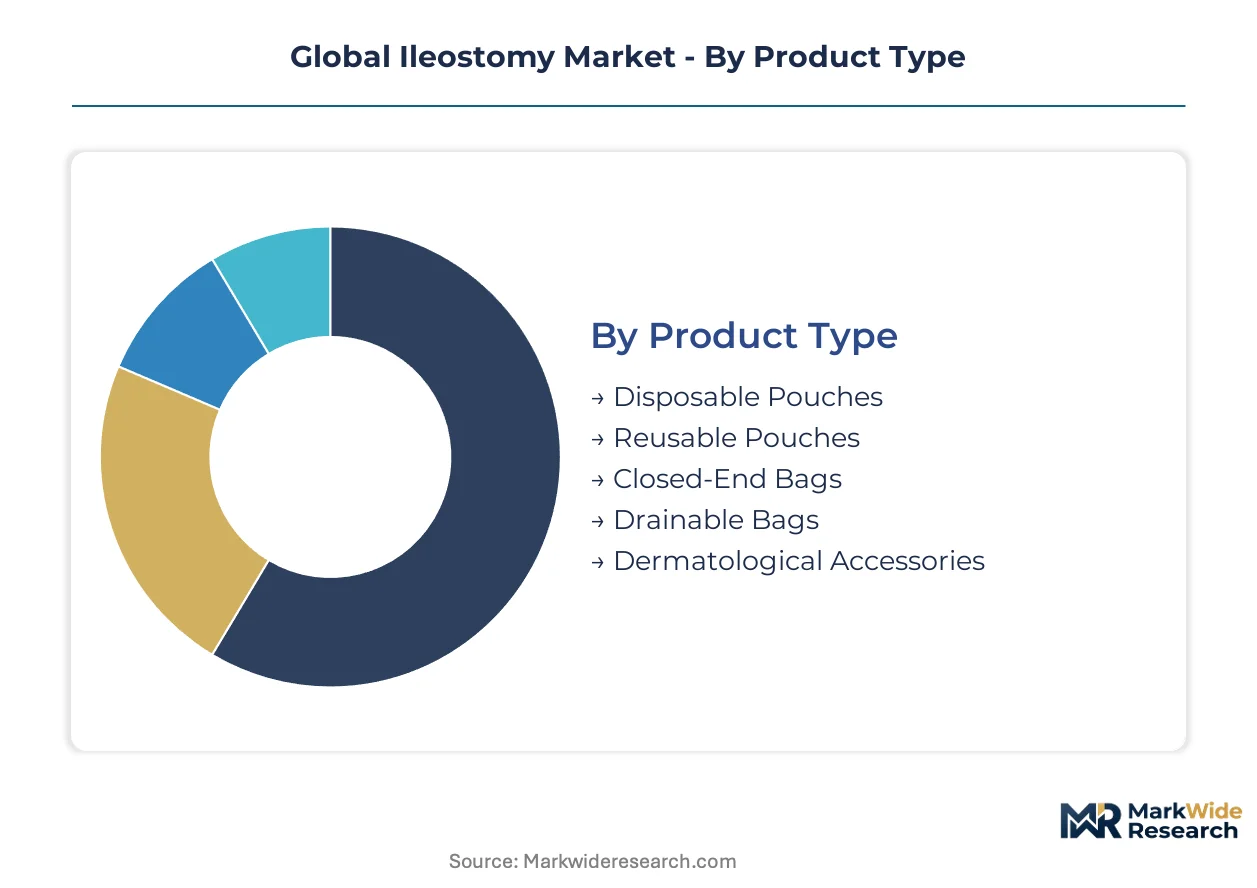
Ileostomy product configuration varies sharply by stoma output characteristics, reimbursement pathway, and patient mobility status. Manufacturers align portfolio depth to these segment boundaries, with material science investments concentrating where wear-time extension commands premium pricing.
Product Type:
Supply concentration for multilayer odor-barrier films in East Asian petrochemical corridors shapes competitive positioning across pouch categories.
- Drainable Bags:High-output stoma management systems with bottom-opening closures and integrated gas filters rated for 3-7 day wear. Demand concentrates among Crohn's disease patients in Germany and the United States where outpatient reimbursement supports frequent replacement cycles.
- Closed-End Bags:Sealed disposal units for low-output stable stomas, constructed with activated carbon layers and discreet profile designs. Japanese PMDA reimbursement codes favor these configurations for elderly patients prioritizing convenience over drainage functionality.
- Disposable Pouches:Single-use systems with hydrocolloid adhesive wafers for acute post-surgical phases.
- Reusable Pouches:Silicone-based barriers with detachable collection chambers for cost-sensitive emerging markets.
- Dermatological Accessories:Skin barrier pastes, powders, and protective films addressing peristomal complications.
Today's leader: Drainable Bags. Tomorrow's challenger: Closed-End Bags.
Application:
Procedure volume distribution across inflammatory bowel disease versus oncology indications determines regional market development priorities.
- Crohn's Disease:Chronic inflammatory condition requiring permanent or temporary ileostomy with high-output management protocols. Patient populations in the United States and Germany drive demand for extended-wear silicone barriers and subscription-based resupply models.
- Ulcerative Colitis:Inflammatory bowel disease often resolving with proctocolectomy and permanent stoma creation. Japanese statutory health insurance funds and United States Medicare Advantage plans increasingly reimburse home-delivered pouch systems for these patients.
- Colon Cancer:Oncological resections with stoma formation during tumor removal procedures.
- Polyps:Preventive colectomy cases with typically temporary diversion requirements.
- Diverticulitis:Emergency surgical interventions with variable stoma duration based on complication severity.
Crohn's Disease claims the steepest expansion trajectory as biologic therapy failures convert to surgical intervention.
End User:
Channel migration from institutional procurement to patient-directed purchasing is fragmenting traditional distributor relationships.
- Home Healthcare Providers:Outpatient networks managing post-surgical care through telehealth-supported resupply protocols. United States and German reimbursement shifts favor these channels, with digital adherence platforms reducing hospital readmission exposure.
- Hospitals:Acute care settings performing initial stoma surgery and patient training. Procurement concentrates on drainable systems for immediate post-operative high-output management.
- Ambulatory Care Centers:Same-day surgical facilities with limited stoma care infrastructure.
- Specialized Clinics:Dedicated stoma care centers providing fitting services and complication management.
Home Healthcare Providers are gaining share fastest as value-based care contracts reward outpatient stability.
Distribution Channel:
Digital channel integration enables manufacturer margin capture previously absorbed by durable medical equipment intermediaries.
- Direct Sales:Manufacturer-to-patient subscription models bypassing distributor markups through recurring delivery protocols. Coloplast and Hollister leverage these channels in the United States and Germany to capture lifetime patient value.
- Online Retailers:E-commerce platforms with insurance pre-authorization integration for reimbursement-eligible purchases.
- Pharmacies:Community and specialty pharmacy networks with limited stoma care expertise.
- Medical Supply Stores:Regional durable medical equipment dealers facing compression from direct channel expansion.
Direct Sales commands premium positioning. Online Retailers threaten pharmacy intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized stoma care nurses in the United States, Germany, and Japan anchor the highest-density clinical networks for ileostomy patient management. These workforce concentrations correlate with reimbursement maturity and established referral pathways for post-surgical care. Regional differentiation follows regulatory fragmentation and polymer supply chain proximity.
United States
Medicare Advantage expansion and value-based care contracts pull procurement toward home healthcare networks with telehealth integration. The FDA maintains Class II device oversight under 21 CFR 876.5900 with ISO 10993 biocompatibility mandates. Cleveland Clinic and Mayo Clinic anchor stoma care training hubs that diffuse advanced barrier fitting protocols through regional health systems.
Germany
Statutory health insurance funds reimburse extended-wear silicone barriers for Crohn's disease patients with documented biologic therapy failure. The EU MDR notified body system, coordinated through BfArM, imposes clinical evidence requirements that compress development timelines for new adhesive formulations. The Rhine-Ruhr corridor hosts concentrated medical device distribution infrastructure serving outpatient networks across North Rhine-Westphalia.
Japan
PMDA maintains distinct reimbursement codes for closed-end pouch configurations favored by elderly patients prioritizing disposal convenience. METI industrial policy supports domestic polymer film production for odor-resistant multilayer substrates. The Kanto region around Tokyo concentrates specialty stoma care clinics with direct manufacturer relationships bypassing traditional medical supply intermediaries.
United Kingdom
NHS England procurement frameworks consolidate demand for drainable systems through national tender mechanisms that compress distributor margins. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while creating separate conformity assessment pathways. The Greater Manchester health system pilots direct-to-patient subscription models for chronic inflammatory bowel disease populations.
India
CDSCO medical device rules classify ostomy products as notified devices requiring import license or domestic manufacturing registration. The PLI scheme for medical devices incentivizes local assembly of PVC-based commodity pouch systems. Gujarat's pharmaceutical and medical device cluster in Ahmedabad hosts contract manufacturers serving price-sensitive emerging market demand across South Asia.
Global Ileostomy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across material science and digital channel domains. The market structure concentrates around multinational medical device conglomerates with integrated polymer film capabilities and regional specialists with custom-fitting expertise. Three archetypes dominate: silicone-adhesive premium barrier developers, PVC commodity pouch fabricators, and digital direct-to-patient platform operators. Strategic moves center on M&A for clinical evidence portfolios and capacity expansion in East Asian polymer supply corridors.
Within the premium barrier tier, Coloplast A/S and Hollister Incorporated exemplify integrated material science and distribution scale. Marlen Manufacturing & Development Company occupies a position among custom-fit specialists serving complex stoma anatomies outside standard product ranges. These three anchors illustrate the competitive tension between volume-driven platform economics and defensible niche positioning in patient-specific care.
| Leading Market Players |
|---|
| Coloplast A/S |
| ConvaTec Group PLC |
| Hollister Incorporated |
| B. Braun Melsungen AG |
| 3M Health Care |
| Smith & Nephew PLC |
| ALCARE Co. Ltd. |
| Marlen Manufacturing & Development Company |
| Flexicare Medical Ltd. |
| Others |
Supply & Pricing Matrix
Home healthcare providers in the United States and Germany anchor procurement volume for ileostomy pouch systems, driving a subscription-based pricing model that bundles recurring supply delivery with telehealth adherence monitoring. This buyer concentration compresses transactional spot purchasing and rewards manufacturers with direct-to-patient channel control.
Pricing Analysis
Subscription bundling separates hardware margins from software-enabled adherence services across premium silicone-adhesive barriers and standard PVC pouch tiers. Price differentiation rests on wear-time certification grade and ISO 10993 biocompatibility tier, with seven-day rated barriers commanding material premiums over three-day systems. Pricing pressure stems from EU MDR clinical evidence mandates elevating regulatory compliance costs for new adhesive formulations. Price-sensitive emerging market buyers in India gravitate toward reusable silicone configurations, while Japanese elderly patients absorb premiums for closed-end disposal convenience.
Supply Chain Analysis
Dual-sourcing requirements for medical-grade multilayer films force manufacturers to qualify suppliers across South Korea, Japan, and domestic EU polymer corridors simultaneously. Raw material dependencies center on odor-resistant polyethylene substrates, activated carbon filter media, and hydrocolloid adhesive resins. Supply chain risk concentrates in East Asian petrochemical corridor concentration exposing procurement to logistics chokepoint vulnerability. Distribution runs through direct-to-patient subscription channels, specialty pharmacy networks, and compressed durable medical equipment dealer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ileostomy care rests on silicone-adhesive material advances compressing replacement cycle frequency and elevating premium-tier capture rates among Crohn's disease populations.
For Market Incumbents: Hedge against EU MDR notified body certification delays by pre-positioning clinical evidence portfolios with BfArM-coordinated jurisdictions before queue congestion extends time-to-market. Prioritize backward integration into East Asian polymer film supply through joint qualification agreements with South Korean substrate specialists. Channel control through direct-to-patient subscription platforms defends margin position against digital health entrants capturing adherence monitoring revenue. For New Entrants and Emerging Players: Enter via Japan's PMDA reimbursement code fragmentation for closed-end pouch configurations, where elderly patient preference for disposal convenience outpaces multinational coverage. Target India's CDSCO-notified device segment through Gujarat-based contract manufacturing partnerships serving price-sensitive South Asian demand. Specialty pharmacy integration with insurance pre-authorization automation offers the most penetrable go-to-market angle against entrenched distributor relationships. For Investors and Strategic Acquirers: Digital health platforms with stoma care software companion capabilities are the most active acquirer in this space, seeking hardware anchors for remote monitoring revenue streams. Long-term viability over a five-to-ten year window favors targets with EU MDR clinical evidence portfolios already navigating notified body certification. The signal to watch is Medicare Advantage value-based care contract expansion rewarding outpatient stability metrics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance unlocks premium segment participation across BfArM jurisdictions. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic training hubs diffuse advanced barrier fitting protocols regionally. |
| Software Companion Development | Telehealth-integrated adherence monitoring secures value-based care contracts with United States payers. |
| Reimbursement Strategy | Japan PMDA distinct stoma care codes favor premium closed-end configurations for elderly populations. |
| Backward Integration | Captive supply of medical-grade multilayer films mitigates East Asian petrochemical corridor concentration risk. |
Research Methodology
Multiple input streams — primary interviews with stoma care nurses and hospital purchasing committees, secondary validation through FDA 510(k) filings and EU MDR notified body documentation, and trade data reconciliation — were triangulated against CMS Medicare reimbursement databases and Japanese PMDA approval records. Bottom-up patient population modeling and top-down manufacturer revenue analysis converged on segment-level estimates across product type, application, and end-user dimensions.
Data-stream reconciliation applied analytical frameworks across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include pouch configuration, wear-time duration tier, stoma output characteristic, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and replacement cycle frequency assumptions, incorporating biologic therapy failure conversion rates for Crohn's disease populations and aging demographic shifts in Japan and Germany.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-time EU MDR certification queue timing introduce uncertainty bands around new product launch assumptions. Deviation in notified body capacity allocation or PMDA reimbursement code revision would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
Gastric Bands Market
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Nasal Implant Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Global Pupillometer Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Hearing Aid with Lithium-Ion Battery Market
Medical Devices
Blood Irradiator Device Market