
 Organoids Kits Market | 2026-2036
Organoids Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Organoids Kits Market Analytics
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified suppliers and peripheral entrants. Thermo Fisher Scientific Inc. leverages its global distribution infrastructure to sustain reagent supply continuity across research institutions. STEMCELL Technologies Inc. specializes in serum-free media formulations that anchor its position in stem cell-derived organoid protocols. Merck KGaA competes through integrated workflow solutions that span matrix proteins to analytical readouts.
Organoids kits comprise curated reagent systems—basement membrane extracts, defined media supplements, and growth factor cocktails—that enable self-organizing three-dimensional tissue structures from stem cells or patient biopsies. These kits standardize the variable parameters of organoid initiation and maintenance, delivering reproducible culture conditions for drug response profiling and developmental biology research. Tumor organoids command premium positioning due to their direct patient-derived origin and predictive value in oncology pipeline decisions, while microfluidics-enabled kits represent the fastest-growing technology dimension as perfusion culture extends organoid longevity and maturation. Scaffold-based approaches retain volume leadership in entry-level research settings where cost sensitivity dominates procurement criteria.
The FDA evaluates organoid data under its qualification program for drug development tools, while the EMA's Innovation Task Force engages developers on organoid-based biomarker submissions. ISO 10993 biocompatibility standards and Good Laboratory Practice guidelines shape kit component specifications and documentation requirements for preclinical applications. Stakeholders must monitor evolving regulatory acceptance pathways that will determine which organoid platforms achieve formal qualification status versus remaining exploratory research tools.
Market Dynamics
Microfluidics-enabled perfusion culture is decomposing the traditional static-batch organoid workflow, forcing kit suppliers to reengineer media formulations and matrix compositions for dynamic flow conditions. This technology shift compresses the viable shelf life of legacy scaffold-based products while opening premium positioning for integrated hardware-software platforms.
Growth Catalysts
- FDA Qualification Program for Drug Development Tools:The FDA's formal pathway for organoid-based assay qualification accelerates pharmaceutical procurement of standardized kits for IND-enabling toxicology studies.
- NIH funding concentration:United States federal research grants for patient-derived tumor organoid biobanks create institutional procurement pull at academic medical centers and NCI-designated cancer centers.
- Serum-free media chemistry:Defined, xeno-free formulations reduce batch-to-batch variability and satisfy EMA guidelines on biological starting materials for cell therapy applications.
Market Restraints
- Matrigel supply concentration:Single-source dependency on Corning's basement membrane extract creates vulnerability for kit manufacturers reliant on laminin-rich substrates.
- ISO 10993 biocompatibility testing costs:Preclinical qualification of novel matrix proteins requires extensive cytotoxicity and sensitization studies that inflate kit development timelines.
- Primary tissue access restrictions:HIPAA-compliant patient sample procurement and informed consent protocols limit tumor organoid establishment rates at smaller research institutions.
Strategic Opportunities
- India CDMO expansion:Contract research organizations in Hyderabad and Bangalore seek organoid platforms for biosimilar immunogenicity testing, creating demand for cost-optimized entry-level kits.
- EU Green Deal chemical substitution:REACH restrictions on animal-derived reagents push European kit suppliers toward synthetic hydrogel alternatives and recombinant protein production.
- Multi-organ microphysiological systems:Convergence of liver-kidney-intestine organoid coupling enables ADMET prediction workflows that single-tissue kits cannot address.
Industry Challenges
- Organoid technologist scarcity:Specialized expertise in stem cell maintenance, 3D imaging, and computational morphometry outstrips training program output across biotechnology hubs.
- GLP documentation burden:Good Laboratory Practice compliance for preclinical safety studies requires extensive batch records and chain-of-custody protocols that strain kit supplier quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organoids Kits Market |
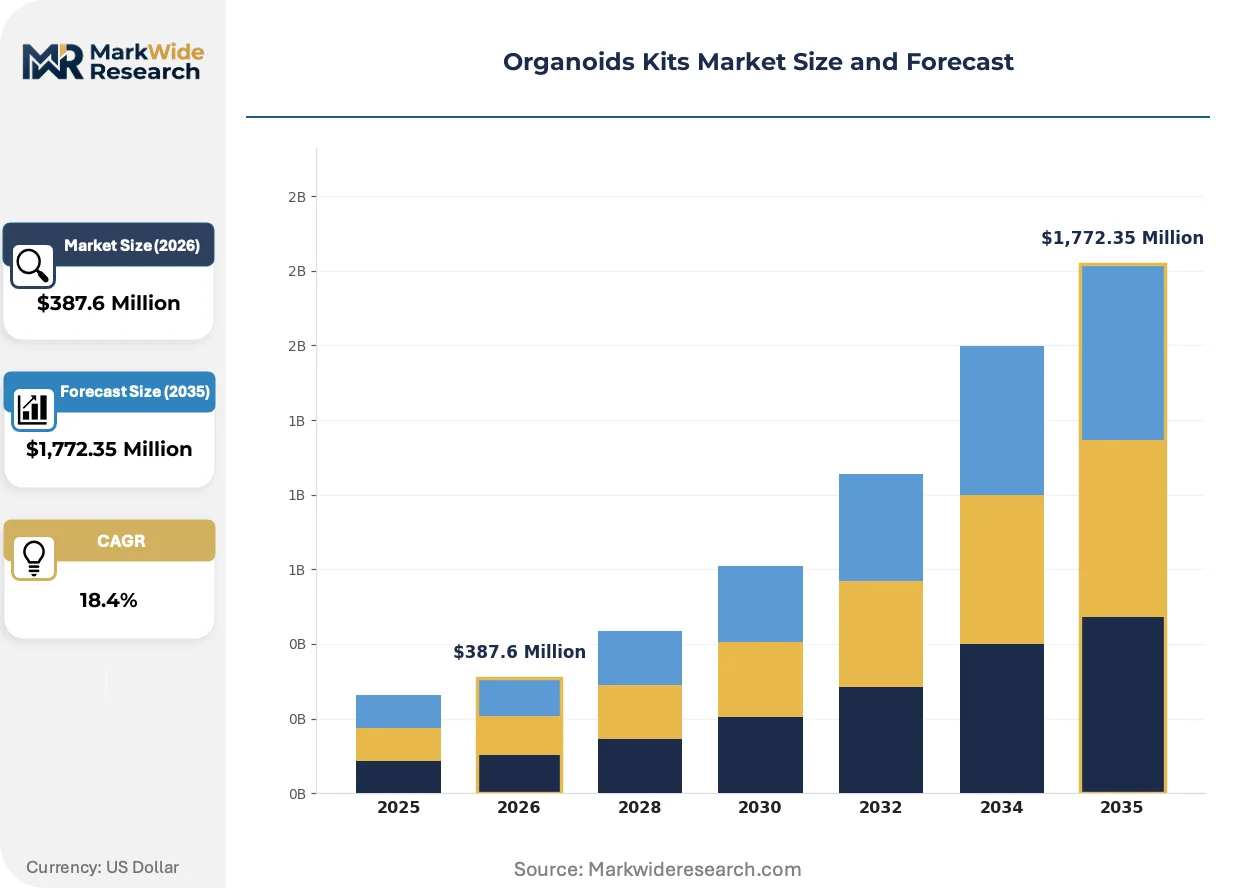
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Cell Cultures, Stem Cell-Derived Organoids, Tumor Organoids, Liver Organoids Application: Drug Discovery, Toxicity Testing, Disease Modeling, Precision Medicine Technology: Microfluidics, Bioprinting, Matrigel Culture, Scaffold-Based End User: Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Academic Laboratories |
| Companies Covered | Thermo Fisher Scientific Inc., STEMCELL Technologies Inc., Corning Incorporated, Merck KGaA, Bio-Techne Corporation, Lonza Group Ltd., Greiner Bio-One International GmbH, Crown Bioscience Inc., Hubrecht Organoid Technology (HUB), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organoids Kits Market Evolving Landscape
Automated liquid handling and AI-driven image analysis are compressing the manual labor intensity of organoid culture, shifting competitive advantage from reagent chemistry to integrated workflow software. These converging capabilities redefine how research institutions evaluate kit procurement decisions.
Organoid-on-a-chip microfluidics is decomposing the static well-plate paradigm by enabling continuous media perfusion and real-time metabolite monitoring. Pharmaceutical toxicology groups at Merck KGaA and Roche have adopted these platforms for repeat-dose hepatotoxicity screening. The technology is decomposing demand for conventional multi-well inserts and forcing matrix suppliers to develop shear-resistant hydrogel formulations compatible with pneumatic pumping systems.
EMA's Innovation Task Force guidance on organoid-derived biomarker submissions is creating regulatory precedent for patient-derived model qualification in oncology trials. European pharmaceutical developers now engage the task force during pre-IND meetings to align organoid data packages with marketing authorization requirements. This policy development most acutely affects tumor organoid kit suppliers seeking formal drug development tool status.
Consolidated procurement through group purchasing organizations is displacing direct institutional purchasing at United States academic medical centers. Premier and Vizient negotiate enterprise pricing for stem cell media and growth factor portfolios, compressing margins for kit distributors dependent on individual laboratory relationships. This behavioral shift concentrates volume with suppliers offering validated GMP-grade documentation and multi-site supply contracts.
Organoids Kits Market Segmentation
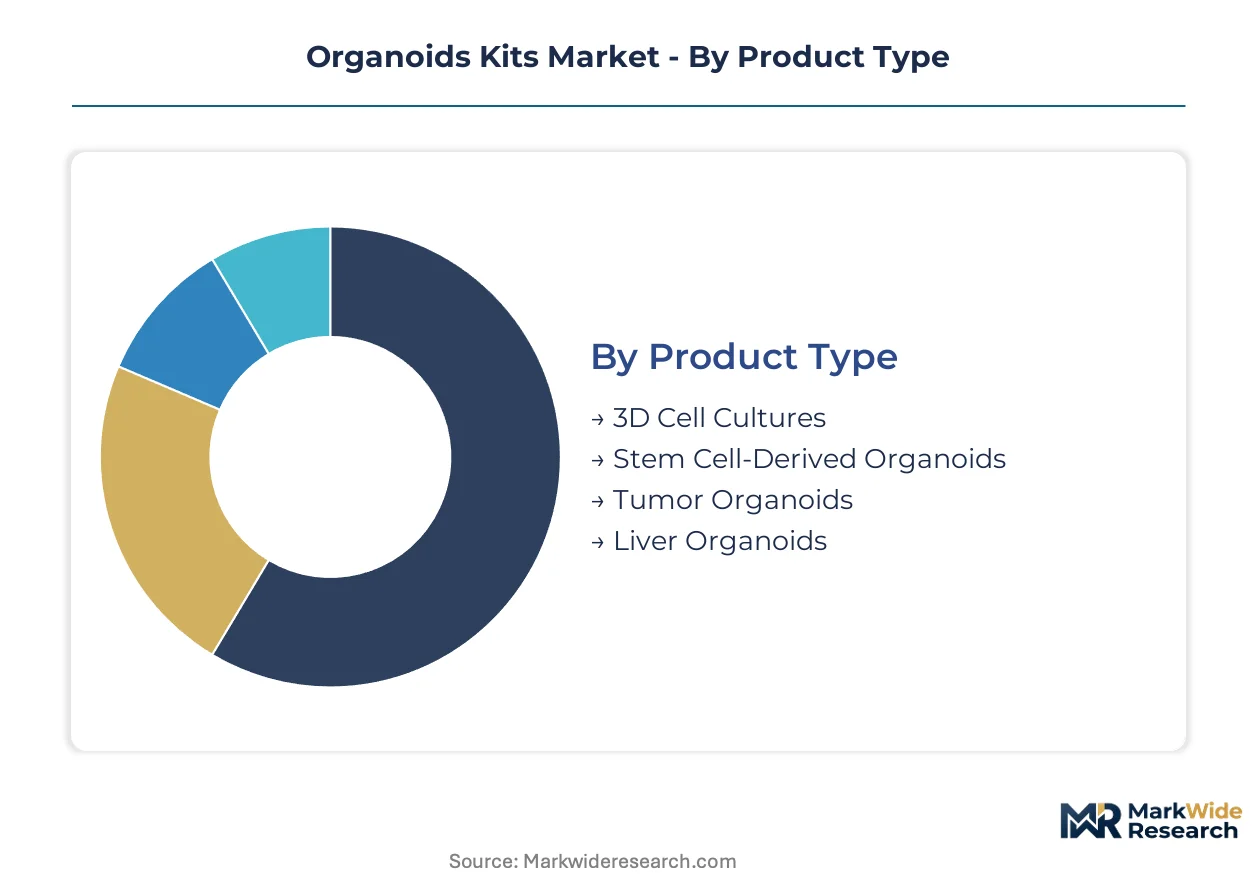
Organoids kits segment across four interlocking dimensions that determine procurement priorities and pricing power. Product type stratification reflects biological complexity premiums, while technology choices increasingly separate high-throughput pharmaceutical workflows from academic exploratory research. Application focus and end-user scale further bifurcate the vendor landscape between standardized reagent suppliers and custom protocol developers.
Product Type:
Tumor organoids face intensifying substitution pressure from patient-derived xenograft alternatives in oncology drug development, forcing kit suppliers to differentiate on turnaround speed and histological fidelity.
- Tumor Organoids:Patient-derived models replicate tumor heterogeneity and therapeutic response patterns with histological fidelity unmatched by cell line aggregates. Demand concentrates at NCI-designated cancer centers in the United States where biobank infrastructure supports prospective sample collection for pharmaceutical partnership programs. HIPAA-compliant procurement protocols and informed consent standardization constrain establishment rates at smaller institutions.
- Stem Cell-Derived Organoids:Pluripotent stem cell protocols enable developmental biology studies and congenital disease modeling through directed differentiation into organ-specific lineages. Research institutions in Boston and San Francisco drive procurement volume for neural and intestinal organoid applications where developmental trajectory mapping supports basic science publication pipelines.
- 3D Cell Cultures:Aggregated cell spheroids provide entry-level three-dimensional architecture for cytotoxicity screening without self-organizing complexity.
- Liver Organoids:Hepatocyte-derived models address ADMET prediction gaps in pharmaceutical toxicology workflows.
Tumor organoids anchor the volume base while stem cell-derived organoids gain share at the steepest rate.
Application:
Cost tier stratification separates premium-priced precision medicine applications from high-volume toxicity testing contracts where kit margins compress under enterprise procurement terms.
- Drug Discovery:Compound screening workflows at pharmaceutical headquarters in New Jersey and Basel demand validated assay reproducibility across multi-site replication studies. FDA qualification pathway engagement for drug development tool status drives kit standardization investments that smaller suppliers cannot underwrite.
- Precision Medicine:Patient-specific organoid establishment for therapeutic selection requires living biobank infrastructure and clinical pathology integration that academic medical centers in Heidelberg and Singapore are assembling through dedicated core facilities. Regulatory precedent from EMA Innovation Task Force guidance shapes data package requirements for biomarker qualification submissions.
- Toxicity Testing:Repeat-dose hepatotoxicity and cardiotoxicity screening generates predictable reagent consumption at contract research organizations.
- Disease Modeling:Rare disease foundation funding supports organoid development for mechanistic studies with limited commercial return.
Toxicity testing anchors the volume base while precision medicine commands the steepest expansion trajectory.
Technology:
Supply concentration in basement membrane extract production constrains Matrigel-dependent segments while microfluidics hardware integration opens proprietary platform opportunities.
- Microfluidics:Perfusion culture systems extend organoid longevity through continuous media exchange and real-time metabolite monitoring. Roche and Merck KGaA toxicology groups have adopted these platforms for repeat-dose screening workflows that static cultures cannot support. Shear-resistant hydrogel formulation requirements differentiate matrix suppliers with pneumatic pumping compatibility.
- Matrigel Culture:Corning's laminin-rich basement membrane extract dominates standardized protocols despite lot-to-lot variability concerns that defined media formulations attempt to mitigate. Single-source dependency creates vulnerability for kit manufacturers without alternative substrate qualification.
- Scaffold-Based:Synthetic hydrogel and decellularized matrix approaches reduce animal-derived reagent dependence for EU Green Deal compliance.
- Bioprinting:Spatially patterned organoid arrays enable vascularization studies and multi-tissue interface modeling.
Matrigel culture anchors the volume base while microfluidics climbs the fastest.
End User:
Customer type determines documentation burden and pricing tolerance, with pharmaceutical procurement demanding GMP-grade batch records that academic laboratories rarely require.
- Pharmaceutical Companies:IND-enabling toxicology studies require GLP-compliant kit documentation with chain-of-custody protocols and stability validation that strain supplier quality systems. Consolidated procurement through Premier and Vizient group purchasing organizations compresses distributor margins at United States academic medical centers.
- Biotechnology Firms:Venture-funded cell therapy developers in Cambridge and South San Francisco prioritize serum-free, xeno-free formulations that satisfy EMA biological starting material guidelines for downstream clinical applications.
- Research Institutions:NIH grant funding supports exploratory organoid applications with flexible protocol adaptation.
- Academic Laboratories:Cost-sensitive entry-level research drives scaffold-based kit procurement where manual handling tolerance remains acceptable.
Pharmaceutical companies anchor the volume base while biotechnology firms gain share most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical headquarters and NCI-designated cancer centers concentrate procurement pull in specific metropolitan clusters across four countries. Academic medical centers with living biobank infrastructure command premium kit specifications that smaller research institutions cannot replicate.
United States
NIH funding for patient-derived tumor organoid biobanks drives institutional procurement at academic medical centers in Boston and San Francisco. FDA qualification pathways for drug development tools accelerate pharmaceutical adoption of standardized assays. NCI-designated cancer centers in Houston and New York maintain dedicated core facilities for pharmaceutical partnership programs.
Germany
Heidelberg and Munich anchor European demand through integrated clinical pathology and organoid establishment workflows. EMA Innovation Task Force guidance shapes biomarker qualification submissions from pharmaceutical developers in Basel-accessible Baden-Württemberg. REACH restrictions on animal-derived reagents push kit suppliers toward synthetic hydrogel alternatives.
United Kingdom
London's Francis Crick Institute and Cambridge cell therapy clusters prioritize serum-free formulations satisfying biological starting material guidelines. NHS England's precision medicine initiatives create procurement pull for patient-specific organoid applications. Oxford and Edinburgh research institutions drive developmental biology kit consumption for neural and intestinal protocols.
China
Shanghai and Beijing biotechnology parks adopt organoid platforms for biosimilar immunogenicity testing and domestic pharmaceutical R&D. NMPA evolving stance on alternative testing methods creates regulatory uncertainty for kit qualification. Shenzhen hardware manufacturers develop microfluidics-integrated platforms for perfusion culture applications.
Singapore
A*STAR research institutes and the National University Hospital system assemble dedicated core facilities for precision medicine applications. The country's biomedical sciences initiative attracts pharmaceutical toxicology outsourcing from regional headquarters. Biopolis and one-north clusters concentrate stem cell-derived organoid expertise for developmental biology research.
Organoids Kits Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with global distribution infrastructure and specialized stem cell media developers with protocol-specific expertise. The market exhibits tiered concentration with three to four integrated workflow suppliers commanding pharmaceutical procurement and a fragmented long tail of regional reagent distributors serving academic laboratories. Two dominant strategic archetypes define competitive positioning: global platform providers leveraging supply chain scale and niche specialists defending margin through formulation chemistry. M&A activity targets microfluidics hardware developers and synthetic hydrogel innovators, while strategic partnerships between kit suppliers and contract research organizations expand installed base in toxicology screening.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions anchored by global distribution networks and integrated workflow portfolios. STEMCELL Technologies Inc. exemplifies the specialized formulation archetype through its serum-free media expertise. Corning Incorporated represents the substrate supply concentration that constrains kit manufacturer flexibility. These three anchors illustrate how competitive advantage separates between scale-driven platform coverage and chemistry-specific protocol optimization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| STEMCELL Technologies Inc. |
| Corning Incorporated |
| Merck KGaA |
| Bio-Techne Corporation |
| Lonza Group Ltd. |
| Greiner Bio-One International GmbH |
| Crown Bioscience Inc. |
| Hubrecht Organoid Technology (HUB) |
| Others |
Value Network & Pricing Analysis
ISO 10993 biocompatibility certification gates both supplier qualification and price tiering in organoids kits, forcing manufacturers to absorb extensive cytotoxicity testing costs while pharmaceutical buyers pay premiums for GLP-compliant documentation chains. Academic laboratories face exclusion from premium tiers as GMP-grade batch records inflate kit prices beyond grant-funded procurement ceilings.
Pricing Analysis
Cost-plus contracts with indexation to growth factor spot markets dominate pharmaceutical procurement, though serum-free media formulations command fixed-price premiums for EMA-compliant cell therapy applications. Price differentiation rests on certification grade—GLP documentation tiers separate pharmaceutical toxicology workflows from exploratory academic research—and volume scale through Premier and Vizient group purchasing consolidation. Cost compression in entry-level scaffold-based kits is intensifying as Indian CDMOs seek biosimilar testing platforms. Academic laboratories exhibit highest price sensitivity, while biotechnology firms pursuing IND-enabling studies demonstrate lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Inventory lead times for laminin-rich basement membrane extracts extend production schedules, compelling kit manufacturers to maintain strategic reserves of Corning-sourced Matrigel amid single-source concentration. Supply concentrates in the United States for growth factor production, Germany for recombinant protein synthesis, and China for microfluidics hardware components. Raw material dependencies include porcine-derived laminin, recombinant EGF and Noggin proteins, and synthetic PEG-based hydrogels. Single-source vulnerability in basement membrane extract supply creates catastrophic disruption risk for standardized protocol manufacturers. Distribution runs through direct institutional contracts at academic medical centers and enterprise agreements with pharmaceutical procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the vendor landscape creates acquisition opportunities as microfluidics convergence and synthetic hydrogel substitution fragment incumbent positions. Microphysiological systems demand is carving specialized niches that mid-scale formulation chemists can defend.
For Market Incumbents: Compound formulation chemistry advantages with microfluidics hardware partnerships to defend against synthetic hydrogel substitution threats from EU Green Deal compliance pressures. Pursue backward integration into recombinant protein production to reduce Corning Matrigel dependency. Invest in GMP-grade documentation infrastructure to capture pharmaceutical procurement consolidation through Premier and Vizient enterprise contracts. For New Entrants and Emerging Players: Anchor in Indian CDMO toxicology outsourcing demand for cost-optimized entry-level kits, where biosimilar immunogenicity testing creates immediate procurement pull. Target scaffold-based liver organoid segments for ADMET screening applications, bypassing entrenched tumor organoid competition. Pursue strategic partnerships with Hyderabad and Bangalore contract research organizations to establish installed base before pharmaceutical qualification pathway maturation. For Investors and Strategic Acquirers: FDA qualification pathway reshapes the acquisition landscape toward synthetic hydrogel innovators and multi-organ microphysiological system developers with formal drug development tool engagement. Long-term viability favors platforms achieving regulatory precedent over exploratory research tool positioning. Watch EMA Innovation Task Force biomarker qualification submissions as inflection indicators for patient-derived model commercialization trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Hydrogel Substitution | REACH compliance drives recombinant laminin alternatives that reduce animal-derived reagent dependence. |
| Microfluidics Hardware Integration | Perfusion culture platforms at Roche and Merck KGaA displace static well-plate workflows. |
| GLP Documentation Investment | Batch record infrastructure captures pharmaceutical procurement through group purchasing consolidation. |
| Multi-Organ System Development | Liver-kidney-intestine coupling enables ADMET prediction beyond single-tissue kit capabilities. |
| Indian CDMO Partnership Expansion | Biosimilar immunogenicity testing demand in Hyderabad creates entry-level kit volume anchors. |
Research Methodology
Desk research of FDA qualification pathway documentation, EMA Innovation Task Force guidance, and NIH funding disbursement records preceded structured interviews with organoid core facility directors, pharmaceutical toxicology group leaders, stem cell media formulation scientists, and group purchasing organization contract managers. Primary fieldwork with biotechnology procurement officers and academic laboratory principal investigators was cross-validated against secondary sources including SEC 10-K filings, ClinicalTrials.gov assay qualification entries, and ISO certification registries. Bottom-up kit shipment estimates from regional distributors were triangulated against top-down pharmaceutical R&D expenditure allocations.
Variance decomposition across product type, technology platform, application focus, and end-user scale informed the analytical framework over the projection horizon. Segmentation modeling incorporated tumor versus stem cell-derived origin, Matrigel versus microfluidics versus scaffold-based technology, and pharmaceutical versus academic procurement channel distinctions. CAGRs were derived from NIH funding trajectory analysis, pharmaceutical pipeline disclosure patterns, and regulatory acceptance pathway progression rates.
Material uncertainties—FDA qualification timeline delays, Matrigel supply disruptions, and REACH enforcement intensity variations—sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory precedent establishment and group purchasing consolidation momentum. Revision becomes warranted when EMA biomarker qualification submission volumes cross institutional adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Global Intravenous Infusion Pump Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market