
 Pipetting Systems Market | 2026-2036
Pipetting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pipetting Systems Market Analytics
Buyer concentration in pharmaceutical companies and large contract research organizations is pivoting toward integrated automation platforms that bundle pipetting with downstream analytics. Thermo Fisher Scientific leverages its extensive distribution network to anchor multi-channel electronic pipette deployments across North American research laboratories. Danaher competes through specialized liquid handling subsidiaries that dominate high-throughput screening installations. Sartorius positions its electronic pipette portfolio to capture demand from bioprocess laboratories seeking GMP-compliant dispensing accuracy.
Pipetting systems comprise precision fluid transfer instruments—manual, electronic, or multi-channel configurations—engineered to deliver microliter-to-milliliter volumes with coefficients of variation below one percent, serving genomics, proteomics, and clinical diagnostics workflows. Electronic pipettes with programmable step sequences and tip ejection mechanisms are displacing manual units in pharmaceutical quality control laboratories where reproducibility requirements have tightened. Research laboratories remain the largest end user segment, though clinical laboratories represent the fastest-growing category as diagnostic automation expands. Direct sales channels occupy the dominant share of high-value electronic pipette transactions, while distributors navigate the fragmented educational institution segment.
FDA 21 CFR Part 11 validation requirements shape electronic pipette procurement decisions in United States pharmaceutical laboratories, while EMA Annex 15 guidelines on computerized systems drive equivalent compliance investments across European Union manufacturing sites. ISO 8655 calibration standards govern volumetric accuracy verification, creating recurring service revenue pools for manufacturers and third-party metrology providers. China's NMPA medical device classification rules for automated liquid handling systems are tightening product registration pathways. Stakeholders must monitor evolving GxP harmonization between FDA and EMA digital data integrity expectations to anticipate specification shifts in next-generation pipetting platforms.
Market Dynamics
Pharmaceutical quality control laboratories are consolidating liquid handling workflows around FDA 21 CFR Part 11 compliant electronic platforms, compressing procurement cycles for standalone manual instruments and favoring integrated automation vendors with validation documentation capabilities.
Growth Catalysts
- EMA Annex 15 computerized systems mandates:European Union pharmaceutical manufacturers are retrofitting liquid handling stations with audit-trail-enabled electronic pipettes to satisfy data integrity inspections.
- Contract research organization cluster expansion:Concentrated biopharma R&D investment in the United States, Germany, and China is creating synchronized demand for high-throughput multi-channel dispensing systems.
- Genomics workflow automation:Next-generation sequencing sample preparation protocols are standardizing on programmable electronic pipettes with step-sequence memory to reduce operator-to-operator variability.
Market Restraints
- Precision component supply concentration:Ceramic piston manufacturing for high-accuracy pipettes concentrates among German and Japanese specialty suppliers, exposing lead time risks.
- ISO 8655 calibration service dependency:Volumetric accuracy verification requires recurring third-party metrology expenditure that constrains total cost of ownership budgets in mid-sized laboratories.
- Manual pipette installed base inertia:Educational institutions and legacy research facilities face capital replacement friction against functional but non-compliant manual instrument fleets.
Strategic Opportunities
- Clinical diagnostics automation expansion:Diagnostic laboratories in China are adopting electronic pipetting modules for immunoassay and molecular testing workflows at accelerating rates.
- Bioprocess GMP compliance demand:Sartorius and specialized vendors are capturing biopharma manufacturing expenditure by positioning electronic pipettes with GMP-validated dispensing accuracy.
- Cloud-connected instrument ecosystems:Electronic pipettes with Wi-Fi-enabled usage logging and remote calibration monitoring are opening subscription service revenue streams.
Industry Challenges
- 21 CFR Part 11 validation expertise scarcity:Pharmaceutical quality teams face recruitment friction for personnel capable of executing electronic pipette IQ/OQ/PQ documentation protocols.
- Multi-vendor integration complexity:Research laboratories struggle to synchronize electronic pipetting platforms with disparate laboratory information management systems and robotic scheduling software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipetting Systems Market |
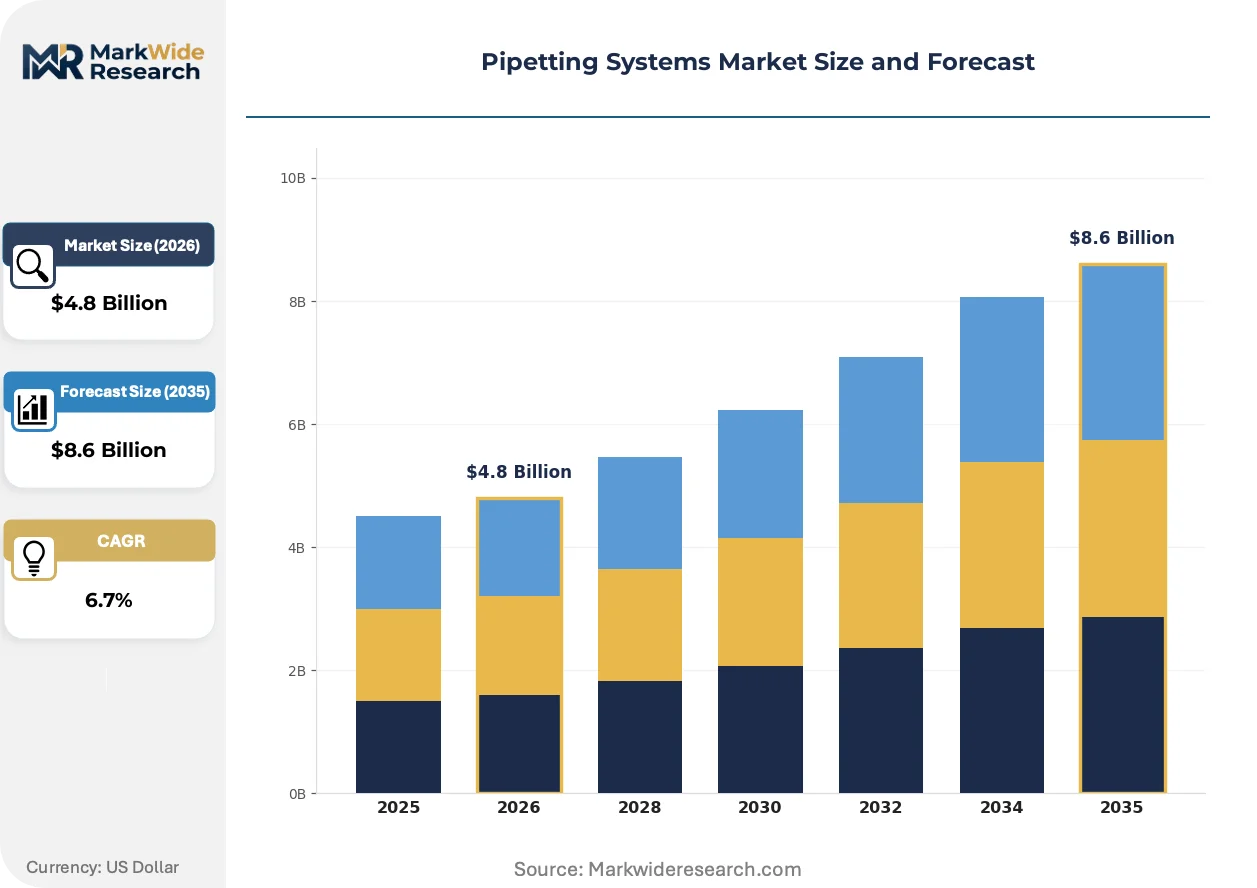
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pipettes, Electronic Pipettes, Multi Channel Pipettes, Positive Displacement Pipettes End User: Research Laboratories, Clinical Laboratories, Pharmaceutical Companies, Educational Institutions Application: Liquid Handling, Sample Preparation, Reagent Dispensing, High-Throughput Screening Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Danaher, Eppendorf, Hamilton Company, Sartorius, Mettler Toledo, Beckman Coulter, Analytik Jena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipetting Systems Market Evolving Landscape
Electronic pipetting platforms are converging with laboratory robotics and cloud data infrastructure, shifting competitive differentiation from hardware precision toward workflow integration and compliance automation capabilities.
Programmable electronic pipettes with step-sequence memory and motorized tip ejection are automating repetitive liquid transfer protocols in pharmaceutical quality control and genomics sample preparation. High-throughput screening facilities are deploying these instruments at accelerating replacement rates against manual alternatives. This automation is compressing assay turnaround times and reducing coefficient of variation below manual operator thresholds.
FDA 21 CFR Part 11 requirements for electronic records and signatures are mandating audit-trail functionality in United States pharmaceutical laboratory equipment procurement specifications. Equipment vendors must now deliver validated software documentation packages alongside hardware to satisfy quality assurance review cycles. Clinical diagnostic laboratories in the United States represent the most affected segment, with procurement committees prioritizing pre-validated platforms over configurable alternatives.
Research procurement committees are unbundling after-sales service contracts from hardware acquisition, negotiating separate calibration and maintenance agreements with third-party metrology providers. This disintermediation pressures manufacturer service revenue margins while expanding ISO 17025-accredited laboratory service market entry. The pattern is most visible in German and United States academic research consortia with centralized purchasing authority.
Pipetting Systems Market Segmentation
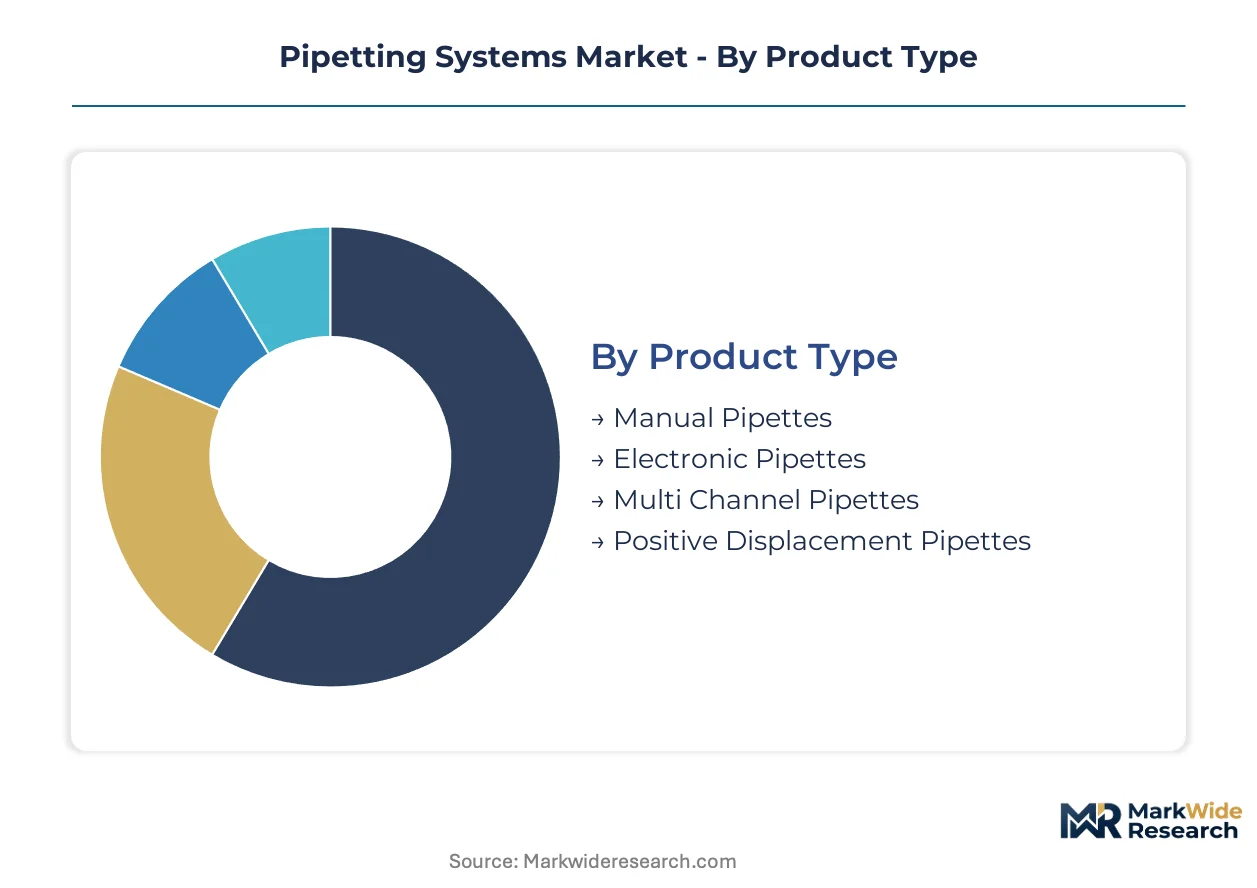
Segmentation in pipetting systems reveals distinct technology-performance-cost tradeoffs that shape procurement patterns across laboratory environments. Each dimension—product architecture, end-user workflow, application protocol, and channel economics—generates separate competitive battlegrounds with divergent margin structures and compliance requirements.
Product Type:
Technical sophistication defines the product hierarchy, with motorized functionality and channel density commanding premium positioning against mechanical alternatives.
- Electronic Pipettes:Programmable step sequences, motorized piston drive, and audit-trail logging enable FDA 21 CFR Part 11 compliance in pharmaceutical quality control laboratories. Demand concentrates in United States and German biopharma manufacturing where GMP-validated dispensing accuracy is mandatory.
- Multi Channel Pipettes:Eight- and twelve-channel configurations standardize microplate workflows, reducing operator-to-operator variability in genomics sample preparation. Contract research organization clusters in Boston and Shanghai are retrofitting high-throughput screening facilities with these instruments at accelerating replacement rates.
- Manual Pipettes:Spring-loaded piston mechanisms dominate educational institutions and legacy research facilities where capital replacement friction persists against functional installed bases.
- Positive Displacement Pipettes:Direct contact piston systems handle viscous or volatile liquids in bioprocess applications requiring sterile dispensing accuracy.
Electronic pipettes lead on scale; multi-channel configurations lead on momentum.
End User:
Procurement authority and compliance burden create divergent customer segments with distinct vendor selection criteria and contract value profiles.
- Research Laboratories:Academic and government facilities with centralized purchasing authority negotiate unbundled service contracts, separating hardware acquisition from third-party ISO 17025 calibration agreements.
- Clinical Laboratories:Diagnostic automation expansion in Chinese urban hospital networks is adopting electronic pipetting modules for immunoassay and molecular testing workflows. This segment is expanding most quickly as regulatory pressure for reproducible diagnostic protocols intensifies.
- Pharmaceutical Companies:Quality control departments mandate validated electronic platforms with IQ/OQ/PQ documentation packages, compressing procurement cycles for standalone manual alternatives.
- Educational Institutions:Budget-constrained biology and chemistry teaching labs maintain manual pipette fleets despite electronic alternatives, creating aftermarket service dependency for legacy instrument calibration.
Research laboratories anchor volume; clinical laboratories drive growth acceleration.
Application:
Workflow protocol standardization determines instrument specification requirements, with throughput and reproducibility thresholds varying sharply across use cases.
- Sample Preparation:Next-generation sequencing protocols standardize on programmable electronic pipettes with step-sequence memory to reduce pre-analytical variability in genomics workflows.
- High-Throughput Screening:Automated liquid handling stations in pharmaceutical discovery facilities require multi-channel dispensing with sub-one-percent coefficient of variation for assay reproducibility.
- Liquid Handling:General-purpose transfer operations span manual to electronic configurations depending on volume precision requirements and operator training levels.
- Reagent Dispensing:Bioprocess manufacturing applications demand GMP-compliant positive displacement systems for sterile buffer and media preparation.
Sample preparation commands specification investment; high-throughput screening scales fastest.
Distribution Channel:
Transaction economics and technical support requirements segment channel strategy, with high-value electronic platforms demanding direct vendor engagement.
- Direct Sales:Validated electronic pipette deployments in pharmaceutical and clinical laboratories require vendor-delivered installation qualification and training, occupying dominant share of high-value transactions.
- Distributors:Fragmented educational and smaller research institution procurement navigates regional distribution networks with inventory proximity advantages.
- Online Retail:Standardized manual pipette configurations and consumable tips migrate to e-commerce platforms with transparent pricing and rapid fulfillment.
- Resellers:Secondary market channels serve budget-constrained facilities with refurbished or discontinued model availability.
Direct sales capture value concentration; online retail expands accessibility fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scientific talent clusters in Boston, Basel, and Shanghai anchor pipetting system procurement decisions. Contract research organization density in these metropolitan areas synchronizes demand for high-throughput liquid handling infrastructure. Regulatory divergence between FDA, EMA, and NMPA compliance frameworks fragments vendor certification requirements across jurisdictions.
United States
Pharmaceutical quality control laboratories in Massachusetts and New Jersey drive electronic pipette replacement cycles. FDA 21 CFR Part 11 mandates audit-trail functionality in procurement specifications, compressing vendor selection to pre-validated platforms. The Greater Boston biotech corridor concentrates multi-channel pipette deployments for genomics sample preparation workflows.
Germany
EMA Annex 15 computerized systems guidelines force retrofit investments across Baden-Württemberg pharmaceutical manufacturing sites. ISO 8655 calibration standards create recurring service revenue pools for metrology providers serving Heidelberg and Munich research consortia. Ceramic piston supply from specialty suppliers in Thuringia exposes lead time vulnerabilities for high-accuracy instruments.
China
Clinical diagnostic automation in Shanghai and Beijing hospital networks accelerates electronic pipetting module adoption. NMPA medical device classification rules tighten registration pathways for automated liquid handling systems. The Zhangjiang Hi-Tech Park contract research cluster standardizes on programmable pipettes for next-generation sequencing protocols.
Japan
PMDA quality system regulations govern pharmaceutical laboratory equipment validation in Osaka and Tokyo manufacturing hubs. Precision component sourcing from domestic ceramic suppliers insulates Japanese vendors from German supply chain disruptions. Yokohama-based research institutions unbundle service contracts, negotiating third-party calibration agreements separately from hardware acquisition.
Switzerland
Swissmedic GMP inspections drive bioprocess laboratory investment in GMP-validated dispensing accuracy around Basel. The country's pharmaceutical manufacturing density supports premium electronic pipette positioning for sterile buffer preparation. Roche and Novartis supplier qualification requirements cascade compliance standards through regional vendor ecosystems.
Pipetting Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the pipetting systems value chain. Life science conglomerates leverage distribution scale and cross-selling synergies to anchor multi-channel electronic deployments. Specialized liquid handling vendors dominate high-throughput screening installations through application-specific engineering. Strategic moves concentrate on validation documentation capabilities and cloud-connected instrument ecosystems.
Among diversified life science platforms, Thermo Fisher Scientific and Danaher occupy positions spanning research and clinical laboratory segments. Eppendorf represents the focused specialist archetype with concentrated liquid handling expertise. These three anchors exemplify divergent competitive vectors: conglomerate breadth versus specialist depth in automated dispensing technology.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Danaher |
| Eppendorf |
| Hamilton Company |
| Sartorius |
| Mettler Toledo |
| Beckman Coulter |
| Analytik Jena |
| Others |
Value Network & Pricing Analysis
Ceramic piston sourcing from Thuringia and specialty Japanese suppliers anchors cost structures across electronic pipette tiers, with precision component scarcity propagating through premium pricing bands into mid-range configurations. Pharmaceutical quality control laboratories absorb validated-platform premiums while educational institutions face capital friction against functional manual installed bases.
Pricing Analysis
The bundled-vs-unbundled service split defines transaction economics in this market. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated electronic platforms with IQ/OQ/PQ documentation from configurable research-grade units and basic manual alternatives. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the educational segment intensifies because procurement committees negotiate unbundled calibration agreements with third-party ISO 17025 providers. Clinical diagnostic laboratories in China exhibit highest price sensitivity, while Swiss bioprocess facilities demonstrate lowest sensitivity due to GMP compliance mandates.
Supply Chain Analysis
Regional distribution centers in Massachusetts, Baden-Württemberg, and Shanghai orchestrate hub-and-spoke patterns for high-value electronic pipette deployments. Manufacturing concentration in Germany, Japan, and the United States draws from ceramic piston, precision motor, and optical sensor inputs. Single-source vulnerability in Thuringia ceramic suppliers exposes lead time risks for sub-one-percent coefficient-of-variation instruments. Distribution runs through direct vendor channels for pharmaceutical validation deployments and fragmented distributor networks for educational procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pipetting Systems Market functions as a stable compounder, with regulatory compliance mandates for electronic records and signatures driving steady replacement cycles across pharmaceutical and clinical laboratory infrastructure.
For Market Incumbents: Lock in service revenue streams by capturing recurring ISO 8655 calibration contracts before third-party metrology providers disintermediate manufacturer margins. Deepen backward integration into ceramic piston production to mitigate Thuringia supply concentration risks. Defend against cloud-connected instrument ecosystems from specialized entrants by accelerating Wi-Fi-enabled usage logging platform deployment. For New Entrants and Emerging Players: Direct-to-clinic digital channels in Chinese urban hospital networks offer the most penetrable route for electronic pipetting module adoption. Target diagnostic automation expansion in Shanghai and Beijing where NMPA registration pathways are tightening but demand acceleration outpaces incumbent capacity. Pursue subscription-based remote calibration monitoring as the go-to-market angle to bypass capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where validation documentation capabilities and cloud-connected instrument ecosystems concentrate competitive differentiation. The 5-10 year viability window favors platforms with FDA 21 CFR Part 11 and EMA Annex 15 compliance automation. Target acquisition archetypes: specialized liquid handling vendors with high-throughput screening application expertise. Watch for IQ/OQ/PQ validation expertise scarcity as the inflection signal indicating incumbent vulnerability to compliance-automation specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Instrument Ecosystem | Wi-Fi-enabled usage logging opens subscription revenue streams for manufacturers. |
| Validation Documentation Investment | Pre-packaged IQ/OQ/PQ protocols compress pharmaceutical procurement cycles. |
| Ceramic Piston Backward Integration | In-house precision component production mitigates Thuringia supply vulnerability. |
| Diagnostic Automation Partnership | Chinese hospital network alliances accelerate electronic pipetting module adoption. |
| Third-Party Calibration Service Acquisition | ISO 17025-accredited metrology provider purchases defend service revenue margins. |
Research Methodology
Direct dialogue with pharmaceutical quality control directors, clinical laboratory managers, contract research organization procurement leads, and third-party metrology service heads grounded qualitative insights. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA Annex 15 computerized systems guidelines, NMPA medical device classification rules, ISO 8655 calibration standards, and SEC filings from diversified life science conglomerates. Bottom-up and top-down triangulation reconciled instrument shipment data with end-user expenditure patterns.
Segment-level outputs across the projection horizon reflect product type, end user workflow, application protocol, and distribution channel dimensions. CAGRs were derived from regression analysis against pharmaceutical R&D expenditure, diagnostic automation capex, and regulatory compliance investment trends. Forecast inputs incorporated genomics workflow automation rates and bioprocess GMP compliance expenditure trajectories.
Ceramic piston supply disruptions, regulatory harmonization delays between FDA and EMA digital data integrity frameworks, and diagnostic automation budget freezes in Chinese hospital networks are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
North America and Europe Medical Technology Market
Medical Devices
Gum Grafting Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
GCC Implantable Medical Devices Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Medical Devices Vigilance Market
Medical Devices
Nitinol-Based Guide Wire Market
Medical Devices
Struts Implants Market
Medical Devices
EEG Electrodes Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Deflectable Catheters Market
Medical Devices
Patient Warming Devices Market