
 Implantable Medical Devices Market | 2026-2036
Implantable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Medical Devices Market Analysis
A capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is redrawing competitive boundaries in implantable medical devices. Medtronic leverages captive semiconductor foundry relationships to secure neurostimulator chip supply. Boston Scientific differentiates through catheter-based delivery system expertise that spans cardiac and peripheral vascular applications.
Implantable medical devices are engineered systems designed for long-term residence within human tissue, typically incorporating biocompatible titanium enclosures, platinum-iridium electrodes, and hermetic sealing rated for decade-long service life. These devices monitor, regulate, or replace physiological functions through continuous electrical, chemical, or mechanical intervention. Cardiac devices generate the largest revenue pool given recurring generator replacement cycles and lead extraction complexity. Orthopedic implants in metals and ceramics command premium pricing tied to bearing surface longevity and osseointegration performance. Neuromodulation devices represent the fastest-expanding segment as spinal cord stimulation and deep brain stimulation broaden their approved indications.
The FDA's Class III premarket approval framework and the EU MDR's strengthened clinical evaluation requirements impose multi-year validation horizons that favor incumbents with established quality management systems. Japan's PMDA and South Korea's MFDS maintain distinct biocompatibility testing protocols that fragment regulatory submission strategies. Stakeholders must weigh reimbursement velocity against regulatory capital commitments when prioritizing geographic launch sequencing.
Market Dynamics
EU MDR's post-market surveillance mandates and FDA's cybersecurity guidance are compressing product lifecycles and forcing manufacturers to redesign legacy platforms for continuous monitoring capabilities rather than discrete approval cycles.
Growth Catalysts
- Japan's PMDA fast-track pathway:Neuromodulation devices for Parkinson's disease receive priority review, accelerating commercialization timelines for deep brain stimulation systems in Tokyo and Osaka metropolitan corridors.
- Platinum-iridium electrode miniaturization:Semiconductor lithography techniques now fabricate neural interfaces below 50 microns, expanding addressable indications to chronic pain and epilepsy.
- South Korea's MFDS biocompatibility harmonization:Mutual recognition agreements with ISO 10993 standards reduce redundant testing for imported cardiac rhythm management devices.
Market Restraints
- Titanium enclosure supply concentration:Three specialized foundries in Germany and Switzerland control aerospace-grade titanium billet allocation, creating procurement bottlenecks for hermetic implant housings.
- FDA cybersecurity premarket requirements:Software bill of materials mandates and post-market vulnerability disclosure protocols extend validation timelines by 14-18 months for connected cardiac devices.
- Lead extraction surgical capacity:Declining numbers of electrophysiologists trained in transvenous lead removal restricts generator replacement volumes in community hospital settings.
Strategic Opportunities
- Closed-loop neuromodulation:Adaptive algorithms that adjust stimulation parameters based on real-time biomarker feedback open replacement markets for fixed-output spinal cord stimulators.
- India's CDSCO medical device rules expansion:Risk-based classification for implantables creates formal regulatory pathway where previous import dependence dominated cardiac device access.
- Direct-to-hospital procurement platforms:GPO-agnostic digital marketplaces bypass traditional distributor markups for high-volume orthopedic implant contracts.
Industry Challenges
- Biocompatibility testing talent scarcity:ISO 10993-18 chemical characterization expertise concentrates in contract research organizations with 6-month backlog for cytotoxicity validation.
- Legacy device cybersecurity retrofitting:Bluetooth Low Energy modules added to decade-old pacemaker architectures create unpatched attack surfaces that expose manufacturers to liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Medical Devices Market |
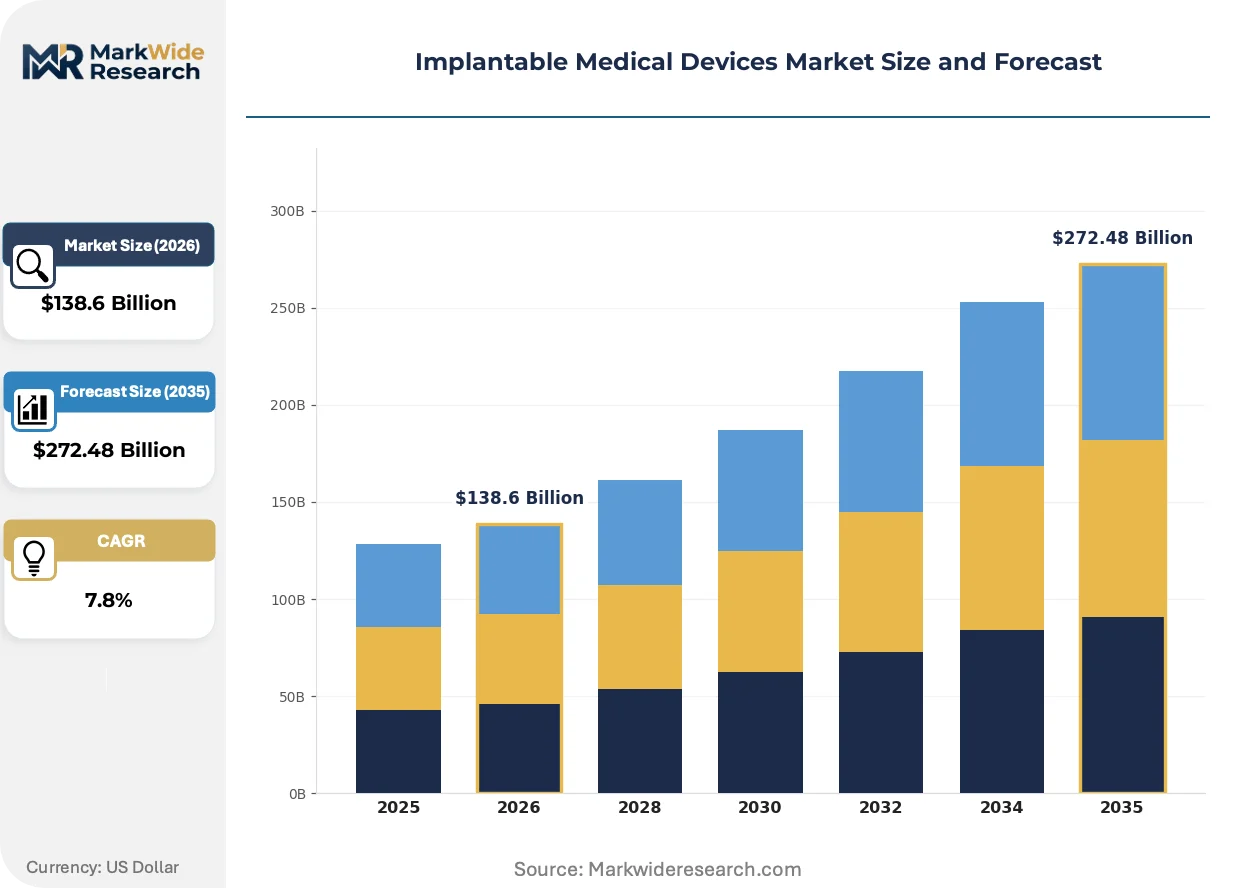
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $272.48 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Devices, Orthopedic Implants, Neuromodulation Devices, Drug Delivery Systems End User: Hospitals, Surgical Centers, Home Healthcare, Rehabilitation Centers Material: Metals, Polymers, Ceramics, Composites Application: Cardiology, Orthopedics, Neurostimulation, Pain Management |
| Companies Covered | Medtronic, Abbott Laboratories, Johnson & Johnson, Boston Scientific Corporation, Biotronik, Stryker, Cochlear, LivaNova PLC, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Medical Devices Market Emerging Trajectories
Material science breakthroughs and algorithmic control systems are redefining implant longevity and therapeutic precision, shifting competitive advantage from mechanical reliability to data-driven personalization.
Bioresorbable magnesium alloys are fragmenting the permanent orthopedic implant paradigm. Scaffolds for craniofacial reconstruction and pediatric applications eliminate secondary removal surgeries. Academic medical centers in Germany and Japan are piloting magnesium sternal closure devices. The technology is fragmenting procurement categories previously dominated by titanium and PEEK polymers.
EU MDR's Unique Device Identification mandate requires real-world performance tracking across the entire implant lifecycle. Manufacturers must submit annual safety reports and maintain technical documentation for 15 years post-market. Cardiac rhythm management devices face the steepest compliance burden due to lead-related adverse event complexity. Smaller competitors without established quality management systems are exiting the European market entirely.
Hospital value analysis committees now require total cost-of-ownership documentation before implant contract approval. Device longevity, revision probability, and explant complexity factor into purchasing decisions alongside upfront acquisition cost. This behavioral shift favors manufacturers with decade-long clinical evidence portfolios. The transformation is most pronounced in United States integrated delivery networks where orthopedic and cardiac implant spending undergoes centralized review.
Implantable Medical Devices Market Segmentation
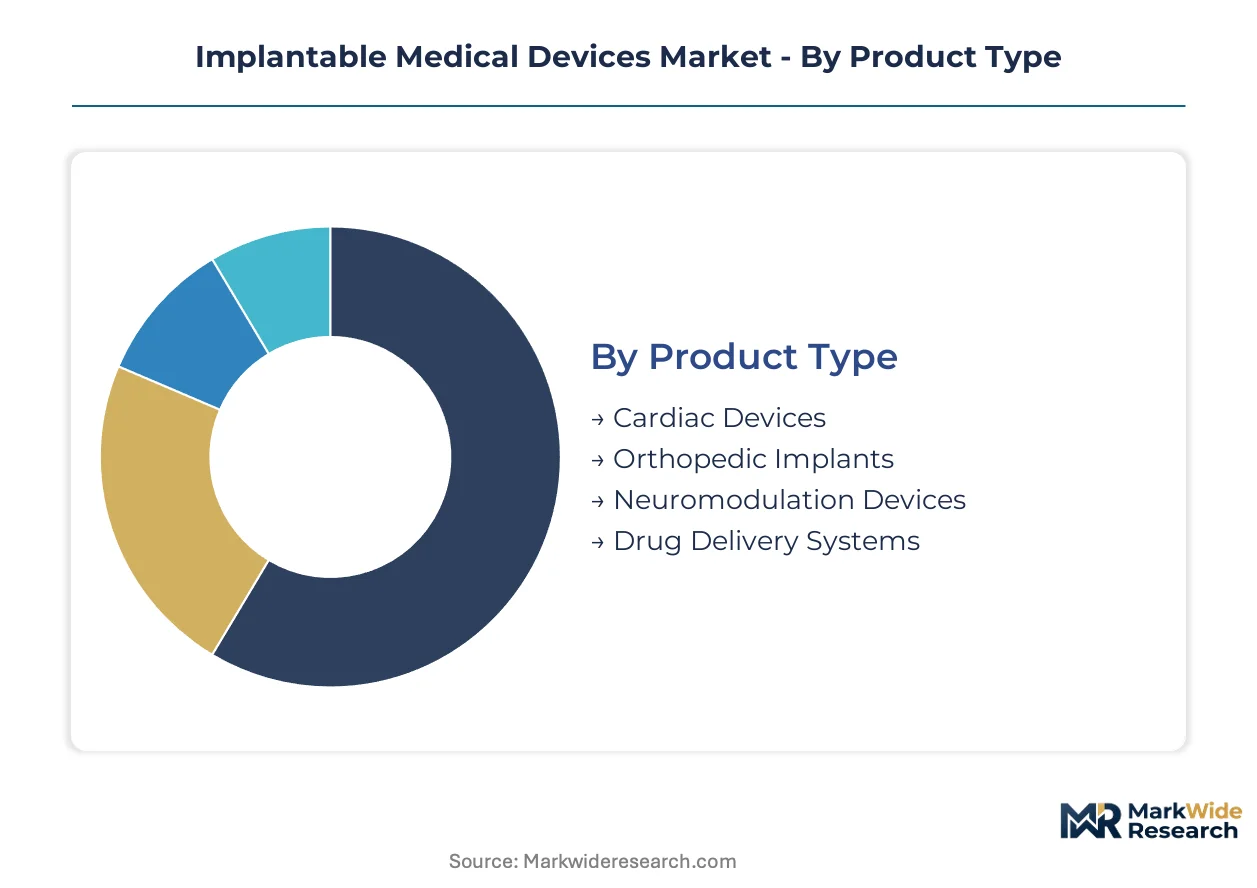
Segmentation in implantable medical devices reveals how substitution pressures and clinical workflow requirements reshape procurement priorities. Product longevity, biocompatibility profiles, and reimbursement coding complexity create divergent margin structures across categories.
Product Type:
Bioresorbable materials and catheter-based alternatives are fragmenting demand for permanent implantable hardware, with substitution pressure varying sharply by therapeutic domain.
- Cardiac Devices:Pacemakers and implantable cardioverter-defibrillators incorporate titanium enclosures with platinum-iridium electrodes rated for decade-long service life. Demand concentrates in United States integrated delivery networks where electrophysiologist capacity constraints restrict generator replacement volumes.
- Neuromodulation Devices:Spinal cord stimulators and deep brain stimulation systems deploy adaptive algorithms for real-time parameter adjustment. Japan's PMDA fast-track pathway for Parkinson's indications accelerates commercialization in Tokyo and Osaka metropolitan corridors.
- Orthopedic Implants:Hip and knee arthroplasty systems in cobalt-chrome and ceramic bearings command premium pricing tied to bearing surface longevity.
- Drug Delivery Systems:Implantable pumps and depot formulations enable localized therapeutic administration for chronic pain and hormonal regulation.
Cardiac devices retain volume leadership; neuromodulation devices hold the steepest expansion curve.
End User:
Procurement authority is consolidating toward centralized value analysis committees that prioritize total cost-of-ownership documentation over discrete acquisition metrics.
- Hospitals:Academic medical centers and community hospitals anchor implantable device procurement through structured tender processes. United States integrated delivery networks now mandate decade-long clinical evidence portfolios before contract approval.
- Surgical Centers:Ambulatory surgical facilities specialize in same-day implant procedures with compressed recovery protocols. Germany's outpatient cardiac rhythm management reimbursement codes enable generator replacements outside traditional hospital settings.
- Home Healthcare:Remote monitoring capabilities allow post-implant surveillance through Bluetooth-enabled telemetry systems.
- Rehabilitation Centers:Post-surgical recovery facilities coordinate neuromodulation parameter optimization and functional restoration protocols.
Hospitals dominate procurement volume; surgical centers are gaining share fastest through site-of-service shifts.
Material:
Biocompatibility testing backlogs and aerospace-grade supply concentration are forcing manufacturers to diversify material sourcing strategies.
- Metals:Titanium and cobalt-chrome alloys provide hermetic sealing and mechanical load-bearing capacity for structural implants. Three specialized foundries in Germany and Switzerland control aerospace-grade titanium billet allocation, creating procurement bottlenecks.
- Polymers:PEEK and silicone elastomers enable electrical insulation and flexible lead bodies in cardiac and neural applications. South Korea's MFDS biocompatibility harmonization with ISO 10993 standards reduces redundant testing requirements.
- Ceramics:Alumina and zirconia bearing surfaces deliver wear resistance for orthopedic weight-bearing applications.
- Composites:Carbon fiber-reinforced polymers and bioactive glass hybrids bridge mechanical and biological integration requirements.
Metals retain structural dominance; polymers are expanding most quickly through miniaturization-enabling flexibility.
Application:
Regulatory capital requirements and clinical evidence horizons segment manufacturers by therapeutic area specialization rather than platform breadth.
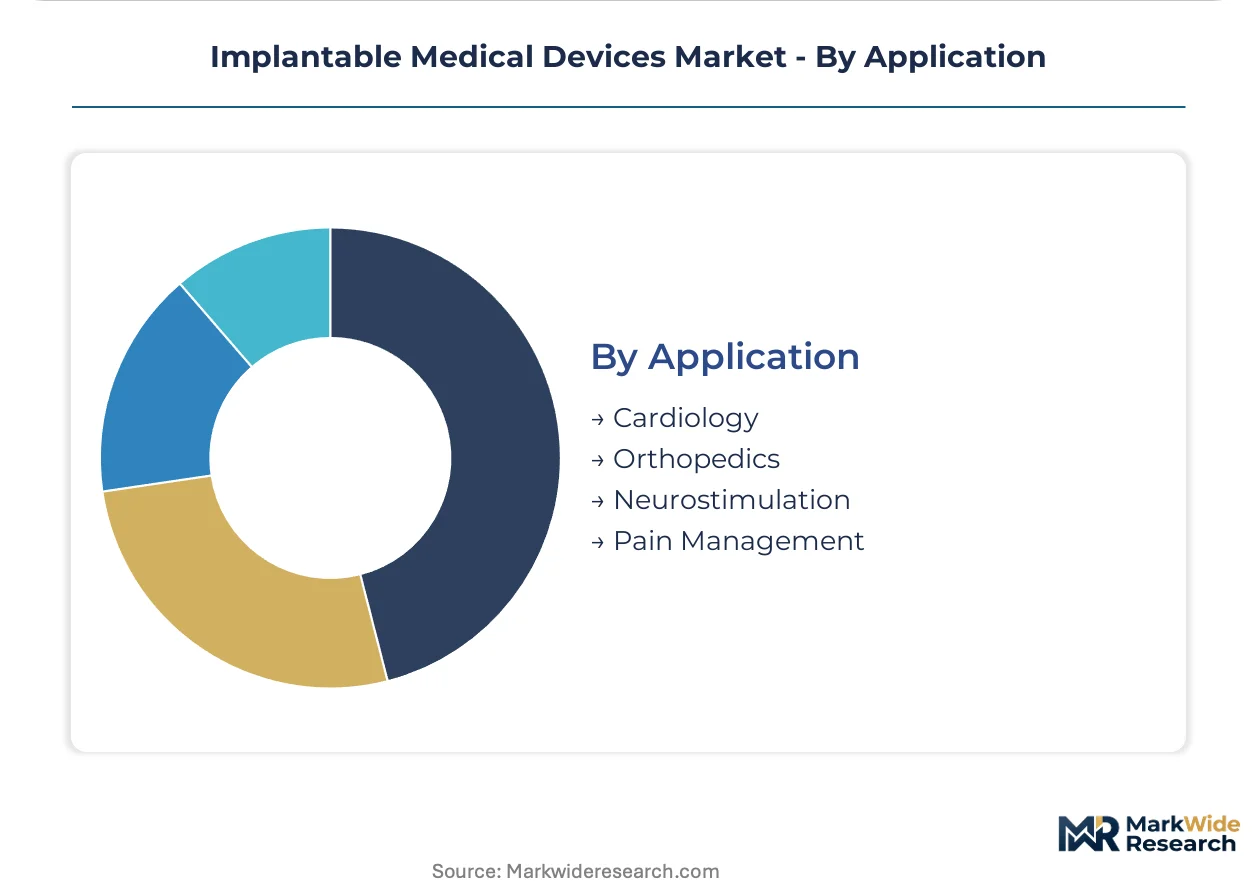
- Cardiology:Arrhythmia management and heart failure therapies generate recurring revenue through generator replacement cycles. FDA cybersecurity premarket requirements extend validation timelines by 14-18 months for connected cardiac devices.
- Neurostimulation:Deep brain stimulation and vagus nerve modulation address movement disorders and epilepsy through closed-loop control architectures. EU MDR's post-market surveillance mandates compress product lifecycles for legacy platform redesigns.
- Orthopedics:Joint reconstruction and spinal fixation systems compete on bearing surface longevity and osseointegration performance metrics.
- Pain Management:Spinal cord stimulation and peripheral nerve block systems target chronic refractory pain through electrical modulation protocols.
Cardiology commands the largest revenue pool; neurostimulation offers the steepest growth trajectory through indication expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Switzerland commands premium multiples for aerospace-grade titanium billet, while procurement costs in India and South Korea compress under biocompatibility harmonization pressures. This asymmetry shapes manufacturer margin structures across implantable device sourcing strategies.
United States
Integrated delivery networks in Texas and Florida concentrate cardiac rhythm management procurement through centralized value analysis committees. FDA cybersecurity premarket requirements extend validation timelines by 14-18 months for connected pacemakers and defibrillators. The Greater Boston corridor anchors electrophysiologist training programs that feed lead extraction surgical capacity into community hospital settings.
Germany
Specialized foundries in Bavaria and Baden-Württemberg control aerospace-grade titanium billet allocation for hermetic implant housings. EU MDR's Unique Device Identification mandate requires 15-year technical documentation retention for cardiac devices. The Rhine-Ruhr metropolitan region pilots magnesium sternal closure devices in academic medical centers, fragmenting procurement categories previously dominated by permanent titanium implants.
Japan
Stroke and arrhythmia incidence in Tokyo and Osaka metropolitan corridors drives neuromodulation and cardiac implant volumes. PMDA fast-track pathways prioritize Parkinson's disease indications for deep brain stimulation systems. The Kansai region hosts electrophysiology procedure volume growth that outpaces national replacement cycle averages.
South Korea
MFDS biocompatibility harmonization with ISO 10993 standards reduces redundant testing for imported cardiac rhythm management devices. Seoul Capital Area hospitals consolidate procurement authority through digital marketplace platforms that bypass traditional distributor markups. The Busan-Ulsan corridor concentrates polymer compounding capacity for flexible lead body manufacturing.
India
CDSCO medical device rules expansion creates formal regulatory pathways for implantables where previous import dependence dominated cardiac device access. Maharashtra and Gujarat host emerging contract research organizations with ISO 10993-18 chemical characterization capabilities. The Delhi-NCR corridor attracts neuromodulation device trials through accelerated ethics committee frameworks.
Implantable Medical Devices Market Vendor Landscape
Concentration sits with integrated manufacturers possessing captive semiconductor foundry relationships and established quality management systems. The vendor base stratifies across three tiers: diversified conglomerates with multi-therapeutic portfolios, mid-cap specialists with catheter-based delivery expertise, and regional assemblers dependent on outsourced component sourcing. Strategic moves center on backward integration into electrode material supply and adaptive algorithm licensing for closed-loop control architectures.
Among diversified medical technology conglomerates, Medtronic, Abbott Laboratories, and Boston Scientific Corporation occupy positions defined by neurostimulator chip supply security and catheter-based delivery system expertise. These entities exemplify the integrated manufacturer archetype through decade-long clinical evidence portfolios that satisfy hospital value analysis committee requirements. Mid-cap specialists including Biotronik and LivaNova PLC sit within the neuromodulation-focused tier, while orthopedic-centric players such as Stryker and Zimmer Biomet anchor reconstructive implant categories.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Biotronik |
| Stryker |
| Cochlear |
| LivaNova PLC |
| Zimmer Biomet |
| Others |
Supply Flow & Price Mechanics
EU MDR's Unique Device Identification mandate gates both supplier qualification and price differentiation simultaneously by requiring 15-year technical documentation retention that only established manufacturers can sustain. Hospital value analysis committees exploit this documentation burden to demand total cost-of-ownership discounts from vendors with decade-long clinical evidence portfolios.
Pricing Analysis
Configured-to-order pricing for patient-specific orthopedic implants commands 40-60% premiums over standard catalog sizes. Three-tier pricing structure across premium, standard, and economy levels stratifies by bearing surface longevity and osseointegration performance metrics. Cost compression in economy-tier cardiac rhythm management devices is intensifying because GPO-agnostic digital marketplaces bypass traditional distributor markups. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement codes, while academic medical centers prioritize longevity metrics over acquisition cost.
Supply Chain Analysis
Germany and Switzerland anchor aerospace-grade titanium billet production for hermetic implant housings. Manufacturing draws from platinum-iridium electrode feedstock, biocompatible polymer compounding, and semiconductor lithography equipment. Single-source vulnerability concentrates in three specialized foundries controlling titanium allocation. Distribution runs through group purchasing organizations and direct-to-hospital digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network procurement centralization that fragments vendor negotiation leverage. Hospital value analysis committees now mandate decade-long clinical evidence portfolios before contract approval.
For Market Incumbents: Consolidate backward integration into electrode material supply to secure neurostimulator chip allocation against foundry capacity constraints. Deepen captive semiconductor relationships before FDA cybersecurity premarket requirements extend validation timelines further. Lock in aerospace-grade titanium billet offtake agreements with Bavarian and Baden-Württemberg foundries. For New Entrants and Emerging Players: Differentiate on closed-loop neuromodulation algorithms that retrofit fixed-output spinal cord stimulators in Japan's PMDA fast-track pathway. Target India's CDSCO formal regulatory pathway where previous import dependence dominated cardiac device access. Pursue hospital system partnerships through remote monitoring capability bundling. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates exiting EU MDR compliance burdens for legacy cardiac rhythm management portfolios. Five-to-ten-year viability hinges on adaptive algorithm licensing revenue streams. Watch for electrophysiologist training program expansion as signal for lead extraction surgical capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Software bill of materials compliance accelerates connected cardiac device market access. |
| CE Marking Pathway | EU MDR clinical evaluation requirements reshape European commercialization timelines. |
| Hospital System Partnership | Integrated delivery network contracts bypass GPO markups for high-volume orthopedic implants. |
| Software Companion Development | Bluetooth-enabled telemetry systems enable post-implant remote monitoring revenue. |
| Reimbursement Strategy | Germany's outpatient cardiac rhythm management codes shift site-of-service economics. |
Methodological Framework
Cross-validation between hospital procurement databases and GPO contract filings anchors the qualitative findings on pricing dynamics. Primary interviews with electrophysiologists, biomedical engineers, hospital purchasing committees, and GPO contracts managers combine with secondary validation from FDA filings, EMA submissions, CMS Medicare data, and hospital procurement databases. Bottom-up device-level demand modeling and top-down market sizing triangulate volume estimates.
Sensitivity analysis across the projection horizon tests forecast robustness against regulatory timeline shifts and raw material supply disruptions. Segmentation dimensions include product type, end user, material composition, and therapeutic application. CAGRs derive from replacement cycle frequency, indication expansion rates, and reimbursement velocity by geography. Forecast inputs incorporate electrophysiologist training pipeline data and titanium foundry capacity utilization.
Forecasts assume regulatory continuity in FDA premarket approval and EU MDR frameworks; material policy shifts would require re-modeling. Specific risks include cybersecurity guidance timeline acceleration, biocompatibility testing backlog extension, and aerospace-grade titanium supply allocation disruption. Recalibration cycles align with material shifts in reimbursement coding and regulatory harmonization agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Band Ligators Market
Medical Devices
India Hemostats Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Intravaginal Device Market
Medical Devices
Global Biliary Stents Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
Needle-Free Vaccine Injectors Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Wearable Insulin Pump Market