
 Transcutaneous Electrical Nerve Stimulation Market | 2026-2036
Transcutaneous Electrical Nerve Stimulation Market Size, Share, and Industry Trends Forecast 2026-2036
Transcutaneous Electrical Nerve Stimulation Market Intelligence
Buyer concentration among physiotherapy clinics is expanding into fragmented home care channels as direct-to-consumer sales reshape distribution. Medtronic plc leverages its neurostimulation heritage to sustain clinical credibility across hospital procurement networks. Omron Healthcare competes through retail pharmacy dominance and consumer-brand recognition in Asia-Pacific markets.
Transcutaneous electrical nerve stimulation delivers pulsed electrical currents through surface electrodes to modulate nociceptive signaling, typically operating at frequencies between 1-150 Hz and pulse widths of 50-200 microseconds for therapeutic analgesia. Portable units anchor volume sales due to Medicare and private payer coverage for at-home chronic pain management, while wearable devices represent the fastest-growing product category as microelectronics miniaturization enables continuous ambulatory therapy. Conventional TENS technology dominates installed base maintenance, though burst mode TENS captures premium positioning among sports medicine specialists seeking improved neuromuscular recruitment patterns.
FDA 510(k) premarket notification requirements govern device clearance timelines in the United States, while EU MDR and CE marking obligations extend conformity assessment burdens for European market access. Japan's PMDA enforces QMS Ministerial Ordinance standards that foreign manufacturers must satisfy through in-country representation. Stakeholders must monitor evolving reimbursement coding decisions by CMS and analogous national health technology assessment bodies that determine whether home use qualifies for durable medical equipment benefits.
Market Dynamics
Patient migration from clinical settings toward self-managed pain protocols is compressing traditional physiotherapy procurement cycles and forcing manufacturers to reconfigure distribution networks around direct-to-consumer channels.
Growth Catalysts
- Medicare Durable Medical Equipment Coverage:CMS reimbursement codes for at-home TENS units eliminate out-of-pocket barriers for chronic pain patients in the United States, accelerating household penetration.
- Microelectronics Miniaturization:Advances in flexible printed circuit boards and low-power Bluetooth chipsets enable wearable form factors that maintain therapeutic output while supporting continuous ambulatory use.
- Germany's Statutory Health Insurance:G-BA assessment procedures recognize TENS as a reimbursable non-pharmacological pain intervention, institutionalizing device prescriptions through general practitioner networks.
Market Restraints
- Silver Price Volatility:Conductive hydrogel electrodes rely on silver chloride coatings, and London Bullion Market Association pricing swings directly compress gross margins on consumable electrode packs.
- Single-Source ASIC Dependency:Pulse-width modulation integrated circuits for precision waveform control concentrate among Taiwanese semiconductor foundries, creating supply vulnerability.
- EU MDR Technical Documentation Burden:Extended conformity assessment timelines for Class IIa medical devices delay product launches by 12-18 months compared to previous Medical Device Directive pathways.
Strategic Opportunities
- Japan's Aging Rural Populations:Prefectures with elderly concentration exceeding 35% present underserved demand for telehealth-integrated TENS monitoring through municipal health cooperatives.
- Neuromuscular Electrical Stimulation Convergence:Hybrid devices combining TENS analgesia with NMES muscle activation protocols capture premium positioning among sports medicine clinics.
- Pharmacy E-Commerce Direct Distribution:Amazon Pharmacy and Walgreens digital platforms bypass durable medical equipment middlemen, capturing margin previously allocated to regional distributors.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Design of closed-loop adaptive stimulation algorithms requires specialized expertise in neurophysiological signal processing that outpaces university pipeline output.
- FDA 510(k) Predicate Device Drift:Substantial equivalence determinations increasingly require clinical data packages as predicate devices age beyond ten years, extending submission preparation cycles.
- Legacy Hospital Procurement System Integration:Enterprise resource planning compatibility with Epic and Cerner electronic health record platforms demands custom API development for prescription-to-delivery workflow automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcutaneous Electrical Nerve Stimulation Market |
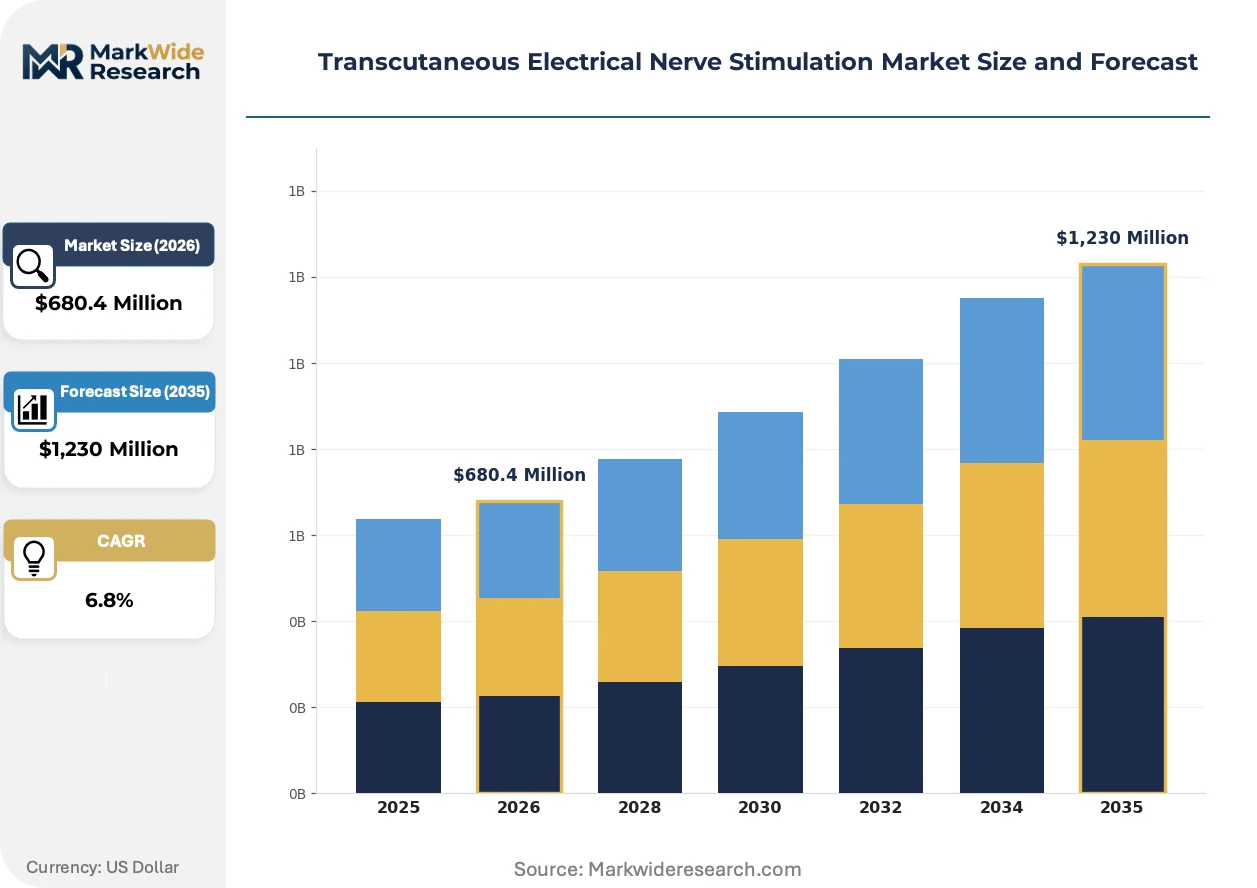
| Market Size in 2026 | $680.4 Million |
| Market Size in 2035 | $1,230 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Desktop Units, Security Devices, Wearable Devices End User: Home Care, Physiotherapy Clinics, Rehabilitation Centers, Hospitals Technology: Conventional TENS, Burst Mode TENS, Interferential Current, High-Voltage Pulsed Current Application: Pain Management, Muscle Rehabilitation, Postoperative Care, Sports Injuries |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Omron Healthcare, Nevro Corp., DJO Global, Zynex Medical, NeuroMetrix, BTL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcutaneous Electrical Nerve Stimulation Market Strategic Shifts & Innovations
Wearable TENS technology is collapsing the distinction between acute clinical intervention and continuous lifestyle-integrated therapy, forcing incumbents to compete on software ecosystems rather than hardware specifications alone.
Closed-loop adaptive stimulation algorithms are rewriting competitive positioning in the premium device tier. These systems modulate pulse parameters in real-time based on skin impedance feedback and accelerometer-derived activity levels. Pain management clinics in the United States are piloting prescription models around these devices. The technology is compressing differentiation timelines as software update cycles replace hardware refresh cycles.
EU MDR post-market surveillance requirements are tightening evidence-generation obligations for existing CE-marked devices. Manufacturers must now maintain systematic literature review protocols and periodic safety update reports beyond initial conformity assessment. German notified bodies are enforcing clinical evaluation report standards most stringently, pushing smaller competitors toward third-party regulatory consultancy dependencies.
Subscription-based electrode replenishment programs are displacing one-time consumable purchases in direct-to-consumer channels. Patients receiving automated monthly hydrogel pad shipments demonstrate 40% higher twelve-month retention than transactional buyers. This model concentrates in United States metropolitan markets where Amazon Subscribe and Save infrastructure supports logistics scale.
Transcutaneous Electrical Nerve Stimulation Market Segmentation
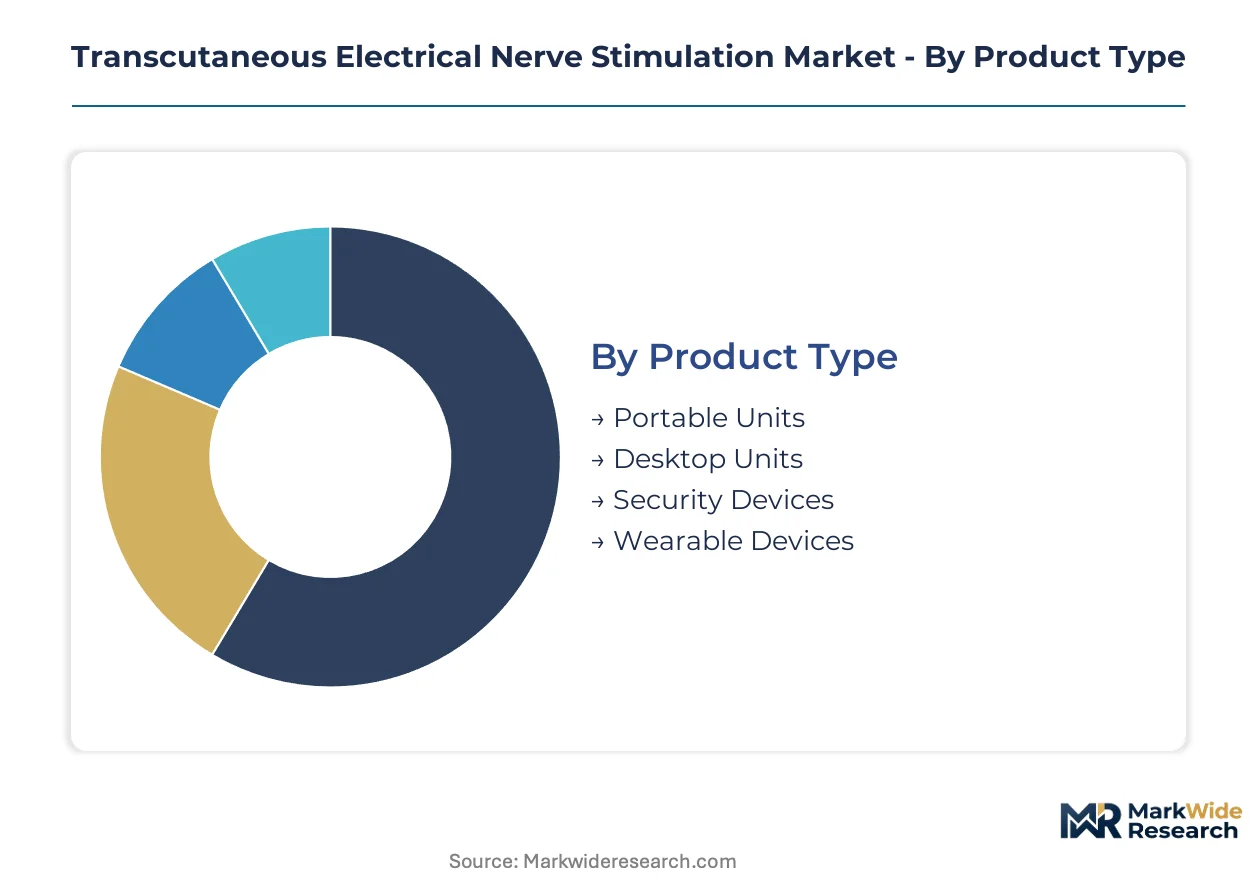
Segmentation in the TENS market reveals divergent engineering priorities across clinical and consumer environments. Product architecture, stimulation protocols, and distribution channels fragment sharply between institutional procurement and direct-to-consumer channels.
Product Type:
Customization intensity spans from FDA-validated prescription hardware to mass-market consumer electronics, with regulatory burden and margin structure inversely correlated across the spectrum.
- Wearable Devices:Flexible printed circuit assemblies and low-power Bluetooth chipsets enable continuous ambulatory therapy. Medicare reimbursement for at-home chronic pain management in the United States accelerates household penetration of patch-style and belt-integrated form factors.
- Portable Units:Handheld battery-operated devices with preset waveform programs dominate durable medical equipment procurement. Germany's G-BA assessment procedures institutionalize prescriptions through general practitioner networks, sustaining volume demand.
- Desktop Units:Multi-channel clinical workstations with programmable parameters serve hospital physiotherapy departments.
- Security Devices:Tamper-proof and patient-monitoring integrated systems address controlled-substance diversion protocols in institutional settings.
Most installed capacity flows through Portable Units. Expansion is steepest in Wearable Devices.
End User:
Procurement authority decentralizes from hospital supply chains toward patient-directed purchasing, compressing traditional distributor margins and forcing direct-to-consumer infrastructure investment.
- Home Care:Patients self-manage chronic pain protocols outside clinical supervision. CMS durable medical equipment coverage in the United States eliminates out-of-pocket barriers, while Japan's aging rural prefectures drive telehealth-integrated monitoring demand.
- Physiotherapy Clinics:Outpatient rehabilitation facilities prescribe device rental-to-purchase pathways. Burst mode TENS and interferential current modalities command premium positioning among sports medicine specialists seeking neuromuscular recruitment optimization.
- Rehabilitation Centers:Post-acute inpatient facilities deploy multi-patient systems with centralized monitoring.
- Hospitals:Acute care settings prioritize enterprise resource planning integration with Epic and Cerner electronic health record platforms.
Revenue concentration remains with Physiotherapy Clinics. Patient migration is accelerating fastest in Home Care.
Technology:
Intellectual property differentiation clusters around waveform modulation algorithms, with closed-loop adaptive systems commanding research and development investment priority.
- Conventional TENS:Fixed-frequency pulsed current between 1-150 Hz with 50-200 microsecond pulse widths constitutes the installed base standard. Maintenance demand from aging device populations in the United States and Germany sustains replacement electrode consumption.
- Burst Mode TENS:Trains of high-frequency pulses delivered at low-frequency intervals enhance neuromuscular recruitment. Sports medicine clinics in Japan and the United States adopt these systems for athletic performance protocols.
- Interferential Current:Crossed medium-frequency carriers generate beat-frequency stimulation for deeper tissue penetration.
- High-Voltage Pulsed Current:Monophasic waveforms with peak voltages exceeding 150V address wound healing and edema reduction applications.
Conventional TENS carries the largest installed base. Burst Mode TENS is gaining share fastest among premium-tier purchasers.
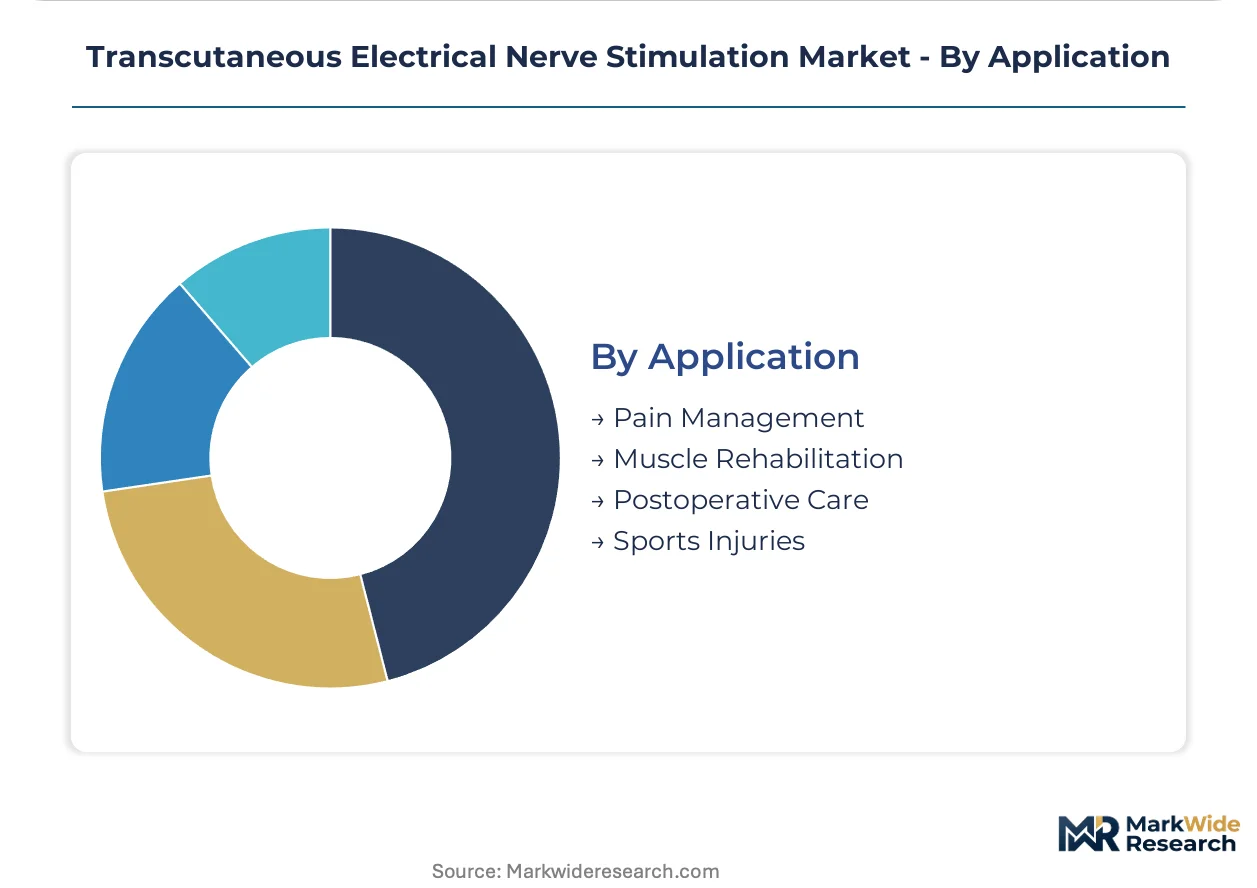
Application:
Clinical evidence requirements vary sharply by indication, with chronic pain management enjoying established reimbursement codes while emerging applications face health technology assessment scrutiny.
- Pain Management:Chronic lower back pain, osteoarthritis, and neuropathic conditions constitute the primary reimbursed indication. Germany's statutory health insurance recognizes TENS as a non-pharmacological intervention, institutionalizing device prescriptions.
- Muscle Rehabilitation:Post-stroke and post-surgical neuromuscular re-education protocols drive institutional procurement. Hybrid devices combining TENS analgesia with NMES activation capture premium positioning in Japanese rehabilitation centers.
- Postoperative Care:Acute pain management protocols in hospital settings reduce opioid consumption.
- Sports Injuries:Athletic training facilities adopt portable and wearable systems for acute injury management and recovery acceleration.
Pain Management dominates prescription volume. Muscle Rehabilitation shows the steepest expansion trajectory as aging populations drive stroke rehabilitation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Germany in home care device penetration, while Japan's aging rural prefectures generate distinct telehealth integration demand that diverges from Western prescription pathways.
United States
Medicare durable medical equipment coverage eliminates out-of-pocket barriers for chronic pain patients, accelerating household penetration of portable and wearable units. FDA 510(k) premarket notification requirements govern clearance timelines, with predicate device drift extending submission preparation cycles. Pain management clinics in Florida and Texas pilot closed-loop adaptive stimulation prescriptions, compressing differentiation timelines as software updates replace hardware refreshes.
Germany
Statutory health insurance through G-BA assessment procedures institutionalizes TENS prescriptions through general practitioner networks, sustaining volume demand for portable units. EU MDR technical documentation burdens delay product launches by 12-18 months compared to previous Medical Device Directive pathways. Notified bodies in Munich and Stuttgart enforce clinical evaluation report standards most stringently, pushing smaller competitors toward third-party regulatory consultancy dependencies.
Japan
Prefectures with elderly concentration exceeding 35% present underserved demand for telehealth-integrated TENS monitoring through municipal health cooperatives. PMDA enforces QMS Ministerial Ordinance standards that foreign manufacturers must satisfy through in-country representation. Rehabilitation centers in Osaka and Nagoya adopt hybrid devices combining TENS analgesia with NMES activation, capturing premium positioning in post-stroke protocols.
United Kingdom
NHS England technology appraisal processes determine reimbursement eligibility for chronic pain management devices, creating procurement concentration among approved suppliers. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while introducing separate UKCA marking obligations. London and Manchester physiotherapy networks drive burst mode TENS adoption among sports medicine specialists seeking neuromuscular recruitment optimization.
Australia
TGA conformity assessment procedures for Class IIa medical devices align with EU MDR evidence requirements, streamlining market access for CE-marked manufacturers. Private health insurance coverage for non-pharmacological pain interventions supplements Medicare reimbursement gaps. Sydney and Melbourne pain clinics integrate wearable TENS with telehealth monitoring platforms, extending prescription continuity beyond clinical encounters.
Transcutaneous Electrical Nerve Stimulation Market Key Industry Players
United States producers anchor the premium clinical tier; Japanese and German specialists hold consumer and rehabilitation segments respectively. The vendor base concentrates among neurostimulation heritage conglomerates, diversified medical technology groups, and focused pain management device specialists. Three archetypes dominate: institutional procurement incumbents leveraging FDA credibility, retail pharmacy channel masters capturing direct-to-consumer volume, and adaptive algorithm innovators rewriting premium positioning. Competitive moves center on M&A for neurostimulation IP portfolios and direct-to-consumer infrastructure buildouts bypassing durable medical equipment middlemen.
Within the institutional procurement tier, Medtronic plc and Boston Scientific Corporation represent neurostimulation heritage anchors sustaining hospital network credibility. Abbott Laboratories occupies a diversified medical technology position spanning prescription and consumer channels. Omron Healthcare exemplifies the retail pharmacy channel mastery archetype, with consumer-brand recognition driving Asia-Pacific volume capture.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Omron Healthcare |
| Nevro Corp. |
| DJO Global |
| Zynex Medical |
| NeuroMetrix |
| BTL |
| Others |
Cost & Logistics Intelligence
London Bullion Market Association silver pricing cascades through TENS electrode manufacturing, compressing gross margins on consumable hydrogel packs and forcing tiered pricing stratification across premium clinical-grade and economy direct-to-consumer channels.
Pricing Analysis
Capacity additions in Vietnam and Malaysia are reshaping price floors for flexible printed circuit assemblies, enabling wearable device manufacturers to undercut legacy portable unit pricing by fifteen to twenty percent at equivalent therapeutic output specifications. Three-tier pricing structure across premium adaptive-algorithm, standard programmable, and economy fixed-waveform levels separates closed-loop prescription devices from retail pharmacy entry units. Pricing pressure stems from silver chloride coating cost volatility on electrode consumables. Home care patients demonstrate highest price sensitivity, while hospital procurement committees prioritize FDA 510(k) clearance tier over unit economics.
Supply Chain Analysis
Biomedical engineering talent scarcity in Shenzhen and Dongguan constrains pulse-width modulation ASIC design capacity, forcing lead time extensions for precision waveform control components. Taiwan, South Korea, and Japan anchor semiconductor foundry output for stimulation integrated circuits. Conductive hydrogel formulations draw from silver chloride, acrylic acid polymers, and medical-grade adhesives sourced through Japanese chemical specialists. Single-source dependency on Taiwanese foundries creates vulnerability to trade restriction scenarios. Distribution runs through durable medical equipment distributors, direct-to-consumer e-commerce platforms, and retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory milestones into demand inflections, with EU MDR Class IIa device transitions and CMS durable medical equipment coding decisions serving as primary demand amplifiers across the analysis window.
For Market Incumbents: Extend software ecosystem lock-in through closed-loop adaptive algorithm subscriptions that collapse hardware replacement cycles and defend against wearable device entrants. Fortify positions by deepening backward integration into flexible printed circuit assembly production in Vietnam, insulating margin from Taiwanese foundry concentration. Prioritize FDA 510(k) predicate device refresh strategies to preempt clinical data package requirements.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in wearable TENS creates white-space opportunity for mid-tier entrants offering prescription-grade waveform precision at direct-to-consumer price positioning. Target Japan's aging rural prefectures with telehealth-integrated monitoring solutions through municipal health cooperative procurement channels. Capture share via pharmacy e-commerce platform partnerships that bypass durable medical equipment distributor margin extraction.
For Investors and Strategic Acquirers: Asymmetric upside sits with adaptive algorithm specialists possessing neurophysiological signal processing IP and existing FDA 510(k) clearances for closed-loop systems. Five-to-ten year viability hinges on reimbursement code expansion for home-use indications. Monitor CMS National Coverage Determination proceedings for ambulatory TENS as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment timelines determine competitive entry sequencing for European markets. |
| Software Companion Development | Bluetooth-integrated mobile applications enable subscription-based electrode replenishment revenue models. |
| Hospital System Partnership | Epic and Cerner EHR integration secures prescription-to-delivery workflow automation contracts. |
| Reimbursement Strategy | G-BA assessment procedures in Germany institutionalize general practitioner prescription pathways. |
| FDA Submission | 510(k) substantial equivalence determinations govern clearance timelines for predicate device refreshes. |
Research Approach
Multiple input streams — regulatory filing databases, hospital procurement contract records, and semiconductor foundry capacity disclosures — were reconciled against primary interviews with biomedical engineers, pain management clinicians, durable medical equipment distributors, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body registers, CMS Medicare durable medical equipment fee schedules, and Japan PMDA QMS Ministerial Ordinance compliance listings. Bottom-up device shipment estimates and top-down healthcare expenditure allocations were triangulated across the analysis window.
Historical manufacturer revenue disclosures were cross-referenced against panel input from procurement officers at physiotherapy clinic chains and retail pharmacy category managers. Segmentation modeling spanned product architecture, stimulation protocol technology, end-user environment, and regional reimbursement framework dimensions. CAGRs were derived from regression analysis of installed base replacement cycles and expansion coefficients for wearable form factor adoption. Forecast inputs incorporated silver price trajectory assumptions and EU MDR transition timeline scenarios.
Caveats apply where FDA predicate device drift requirements, Taiwan semiconductor export restrictions, or CMS coding reversals could materially shift the outlook. Forecasts reflect documented assumptions regarding reimbursement continuity and foundry capacity expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Ocular Implants Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Active Wheelchair Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Bone Fixation Plates Market