
 Needle-Free Drug Delivery Devices Market | 2026-2036
Needle-Free Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Needle-Free Drug Delivery Devices Market Intelligence
ISO 13485 certification cycles for medical device quality management is collapsing from three-year to annual surveillance intervals, raising barriers for new entrants. PharmaJet sustains jet injector manufacturing scale across North American and European distribution networks. Antares Pharma differentiates through spring-powered autoinjector technology leadership in hormone therapy delivery. 3M dominates microneedle patch R&D intensity with extensive polymer science capabilities.
Needle-free drug delivery devices employ spring-loaded, gas-powered, or piezoelectric mechanisms to propel liquid or powder formulations through skin or mucosal barriers at velocities exceeding 100 meters per second, eliminating conventional hypodermic needles. These systems serve primary commercial purposes in mass immunization campaigns, chronic disease self-management, and biologics administration where needle phobia or sharps disposal constraints limit conventional approaches. Jet injectors anchor the product type landscape with established clinical validation and hospital procurement contracts, while microneedle patches represent the fastest-growing segment as dissolving arrays enable thermostable vaccine distribution without cold chain infrastructure. Home care end users command expanding margin pools as reimbursement frameworks shift toward outpatient administration models.
FDA 510(k) clearance requirements and CE marking under the EU Medical Device Regulation shape device design specifications, clinical evidence thresholds, and post-market surveillance obligations for manufacturers seeking commercial access. EMA's evolving position on needle-free biologics bioequivalence is forcing companies to generate comparative pharmacokinetic data against conventional injection benchmarks. Stakeholders must monitor how FDA draft guidance on interchangeable needle-free products reshapes competitive positioning and investment priorities for platform technologies.
Market Dynamics
ISO 13485 surveillance interval compression from three-year to annual cycles is restructuring competitive entry barriers, forcing smaller device manufacturers to absorb recurring certification costs or exit procurement pipelines entirely.
Growth Catalysts
- Home Care Administration:Reimbursement frameworks in the United States and Germany now explicitly cover outpatient needle-free biologics delivery, shifting chronic disease management from clinical settings to patient-controlled environments.
- EMA Bioequivalence Pathways:The European Medicines Agency's evolving guidance on needle-free biologics comparability is accelerating regulatory clarity for platform developers seeking CE marking under the EU Medical Device Regulation.
- Piezoelectric Propulsion:Solid-state actuation mechanisms eliminate compressed gas dependencies, enabling portable jet injector designs that operate across variable temperature conditions without mechanical degradation.
Market Restraints
- Polymer Feedstock Volatility:Medical-grade polycarbonate and cyclic olefin polymer prices fluctuate with petrochemical input costs, compressing margins for microneedle array manufacturers dependent on precision molding.
- Single-Source Component Risk:High-velocity nozzle fabrication concentrates among Japanese and German precision machining suppliers, creating geographic chokepoints for jet injector production scaling.
- Skin Penetration Consistency:Interpatient variability in stratum corneum thickness and elasticity limits dose reproducibility for powder-based transdermal systems, constraining therapeutic categories where pharmacokinetic precision matters.
Strategic Opportunities
- Rural India Distribution:Cold chain infrastructure gaps in subnational regions create demand for thermostable dissolving microneedle vaccines that bypass refrigeration requirements entirely.
- Hormone Therapy Self-Administration:Spring-powered autoinjector platforms originally developed for insulin delivery are migrating into fertility and endocrine applications where needle phobia drives switching behavior.
- FDA Interchangeability Designation:Draft guidance on substitutable needle-free products is creating first-mover advantages for manufacturers that generate comparative pharmacokinetic datasets against conventional injection benchmarks.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 14-24 month completion timelines, delaying market entry for novel polymer formulations in microneedle substrates.
- Legacy Health Record Integration:Hospital procurement systems lack standardized device identification codes for needle-free delivery platforms, forcing manual inventory reconciliation that slows adoption in integrated delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Needle-Free Drug Delivery Devices Market |
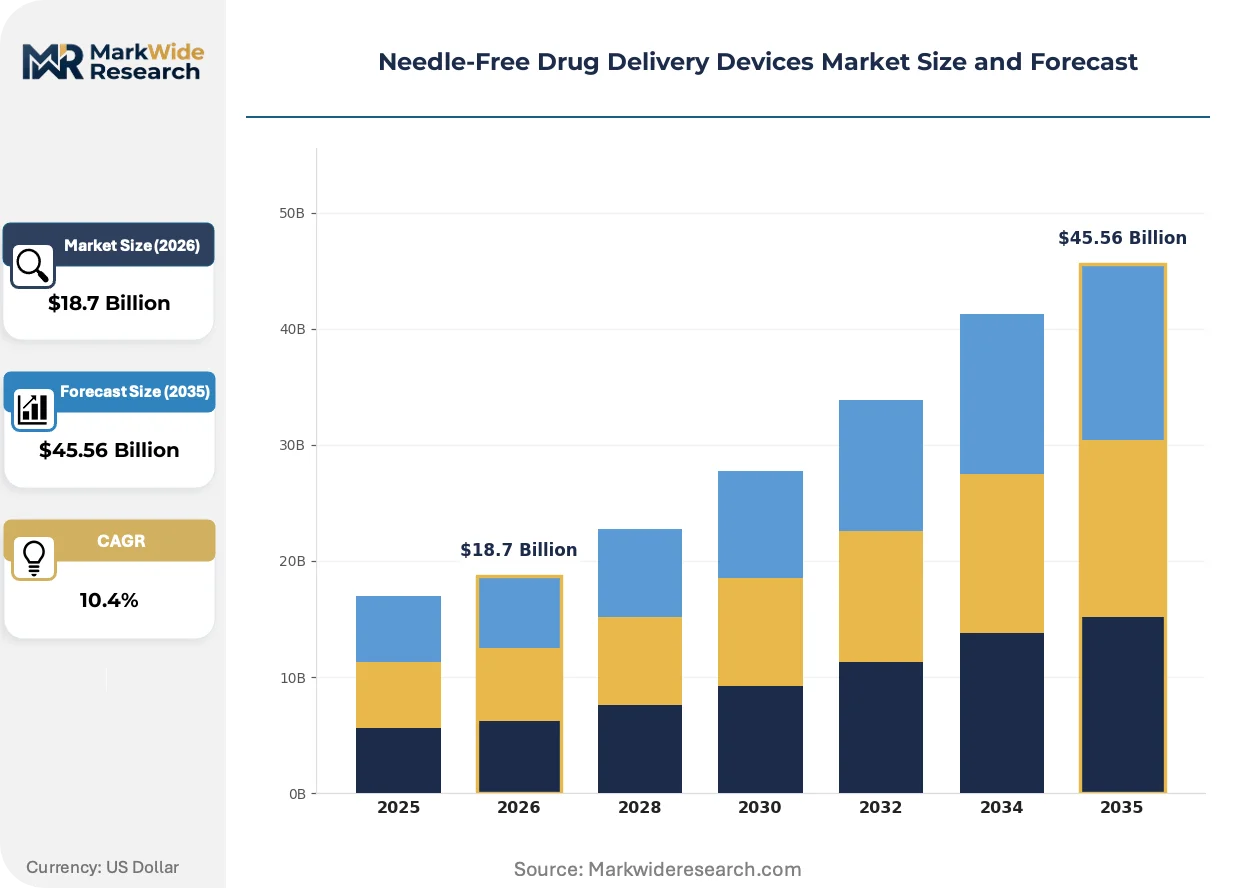
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $45.56 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jet Injectors, Microneedle Patches, Inhalers, Nasal Sprays End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Mode: Transdermal, Intranasal, Inhalation, Intravenous Regulation: FDA Approved, CE Marked, Others, Under Review |
| Companies Covered | PharmaJet, Antares Pharma, 3M, Crossject SA, Portal Instruments Inc., Injex Pharma AG, West Pharmaceutical Services, Vaxxas Pty Ltd, Medical International Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Needle-Free Drug Delivery Devices Market Strategic Shifts & Innovations
Device architecture is fragmenting across competing propulsion philosophies, with gas-powered legacy systems defending hospital contracts while piezoelectric and spring-loaded alternatives capture outpatient and self-administration segments.
Microneedle patch technology is bifurcating between dissolving polymer arrays for vaccine distribution and hydrogel-forming designs for sustained drug release. Pediatric immunization programs in low-resource settings are adopting dissolving formats at accelerated procurement cycles. This divergence is compressing R&D investment into platform-specific manufacturing rather than universal device architectures.
The FDA's draft guidance on interchangeable needle-free biologics is forcing manufacturers to redesign clinical trial protocols around comparative pharmacokinetic endpoints. Sponsors must now demonstrate bioequivalence against reference listed drugs administered via conventional needles. Small-cap platform developers lacking in-house regulatory affairs capacity are outsourcing submission preparation to specialized consulting firms in the Washington DC corridor.
Patient-administered chronic disease management is displacing clinic-based injection protocols across diabetes, multiple sclerosis, and growth hormone deficiency categories. Specialty pharmacies are capturing device dispensing margins previously retained by hospital outpatient departments. This channel migration is most visible in United States commercial insurance markets where copay structures favor mail-order distribution over facility-based administration.
Needle-Free Drug Delivery Devices Market Segmentation
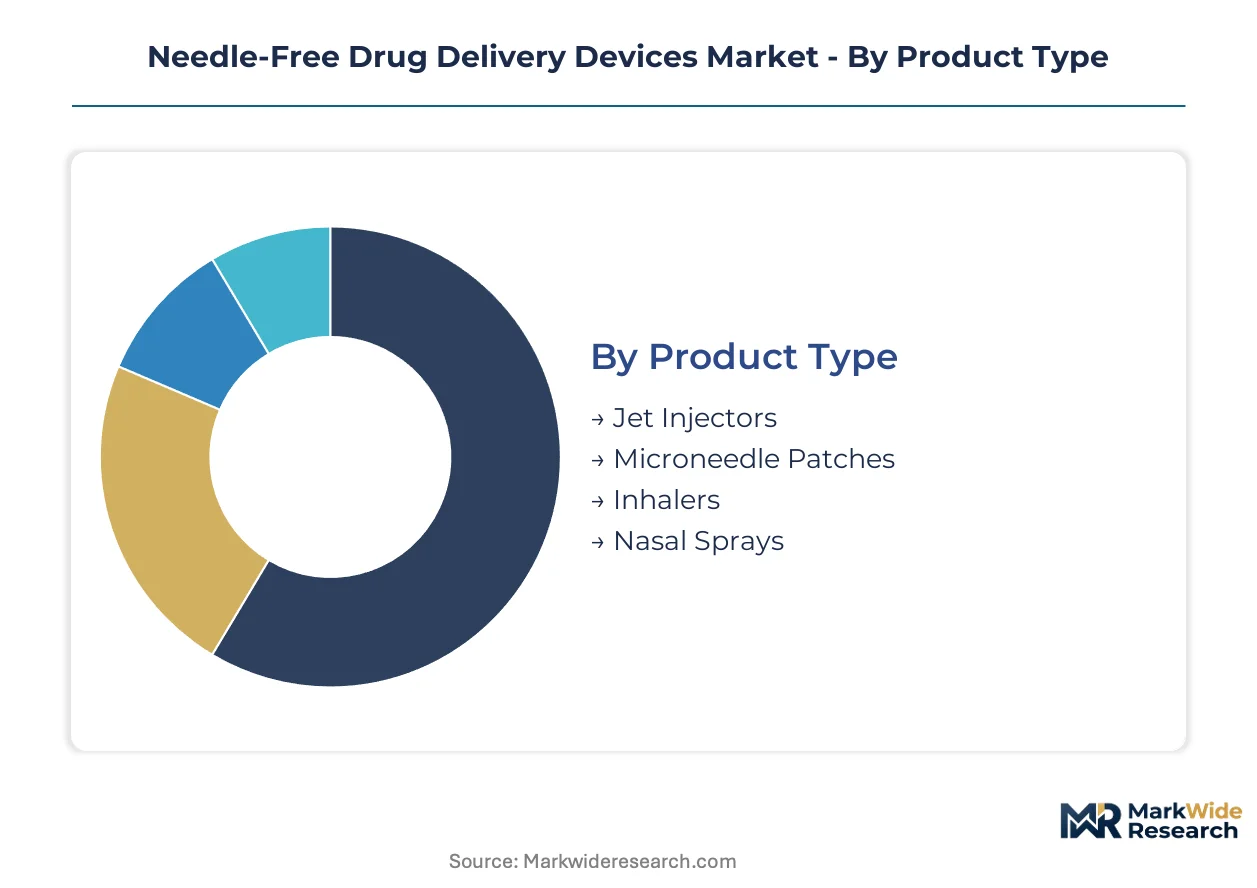
Needle-free delivery platforms fragment across propulsion mechanisms, clinical settings, and regulatory jurisdictions. Each segmentation dimension reveals distinct margin structures and geographic concentration patterns that shape manufacturer investment priorities.
Product Type:
Jet injectors dominate hospital procurement in the United States and Germany where established clinical validation supports premium pricing. Microneedle patches export most heavily to low-resource regions lacking cold chain infrastructure.
- Jet Injectors:Gas-powered and spring-loaded systems propel liquid formulations through precision-engineered nozzles at velocities exceeding 100 meters per second. Demand concentrates in United States hospital systems and German university medical centers where bulk immunization contracts and chronic disease protocols favor established clinical evidence bases.
- Microneedle Patches:Dissolving polymer arrays and hydrogel-forming designs enable thermostable biologics distribution without refrigeration. Export-led growth accelerates toward rural India and sub-Saharan Africa where last-mile cold chain gaps constrain conventional vaccine delivery; pediatric immunization programs drive procurement volume.
- Inhalers:Pressurized metered-dose and dry-powder devices deliver respiratory therapies through pulmonary deposition.
- Nasal Sprays:Mucosal atomization devices target rapid systemic absorption for emergency medications and hormone therapies.
Jet injectors hold the largest share; momentum sits with microneedle patches.
End User:
Home care settings command expanding margin pools as reimbursement frameworks shift toward outpatient administration. Hospital procurement remains concentrated in tertiary care centers with integrated device evaluation committees.
- Hospitals:Tertiary care centers in the United States, Germany, and Japan anchor jet injector procurement through centralized purchasing agreements and infection control committees that prioritize sharps waste reduction.
- Home Care:Self-administration platforms capture reimbursement codes in United States commercial insurance and German statutory health insurance frameworks; diabetes, multiple sclerosis, and growth hormone deficiency patients drive device switching from clinic-based injection protocols.
- Clinics:Outpatient facilities balance cost constraints against patient throughput requirements.
- Pharmacies:Specialty and mail-order channels capture dispensing margins previously retained by hospital outpatient departments.
Hospitals retain volume leadership; home care is climbing the fastest.
Delivery Mode:
Transdermal systems span the widest geographic footprint from United States suburban markets to Indian rural distribution networks. Intranasal delivery concentrates in emergency medicine applications with concentrated hospital demand.
- Transdermal:Jet injectors and microneedle arrays penetrate stratum corneum barriers for systemic drug absorption. United States and German chronic disease management programs favor transdermal biologics; Indian immunization campaigns adopt dissolving microneedles for thermostable vaccine distribution.
- Intranasal:Mucosal atomization targets rapid central nervous system drug delivery for emergency medications. United States emergency departments and Japanese trauma centers concentrate demand; opioid overdose reversal and seizure rescue applications drive procurement.
- Inhalation:Pulmonary deposition serves respiratory and systemic therapies through alveolar absorption.
- Intravenous:Needle-free vascular access devices reduce sharps exposure in high-frequency injection settings.
Transdermal systems hold the largest share; intranasal delivery shows the steepest expansion trajectory in emergency medicine.
Regulation:
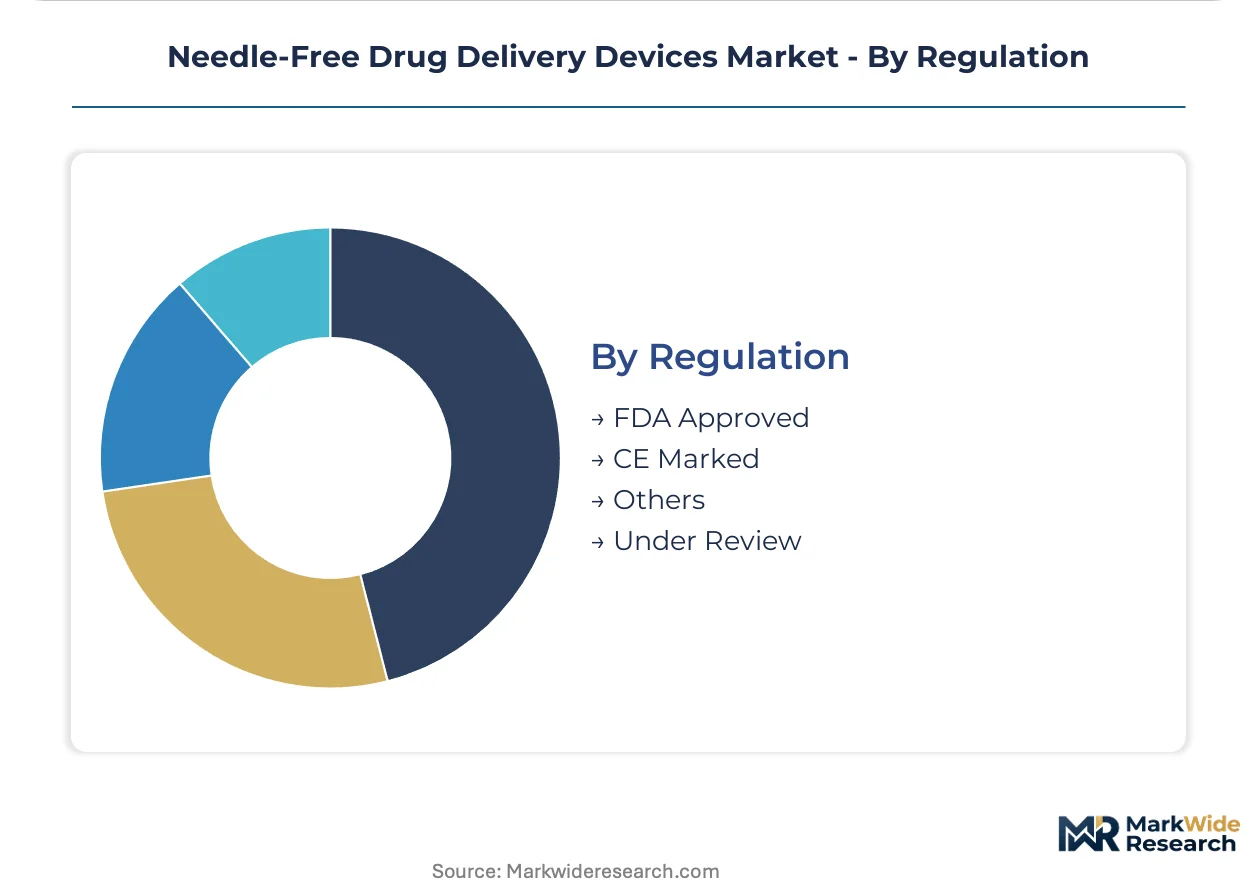
FDA and CE marking pathways impose divergent clinical evidence requirements that fragment manufacturer regulatory strategies. Under-review devices concentrate in early-stage platform developers lacking comparative pharmacokinetic datasets.
- FDA Approved:United States 510(k) clearance and biologics license application pathways require substantial equivalence demonstrations or comparative pharmacokinetic studies against reference listed drugs. Manufacturers targeting United States commercialization prioritize jet injector clinical validation; FDA draft guidance on interchangeable needle-free products is forcing protocol redesigns around bioequivalence endpoints.
- CE Marked:EU Medical Device Regulation conformity assessment demands technical documentation and quality management system certification under ISO 13485. European manufacturers face annual surveillance interval compression that raises barriers for smaller device producers; EMA evolving bioequivalence positions accelerate regulatory clarity for platform developers.
- Others:National approvals in Japan, Switzerland, and Australia follow reference regulatory frameworks.
- Under Review:Pre-submission and pending applications concentrate among microneedle patch developers generating first-in-class clinical evidence.
FDA-approved devices hold the largest share; CE-marked platforms are gaining share fastest as European reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement frameworks for outpatient biologics delivery are restructuring procurement patterns across major healthcare markets. United States commercial insurers and German statutory health funds now explicitly cover needle-free self-administration devices. Japanese regulators accelerate PMDA review timelines for piezoelectric jet injectors targeting chronic disease management.
United States
Specialty pharmacies capture device dispensing margins previously retained by hospital outpatient departments. FDA draft guidance on interchangeable needle-free products forces sponsors to redesign clinical protocols around comparative pharmacokinetic endpoints. The Boston-Cambridge corridor anchors venture financing for early-stage microneedle platform developers.
Germany
University medical centers in Berlin and Munich anchor jet injector procurement through centralized purchasing agreements prioritizing sharps waste reduction. Annual ISO 13485 surveillance interval compression raises barriers for smaller device manufacturers seeking CE marking under EU Medical Device Regulation. The Baden-Württemberg precision machining cluster supplies high-velocity nozzle components to global jet injector producers.
Japan
PMDA accelerates review timelines for piezoelectric propulsion devices targeting diabetes and growth hormone deficiency self-administration. METI funding programs support domestic manufacturing scale-up for solid-state actuation mechanisms. The Kansai region's polymer science infrastructure feeds microneedle substrate development for thermostable vaccine applications.
India
Rural immunization programs adopt dissolving microneedle patches to bypass last-mile cold chain infrastructure gaps. CDSCO streamlined medical device registration pathways accelerate market entry for thermostable vaccine delivery platforms. The Hyderabad-Genome Valley cluster concentrates contract manufacturing for dissolving polymer array production.
Australia
TGA alignment with FDA bioequivalence standards facilitates parallel submission strategies for platform developers. Government procurement programs prioritize needle-free devices for national immunization campaigns in remote indigenous communities. Melbourne's biomedical precinct anchors clinical validation studies for intranasal emergency medication delivery systems.
Needle-Free Drug Delivery Devices Market Key Industry Players
Listed leaders compete with private specialists across regulatory affairs capacity and manufacturing scale. The vendor base stratifies between diversified healthcare conglomerates with polymer science capabilities and focused device developers lacking in-house quality management systems. Three archetypes dominate: jet injector incumbents defending hospital procurement contracts, microneedle patch pioneers capturing export-led growth, and spring-powered autoinjector specialists migrating into hormone therapy applications. Competitive moves concentrate on strategic partnerships with specialty pharmacy distributors and technology licensing agreements to bypass biocompatibility testing bottlenecks.
Within the jet injector tier, PharmaJet and Antares Pharma exemplify platform developers with established clinical validation bases. Among diversified technology conglomerates, 3M occupies a position representing polymer science capabilities applicable to microneedle substrate innovation. These three anchors illustrate the structural divergence between device-focused specialists and materials-science-backed diversified players competing for distinct procurement channel preferences.
| Leading Market Players |
|---|
| PharmaJet |
| Antares Pharma |
| 3M |
| Crossject SA |
| Portal Instruments Inc. |
| Injex Pharma AG |
| West Pharmaceutical Services |
| Vaxxas Pty Ltd |
| Medical International Technology |
| Others |
Cost & Logistics Intelligence
Piezoelectric actuators displacing compressed gas mechanisms in portable jet injectors redraws procurement geography toward Japanese and German precision electronics clusters while compressing per-unit manufacturing economics through solid-state reliability gains. This substitution simultaneously elevates device pricing power for certified manufacturers and squeezes margin pools for gas-dependent legacy producers locked into volatile helium supply contracts.
Pricing Analysis
Certification grade creates the primary spread between FDA-cleared hospital procurement tiers and CE-marked outpatient devices, with ISO 13485 annual surveillance costs embedding directly into premium pricing structures. Three-tier pricing stratifies across premium jet injectors with established bioequivalence datasets, standard spring-powered autoinjectors, and economy microneedle patches for immunization campaigns. Pricing pressure stems from polymer feedstock volatility in medical-grade polycarbonate sourcing, with contract manufacturers absorbing margin compression rather than passing through to price-sensitive public health procurement agencies in India and sub-Saharan Africa.
Supply Chain Analysis
High-velocity nozzle fabrication concentrates among Baden-Württemberg precision machining houses and Kansai-region Japanese suppliers, creating geographic chokepoints that constrain jet injector production scaling during demand surges. The device ecosystem draws from German polymer science infrastructure for microneedle substrates, Japanese piezoelectric ceramics for solid-state actuation, and Indian contract manufacturing for dissolving array assembly. Single-source vulnerability in precision nozzle supply exposes manufacturers to logistics disruption, with distribution running through specialty pharmacy channels in the United States and hospital procurement consortia in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 surveillance interval compression is driving a cyclical consolidation phase that favors scaled manufacturers with in-house quality management systems over fragmented platform developers.
For Market Incumbents: Fortify hospital procurement relationships through bioequivalence dataset investments that preempt FDA interchangeability designations, while capturing backward integration into precision nozzle manufacturing to neutralize single-source supply risk from German and Japanese machining suppliers. For New Entrants and Emerging Players: CDSCO fast-track registration for thermostable microneedle vaccines offers the most penetrable entry vector, targeting rural Indian immunization programs with dissolving polymer arrays that bypass cold chain infrastructure gaps entirely. For Investors and Strategic Acquirers: The market sits at a regulatory-clarification phase that favors diversified healthcare conglomerates with polymer science capabilities over pure-play device developers lacking biocompatibility testing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Interchangeability Pathway | Comparative pharmacokinetic studies against reference listed drugs unlock substitutability premiums in United States commercial insurance markets. |
| CE Marking Acceleration | EMA evolving bioequivalence guidance reduces regulatory uncertainty for platform developers seeking European market access. |
| Specialty Pharmacy Partnership | Mail-order dispensing margins in United States copay structures displace hospital outpatient department capture. |
| Piezoelectric Manufacturing Scale-Up | METI-funded domestic production in Japan reduces dependency on compressed gas supply chains for portable device deployment. |
| Rural India Distribution Network | CDSCO streamlined registration enables last-mile vaccine delivery without refrigeration infrastructure investment. |
Research Approach
A spread of perspectives from regulatory affairs directors at device manufacturers, hospital procurement committee members, specialty pharmacy dispensing managers, and polymer science R&D leads converged on the working assumptions anchoring this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EMA medical device registration filings, ISO 13485 certification records, and hospital GPO contract repositories. Bottom-up device shipment estimates triangulated against top-down reimbursement code analysis across United States commercial insurance and German statutory health insurance frameworks.
Segmentation dimensions modeled span propulsion mechanism, clinical setting, regulatory jurisdiction, and patient administration mode across the projection horizon. CAGR derivation incorporated patient population growth in diabetes, multiple sclerosis, and growth hormone deficiency categories alongside reimbursement code expansion rates for outpatient biologics delivery. Forecast inputs included ISO 13485 certification timeline compression effects and polymer feedstock price elasticity assumptions for microneedle substrate manufacturing.
Decision-makers should treat outputs as directional under stable regulatory surveillance interval assumptions; material deviation in FDA draft guidance finalization would warrant model refresh. Practitioners should keep alternative scenarios live as EMA bioequivalence positions and Indian cold chain infrastructure investment levels evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Subdural Electrodes Market
Medical Devices
Otoscope Devices Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Light Therapy Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
France Respiratory Devices Market