
 Global Dry Powder Inhaler (DPI) Market | 2026-2036
Global Dry Powder Inhaler (DPI) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dry Powder Inhaler (DPI) Market Foresight
Capsule-based bundling with disease-specific drug formulations is hardening as the dominant configuration pattern for DPI procurement decisions. GlaxoSmithKline plc leverages its breath-actuated technology portfolio to sustain leadership across asthma and COPD indications. Boehringer Ingelheim anchors European manufacturing scale while Cipla competes aggressively on complex generic reservoir designs in emerging markets.
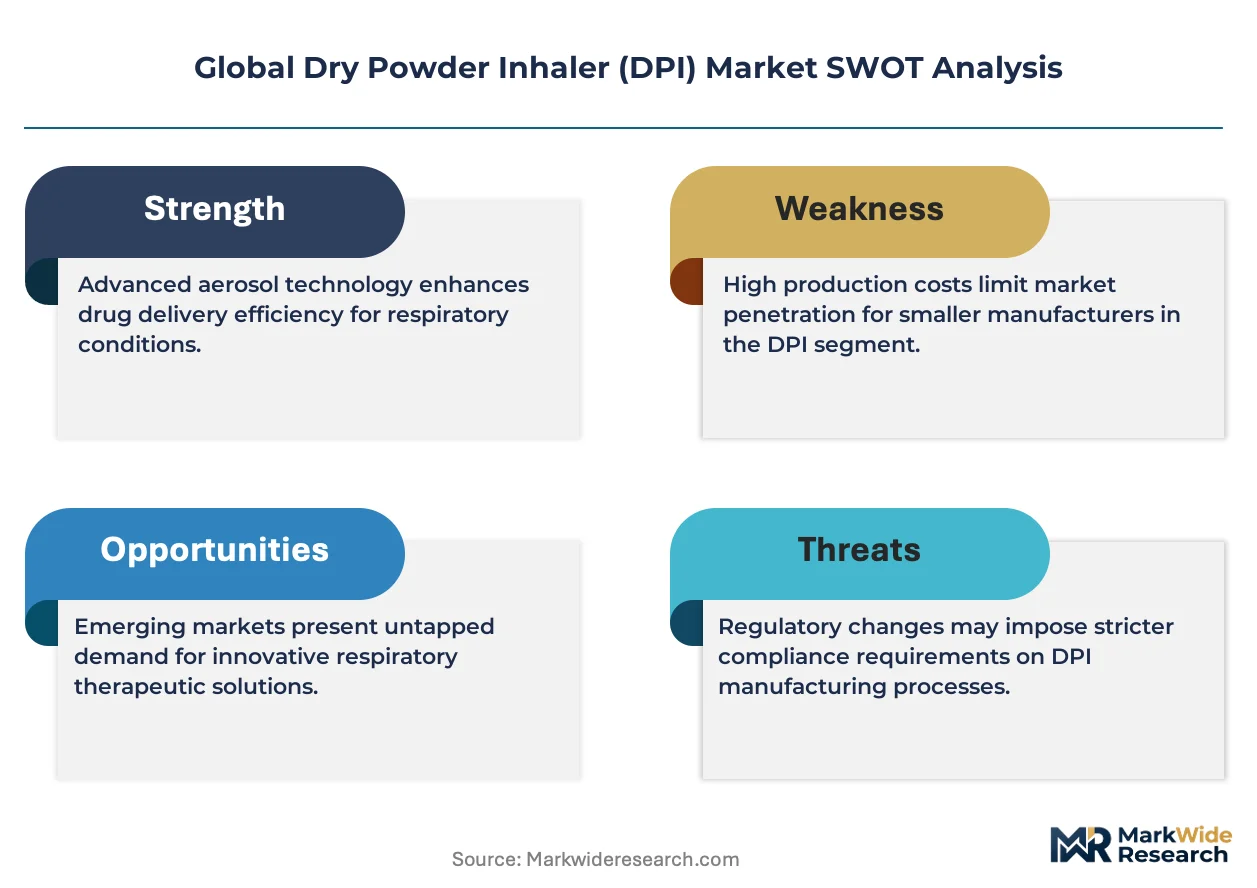
A dry powder inhaler is a passive or active breath-actuated drug delivery device that aerosolizes micronized pharmaceutical powder, typically with particle diameters of 1–5 micrometers, for direct deposition into the pulmonary tract to treat obstructive and inflammatory respiratory conditions. Single-dose and multi-dose DPI configurations dominate current volume, though carrier-free formulations are gaining fastest as manufacturers seek to eliminate lactose excipient variability and improve dose consistency. The application split heavily favors asthma and chronic obstructive airway disorder, where repeat prescription volumes create the deepest margin pools for device-drug combination holders.
The FDA's bioequivalence standards for orally inhaled products and the EMA's MDR requirements for drug-device combinations jointly elevate R&D barriers and compliance costs for market entrants. ISO 20072 testing protocols for inhaler performance further standardize how manufacturers demonstrate emitted dose uniformity across variable patient inspiratory flow rates. Stakeholders must monitor how carrier-free and active DPI technologies reshape patent cliffs and generic substitution timelines.
Market Dynamics
Breath-actuated drug deposition technology is compressing development timelines while FDA bioequivalence standards for complex generics are hardening competitive moats around incumbent device-drug combinations.
Growth Catalysts
- Medicare reimbursement expansion:US federal coverage for home-administered respiratory therapy is pulling volume toward self-managed care settings. This reimbursement architecture rewards device portability and patient training simplicity.
- Carrier-free formulation chemistry:Elimination of lactose excipients is improving dose reproducibility across variable inspiratory flow profiles. Manufacturers are reformulating around this stability advantage.
- ISO 20072 standardization:Uniform emitted-dose testing protocols are reducing regulatory friction for cross-border product registrations. This harmonization accelerates multi-market launches from centralized manufacturing footprints.
Market Restraints
- High-purity lactose supply concentration:Pharmaceutical-grade carrier lactose production clusters in Western European chemical processing corridors. This geographic density creates input vulnerability for multi-dose reservoir formulations.
- EMA MDR compliance burden:Drug-device combination classification under the EU Medical Device Regulation imposes parallel quality-system audits. Smaller generic entrants face disproportionate certification costs relative to revenue scale.
- Flow-rate variability limitation:Patient inspiratory force spans a fourfold range (15–60 L/min), degrading lung deposition consistency for passive breath-actuated designs. This physiological spread caps efficacy predictability.
Strategic Opportunities
- Active DPI motorization:Battery-powered aerosolization decouples drug delivery from patient inspiratory capacity. Pediatric and geriatric segments represent immediate addressable populations for this technology bridge.
- India CDSCO abbreviated approval pathway:The Indian regulator's streamlined bioequivalence framework for locally manufactured complex generics reduces time-to-market versus FDA or EMA routes. Domestic producers are exploiting this regulatory arbitrage.
- Telehealth-integrated adherence monitoring:Bluetooth-enabled dose counters feeding remote patient management platforms are opening subscription revenue streams. US pulmonology practices are piloting this reimbursement-adjacent service layer.
Industry Challenges
- Inhaler engineering talent scarcity:Cross-disciplinary expertise spanning fluid dynamics, pharmaceutical powder science, and human factors engineering concentrates in a handful of academic and industrial clusters. Recruitment competition intensifies as device portfolios expand.
- Legacy device obsolescence coordination:Transitioning installed bases from chlorofluorocarbon-propelled metered-dose inhalers to DPI alternatives requires synchronized manufacturing phase-out and patient education investments. This coordination burden falls heaviest on established respiratory portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dry Powder Inhaler (DPI) Market |
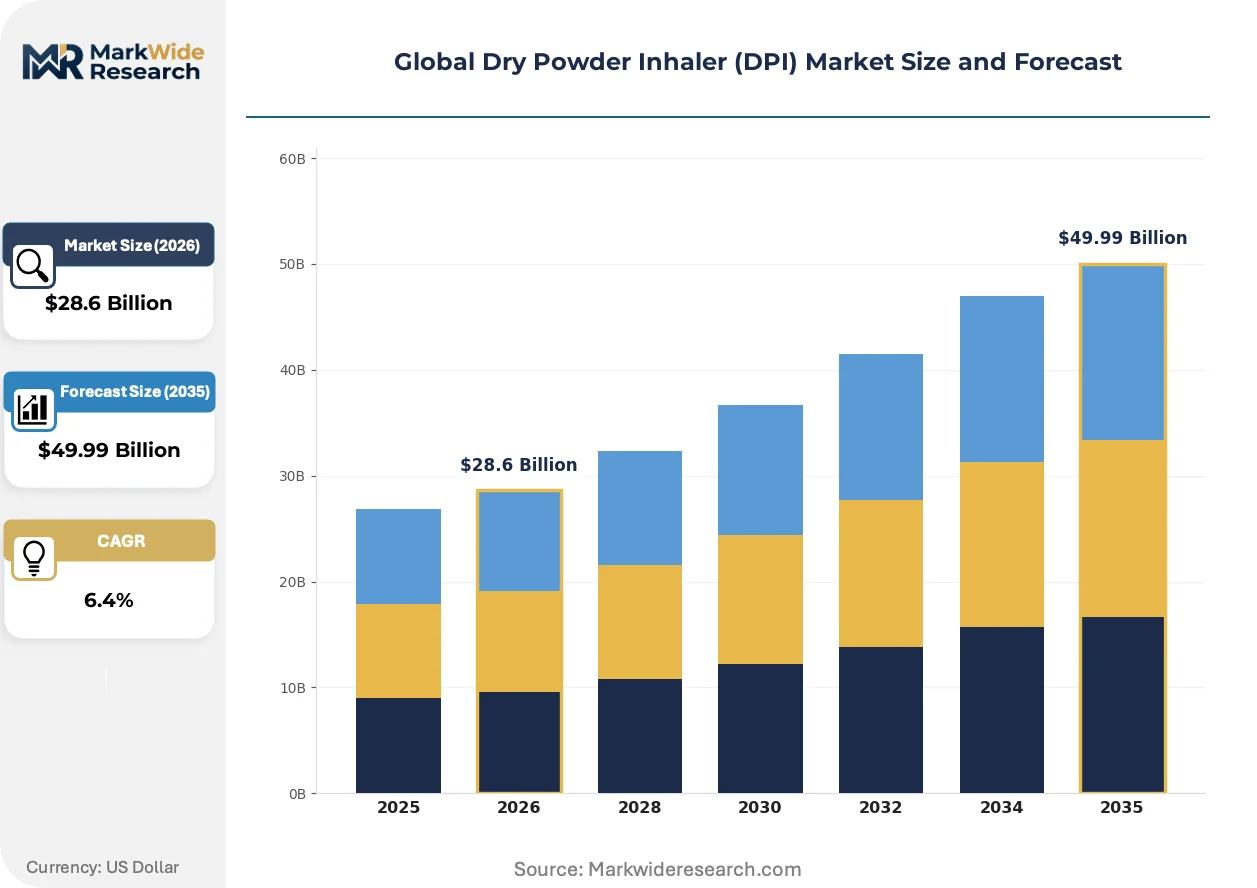
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Dose DPI, Multi-Dose DPI, Reservoir DPI, Capsule-Based DPI, Pre-Dosed DPI Technology: Breath-Actuated, Passive DPI, Active DPI, Multi-Carrier, Carrier-Free Application: Asthma, Chronic Obstructive Airway Disorder, Pulmonary Fibrosis, Cystic Fibrosis, Allergic Rhinitis End User: Specialty Clinics, Research Laboratories, Pharmacies, Home Care, Respiratory Therapy Centers |
| Companies Covered | AstraZeneca, GlaxoSmithKline plc, Boehringer Ingelheim, Teva Pharmaceutical Industries Ltd, Cipla, Vectura Group plc, Hovione, Chiesi Farmaceutici S.p.A., MannKind Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dry Powder Inhaler (DPI) Market Shifts & Advancements
Digital connectivity and real-world evidence generation are redefining how device performance is validated and reimbursed, shifting competitive advantage toward data-integrated delivery ecosystems.
Active breath-actuated systems with integrated flow sensors are converging with cloud-based pulmonary function monitoring to enable personalized dose titration. Home care providers and accountable care organizations in the United States are piloting these connected inhalers for high-utilization asthma populations. This convergence is compressing the traditional separation between drug delivery hardware and disease management software, forcing device manufacturers to build or partner for data infrastructure.
The FDA's evolving bioequivalence guidance for orally inhaled products now requires comparative clinical endpoint studies alongside pharmacokinetic bridging. This regulatory elevation is extending generic approval timelines and protecting originator revenue streams for device-drug combinations. Complex generic entrants are responding by investing in proprietary inhaler geometries that sidestep direct reference product comparisons.
Hospital procurement consortia are consolidating respiratory device purchasing across integrated delivery networks, unbundling device selection from pharmaceutical formulary decisions. This buying-pattern shift transfers negotiation leverage toward supply chain managers and away from individual prescribers. The United Kingdom's National Health Service and several US regional health systems are most advanced in this centralized sourcing transition.
Global Dry Powder Inhaler (DPI) Market Segmentation
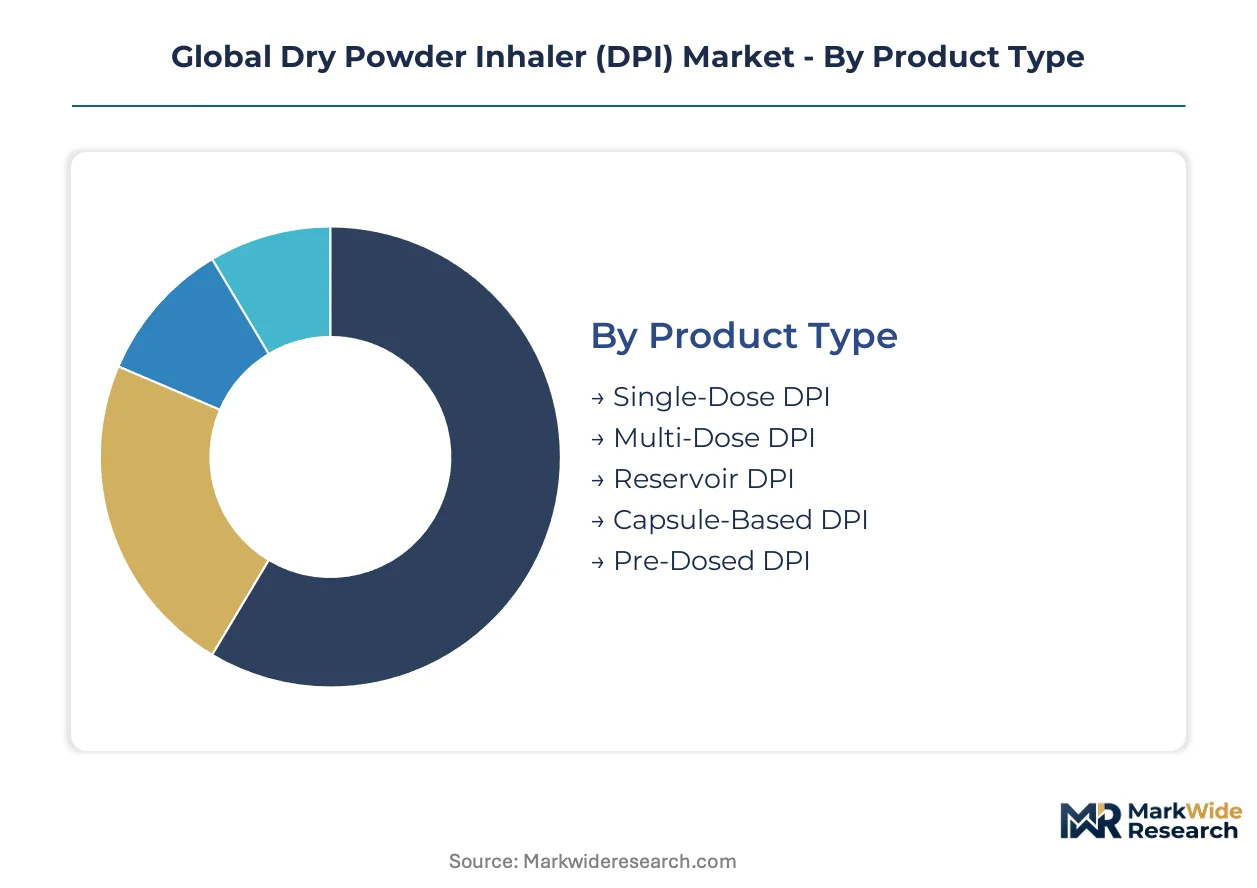
DPI procurement decisions hinge on device-drug compatibility, patient inspiratory capacity, and reimbursement pathways. Each segmentation dimension reveals distinct supply chain configurations and margin structures that shape competitive positioning across therapeutic categories.
Product Type:
Manufacturing footprints concentrate around high-volume multi-dose platforms, while specialized single-dose formats serve niche therapeutic requirements.
- Multi-Dose DPI:Reservoir-based designs store 30–120 doses in blister strips or bulk powder chambers. US Medicare reimbursement for home-administered respiratory therapy concentrates demand for patient-convenient refill cycles. Manufacturers optimize these devices for asthma maintenance therapy where prescription volumes sustain deep margin pools.
- Capsule-Based DPI:Single-unit dose containment in gelatin or HPMC shells eliminates stability concerns for moisture-sensitive formulations. European pharmaceutical-grade lactose supply corridors in the Netherlands and Germany anchor production for these carrier-dependent configurations.
- Single-Dose DPI:Disposable breath-actuated units serve acute rescue scenarios and clinical trial settings.
- Reservoir DPI:Bulk powder storage with metered-dose mechanisms supports high-frequency COPD therapy.
- Pre-Dosed DPI:Factory-sealed individual doses address strict hospital formulary compliance requirements.
Multi-Dose DPI absorbs the bulk of installed capacity; Capsule-Based DPI is expanding most quickly as carrier-free chemistry advances.
Technology:
Patient inspiratory force variability drives divergence between passive breath-dependent designs and powered active alternatives.
- Breath-Actuated:Inspiratory flow triggers powder deagglomeration without patient coordination requirements. US pulmonology practices favor these devices for geriatric populations where hand-breath synchronization fails. FDA bioequivalence standards for complex generics now require comparative clinical endpoint studies for these reference-listed products.
- Active DPI:Battery-powered aerosolization decouples drug delivery from patient lung capacity. Pediatric and geriatric segments in Japan and Germany represent immediate addressable populations for this technology bridge.
- Passive DPI:Relies entirely on patient inspiratory force without mechanical assistance.
- Multi-Carrier:Employs lactose and alternative excipient blends for dose uniformity.
- Carrier-Free:Eliminates excipient variability through engineered particle engineering.
Breath-Actuated platforms command the deepest revenue pools; Active DPI shows steepest expansion trajectory as motorization costs decline.
Application:
Prescription refill frequency and chronic disease burden determine device procurement economics across therapeutic areas.
- Asthma:Chronic inflammatory airway condition requiring daily controller therapy and periodic rescue intervention. US commercial and Medicare Part D formularies sustain the highest prescription volumes globally for this indication.
- Chronic Obstructive Airway Disorder:Progressive airflow limitation with irreversible components demands long-acting bronchodilator combinations. European EMA MDR compliance costs for drug-device combinations concentrate procurement decisions among established respiratory portfolios.
- Pulmonary Fibrosis:Interstitial lung disease with antifibrotic powder formulations.
- Cystic Fibrosis:Genetic mucus clearance disorder requiring enzyme replacement delivery.
- Allergic Rhinitis:Seasonal nasal inflammation with corticosteroid powder options.
Asthma captures the majority of device-drug combination revenue; Chronic Obstructive Airway Disorder gains share fastest as populations age.
End User:
Procurement authority shifts from individual prescribers to supply chain managers as care settings consolidate purchasing.
- Home Care:Self-administered respiratory therapy outside clinical environments. US federal reimbursement expansion for home-administered care pulls volume toward portable devices with simplified patient training.
- Specialty Clinics:Pulmonology and allergy practices with direct device sampling programs.
- Research Laboratories:Clinical trial supply for bioequivalence and pharmacokinetic studies.
- Pharmacies:Retail dispensing with generic substitution incentives.
- Respiratory Therapy Centers:Hospital outpatient departments with integrated delivery network contracts.
Home Care dominates volume acceleration; Specialty Clinics retain premium pricing power for originator products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of dry powder inhalers clusters in Western Europe and North America, while demand growth accelerates fastest in Asian markets where respiratory disease burdens and healthcare access expand simultaneously.
United States
Medicare Part D reimbursement for home-administered respiratory therapy sustains the world's largest prescription volume for asthma and COPD maintenance. FDA bioequivalence standards for complex generic orally inhaled products harden competitive moats around incumbent device-drug combinations. The Research Triangle Park corridor in North Carolina anchors clinical trial infrastructure for inhaler performance validation.
Germany
EMA MDR compliance requirements for drug-device combinations concentrate procurement authority among established respiratory portfolios with quality-system scale. Industrial chemical processing corridors in the Rhineland supply pharmaceutical-grade lactose carriers for multi-dose reservoir formulations. Bavaria's precision manufacturing clusters host active DPI motorization development programs.
India
CDSCO abbreviated approval pathways for locally manufactured complex generics reduce regulatory timelines versus FDA or EMA routes. Domestic producers exploit this regulatory arbitrage to supply reservoir-based designs across emerging markets. Hyderabad and Ahmedabad pharmaceutical manufacturing zones concentrate generic DPI formulation capacity.
Japan
PMDA guidelines for orally inhaled products align with ISO 20072 testing protocols, streamlining cross-border registration for multinational device portfolios. Geriatric respiratory populations drive demand for active DPI technologies that decouple drug delivery from inspiratory force. The Kansai region hosts specialized powder engineering research consortia.
United Kingdom
NHS centralized procurement consortia unbundle device selection from pharmaceutical formulary decisions, transferring leverage toward supply chain managers. National Institute for Health and Care Excellence cost-effectiveness assessments shape reimbursement for connected inhaler adherence monitoring. Cambridge life sciences clusters incubate telehealth-integrated dose counter technologies.
Global Dry Powder Inhaler (DPI) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across device-drug combination portfolios, creating a tiered structure where scale advantages in regulatory compliance separate leaders from followers. The vendor base stratifies between originator pharmaceutical companies with captive device engineering, contract development and manufacturing organizations with platform technologies, and emerging market generic houses with cost-optimized reservoir designs. Two dominant competitive moves define current positioning: proprietary inhaler geometry development to sidestep direct bioequivalence comparisons, and strategic partnerships with digital health platforms for adherence monitoring integration.
Within the diversified pharmaceutical tier, GlaxoSmithKline plc and AstraZeneca exemplify device-drug combination holders leveraging breath-actuated technology portfolios across asthma and COPD indications. Boehringer Ingelheim anchors European manufacturing scale for multi-dose platforms, while Cipla occupies a position within the emerging market generic segment focused on complex reservoir designs. These three entities represent distinct archetypes—originator-integrated, regional manufacturing-scale, and cost-optimized generic—each pursuing divergent pathways through FDA bioequivalence and EMA MDR compliance barriers.
| Leading Market Players |
|---|
| AstraZeneca |
| GlaxoSmithKline plc |
| Boehringer Ingelheim |
| Teva Pharmaceutical Industries Ltd |
| Cipla |
| Vectura Group plc |
| Hovione |
| Chiesi Farmaceutici S.p.A. |
| MannKind Corporation |
| Others |
Supply & Pricing Matrix
Originator-to-generic tier divergence in device-drug combinations manifests in both pricing power and supply chain sourcing strategies, with FDA bioequivalence tiers creating distinct procurement corridors that separate premium breath-actuated portfolios from commodity reservoir designs sourced through Indian manufacturing zones.
Pricing Analysis
Margin tightening in complex generic reservoir designs reflects EMA MDR compliance cost absorption and ISO 20072 testing investments. Three-tier pricing structure across premium, standard, and economy levels separates originator device-drug combinations with proprietary geometries from multi-dose platforms with carrier-free chemistry and basic passive DPI alternatives. Price differentiation traces to certification grade and vertical integration depth in pharmaceutical-grade lactose supply. Hospital procurement consortia exhibit highest price sensitivity; originator portfolios with captive device engineering maintain pricing power.
Supply Chain Analysis
Dual-sourcing requirements for pharmaceutical-grade lactose carriers mandate qualification of both Netherlands and German chemical processing corridors alongside Indian excipient alternatives. Raw material dependencies center on high-purity lactose, engineered polymer components for device housings, and micronized API powders. Supply chain risk concentrates in single-source vulnerability for carrier-dependent formulations. Distribution runs through hospital procurement consortia, integrated delivery networks, and retail pharmacy channels with generic substitution protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DPI sector sits in active-to-passive technology transition, with battery-powered aerosolization displacing breath-dependent designs in pediatric and geriatric segments where inspiratory force variability degrades clinical outcomes.
For Market Incumbents: Deploy proprietary inhaler geometry development to sidestep direct FDA bioequivalence comparisons with reference-listed products. Anchor European manufacturing scale for multi-dose platforms while building captive supply of pharmaceutical-grade lactose to offset carrier input vulnerability from Dutch and German chemical corridors. EMA MDR compliance investments protect against emerging market generic entrants with abbreviated regulatory pathways.
For New Entrants and Emerging Players: Telehealth-integrated adherence monitoring offers the most penetrable white-space target, with Bluetooth-enabled dose counters feeding remote patient management platforms in US pulmonology practices. Exploit CDSCO abbreviated approval pathways in India to compress time-to-market versus FDA or EMA routes for reservoir-based designs. Direct-to-clinic sampling programs bypass hospital procurement consortia that favor established portfolios.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of contract development organizations with platform inhaler technologies and ISO 20072 validation capabilities. Long-term viability favors device-drug combination holders with active DPI motorization programs and data infrastructure partnerships for connected inhaler ecosystems. Watch FDA bioequivalence guidance evolution for orally inhaled products as inflection indicator for generic substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Active DPI Motorization Program | Battery-powered aerosolization decouples delivery from patient inspiratory capacity in geriatric segments. |
| Carrier-Free Formulation Chemistry | Elimination of lactose excipients improves dose reproducibility across variable flow profiles per ISO 20072. |
| Telehealth Platform Partnership | Bluetooth dose counters enable subscription revenue streams adjacent to Medicare reimbursement expansion. |
| CDSCO Abbreviated Approval Pathway | Streamlined Indian regulatory framework reduces time-to-market versus FDA bioequivalence requirements. |
| Hospital Procurement Consortium Contract | Integrated delivery network agreements secure volume commitments amid unbundling of device from formulary decisions. |
Research Methodology
Multi-period observation of prescription refill volumes, device-drug combination approvals, and Medicare reimbursement policy shifts anchored the trend analysis, supplemented by interviews with regulatory affairs leads at originator pharmaceutical companies, formulary directors at US hospital systems, biomedical engineers at device manufacturing facilities, and procurement managers at European chemical processing corridors. Secondary validation drew from FDA 510(k) filings for orally inhaled products, EMA MDR submission databases, CMS Medicare Part D utilization data, and ISO 20072 testing protocol documentation. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation cross-validated market sizing.
Input-output matrix frameworks linked patient inspiratory capacity distributions to device technology adoption curves across the projection horizon. Segmentation dimensions spanned product type, technology architecture, therapeutic application, and end-user setting with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to Medicare enrollment projections and asthma prevalence epidemiology. Forecast inputs incorporated carrier-free formulation penetration rates and active DPI motorization cost decline assumptions.
Inputs from FDA bioequivalence guidance documents and EMA MDR implementation timelines were available through the study window; gaps in real-world connected inhaler adherence data and telehealth reimbursement coding introduce uncertainty bands around digital ecosystem revenue forecasts. Deviation in FDA complex generic approval timelines or EMA MDR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Electrophysiology Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Slip Disc Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Neurostimulation Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
Surgical Smart Glasses Market