
 Epistaxis Devices Market | 2026-2036
Epistaxis Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Epistaxis Devices Market Foresight
Aftermarket service revenue for nasal pack training and restocking contracts is narrowing toward manufacturers with direct hospital integration. Medtronic plc leverages its broad ENT portfolio to bundle epistaxis devices with surgical navigation systems. Smith & Nephew plc anchors its position through absorbent polymer R&D and wound-care cross-selling infrastructure. Stryker Corporation competes via emergency room distribution density and capital equipment placement programs.
Epistaxis devices encompass hemostatic instruments designed to arrest anterior and posterior nasal bleeding through mechanical compression, thermal cauterization, or balloon tamponade, typically constructed from silicone, polyurethane, or absorbent polymers with inflation pressures calibrated to mucosal tolerance. These devices serve otolaryngologists, emergency physicians, and first responders requiring rapid bleeding control without surgical intervention. Nasal packs manufactured from absorbent polymers capture expanding share as outpatient clinic preference shifts toward dissolvable formats that eliminate removal trauma. Balloon catheters sustain premium positioning in posterior epistaxis management where visualization limits and bleeding severity demand controlled, pressure-adjustable intervention.
FDA 510(k) pathways govern device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for hemostatic claims across European markets. BIS certification and CDSCO oversight shape import dynamics and local manufacturing incentives in India. Stakeholders must monitor how regulator convergence on biocompatibility testing standards reshapes material selection and supplier qualification timelines.
Market Dynamics
Hospital emergency departments are consolidating purchasing authority around rapid nasal packing systems, compressing vendor selection criteria toward devices with integrated training protocols and restocking logistics. This procurement centralization is restructuring competitive access points across the epistaxis device supply base.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined clearance timelines for absorbable polymer innovations are shortening commercialization cycles. Device developers now reach hospital formulary committees faster than through traditional PMA routes.
- Anticoagulant Therapy Prevalence:Rising warfarin and direct oral anticoagulant prescriptions among aging populations are elevating procedural complexity. Emergency physicians require more sophisticated hemostatic interventions for patients with impaired coagulation.
- Absorbable Polymer Chemistry:Advances in hydrocolloid and oxidized cellulose formulations are eliminating traumatic pack removal. Otolaryngology clinics are converting mechanical compression protocols to dissolvable formats.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Specialty silicone suppliers in Germany and Japan control feedstock for balloon catheter manufacturing. Price volatility in this input stream compresses margin flexibility for device assemblers.
- EU MDR Clinical Evidence Burden:Stricter hemostatic performance documentation requirements under the Medical Device Regulation are extending European market entry timelines. Smaller developers face disproportionate compliance cost absorption.
- Silver Nitrate Cauterization Persistence:Low-cost chemical cautery remains the first-line intervention for anterior bleeds in resource-constrained settings. This substitute limits premium device penetration in price-sensitive procurement environments.
Strategic Opportunities
- Outpatient Clinic Conversion:Freestanding ENT ambulatory surgery centers in the United States represent underpenetrated deployment channels. These facilities seek single-use dissolvable packs to eliminate follow-up removal appointments.
- PLI Scheme Manufacturing Incentives:India's Production Linked Incentive program for medical devices is attracting contract manufacturing investment. Export-oriented production hubs can serve Middle East and Southeast Asian markets with competitive unit economics.
- Thermal Cauterization Balloon Hybridization:Convergence of radiofrequency energy delivery with pressure-adjustable tamponade is creating next-generation posterior bleed management. Early clinical validation is underway at tertiary referral centers.
Industry Challenges
- ENT Device Specialist Training Bottleneck:Proper nasal pack placement technique requires hands-on instruction that outpaces available clinical educator capacity. Manufacturers must embed training modules within device packaging or risk improper utilization.
- Biocompatibility Testing Queue Compression:ISO 10993 cytotoxicity and sensitization studies face laboratory backlog delays. Extended validation timelines compress product launch windows against competitor entries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epistaxis Devices Market |
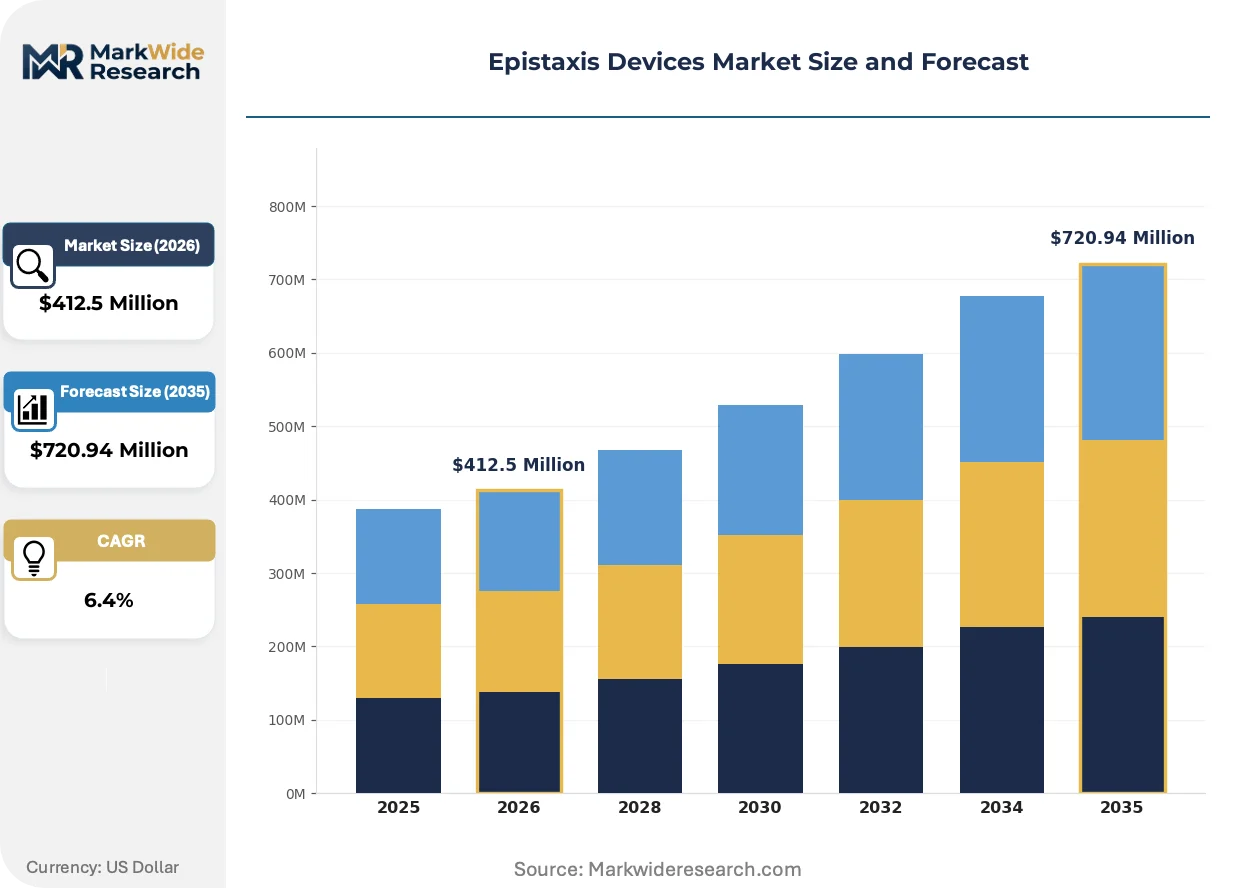
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compress, Cauterizing Device, Nasal Pack, Balloon Catheter Material: Silicone, Stainless Steel, Polyurethane, Absorbent Polymer Application: Hospital, Home Care, Outpatient Clinic, Emergency Room End User: ENT Specialists, General Practitioners, Emergency Medical Services, Patients |
| Companies Covered | Medtronic plc, Smith & Nephew plc, Stryker Corporation, Teleflex Incorporated, Summit Medical, Medline Industries Inc., DeRoyal Industries Inc., Entellus Medical, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epistaxis Devices Market Shifts & Advancements
Digital workflow integration is reshaping how epistaxis interventions are documented, billed, and quality-assured across emergency medicine and otolaryngology practice settings.
Smart balloon catheter systems with embedded pressure sensors and Bluetooth connectivity are virtualizing post-placement monitoring. Emergency departments at academic medical centers are piloting these devices to reduce nursing observation burden. Real-time pressure telemetry is enabling remote surveillance protocols that compress length-of-stay metrics.
EU MDR Article 10 clinical evaluation requirements are mandating prospective bleeding cessation data for hemostatic device claims. Manufacturers must now commission controlled studies demonstrating superiority over standard-of-care compression. Posterior balloon catheter segments face the steepest evidence generation burden given the severity of underlying clinical presentations.
Hospital value analysis committees are consolidating vendor contracts around bundled service models that unbundle device procurement from training and restocking logistics. Group purchasing organizations are displacing individual hospital negotiations with multi-year enterprise agreements. This concentration is most visible in the United States, where health system consolidation has reduced the number of independent purchasing entities by half over the past decade.
Epistaxis Devices Market Segmentation
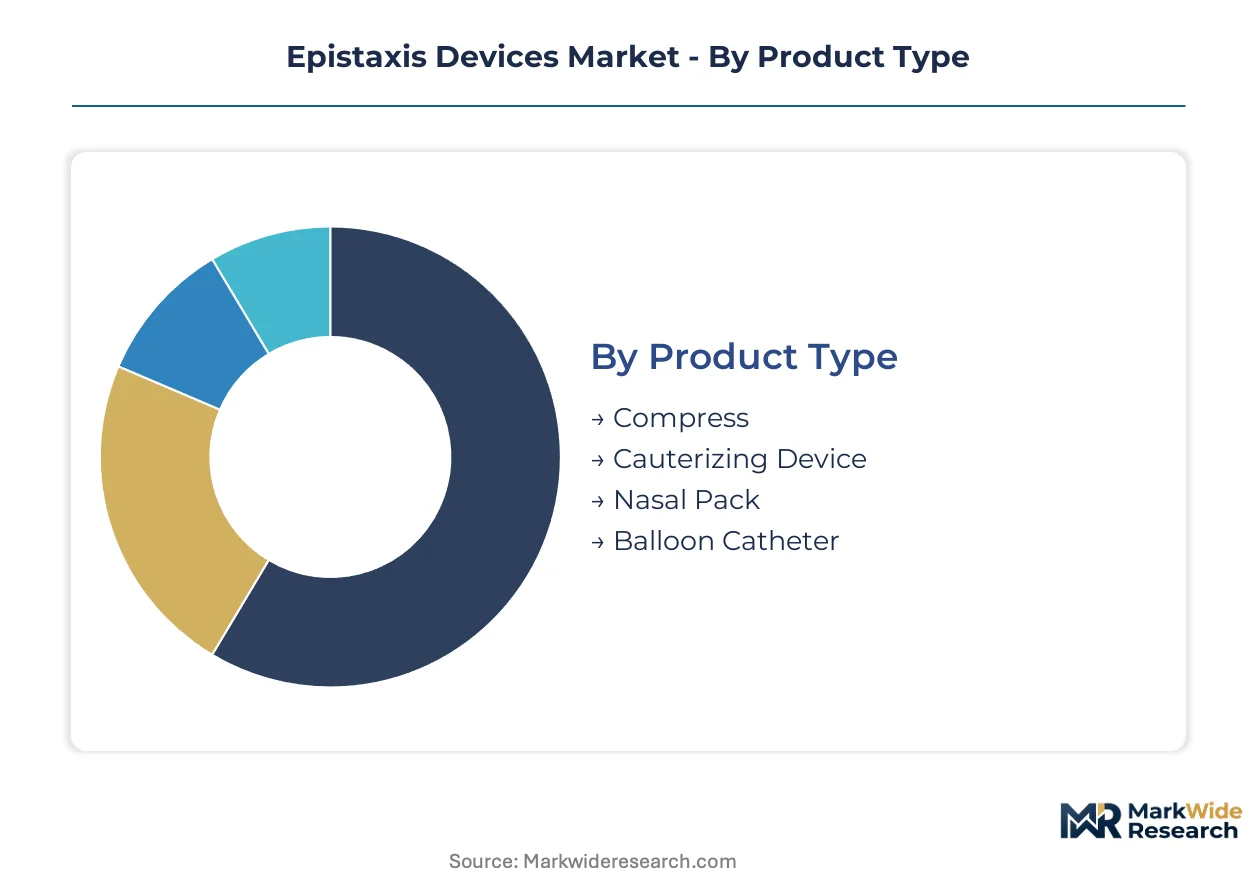
Epistaxis device purchasing splits across clinical settings, material preferences, and user expertise levels. Manufacturers must align product portfolios with these divergent specifications to secure formulary placement and recurring revenue streams.
Product Type:
Cost tier determines procurement patterns across mechanical, thermal, and pressure-based intervention categories.
- Nasal Pack:Absorbent polymer and oxidized cellulose constructions enable dissolvable formats that eliminate traumatic removal procedures. Hospital emergency departments in the United States are converting mechanical compression protocols to these formats as anticoagulant therapy prevalence elevates procedural complexity.
- Balloon Catheter:Silicone and polyurethane constructions with calibrated inflation pressures address posterior bleeds where visualization limits demand controlled tamponade. Tertiary referral centers sustain premium positioning for these devices given the severity of underlying clinical presentations.
- Compress:External nasal compression devices provide first-line mechanical intervention for anterior bleeds in resource-constrained settings.
- Cauterizing Device:Thermal and chemical cauterization instruments serve low-cost intervention protocols where device procurement budgets remain restricted.
Nasal Pack holds installed capacity. Balloon Catheter is rotating up the share rankings.
Material:
Supply concentration and biocompatibility certification timelines differentiate raw material sourcing strategies.
- Absorbent Polymer:Hydrocolloid and oxidized cellulose formulations dissolve within mucosal tissue, eliminating follow-up removal appointments. Outpatient clinics in the United States are expanding deployment of these materials as freestanding ENT ambulatory surgery centers seek single-use formats.
- Silicone:Medical-grade specialty suppliers in Germany and Japan control feedstock for balloon catheter manufacturing, creating price volatility that compresses margin flexibility for device assemblers.
- Polyurethane:Alternative elastomer for balloon construction offering distinct inflation pressure characteristics and cost positioning.
- Stainless Steel:Structural component in cauterizing instrument construction, subject to commodity metal pricing fluctuations.
Absorbent Polymer is climbing the fastest. Silicone maintains legacy installed base.
Application:
Customer type and reimbursement environment shape volume concentration across care delivery settings.
- Emergency Room:Rapid nasal packing systems with integrated training protocols dominate procurement criteria as hospital emergency departments consolidate purchasing authority. Academic medical centers are piloting smart balloon catheter systems with embedded pressure sensors to reduce nursing observation burden.
- Outpatient Clinic:Freestanding ENT ambulatory surgery centers represent underpenetrated deployment channels seeking dissolvable packs to eliminate follow-up removal appointments.
- Hospital:Inpatient otolaryngology services require device formats compatible with surgical navigation system integration.
- Home Care:Direct-to-patient distribution channels for recurrent epistaxis management in anticoagulated populations.
Emergency Room captures procedural volume concentration. Outpatient Clinic is gaining share fastest.
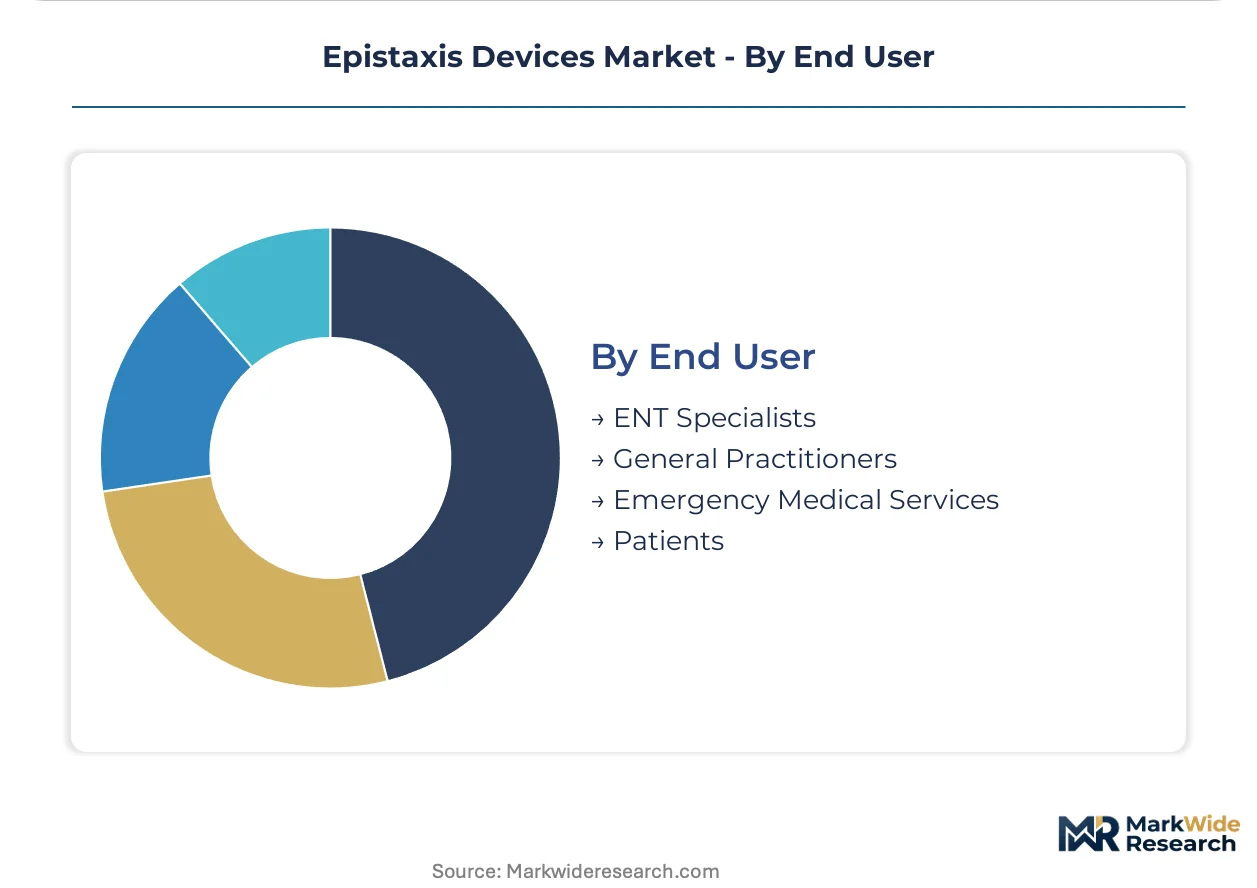
End User:
Training requirements and clinical decision authority stratify device specification demands across prescriber categories.
- ENT Specialists:Otolaryngologists drive adoption of advanced hemostatic interventions and dissolvable polymer formats. These specialists require hands-on instruction for proper nasal pack placement technique, creating training module embedding requirements within device packaging.
- Emergency Medical Services:First responders in field settings prioritize rapid deployment mechanical compression devices with minimal training burden.
- General Practitioners:Primary care settings rely on first-line chemical cautery and basic compression protocols.
- Patients:Self-administered intervention segment for recurrent epistaxis in anticoagulated home care populations.
ENT Specialists anchor premium segment demand. Emergency Medical Services is expanding addressable volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Emergency departments in the United States absorb premium pricing for rapid-deployment systems, while procurement in India and Southeast Asia remains anchored to cost-per-unit thresholds that favor basic mechanical compression formats.
United States
Aging demographics and direct oral anticoagulant therapy prevalence sustain procedural volume concentration across hospital emergency departments. FDA 510(k) pathway acceleration for absorbable polymer innovations shortens commercialization cycles for domestic developers. Academic medical centers in Boston and Baltimore pilot smart balloon catheter systems with embedded pressure sensors to reduce nursing observation burden.
Germany
Medical-grade silicone supply concentration among specialty chemical suppliers creates feedstock dependency for balloon catheter manufacturing. EU MDR Article 10 clinical evaluation requirements mandate prospective bleeding cessation data for hemostatic device claims. Industrial clusters in North Rhine-Westphalia host contract manufacturing facilities serving Middle East export markets.
India
Price-sensitive procurement environments sustain silver nitrate cauterization as first-line intervention for anterior bleeds. CDSCO oversight and BIS certification shape import dynamics for foreign device manufacturers. The Production Linked Incentive scheme for medical devices attracts contract manufacturing investment to Maharashtra and Gujarat for export-oriented production hubs.
Japan
PMDA regulatory frameworks govern hemostatic device approval timelines with emphasis on biocompatibility documentation. METI industrial policy supports domestic manufacturing of advanced polymer formulations. Tokyo and Osaka metropolitan areas concentrate tertiary referral centers where posterior epistaxis management demands premium balloon catheter interventions.
Brazil
ANVISA regulatory pathways for Class II medical devices create moderate market entry barriers for international manufacturers. Resource-constrained public hospital procurement favors low-cost chemical cautery over premium device formats. São Paulo state anchors private healthcare infrastructure where dissolvable polymer packs gain traction among outpatient ENT clinics.
Epistaxis Devices Market Competitive Landscape
Capability concentration sits with diversified medical technology conglomerates possessing integrated ENT portfolios; scale advantage sits with emergency care distribution specialists commanding dense hospital relationships. The vendor base organizes around three strategic archetypes: diversified platform players bundling epistaxis devices with surgical navigation systems, absorbent polymer specialists leveraging wound-care cross-selling infrastructure, and emergency room distribution density competitors deploying capital equipment placement programs. Dominant competitive moves include portfolio bundling with adjacent ENT modalities and direct hospital integration through training and restocking service contracts.
Within the diversified platform tier, Medtronic plc and Smith & Nephew plc exemplify archetypes anchoring competitive positioning through broad therapeutic portfolios. Stryker Corporation occupies a position representing emergency care distribution density strategies. These three entities collectively illustrate how competitive access points restructure around procurement centralization in hospital emergency departments.
| Leading Market Players |
|---|
| Medtronic plc |
| Smith & Nephew plc |
| Stryker Corporation |
| Teleflex Incorporated |
| Summit Medical |
| Medline Industries Inc. |
| DeRoyal Industries Inc. |
| Entellus Medical |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Japanese medical-grade silicone suppliers compresses margin flexibility across balloon catheter manufacturing tiers while simultaneously forcing device assemblers into premium pricing stratification that separates absorbable polymer formats from mechanical compression alternatives.
Pricing Analysis
Aftermarket service revenue from nasal pack training and restocking contracts drives lifetime value for manufacturers with direct hospital integration. Three-tier pricing structure across premium, standard, and economy levels separates smart balloon catheter systems with embedded sensors from basic mechanical packs and silver nitrate cauterization alternatives. Pricing pressure stems from EU MDR clinical evidence burdens that extend European market entry timelines and elevate compliance costs for smaller developers. Emergency medical services and resource-constrained procurement environments in India and Southeast Asia exhibit the highest price sensitivity, while academic medical centers in the United States absorb premium positioning for posterior bleed management technologies.
Supply Chain Analysis
Export-control regimes on advanced polymer formulations and medical-grade silicone feedstock limit technology transfer to emerging manufacturing hubs in India and Southeast Asia. Supply concentration rests in Germany and Japan for specialty silicone, the United States for hydrocolloid and oxidized cellulose chemistry, and India for contract manufacturing under PLI scheme incentives. Raw material dependencies include medical-grade silicone, absorbent polymers, and polyurethane elastomers for balloon construction. Single-source vulnerability from German and Japanese chemical suppliers creates feedstock price volatility that compresses assembler margins. Distribution runs through hospital group purchasing organizations in the United States and emergency care distribution networks serving consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
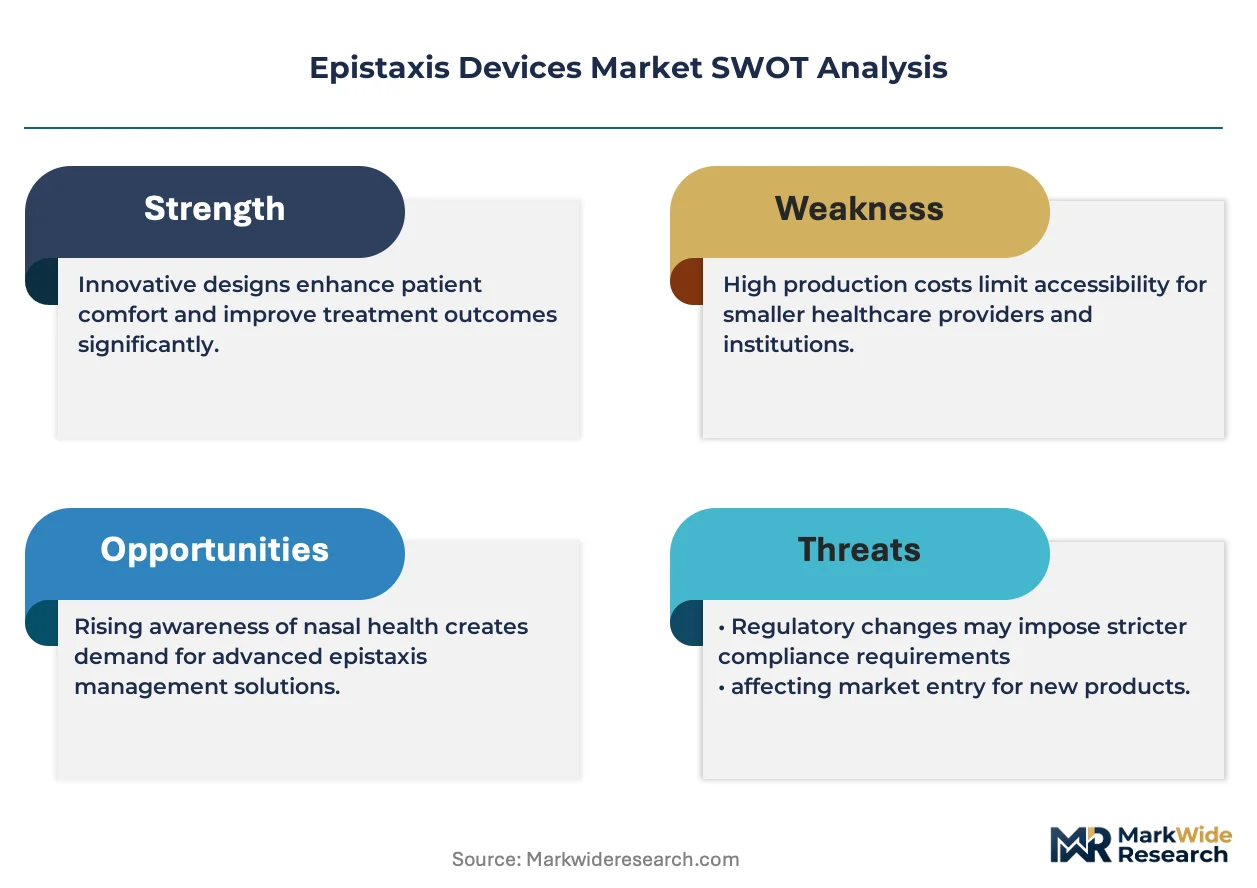
The epistaxis device market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA 510(k) pathway familiarity and established hospital formulary relationships create switching costs that disadvantage new entrants.
For Market Incumbents: Insulate market position by deepening captive supply of medical-grade silicone through backward integration into German and Japanese chemical supplier networks, and by embedding training modules within device packaging to lock in hospital emergency department procurement contracts against emerging polymer specialists. Silver nitrate cauterization persistence in price-sensitive markets and EU MDR evidence generation burdens represent primary threats requiring defensive certification investment. For New Entrants and Emerging Players: Freestanding ENT ambulatory surgery centers in the United States represent underpenetrated deployment channels seeking single-use dissolvable packs to eliminate follow-up removal appointments. Target outpatient clinic conversion through absorbable polymer chemistry innovation and direct-to-clinic distribution partnerships that bypass consolidated hospital purchasing authority. India's PLI scheme manufacturing incentives offer export-oriented production hub access for Middle East and Southeast Asian market entry. For Investors and Strategic Acquirers: Absorbent polymer specialists with wound-care cross-selling infrastructure and established hospital training contract networks represent the highest-value acquisition targets for portfolio diversification into emergency care settings. Long-term viability hinges on regulatory entrenchment durability and hospital consolidation trajectory. Monitor FDA 510(k) clearance velocity for absorbable polymer innovations as the inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined clearance timelines compress commercialization cycles for absorbable polymer device developers. |
| Hospital System Partnership | Direct integration with emergency department formulary committees secures recurring restocking contract revenue. |
| CE Marking Pathway Investment | EU MDR Article 10 compliance enables European market access for hemostatic performance claims. |
| Software Companion Development | Bluetooth-enabled pressure telemetry systems reduce nursing observation burden at academic medical centers. |
| Reimbursement Strategy | Coding alignment with anticoagulant therapy prevalence elevates procedural reimbursement for complex interventions. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with otolaryngologists, emergency department purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CDSCO import registration databases, hospital procurement contracts, and EU MDR technical documentation. Bottom-up triangulation of device shipment volumes and top-down reconciliation against health system procedural data anchored market sizing.
Forecast inputs considered product type segmentation across nasal packs, balloon catheters, compresses, and cauterizing devices; material chemistry tiers spanning absorbent polymers, silicone, and polyurethane; and application settings including emergency rooms, outpatient clinics, hospitals, and home care. CAGRs were derived from regression analysis of procedural volume drivers including aging demographics and anticoagulant therapy prevalence across the analysis window. Anticoagulant prescription trends and health system consolidation patterns served as industry-specific forecast inputs.
Practitioners should monitor FDA regulatory pathway modifications, EU MDR enforcement intensity, and medical-grade silicone supply disruptions for early signals of forecast revision. Material shifts in anticoagulant therapy protocols or hospital procurement centralization velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Medical Puncture Navigation Robot Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Global Medical Drones Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
Global Colposcopy Devices Market
Medical Devices
Global Pacemakers Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Asthma Device Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Prostate Biopsy Devices Market