
 Alexandrite Gemstone Lasers Market | 2026-2036
Alexandrite Gemstone Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Alexandrite Gemstone Lasers Market Analysis
A shortage of specialized crystal growth engineers is redrawing competitive boundaries in alexandrite laser manufacturing. Candela Medical leverages its vertically integrated alexandrite rod production to sustain margin control across the aesthetic device value chain. Cynosure anchors North American demand through its installed base of hair removal platforms. Lutronic Corporation differentiates by competing across both Q-switched and long-pulse modalities in Asian dermatology markets.
Alexandrite gemstone lasers are solid-state systems employing chromium-doped chrysoberyl crystals emitting at 755 nanometers, manufactured through Czochralski pulling or hydrothermal synthesis of synthetic alexandrite boules before precision doping and optical finishing. Their primary commercial purpose centers on selective photothermolysis for dermatological procedures and precision material processing where tunable wavelength absorption proves critical. Solid-state lasers occupy the dominant revenue position given alexandrite's inherent gain medium architecture, while pulsed laser technology captures accelerating share as nanosecond-domain pulse structures improve treatment efficacy with reduced thermal collateral damage. Medical aesthetic procedures concentrate the largest end-user margin pool, though industrial applications in gemstone cutting sustain premium pricing for specialized system configurations.
FDA 510(k) premarket notification requirements govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for laser systems entering European markets. ISO 13485 quality management certification functions as a baseline market access predicate across major jurisdictions, with notified body scrutiny intensifying for active implantable and high-power laser classifications. Stakeholders must monitor evolving MDR technical documentation requirements and FDA software-as-medical-device guidance that could reclassify AI-integrated treatment planning modules.
Market Dynamics
Alexandrite laser manufacturing is consolidating around captive crystal growth capabilities as synthetic boule quality becomes the primary bottleneck separating profitable system integrators from component-dependent assemblers. This supply concentration is redrawing competitive boundaries across dermatology device supply chains.
Growth Catalysts
- FDA 510(k) pathway compression:Streamlined premarket notification timelines for laser systems are accelerating commercialization cycles for manufacturers targeting United States dermatology clinics.
- Q-switched modality expansion:Nanosecond-domain pulse structures are improving tattoo removal efficacy while reducing thermal collateral damage, broadening treatable patient populations.
- German engineering cluster density:Concentrated medical laser expertise around Jena and Florence is sustaining precision optics innovation and specialized workforce pipelines.
Market Restraints
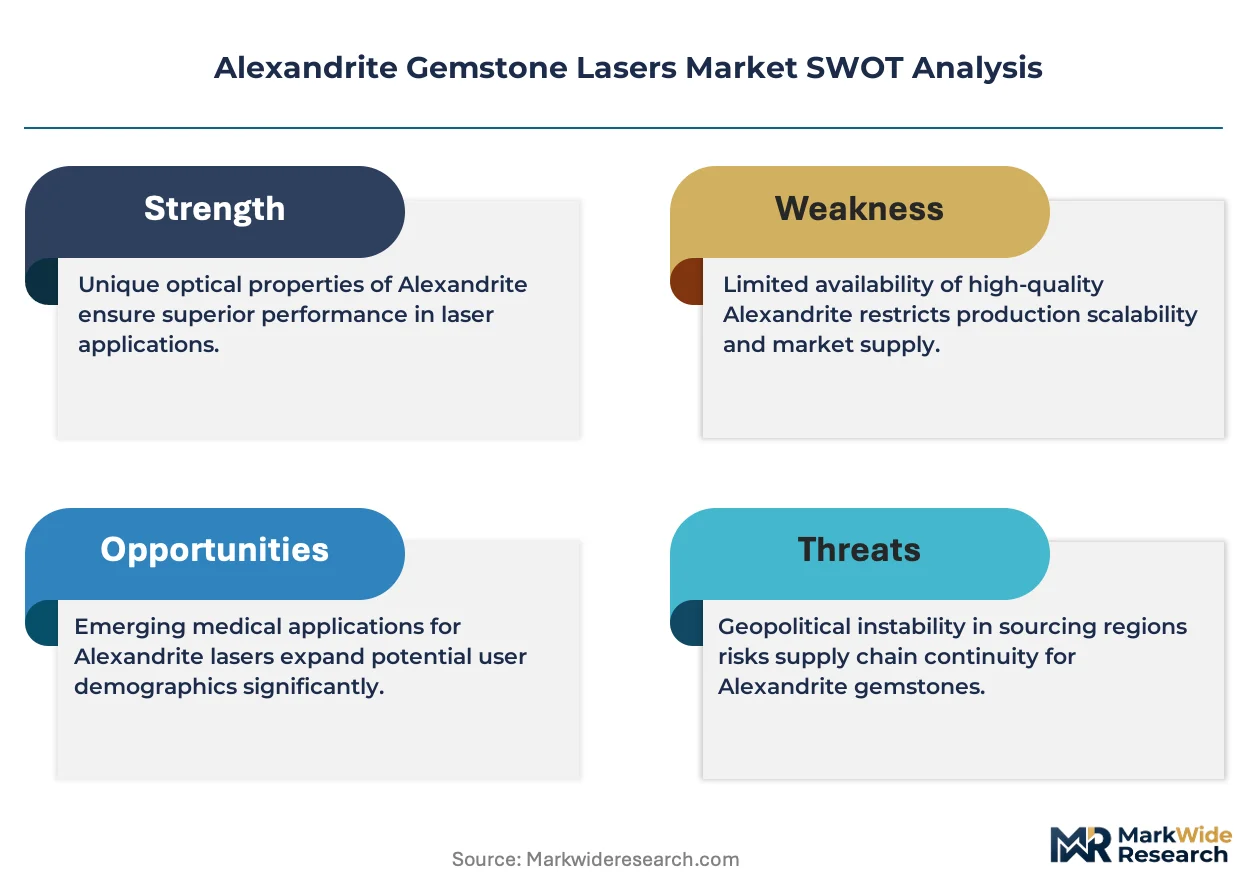
- Chromium-doped chrysoberyl supply concentration:Limited qualified synthetic crystal growers constrain alexandrite rod availability and inflate input costs for non-integrated device manufacturers.
- EU MDR clinical evidence requirements:Stricter technical documentation and notified body scrutiny for active laser classifications are extending time-to-market for European commercialization.
- Diode laser substitution:Lower-cost 808 nanometer and 1064 nanometer platforms are capturing price-sensitive hair removal segments from alexandrite systems.
Strategic Opportunities
- Industrial gemstone processing:Precision cutting applications for colored stones are opening non-medical revenue streams with premium system configurations.
- AI-integrated treatment planning:Convergence of machine learning algorithms with laser parameter optimization is creating differentiated service offerings in aesthetic chains.
- Asian dermatology market penetration:Underdeveloped laser aesthetics infrastructure in tier-two Chinese cities offers expansion vectors for long-pulse platform providers.
Industry Challenges
- Czochralski growth engineer scarcity:Specialized crystal pulling expertise is concentrating at legacy manufacturers, constraining new entrant scale-up.
- ISO 13485 certification timelines:Quality management system implementation for active laser devices demands 18-24 month validation cycles before market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alexandrite Gemstone Lasers Market |
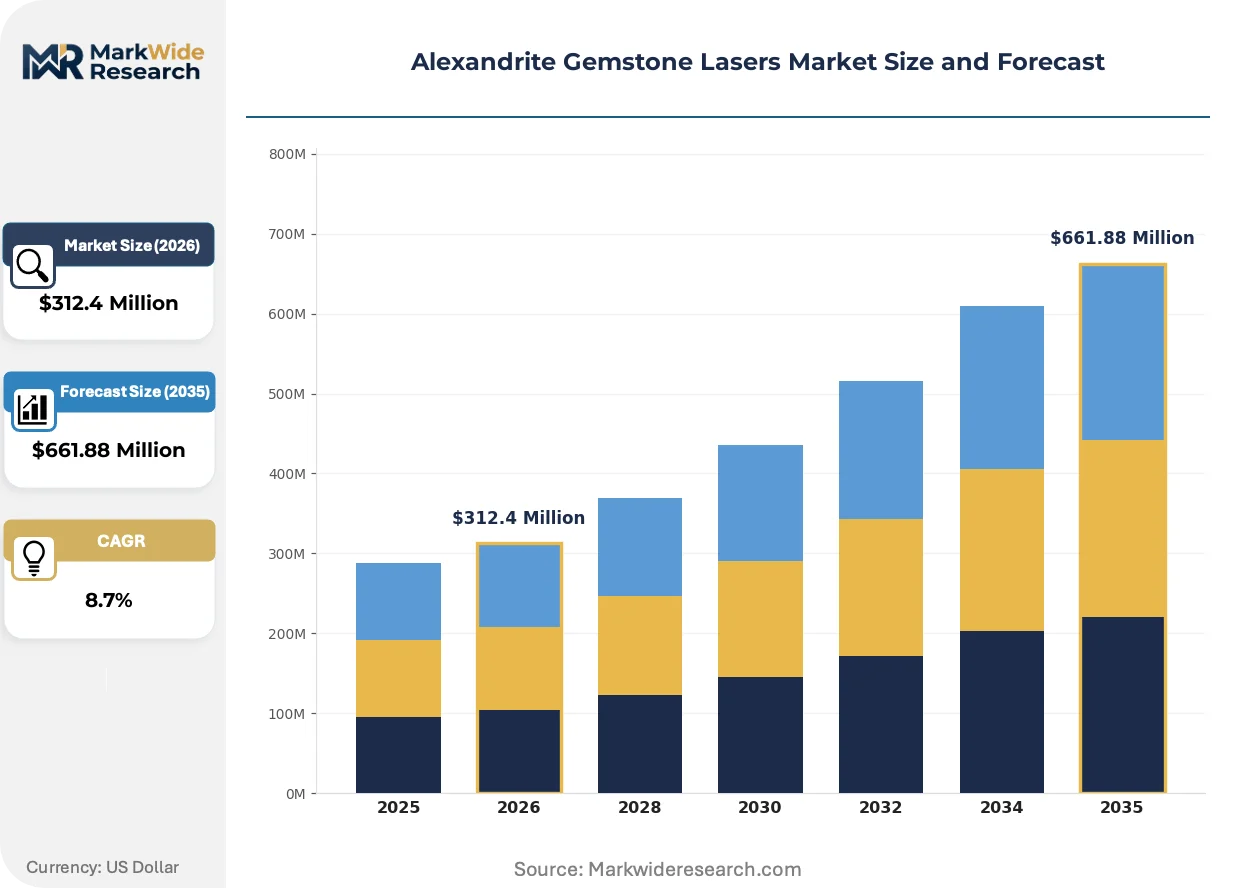
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Lasers, Diode Lasers, Fiber Lasers, Gas Lasers End User: Jewelry Manufacturers, Medical Clinics, Research Laboratories, Industrial Applications Application: Gem Cutting, Laser Engraving, Medical Aesthetic Procedures, Laser Marking Technology: Q-Switching, Continuous Wave, Pulsed Laser, Nanosecond Technology |
| Companies Covered | Candela Medical, Cynosure, Lutronic Corporation, Lumenis, Alma Lasers, Quanta Systems, Asclepion Laser Technologies, DEKA, Fotona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alexandrite Gemstone Lasers Market Emerging Trajectories
Pulse structure engineering and software-defined treatment protocols are compressing the gap between clinical efficacy and operator skill requirements. These developments are democratizing alexandrite laser deployment beyond specialist dermatologists.
Picosecond-domain alexandrite architectures are supplanting traditional nanosecond systems in tattoo removal applications. Aesthetic clinic chains in the United States are accelerating adoption timelines as reduced pulse durations improve pigment fragmentation while minimizing surrounding tissue thermal load. This technology transition is compressing treatment session counts and enabling competitive differentiation through faster patient throughput.
EU Medical Device Regulation Article 10 technical documentation requirements are intensifying clinical evidence burdens for laser system manufacturers. Notified body scrutiny of active device classifications is forcing portfolio rationalization among smaller European vendors. Germany-based engineering firms are responding by consolidating regulatory affairs functions and pre-submission engagement with BSI and TÜV SÜD.
After-sales service unbundling is fragmenting traditional capital equipment purchasing patterns in North American dermatology practices. Device financing through third-party lessors is displacing outright ownership, compressing manufacturer margin capture to consumables and software subscriptions. This shift is most visible in multi-site aesthetic chains seeking operational flexibility over balance sheet asset accumulation.
Alexandrite Gemstone Lasers Market Segmentation
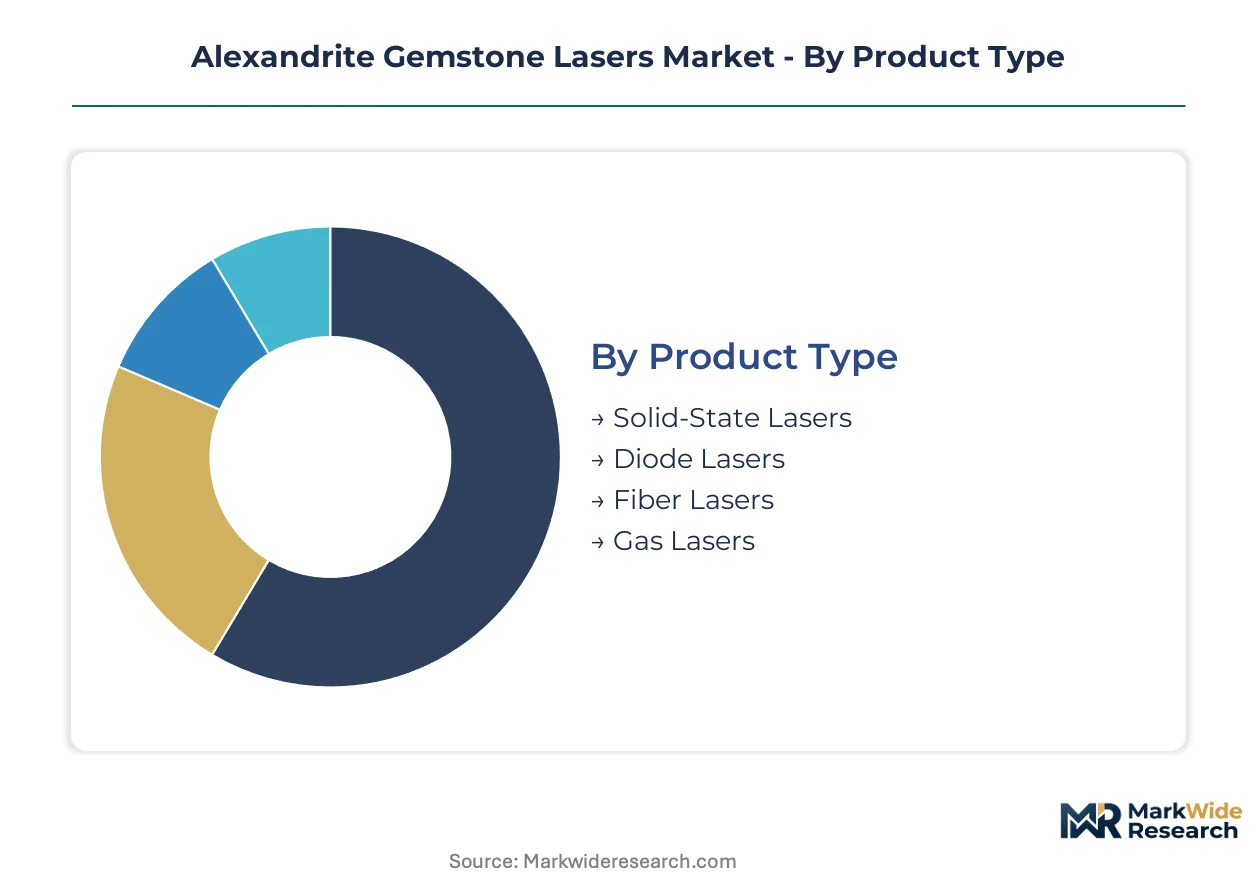
Alexandrite laser manufacturers configure product portfolios across four intersecting dimensions. Each segmentation axis carries distinct margin profiles and regulatory requirements that shape competitive positioning.
Product Type:
Solid-state architectures command the highest gross margins due to captive crystal growth advantages and proprietary resonator designs.
- Solid-State Lasers:Chromium-doped chrysoberyl crystals in rod or slab configurations deliver 755 nanometer output with superior beam quality for dermatological precision. Medical aesthetic chains in the United States concentrate procurement here, drawn by established clinical protocols and FDA 510(k) precedent libraries.
- Diode Lasers:Semiconductor-based alternatives at 808 nanometers and 1064 nanometers compete aggressively on footprint and cooling simplicity. Price-sensitive hair removal segments in Germany and South Korea are migrating toward these platforms, pressuring alexandrite system ASPs.
- Fiber Lasers:Rare-earth doped silica architectures offer beam delivery flexibility for industrial material processing. Jewelry manufacturers in India leverage fiber-coupled systems for precision gemstone cutting applications.
- Gas Lasers:CO2 and excimer alternatives occupy niche medical and research roles where tissue ablation depth requires longer infrared wavelengths. Research laboratories in Japan maintain limited installed bases for specialized histological applications.
The dominant share belongs to Solid-State Lasers, while Diode Lasers are closing the gap fastest.
End User:
Customer concentration patterns split between capital-rich institutional buyers and fragmented commercial operators with diverging financing preferences.
- Jewelry Manufacturers:Precision cutting and engraving of colored gemstones demands high peak power with minimal thermal damage zones. Manufacturers in Jaipur and Surat, India, represent concentrated demand for compact Q-switched systems.
- Medical Clinics:Dermatology and aesthetic medicine practices drive recurring revenue through consumable handpieces and service contracts. Multi-site chains in the United States are shifting toward subscription-based equipment financing models.
- Research Laboratories:Spectroscopy and materials science applications require tunable wavelength stability and extended pulse control. Academic institutions in Germany and Switzerland sustain demand for specialized system configurations.
- Industrial Applications:Micromachining and semiconductor processing utilize alexandrite's tunable absorption characteristics. Precision engineering firms in Japan deploy these systems for ceramic scribing and thin-film patterning.
Medical Clinics generate the largest revenue pool, though Jewelry Manufacturers are expanding most quickly in absolute terms.
Application:
Clinical efficacy documentation and reimbursement pathways determine which applications absorb R&D investment and regulatory submission resources.
- Gem Cutting:Controlled fracture propagation in colored stones exploits alexandrite's absorption match with chromium-bearing minerals. Artisanal cutting houses in Sri Lanka and Myanmar source refurbished medical lasers for secondary gem processing.
- Laser Engraving:Subsurface marking of transparent materials requires precise focal depth control without surface ablation. Luxury goods manufacturers in Switzerland deploy these systems for watch crystal personalization.
- Medical Aesthetic Procedures:Selective photothermolysis for hair removal, tattoo elimination, and pigmented lesion treatment represents the primary commercial volume. FDA-cleared indications in the United States cover Fitzpatrick skin types I-IV with expanding type V-VI protocols.
- Laser Marking:Permanent identification coding on medical devices and aerospace components demands corrosion-resistant annealing marks. German automotive suppliers specify alexandrite systems for traceability compliance under EU MDR.
Medical Aesthetic Procedures hold the dominant position, while Gem Cutting is gaining share fastest among non-medical verticals.
Technology:
Pulse generation architectures differentiate clinical outcomes and operator skill requirements, with shorter domains commanding technology premiums.
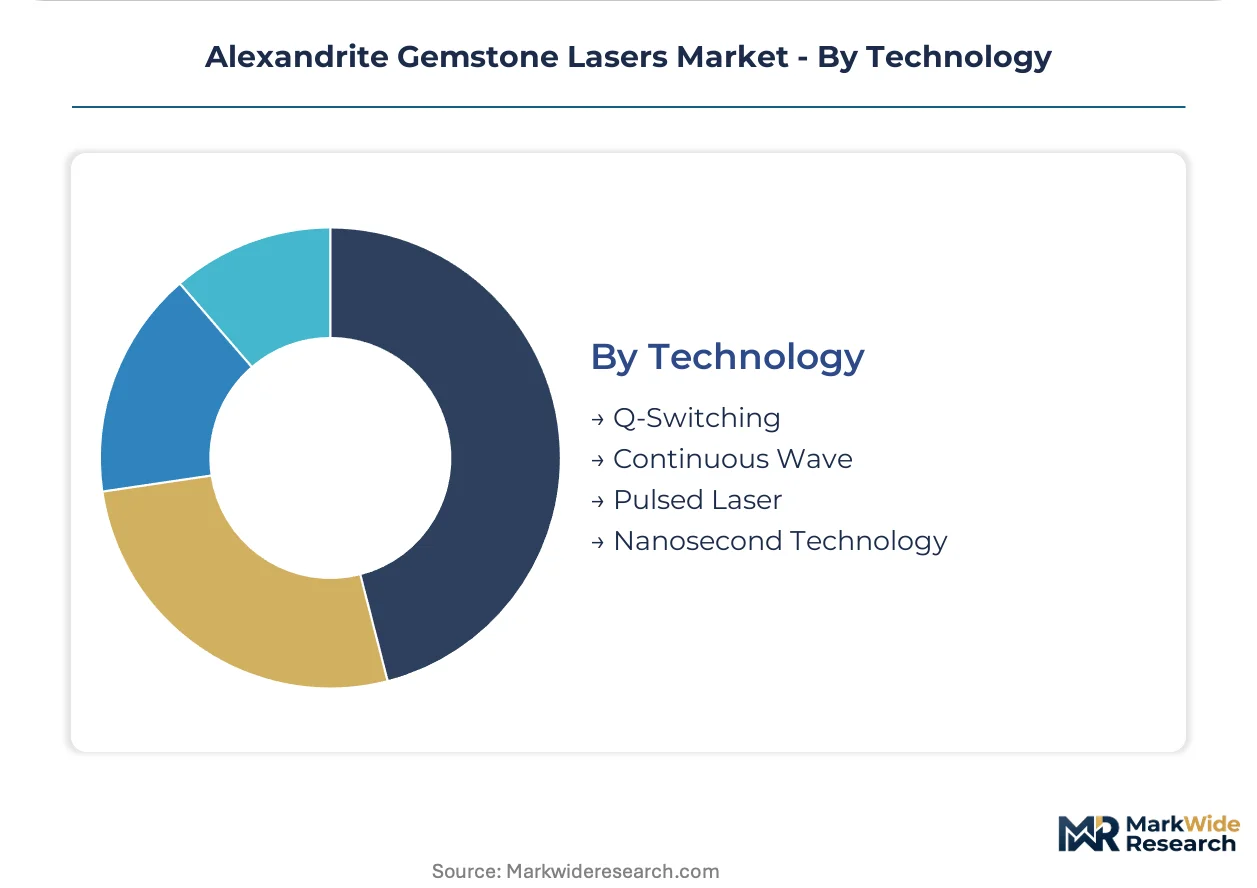
- Q-Switching:Electro-optic or acousto-optic modulation produces nanosecond-scale giant pulses optimized for pigment fragmentation. Tattoo removal protocols in the United States are standardizing on Q-switched 755 nanometer platforms for multi-color ink clearance.
- Continuous Wave:Uninterrupted emission supports thermal coagulation applications in vascular lesion treatment. German dermatology clinics retain limited installed bases for specific telangiectasia protocols.
- Pulsed Laser:Millisecond-domain structures enable hair removal through gradual follicular heating with epidermal cooling integration. Long-pulse alexandrite systems dominate Asian aesthetic markets where darker skin types require conservative thermal loading.
- Nanosecond Technology:Precise pulse width control bridges Q-switched peak power and long-pulse thermal accumulation. Emerging picosecond architectures are supplanting traditional nanosecond platforms in premium tattoo removal segments.
Pulsed Laser technology commands the largest installed base, while Q-Switching is climbing the fastest as picosecond architectures penetrate aesthetic chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where Asclepion and DEKA command premium system configurations, while Chinese manufacturers compete on diode laser substitution at compressed margins. This asymmetry reshapes procurement patterns across dermatology chains and industrial users.
United States
Multi-site aesthetic chains in Florida and Texas are accelerating equipment financing through third-party lessors rather than capital purchases. FDA 510(k) premarket notification pathways compress commercialization timelines for laser system manufacturers targeting dermatology clinics. Boston and Los Angeles anchor dense clusters of medical device regulatory affairs expertise serving pre-submission engagement strategies.
Germany
Precision optics engineering concentrates around Jena and Florence with specialized workforce pipelines sustaining medical laser innovation. EU Medical Device Regulation Article 10 technical documentation requirements intensify clinical evidence burdens for active laser classifications entering European markets. Asclepion Laser Technologies and DEKA anchor this engineering cluster with vertically integrated crystal growth capabilities.
China
Tier-two cities in Sichuan and Jiangsu provinces present expansion vectors for long-pulse platform providers as dermatology infrastructure develops. NMPA medical device registration pathways govern commercialization for imported laser systems entering domestic aesthetic markets. Yangtze River Delta manufacturing bases supply component assemblies for non-integrated device manufacturers lacking captive crystal growth.
Japan
Research laboratories in Kanto and Kansai regions sustain demand for specialized system configurations requiring tunable wavelength stability. PMDA pharmaceutical and medical device agency oversight applies to laser systems marketed for therapeutic indications beyond aesthetic applications. Precision engineering firms in Nagoya deploy alexandrite systems for ceramic scribing and thin-film patterning in semiconductor processing.
India
Jewelry manufacturers in Jaipur and Surat represent concentrated demand for compact Q-switched systems in precision gemstone cutting applications. BIS certification requirements for imported laser equipment create compliance barriers for non-domestic manufacturers entering the industrial processing segment. Artisanal cutting houses source refurbished medical lasers for secondary gem processing, opening aftermarket service opportunities.
Alexandrite Gemstone Lasers Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the alexandrite laser value chain. Captive crystal growth capabilities separate profitable system integrators from component-dependent assemblers, consolidating supply-side power among legacy manufacturers. Three archetypes dominate: vertically integrated device manufacturers with in-house boule production, specialized optics engineering firms with regulatory expertise, and regional assemblers sourcing rods from qualified growers. Competitive moves concentrate on backward integration into synthetic chrysoberyl production and strategic partnerships with Asian dermatology distributors.
Among German engineering specialists, Asclepion Laser Technologies and DEKA exemplify the vertically integrated archetype with Jena-area manufacturing bases. Candela Medical occupies a position representing North American aesthetic device consolidation with established 510(k) precedent libraries. Lutronic Corporation sits within the Asian market penetration tier, competing across multiple pulse modalities in underdeveloped dermatology infrastructure markets.
| Leading Market Players |
|---|
| Candela Medical |
| Cynosure |
| Lutronic Corporation |
| Lumenis |
| Alma Lasers |
| Quanta Systems |
| Asclepion Laser Technologies |
| DEKA |
| Fotona |
| Others |
Supply Flow & Price Mechanics
Eighteen-month crystal growth lead times for chromium-doped chrysoberyl boules concentrate pricing power with German and Japanese manufacturers possessing captive Czochralski pulling capabilities, while non-integrated assemblers absorb margin compression from rod spot-market volatility.
Pricing Analysis
German-manufactured alexandrite laser systems command 40-60% price premiums over Chinese-assembled alternatives in North American dermatology procurement. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification status and after-sales service bundling. Cost compression in the mid-tier segment intensifies as 808 nanometer diode lasers capture price-sensitive hair removal volumes. Multi-site aesthetic chains exhibit highest price sensitivity through equipment financing preferences, while research laboratories demonstrate lowest sensitivity due to grant-funded capital budgets.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for synthetic crystal feedstock and precision optical components. Manufacturing concentrates in Germany, Japan, and the United States, drawing from chromium oxide suppliers in South Africa and Kazakhstan. Supply chain vulnerability rests on single-source dependency for qualified Czochralski growth engineers. Distribution runs through authorized medical device distributors in regulated markets and direct OEM relationships for industrial gemstone processing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized crystal growth engineering talent pools have contracted to fewer than a dozen qualified facilities worldwide, transforming synthetic alexandrite boule production into the decisive capability gap separating profitable system integrators from margin-squeezed assemblers.
For Market Incumbents: Fortify backward integration into synthetic chrysoberyl production through acquisition of qualified Czochralski facilities in Germany or Japan. Expand regulatory affairs capacity in anticipation of EU MDR Article 10 clinical evidence intensification for active laser classifications. Prioritize ISO 13485 certification maintenance as competitive moat against emerging Asian assemblers. For New Entrants and Emerging Players: Differentiate on AI-integrated treatment planning software modules that reclassify under FDA software-as-medical-device guidance. Target tier-two Chinese cities in Sichuan and Jiangsu provinces where dermatology infrastructure remains underdeveloped. Pursue NMPA registration partnerships with established domestic distributors rather than direct market entry. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because captive crystal growth capabilities are concentrating supply-side power among legacy manufacturers with Jena-area or Japanese manufacturing bases. Acquisition targets should display vertical integration into boule production or exclusive supply agreements with qualified growers. Monitor FDA 510(k) clearance velocity for picosecond-domain architectures as inflection signal for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Crystal Growth Facility Acquisition | Captive boule production secures margin control against rod spot-market volatility. |
| AI Treatment Planning Module Development | FDA software-as-medical-device guidance creates regulatory differentiation pathway. |
| EU MDR Technical Documentation Investment | Notified body pre-submission engagement compresses European commercialization timelines. |
| Asian Distribution Partnership | NMPA-registered domestic partners navigate tier-two city market entry complexity. |
| Picosecond Architecture R&D Scale-Up | Reduced pulse durations improve tattoo removal efficacy and patient throughput economics. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and hospital procurement contract records. Primary interviews encompassed crystal growth engineers at synthetic chrysoberyl manufacturers, regulatory affairs directors at laser device OEMs, and dermatology clinic procurement managers at multi-site aesthetic chains. Secondary sources included notified body guidance documents, ISO 13485 certification registries, and customs trade data for laser component imports. Bottom-up unit economics triangulated against top-down market sizing across solid-state and pulsed laser technology segments.
Segmentation dimensions modeled include product architecture, pulse generation technology, end-user category, and application vertical across the projection horizon. CAGRs derive from installed base growth rates, replacement cycle analysis, and pricing trajectory assumptions for premium versus standard system tiers. Industry-specific forecast inputs incorporate FDA 510(k) clearance velocity metrics and EU MDR notified body capacity constraints.
Material uncertainties — regulatory reclassification of AI-integrated modules, chromium feedstock price volatility, and qualified crystal grower labor mobility — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable reimbursement pathways for aesthetic procedures and continued 755 nanometer wavelength clinical preference. Recalibration cycles align with material shifts in FDA guidance issuance and EU MDR implementation enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Cranial Implants Treatment Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Intravaginal Device Market
Medical Devices
Oxygenator Market
Medical Devices
Clinical Rollators Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Brachytherapy Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Cardiac Catheters and Guidewires Market