
 Acid Sphingomyelinase Deficiency Market | 2026-2036
Acid Sphingomyelinase Deficiency Market Size, Share, and Industry Trends Forecast 2026-2036
Acid Sphingomyelinase Deficiency Market Analysis
The capital-intensity divergence between gene therapy platforms and small-molecule developers is bifurcating competitive strategy across the Acid Sphingomyelinase Deficiency landscape. Sanofi leverages its recombinant enzyme manufacturing infrastructure to sustain supply security for chronic replacement regimens. Takeda anchors its position through rare disease commercial infrastructure inherited from legacy Shire operations. Orchard Therapeutics specializes in autologous ex vivo gene correction, occupying a premium tier that demands distinct reimbursement negotiation capabilities.
Acid sphingomyelinase deficiency denotes a lysosomal storage disorder arising from SMPD1 mutations that cripple sphingomyelin hydrolysis, causing progressive lipid accumulation in macrophage-rich organs such as liver, spleen, and lung. The condition demands interventions that restore enzymatic activity or curtail substrate burden, with recombinant enzymes currently dominating commercial revenue while gene therapy platforms attract development-stage investment. Viral vector delivery systems are capturing disproportionate R&D allocation due to their potential for durable correction, whereas substrate reduction therapy retains relevance for patients with contraindications to biologics. Nanoparticle delivery approaches remain preclinical but represent a margin pool should they resolve immunogenicity barriers that constrain existing modalities.
FDA orphan drug incentives and EMA PRIME designation frameworks shape clinical development timelines and market exclusivity structures for acid sphingomyelinase deficiency therapeutics. The EU F-Gas Regulation constrains certain propellant and solvent applications in manufacturing processes, indirectly influencing production economics for inhaled or aerosolized delivery formats. Stakeholders must monitor evolving gene therapy reimbursement models and manufacturing scale-up feasibility to determine portfolio prioritization between one-time curative interventions and chronic maintenance therapies.
Market Dynamics
Gene therapy manufacturing scale-up is decomposing the chronic maintenance paradigm that has sustained enzyme replacement revenue models for acid sphingomyelinase deficiency. Developers face immediate portfolio decisions between one-time curative interventions and recurring biologic regimens as viral vector production capacity expands.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity provisions accelerate clinical trial enrollment incentives for rare lysosomal storage disorders. Pediatric treatment centers in the United States prioritize protocol participation.
- EMA PRIME Designation:Accelerated assessment pathways compress regulatory review timelines for acid sphingomyelinase deficiency therapeutics. Early access schemes in Germany anchor European patient identification.
- Autologous Ex Vivo Gene Correction:Lentiviral vector platforms enable durable enzymatic restoration without immunosuppression. Specialized cell processing facilities in Boston and London attract development-stage capital.
Market Restraints
- Viral Vector Manufacturing Bottlenecks:Plasmid DNA scarcity and suspension cell line limitations constrain gene therapy batch yields. Contract manufacturing organizations in Maryland and North Carolina operate at capacity ceilings.
- EU F-Gas Regulation Compliance:Perfluorinated compound restrictions increase solvent procurement costs for aerosolized delivery formulations. Manufacturing sites in the Netherlands and Belgium face reformulation requirements.
- Substrate Reduction Therapy Substitution:Small-molecule alternatives retain relevance for patients with anti-drug antibodies or infusion reactions. Miglustat analogs compete in the chronic maintenance segment.
Strategic Opportunities
- Underpenetrated Pediatric Neurology Networks:Academic medical centers in Spain and Italy lack dedicated lysosomal storage disease coordinators. Regional expansion targets 40% of undiagnosed Type B cases.
- Reimbursement Model Convergence:Outcome-based payment frameworks for gene therapy align provider incentives with durable response metrics. Germany's G-BA assessment procedures establish precedent for annuity structures.
- Nanoparticle Delivery Platforms:Lipid nanoparticle encapsulation of recombinant enzyme reduces immunogenicity and enables subcutaneous administration. Preclinical programs at MIT and University of Pennsylvania advance toward IND-enabling studies.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Viral vector process development and analytical method validation require specialized biochemical engineering expertise. Boston and San Francisco biotech clusters compete for limited personnel pools.
- Long-Term Follow-Up Infrastructure:Fifteen-year post-treatment monitoring mandates for gene therapy impose data collection burdens. Clinical sites must sustain patient registry participation across investigator transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acid Sphingomyelinase Deficiency Market |
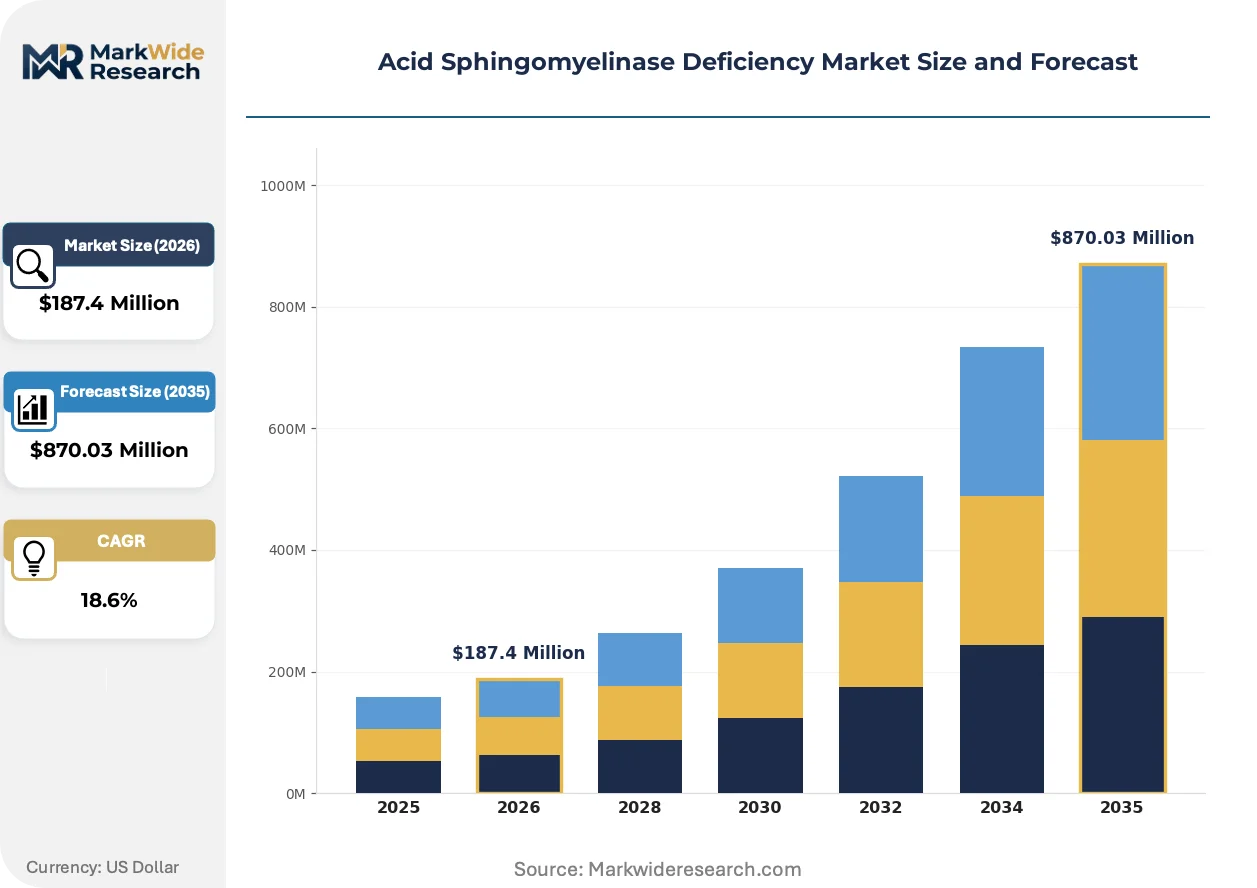
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Enzymes, Gene Therapy, Substrate Reduction Therapy, Small Molecule Inhibitors End User: Hospitals, Specialty Clinics, Research Institutions, Home Healthcare Technology: CRISPR, RNA Interference, Viral Vectors, Nanoparticle Delivery Application: Pediatric Treatment, Disease Management, Clinical Research, Patient Support Programs |
| Companies Covered | Sanofi, Takeda, Orchard Therapeutics, Orphazyme, Avrobio, Catalyst Pharmaceuticals, Lexicon Pharmaceuticals, Amicus Therapeutics, BridgeBio Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acid Sphingomyelinase Deficiency Market Emerging Trajectories
Next-generation delivery modalities are fragmenting the therapeutic monopoly held by intravenous enzyme replacement. Developers now confront platform selection decisions that will determine manufacturing footprints and reimbursement negotiations for the next decade.
AAV-mediated gene therapy is decomposing the chronic infusion dependency that has defined acid sphingomyelinase deficiency management. Pediatric metabolic centers in Philadelphia and Cincinnati are prioritizing clinical trial access for treatment-naive patients. This shift is compressing the addressable market for maintenance biologics while expanding upfront gene therapy expenditure pools.
EMA's F-Gas Regulation is forcing solvent substitution in viral vector purification processes. Manufacturers must validate alternative chromatography buffers that maintain vector potency without perfluorinated compound content. Gene therapy developers with European supply chains face 18-24 month process revalidation timelines.
Patient advocacy organizations are consolidating newborn screening expansion campaigns across state health departments. Parent-led foundations in California and New York are directly funding SMPD1 assay validation studies. This behavioral shift is accelerating pre-symptomatic diagnosis rates and compressing the interval between identification and treatment initiation.
Acid Sphingomyelinase Deficiency Market Segmentation
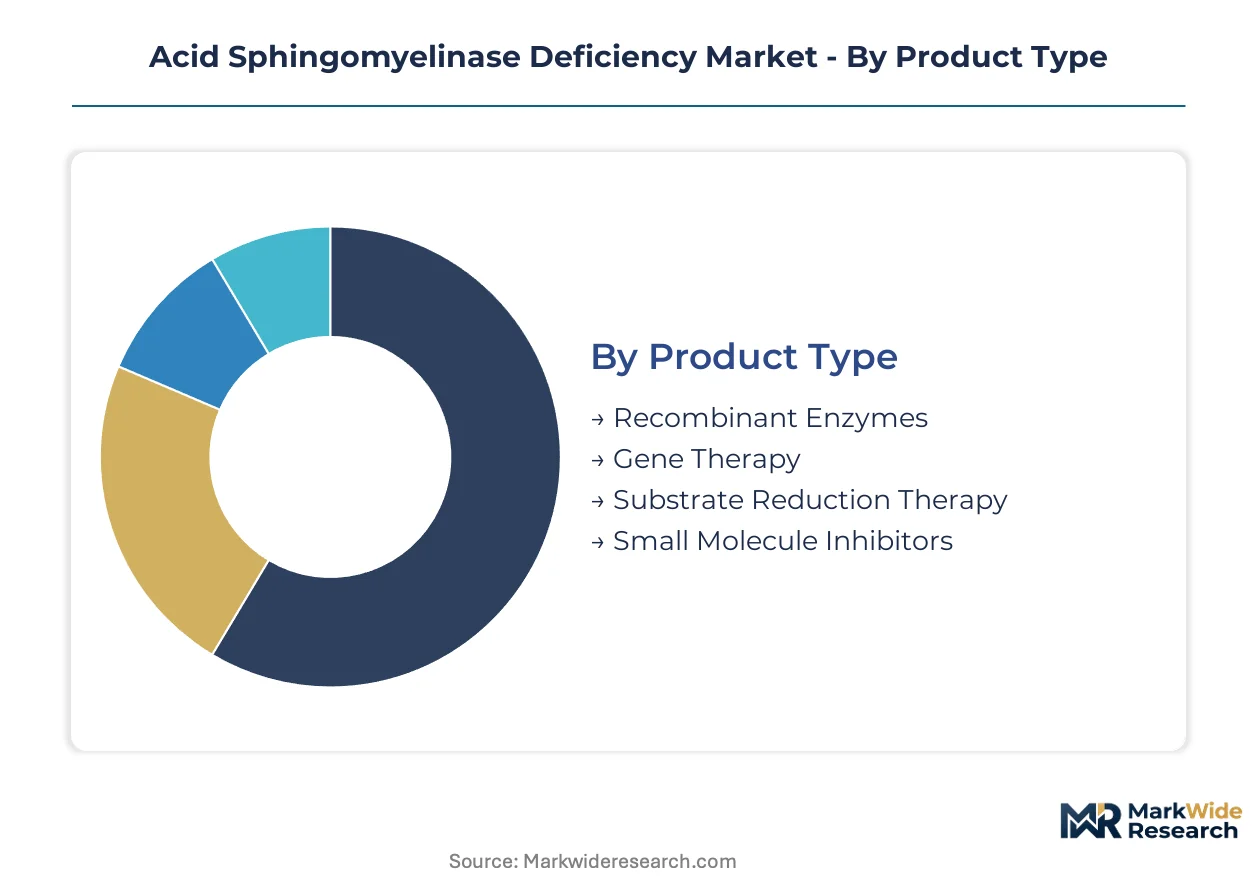
Therapeutic modality selection in acid sphingomyelinase deficiency determines manufacturing footprints, reimbursement negotiations, and patient access pathways. Platform economics diverge sharply between chronic maintenance regimens and one-time curative interventions.
Product Type:
Domestic production concentrates recombinant enzymes in established biomanufacturing clusters, while gene therapy platforms depend on specialized viral vector facilities with transatlantic supply chains.
- Recombinant Enzymes:Intravenous infusions of acid sphingomyelinase restore catalytic function in macrophage-rich organs. Demand clusters at pediatric metabolic centers in Philadelphia and Cincinnati where chronic maintenance protocols dominate clinical practice.
- Gene Therapy:AAV and lentiviral vector delivery enables durable SMPD1 expression without repeated dosing. German lysosomal storage disease clinics anchor European adoption, driven by outcome-based reimbursement frameworks from G-BA assessments.
- Substrate Reduction Therapy:Small-molecule glucosylceramide synthase inhibitors provide alternatives for patients with biologic contraindications.
- Small Molecule Inhibitors:Oral formulations target residual enzymatic activity preservation in attenuated phenotypes.
Recombinant enzymes command the established base. The steepest expansion runs through gene therapy.
End User:
Site-of-care economics fragment procurement patterns, with high-complexity infusions requiring hospital infrastructure and maintenance therapies shifting toward decentralized administration.
- Hospitals:Academic medical centers manage acute complications and gene therapy conditioning regimens. Tertiary pediatric facilities in Boston and London concentrate infusion capacity for enzyme replacement protocols.
- Specialty Clinics:Dedicated lysosomal storage disease centers coordinate multidisciplinary care and clinical trial access. Spanish and Italian networks remain underpenetrated relative to diagnostic prevalence.
- Research Institutions:University-affiliated sites conduct natural history studies and biomarker validation for regulatory submissions.
- Home Healthcare:Subcutaneous enzyme formulations and remote monitoring enable patient-managed chronic therapy outside institutional settings.
Hospitals retain the highest-acuity patient share. Specialty clinics are gaining share fastest through newborn screening expansion.
Technology:
Intellectual property concentration varies across modalities, with viral vector manufacturing expertise residing in contract development organizations and CRISPR platforms controlled by gene editing specialists.
- CRISPR:In vivo base editing approaches target hepatocyte-specific SMPD1 correction. Preclinical programs at MIT and University of Pennsylvania advance toward IND-enabling toxicology studies.
- RNA Interference:Sphingomyelin synthase knockdown reduces substrate accumulation in parallel with enzyme restoration strategies.
- Viral Vectors:AAV serotype selection and capsid engineering determine tissue tropism and immunogenicity profiles for liver-directed gene therapy.
- Nanoparticle Delivery:Lipid nanoparticle encapsulation of recombinant enzyme reduces neutralizing antibody formation and enables subcutaneous administration routes.
Viral vectors anchor current clinical development. Nanoparticle delivery is expanding most quickly through preclinical partnerships.
Application:
Patient journey stage determines intervention intensity, with pre-symptomatic diagnosis compressing timelines between identification and treatment initiation across state newborn screening programs.
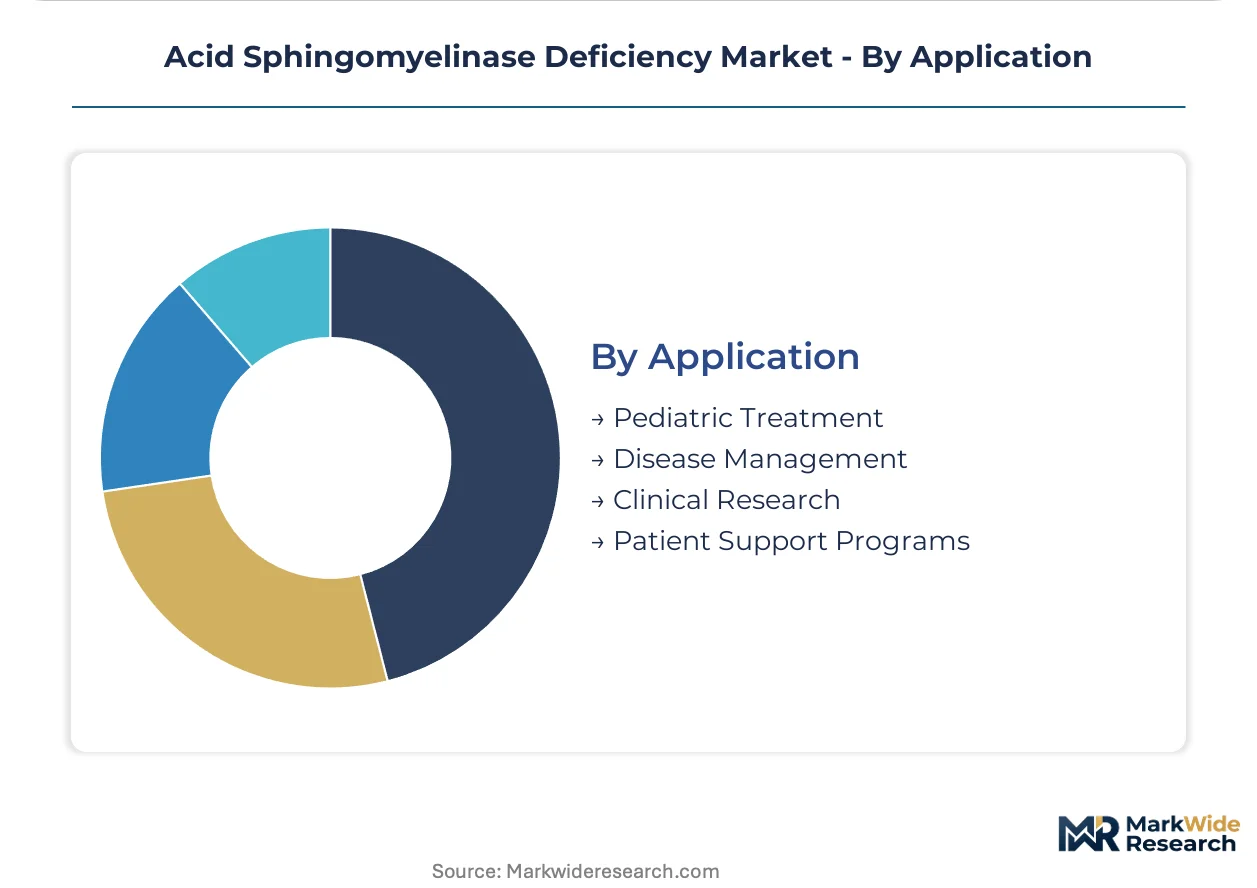
- Pediatric Treatment:Early intervention prevents irreversible neurovisceral damage in Type A and Type B presentations. Parent-led foundations in California and New York directly fund SMPD1 assay validation for expanded screening panels.
- Disease Management:Chronic monitoring protocols track hepatosplenomegaly progression and pulmonary function decline in attenuated phenotypes.
- Clinical Research:Natural history registries and biomarker qualification studies support regulatory submissions for novel therapeutic platforms.
- Patient Support Programs:Manufacturer-sponsored services address infusion logistics, antibody testing, and travel reimbursement for specialized care access.
Disease management represents the largest patient volume. Pediatric treatment is climbing the fastest through screening expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement elasticity varies sharply across markets. German payers accept premium gene therapy pricing through outcome-based models. United States commercial insurers demand rigorous cost-effectiveness documentation. United Kingdom NICE assessments impose stricter value thresholds.
United States
FDA orphan drug exclusivity accelerates clinical trial enrollment at pediatric metabolic centers in Philadelphia and Cincinnati. Parent-led foundations in California and New York directly fund SMPD1 assay validation for expanded newborn screening panels. Boston's specialized cell processing facilities attract development-stage gene therapy capital.
Germany
G-BA assessment procedures establish precedent for annuity-based reimbursement structures for one-time curative interventions. EMA PRIME designation compresses regulatory review timelines for acid sphingomyelinase deficiency therapeutics. Specialized lysosomal storage disease clinics in Munich and Hamburg anchor European patient identification and access.
United Kingdom
NICE technology appraisals impose stringent cost-per-QALY thresholds that constrain gene therapy adoption in England. Early access schemes through the Medicines and Healthcare products Regulatory Agency enable pre-approval treatment for pediatric Type A cases. London's academic medical centers concentrate natural history registry participation.
Japan
PMDA sakigake designation accelerates review timelines for innovative lysosomal storage disorder therapies. METI funding supports domestic viral vector manufacturing capacity expansion in the Kanto region. Tokyo's pediatric neurology networks remain underpenetrated relative to estimated disease prevalence.
France
ANSM early access programs enable treatment initiation before formal reimbursement listing for ultra-rare indications. National newborn screening expansion campaigns target SMPD1 inclusion in the national panel by 2027. Parisian academic hospitals coordinate multicenter natural history studies for regulatory submissions.
Acid Sphingomyelinase Deficiency Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the acid sphingomyelinase deficiency landscape. Recombinant enzyme manufacturers leverage established biomanufacturing infrastructure against gene therapy developers building novel viral vector supply chains. Three archetypes dominate: legacy rare disease pharmaceutical houses with commercial infrastructure, gene therapy platform specialists with manufacturing partnerships, and substrate reduction therapy developers with small-molecule expertise. Competitive moves center on manufacturing scale-up investments and reimbursement negotiation capabilities for novel payment models.
Among integrated pharmaceutical houses, Sanofi and Takeda occupy positions anchored by recombinant enzyme manufacturing infrastructure and inherited rare disease commercial operations respectively. Orchard Therapeutics exemplifies the gene therapy specialist archetype, sitting within the premium tier that demands distinct outcome-based reimbursement capabilities. These three companies represent the strategic spectrum from chronic maintenance paradigms toward one-time curative interventions.
| Leading Market Players |
|---|
| Sanofi |
| Takeda |
| Orchard Therapeutics |
| Orphazyme |
| Avrobio |
| Catalyst Pharmaceuticals |
| Lexicon Pharmaceuticals |
| Amicus Therapeutics |
| BridgeBio Pharma |
| Others |
Supply Flow & Price Mechanics
FDA orphan drug exclusivity provisions gate both supply qualification and price differentiation simultaneously, requiring manufacturers to secure seven-year market exclusivity before premium pricing tiers activate for acid sphingomyelinase deficiency therapeutics.
Pricing Analysis
Outcome-based annuity contracts for gene therapy drive lifetime value capture beyond initial treatment administration. Pricing stratifies across premium curative interventions, standard chronic enzyme replacement, and economy-tier substrate reduction alternatives. Cost compression in the chronic maintenance segment intensifies as gene therapy candidates advance through clinical development. Pediatric treatment centers exhibit lowest price sensitivity due to limited therapeutic alternatives and urgency of intervention timelines.
Supply Chain Analysis
Transatlantic container availability constraints elevate inbound logistics costs for plasmid DNA and viral vector raw materials sourced from European contract manufacturing organizations. Manufacturing concentration centers on the United States, Germany, and Switzerland for recombinant enzyme production and viral vector processing. Critical dependencies include suspension cell lines, specialized chromatography resins, and perfluorinated compound alternatives for purification buffers. Single-source vulnerability in plasmid DNA supply threatens batch yield consistency. Distribution runs through hospital-based specialty pharmacies and dedicated lysosomal storage disease treatment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acid sphingomyelinase deficiency market operates within a cyclical recovery phase driven by newborn screening expansion campaigns compressing diagnosis-to-treatment intervals across state health departments.
For Market Incumbents: Secure viral vector manufacturing capacity through captive production facilities or exclusive contract manufacturing organization partnerships before plasmid DNA scarcity worsens. Consolidate reimbursement negotiation capabilities by acquiring specialized gene therapy market access consultancies. Gene therapy platform substitution threatens chronic enzyme replacement revenue streams. For New Entrants and Emerging Players: Differentiate on subcutaneous nanoparticle delivery platforms that circumvent immunogenicity barriers constraining existing intravenous modalities. Target underpenetrated pediatric neurology networks in Spain and Italy where dedicated lysosomal storage disease coordinators remain absent. Pursue hospital system partnership models that bundle diagnostic testing with therapeutic access. For Investors and Strategic Acquirers: EMA PRIME designation reshapes the acquisition landscape by compressing regulatory timelines and validating platform durability for gene therapy developers. Five-to-ten year viability hinges on manufacturing scale-up feasibility rather than clinical efficacy alone. Acquisition target archetype: gene therapy specialists with validated lentiviral vector platforms and established G-BA reimbursement precedents. Signal to monitor: outcome-based payment framework adoption rates in German statutory health insurance.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Viral vector batch yield expansion at Maryland and North Carolina contract manufacturing organizations reduces supply bottlenecks. |
| Regulatory Approval Pathway | EMA PRIME designation compresses assessment timelines for acid sphingomyelinase deficiency therapeutics entering European markets. |
| Reimbursement Strategy | G-BA annuity structures establish precedent for outcome-based gene therapy payment models across German statutory health insurance. |
| Clinical Trial Advancement | Pediatric metabolic centers in Philadelphia and Cincinnati prioritize protocol participation for treatment-naive patient recruitment. |
| Pipeline Diversification | Substrate reduction therapy candidates address biologic contraindication segments and extend chronic maintenance revenue capture. |
Methodological Framework
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation across FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume estimates and top-down revenue triangulation converged on segmentation outputs. Primary interviews captured manufacturing capacity constraints, reimbursement negotiation dynamics, and site-of-care economics.
Variance decomposition across therapeutic modality, patient population, administration route, and regional regulatory cluster enabled granular trajectory assessment over the projection horizon. CAGRs were derived from segmented volume and value build-ups calibrated to disclosed clinical trial enrollment rates and approved therapy pricing benchmarks. Gene therapy manufacturing scale-up feasibility and newborn screening expansion timelines served as critical forecast inputs.
Material uncertainties — regulatory approval delays, viral vector manufacturing batch failures, and reimbursement framework rejections — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding clinical efficacy endpoints and payer acceptance thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Erdheim-Chester Disease Market