
 Drug Delivery Devices Market | 2026-2036
Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Delivery Devices Market Intelligence
The shift towards outcome-based reimbursement and leasing models for high-value equipment is tilting the competitive field towards service-oriented providers. This trend favors companies that can bundle devices with monitoring services. Becton, Dickinson and Company leverages its vast manufacturing scale in injection systems to command the high-volume segment. Medtronic specializes in complex, integrated systems for chronic disease management, such as insulin pumps. Insulet Corporation competes effectively through its focus on innovative, patient-centric designs like wearable patch pumps.
Drug delivery devices are engineered systems for the controlled and targeted administration of therapeutic agents into the body. These devices are designed to optimize a drug's pharmacokinetic profile by controlling its release rate, duration, and location. Their primary purpose is to enhance therapeutic efficacy, minimize side effects, and improve patient compliance. While injectors and inhalers constitute major product segments by volume, advanced infusion pumps and smart transdermal patches represent areas of high-margin growth. Diabetes management and oncology are the dominant therapy areas attracting significant R&D investment.
Regulatory frameworks from the US FDA and the European Union's MDR dictate stringent requirements for device design, material safety, and manufacturing processes. In parallel, China's NMPA is aligning its standards with international benchmarks, creating a complex global compliance landscape. These regulations impact development costs and market access timelines for all device classes. Stakeholders must now focus on integrating digital health capabilities while navigating the evolving standards for combination products and software as a medical device.
Market Dynamics
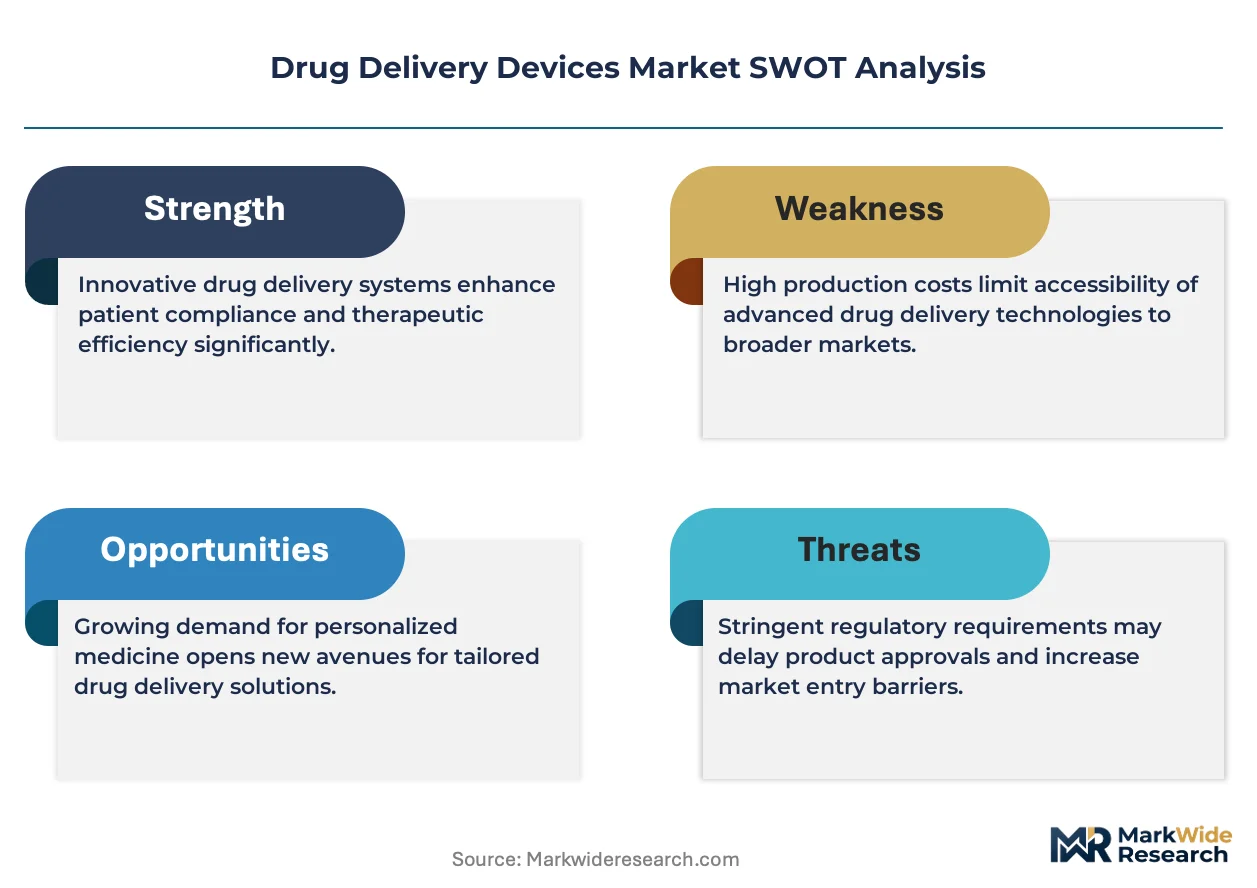
The central dynamic shaping the drug delivery device market is the design tension between escalating regulatory stringency and the powerful demand shift toward patient-centric, self-administered therapies. This forces manufacturers to innovate for usability while simultaneously increasing investment in rigorous validation.
Growth Catalysts
- Biologic Drug Pipeline:The expanding pipeline of high-viscosity biologic drugs for chronic conditions necessitates the development of advanced autoinjectors and large-volume wearable devices capable of effective subcutaneous administration.
- Home Healthcare Expansion:A strong patient preference for treatment outside of clinical settings, particularly in the home healthcare provider segment, accelerates adoption of user-friendly devices for self-management of diseases like diabetes.
- Chinese Healthcare Modernization:Government initiatives in China to upgrade healthcare infrastructure and the rising disposable income of its middle class create concentrated demand for advanced drug delivery systems, from insulin pumps to inhalers.
Market Restraints
- Regulatory Compliance Costs:The European Union's MDR and similar stringent frameworks from the US FDA increase development costs and extend market access timelines, requiring substantial investment in clinical data and post-market surveillance.
- Material and Sterilization Limits:Ensuring the biocompatibility and stability of device materials when in contact with complex biologic drugs presents significant technical hurdles, as does finding compatible sterilization methods that do not degrade device components.
- Generic Competition Pressure:The availability of low-cost generic drugs administered via basic syringes or vials creates significant price pressure, limiting the addressable market for premium, high-margin delivery systems in some therapy areas.
Strategic Opportunities
- Digital Health Integration:Connecting delivery devices with software applications and sensors creates smart systems that improve patient adherence, provide real-time data to clinicians, and support outcome-based reimbursement models.
- Cell and Gene Therapies:The emergence of cell and gene therapies presents a white-space opportunity for developing novel, highly specialized delivery systems capable of targeted, precise administration to specific tissues or organs.
- Emerging Market Penetration:There is significant opportunity to introduce advanced devices, such as continuous glucose monitors and patch pumps, into middle-income countries in Latin America and Southeast Asia where chronic disease prevalence is rising.
Industry Challenges
- Global Regulatory Harmonization:Manufacturers face substantial operational challenges in navigating the differing requirements for combination products and software as a medical device between the US FDA, the EU's MDR, and China's NMPA.
- System Interoperability:Achieving seamless data exchange between smart drug delivery devices, electronic health record (EHR) systems, and telehealth platforms requires overcoming significant technical and data security hurdles.
- Human Factors Engineering Talent:A scarcity of engineers with specialized expertise in human factors and usability testing for medical devices constrains the development of products that are both safe and intuitive for patient self-administration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Delivery Devices Market |
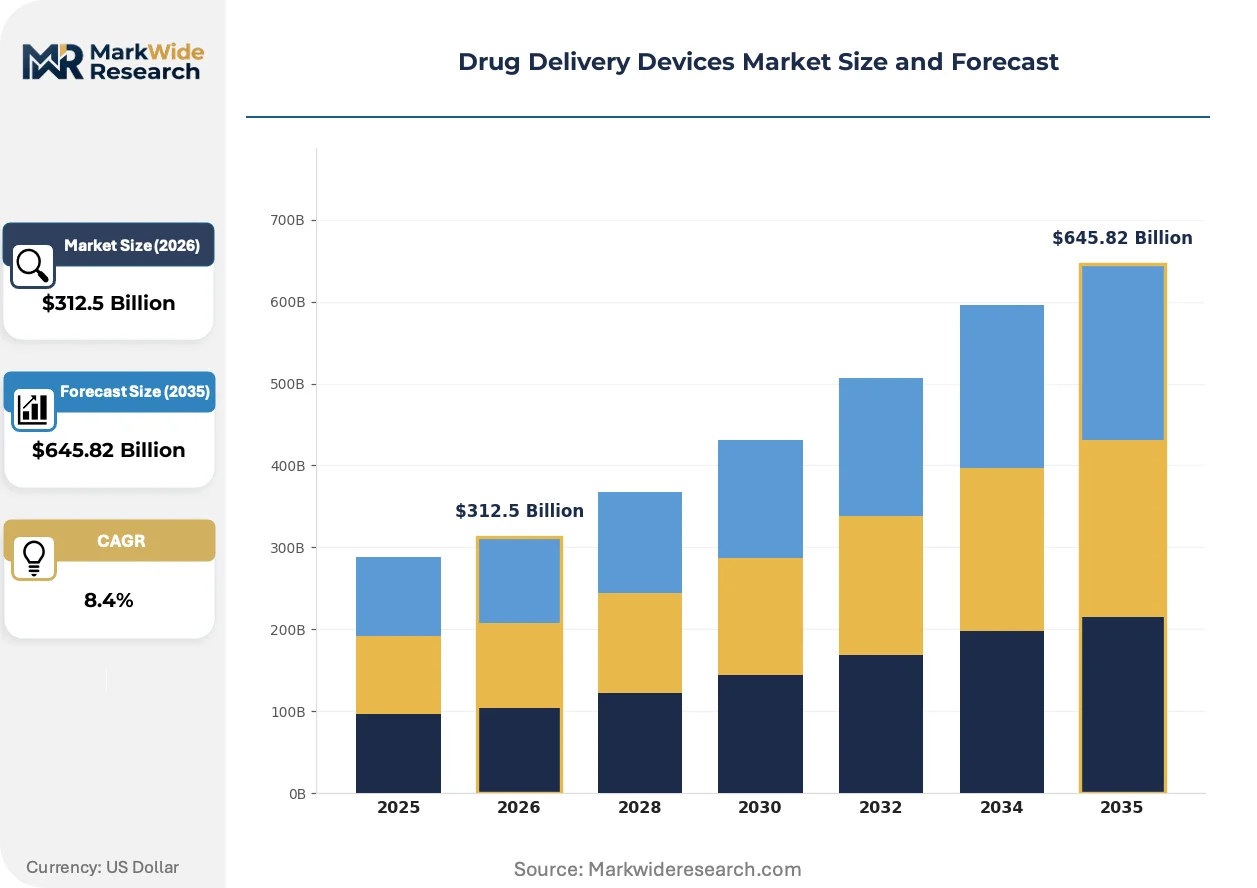
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $645.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectors, Nebulizers, Inhalers, Transdermal Patches, Infusion Pumps Therapy Area: Oncology, Diabetes Management, Respiratory Disorders, Cardiovascular Diseases, Pain Management End User: Hospitals, Specialty Clinics, Home Healthcare Providers, Pharmacies, Research Institutions Delivery Technology: Needle-Free Injection, Metered-Dose, Dry Powder, Electronic Delivery, Micro-Needle Systems |
| Companies Covered | Johnson & Johnson Services, Inc, Pfizer, Inc., F. Hoffmann-La Roche Ltd, Novartis AG, Becton, Dickinson and Company, Medtronic, West Pharmaceutical Services, Inc., Gerresheimer AG, Insulet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Delivery Devices Market Strategic Shifts & Innovations
Device intelligence and connectivity are fundamentally changing the market's value proposition. The focus is shifting from the mechanical act of drug administration to the creation of integrated digital ecosystems that monitor therapy, track adherence, and generate actionable health data.
Wearable patch pumps are automated systems providing continuous subcutaneous drug delivery over extended periods. Patients with chronic conditions like diabetes are rapidly adopting these devices to replace multiple daily injections. This technology is rendering obsolete the burdensome regimen of frequent, manual self-injections with traditional syringes for a growing number of complex therapies, improving quality of life.
The European Union's Medical Device Regulation (MDR) has introduced a more rigorous regulatory environment for all devices. Its industrial consequence is a significant increase in the clinical evidence and post-market surveillance required to maintain or gain market access. Manufacturers of older, legacy devices are most affected, often being forced to undertake costly new studies or withdraw products from the EU market.
A definitive shift toward value-based healthcare models is altering purchasing criteria for drug delivery systems. This change disrupts traditional sales cycles based on unit volume, favoring integrated device and software platforms that can prove a direct impact on patient outcomes. This trend is most pronounced in chronic disease management within large US health networks, where payers directly incentivize improved therapeutic efficacy and adherence.
Drug Delivery Devices Market Segmentation
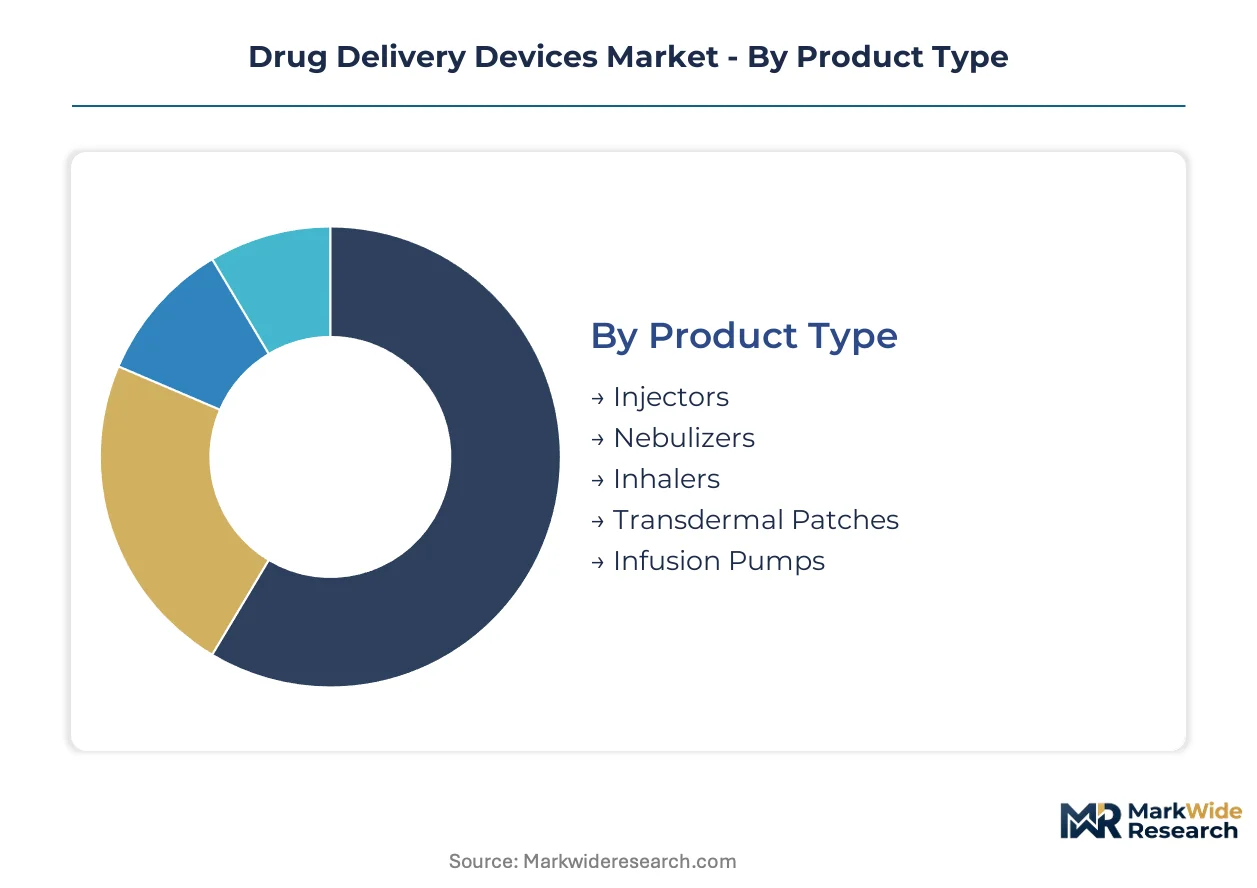
The segmentation of the drug delivery devices market provides a granular view of product utility, therapeutic applications, and end-user adoption patterns. Understanding these distinct categories helps stakeholders identify specific growth vectors and address targeted patient needs across diverse healthcare landscapes.
Product Type:
The drug delivery device market segments by product type, reflecting a broad use-case spectrum from rapid self-administration to continuous therapeutic management.
- Injectors:These devices facilitate parenteral drug administration, often for biologics or vaccines, encompassing pre-filled syringes, autoinjectors, and pen injectors. Demand for advanced autoinjectors concentrates in home healthcare settings, driven by the expanding pipeline of high-viscosity biologic drugs for chronic conditions.
- Infusion Pumps:Automated systems deliver fluids, nutrients, or medications into a patient's body in controlled amounts, including insulin pumps and pain management systems. High-margin growth for these devices is notable in diabetes management, where continuous subcutaneous insulin delivery improves patient outcomes.
- Nebulizers:These devices convert liquid medication into a fine mist for inhalation, primarily used for respiratory disorders.
- Inhalers:Handheld devices deliver medication to the lungs, encompassing metered-dose inhalers and dry powder inhalers for conditions like asthma.
- Transdermal Patches:These adhesive patches deliver medication through the skin at a controlled rate over an extended period.
The dominant share belongs to Injectors, while Infusion Pumps are closing the gap fastest.
Therapy Area:
Segmentation by therapy area highlights the diverse application focus of drug delivery devices, aligning with specific patient populations and disease progression.
- Oncology:This segment includes devices for administering chemotherapy, supportive care medications, and targeted therapies. Significant R&D investment targets this area, focusing on precision delivery systems for complex cancer treatments.
- Diabetes Management:Devices such as insulin pens, autoinjectors, and continuous glucose monitors fall under this category. Patient preference for self-management outside clinical settings accelerates adoption of user-friendly diabetes devices.
- Respiratory Disorders:Devices like nebulizers and inhalers are crucial for managing conditions such as asthma and COPD.
- Cardiovascular Diseases:This area utilizes drug delivery devices for anticoagulants, antiarrhythmics, and other cardiac medications.
- Pain Management:Infusion pumps and transdermal patches are commonly employed for controlled delivery of analgesics.
Diabetes Management commands significant market presence, with Oncology demonstrating the steepest expansion trajectory.
End User:
The end-user segmentation delineates distinct customer types, from professional clinical settings to individual patient homes, each with unique device requirements.
- Hospitals:These institutions represent a major end-user segment for a wide range of drug delivery devices, including infusion pumps and specialized injectors. Regulatory requirements from the US FDA and European Union's MDR dictate device procurement in these settings.
- Home Healthcare Providers:This segment includes patients and caregivers who administer therapies outside traditional clinical environments, driving demand for user-friendly, self-administered devices. The expansion of home healthcare accelerates adoption of advanced autoinjectors and wearable patch pumps.
- Specialty Clinics:These facilities focus on specific disease areas, utilizing targeted drug delivery systems for their patient populations.
- Pharmacies:Retail and hospital pharmacies distribute drug delivery devices, particularly those for self-administration.
- Research Institutions:Academic and private research organizations use specialized drug delivery systems for clinical trials and drug development.
Hospitals remain a foundational end-user segment, but Home Healthcare Providers are gaining share fastest.
Delivery Technology:
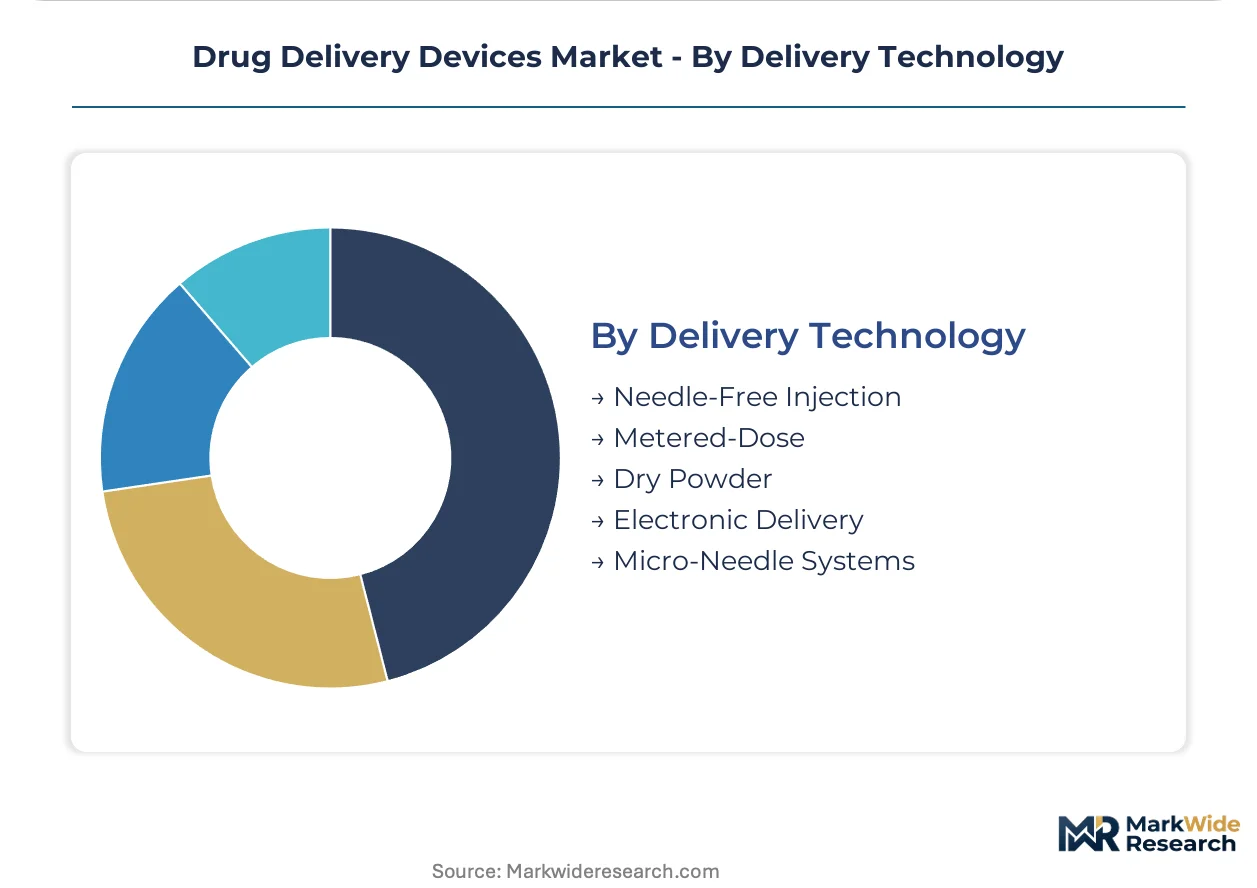
Delivery technology segmentation illustrates the varying maturity levels and innovation trajectories within the market, from established methods to advanced systems.
- Electronic Delivery:This category encompasses smart devices integrated with software applications and sensors, providing real-time data and enhancing patient adherence. Digital health integration creates smart systems that support outcome-based reimbursement models.
- Micro-Needle Systems:These innovative systems deliver drugs through microscopic needles, offering a less invasive alternative to traditional injections. The emergence of cell and gene therapies presents a white-space opportunity for these specialized systems.
- Needle-Free Injection:Technologies that deliver medication without a hypodermic needle reduce needle-stick injuries and improve patient comfort.
- Metered-Dose:These technologies deliver a precise, consistent dose of medication, commonly found in inhalers.
- Dry Powder:Systems that deliver medication in a dry powder form for inhalation, often used for respiratory conditions.
Metered-Dose technologies hold a stable position, while Electronic Delivery systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global drug delivery devices market exhibits a complex interplay between domestic manufacturing capabilities and international trade flows. While advanced economies often drive innovation and export high-value specialized devices, emerging markets are increasingly becoming significant importers due to expanding healthcare needs. This dynamic shapes investment priorities and regulatory alignment across diverse geographies.
United States
Demand for advanced drug delivery systems in the United States is strong, driven by the expanding biologics pipeline and home healthcare preference. The US FDA imposes rigorous standards for device design and clinical validation. Major medical device clusters in regions like Boston and California foster innovation in connected device technologies.
China
China's market demand concentrates due to its expanding middle class and government initiatives for healthcare infrastructure modernization. The NMPA aligns its regulatory standards with international benchmarks, influencing local manufacturing. Cities like Shanghai and Shenzhen are becoming hubs for domestic production and advanced medical device R&D.
Germany
German demand for drug delivery devices stems from its aging population and focus on high-precision medical technologies. The European Union's MDR significantly impacts device design and validation protocols for German manufacturers. Bavaria and North Rhine-Westphalia host prominent medical technology clusters, specializing in advanced infusion systems.
India
India experiences rising demand for user-friendly drug delivery devices, particularly for chronic disease management like diabetes. The CDSCO regulates medical device imports and local manufacturing, emphasizing quality and accessibility. Bangalore and Hyderabad are emerging as key centers for medical device development.
Japan
Japan's market for drug delivery devices is characterized by emphasis on patient safety and technological sophistication, serving an elderly demographic. PMDA regulations ensure stringent quality control and clinical evidence requirements for all medical devices. The Tokyo metropolitan area remains a central hub for pharmaceutical and medical device innovation.
Drug Delivery Devices Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established pharmaceutical giants leveraging their drug portfolios alongside specialized medical device manufacturers. The market includes large-scale diversified conglomerates and nimble innovation-focused firms. Strategic archetypes range from high-volume component suppliers to integrated solution providers bundling devices with digital health services. Portfolio diversification and strategic partnerships are dominant competitive moves, allowing companies to address a broader spectrum of therapeutic areas.
Specialists in integrated systems for chronic disease management, such as Medtronic, exemplify the shift towards comprehensive patient care. Alongside, Becton, Dickinson and Company represents the established high-volume segment, leveraging its vast manufacturing scale in injection systems. Insulet Corporation, with its focus on innovative, patient-centric designs like wearable patch pumps, anchors the segment prioritizing user experience and adherence. These firms navigate the complex regulatory environment by focusing on distinct value propositions.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc |
| Pfizer, Inc. |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Becton, Dickinson and Company |
| Medtronic |
| West Pharmaceutical Services, Inc. |
| Gerresheimer AG |
| Insulet Corporation |
| Others |
Cost & Logistics Intelligence
Sterile manufacturing capabilities for advanced components in Switzerland and Germany concentrate upstream value, directly influencing premium pricing for integrated delivery systems downstream. This concentration shapes market access and profitability across various device classes.
Pricing Analysis
Industrial OEM buyers anchor the value-based pricing model for complex drug delivery systems. Pricing stratifies across premium, standard, and economy tiers, driven by device complexity and regulatory certification (US FDA, EU MDR). Cost compression in high-volume segments stems from generic competition for basic devices. Home healthcare providers demonstrate higher price sensitivity for routine supplies, while specialty clinics prioritize advanced, outcome-driven solutions.
Supply Chain Analysis
Single-source vulnerability for specialized micro-electronics from East Asia dominates supply chain risk for smart drug delivery devices. Geographic concentration for precision components rests in Germany and Switzerland, while basic device manufacturing often centers in China. Raw material dependencies include medical-grade polymers and specialized glass for pre-filled syringes. Distribution runs through a hybrid model, combining direct sales to hospital networks with third-party logistics for home healthcare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drug delivery devices market is in an early-cycle expansion phase, driven by the increasing penetration of self-administered biologic therapies for chronic conditions.
For Market Incumbents: Build a regulatory compliance moat around advanced device platforms, anticipating stricter global standards for combination products. Invest in integrated digital health ecosystems to capture recurring revenue streams and counter generic competition. Prioritize R&D in specialized delivery for cell and gene therapies, leveraging existing manufacturing scale.
For New Entrants and Emerging Players: Specialized delivery systems for emerging cell and gene therapies represent an unaddressed white space for novel entrants. Target underpenetrated middle-income countries in Southeast Asia for user-friendly diabetes management devices. Focus on patient-centric design and intuitive software interfaces as a key go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap device manufacturers specializing in connected health solutions, offering a clear long-term growth trajectory over the next decade. Seek companies with strong intellectual property in smart sensors and data analytics for therapeutic adherence. Watch for increased M&A activity focused on digital health integration capabilities as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop integrated digital ecosystems | Connects devices with software, enhancing patient adherence and providing real-time data to clinicians. |
| Invest in human factors engineering | Ensures devices are intuitive and safe for self-administration, crucial for home healthcare adoption. |
| Form strategic partnerships for biologic drug delivery | Accelerates development of advanced autoinjectors and wearable devices for high-viscosity drugs. |
| Expand manufacturing capabilities for advanced materials | Secures supply of biocompatible polymers and specialized glass for next-generation devices. |
| Navigate NMPA/MDR compliance | Ensures market access in China and the European Union, critical for global product launches. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and rigorous secondary validation of published data. Primary research involved discussions with device engineers, regulatory affairs specialists, hospital procurement managers, and home healthcare providers. Secondary sources included US FDA filings, EU MDR guidance documents, NMPA publications, and academic literature on device materials. This approach facilitated bottom-up and top-down triangulation.
The forecast framework considered inputs such as biologic drug pipeline expansion, evolving regulatory landscapes, and patient preference shifts across the analysis window. Segmentation dimensions modeled included product type, therapy area, end-user, and delivery technology. Compound annual growth rates were derived from historical trends and projected market drivers, incorporating R&D spending on novel drug formulations and patient demographics for chronic diseases.
Macroeconomic conditions sit as an overlay; deviation in global healthcare spending or raw material costs would shift the trajectory of market expansion. Forecasts reflect assumptions documented through this process, acknowledging geopolitical disruptions and unforeseen technological breakthroughs as key risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Global Electronic Stethoscope Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
Cryoablation Devices Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Global Venous Stents Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Solar Surgical Light Market
Medical Devices
India Biopsy Devices Market
Medical Devices
North America Arthroscopy Devices Market