
 Intranasal Drug and Vaccine Delivery Market | 2026-2036
Intranasal Drug and Vaccine Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Intranasal Drug and Vaccine Delivery Market Intelligence
Platform licensing revenue is fragmenting across formulation specialists and device manufacturers as intranasal delivery gains therapeutic breadth. GSK plc leverages decades of respiratory vaccine expertise to anchor its position in spray-based immunization. Teva Pharmaceutical Industries Ltd sustains competitive presence through its established central nervous system franchise and migraine therapy portfolio. AptarGroup, Inc. dominates nasal pump and valve technology, supplying critical device components to multiple pharmaceutical partners.
Intranasal drug and vaccine delivery encompasses administration of pharmaceutical agents via the nasal mucosa, typically using devices that generate droplets between 10-100 micrometers to optimize deposition in the olfactory and respiratory epithelium. This route exploits the dense vascularization and immune cell populations of the nasal cavity to achieve rapid systemic absorption or local mucosal immunity, with particular utility for compounds requiring blood-brain barrier circumvention or needle-free mass immunization campaigns. Spray delivery commands the largest volume share among methods due to established clinical familiarity and device availability, while powder formulations represent the fastest-expanding segment as manufacturers pursue thermostable alternatives that eliminate cold-chain dependency. Vaccine formulations attract the majority of development investment, though analgesic applications sustain meaningful revenue streams through acute pain management indications.
The FDA maintains stringent requirements for nasal spray bioequivalence and device reproducibility, while the EMA's MDR framework governs combination product classifications in Europe. The WHO prequalification pathway shapes access for intranasal vaccines in low-income country procurement, creating tiered regulatory demands across development and commercialization stages. Stakeholders must monitor how mucosal immunity correlates of protection evolve in regulatory guidance, as these definitions will determine which candidates advance through accelerated review channels.
Market Dynamics
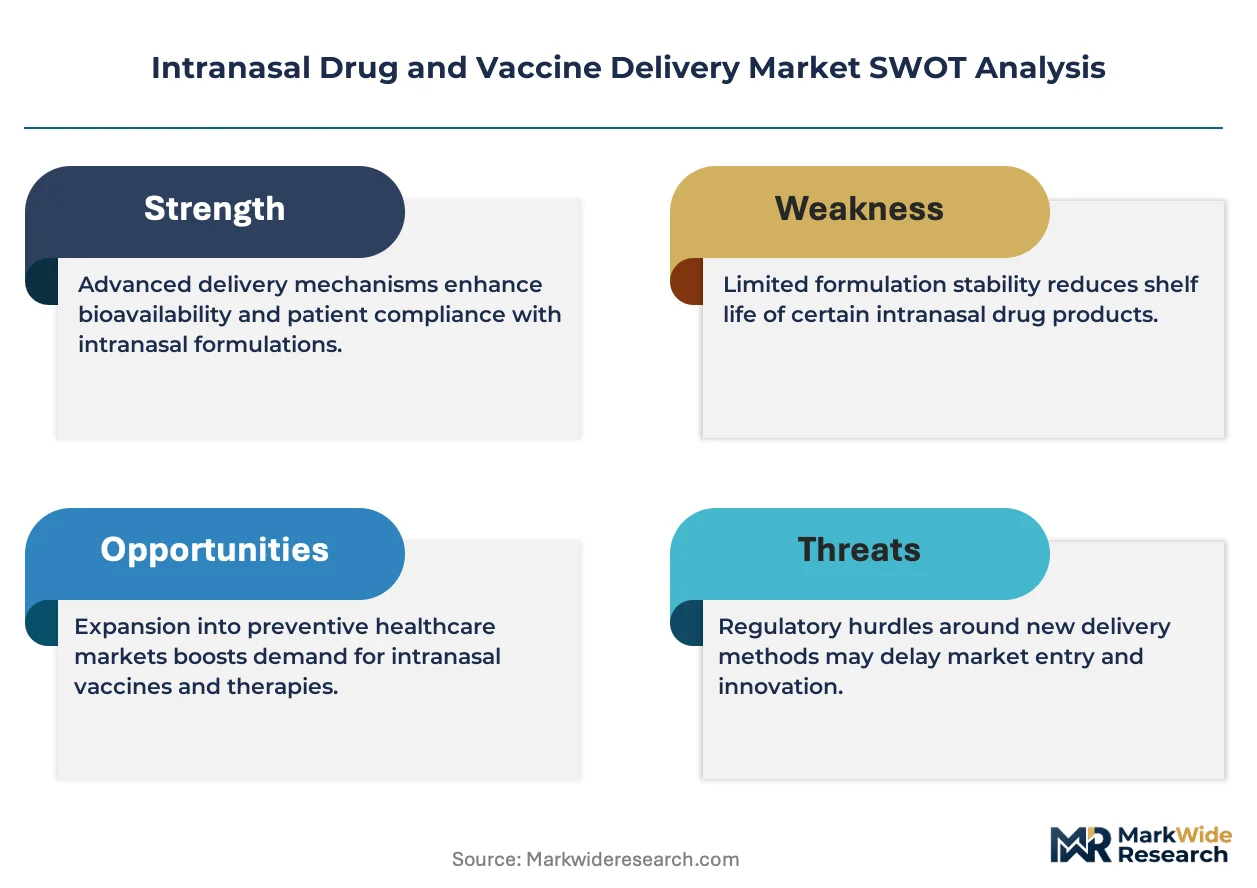
Platform licensing revenue is fragmenting across formulation specialists and device manufacturers as intranasal delivery gains therapeutic breadth beyond respiratory applications.
Growth Catalysts
- FDA Accelerated Pathway:The FDA's streamlined review for needle-free mucosal immunization platforms compresses development timelines for spray-based vaccines targeting respiratory pathogens.
- Powder Thermostability:Dry powder formulations eliminate cold-chain dependency, expanding distribution reach to tropical and resource-limited settings where refrigeration infrastructure is scarce.
- Blood-Brain Barrier Circumvention:Central nervous system drug developers exploit nasal olfactory epithelium vascularization to deliver neurotherapeutics without invasive administration.
Market Restraints
- Device Component Concentration:Nasal pump and valve technology supply concentrates among specialized manufacturers, creating single-source vulnerability for pharmaceutical partners.
- MDR Classification Friction:The EMA's Medical Device Regulation creates combination product ambiguity, extending certification timelines for spray-device integrated systems.
- Oral Tablet Substitution:Conventional oral analgesics retain physician familiarity and pharmacy formulary preference for acute pain management outside migraine indications.
Strategic Opportunities
- India Manufacturing Expansion:CDSCO regulatory alignment with WHO prequalification standards positions Indian contract manufacturers to supply intranasal vaccines for Gavi procurement channels.
- Mental Health Applications:Ketamine and esketamine intranasal delivery for treatment-resistant depression represents an emerging therapeutic category with limited device-optimized competition.
- Digital Health Integration:Connected spray devices with dose-tracking sensors enable adherence monitoring for chronic CNS conditions, creating subscription revenue streams.
Industry Challenges
- Formulation Scientist Scarcity:Nasal mucoadhesive polymer expertise remains concentrated among legacy respiratory vaccine developers, constraining talent acquisition for new entrants.
- Clinical Endpoint Validation:Correlates of protection for mucosal immunity lack standardized regulatory acceptance criteria, complicating Phase III trial design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intranasal Drug and Vaccine Delivery Market |
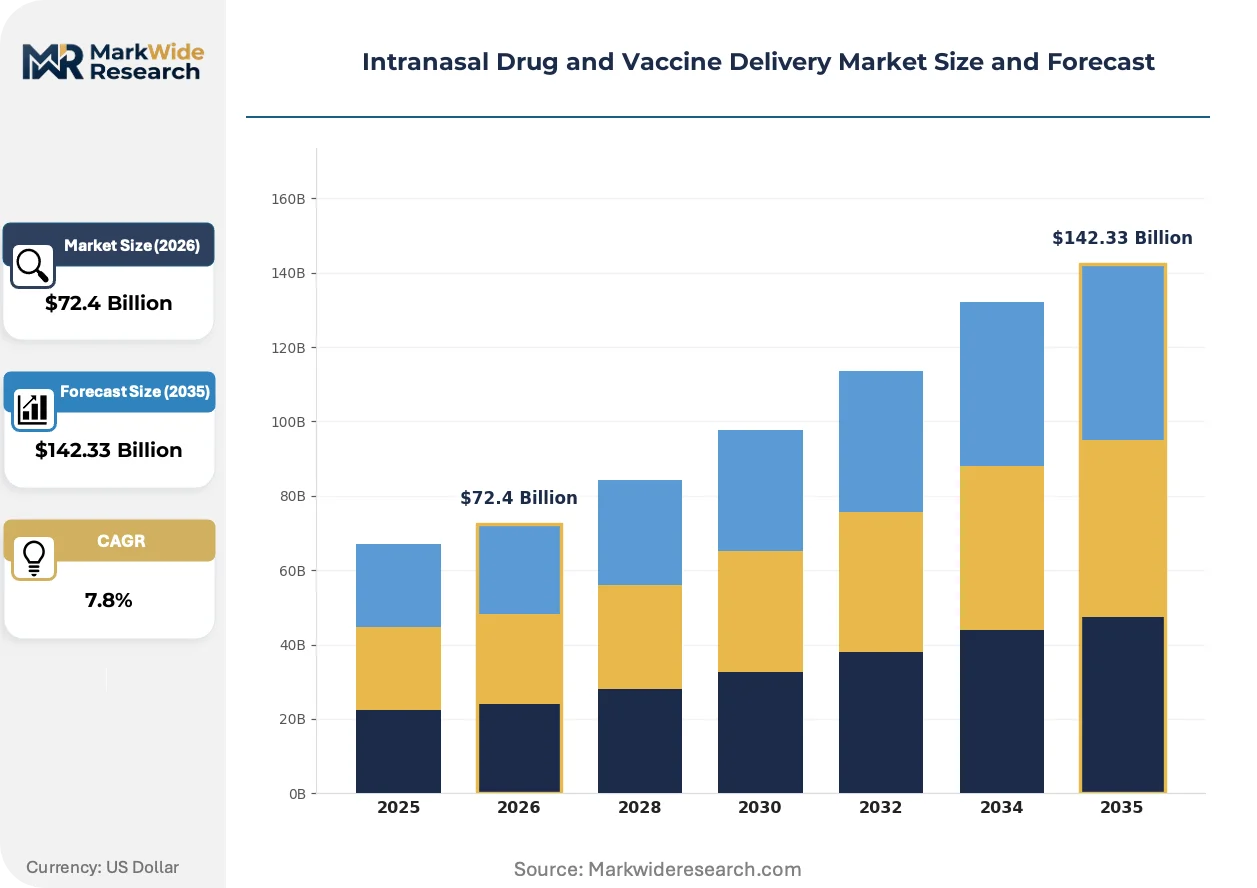
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $142.33 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Method: Spray, Gel, Powder, Droplet End User: Hospitals, Clinics, Homecare, Pharmacies Formulation Type: Vaccine, Analgesics, Antiviral, Hormones Administration Strategy: Preventive, Therapeutic, Prophylactic, Emergency |
| Companies Covered | GSK plc, Teva Pharmaceutical Industries Ltd, AptarGroup, Inc., UCB S.A., Teleflex Incorporated, 3M, Bespak Limited, Optinose, Nemera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intranasal Drug and Vaccine Delivery Market Strategic Shifts & Innovations
Device-integrated digital capabilities and thermostable formulation platforms are redefining competitive differentiation beyond traditional spray mechanics.
Spray pump technology is migrating from standard mechanical actuators to precision-metered electronic devices. Hospital systems in the United States now specify dose-verification features for patient-administered CNS therapies. This shift is compressing margins for conventional mechanical pump suppliers while rewarding electronics-integrated device partnerships.
The EMA's MDR framework is tightening combination product classification requirements for nasal spray-drug pairings. Manufacturers must now submit device and formulation as unified regulatory packages rather than sequential approvals. European pharmaceutical partners are responding by acquiring captive device capabilities or securing exclusive supply agreements with certified component specialists.
Hospital procurement for migraine therapies now favors single-use disposable units over multi-dose reservoirs despite higher per-dose cost. This preference shift reflects infection control protocols and dosing accuracy concerns in acute care settings. The pattern is most visible in United States health system formularies, where pharmacy and therapeutics committees prioritize patient safety metrics over unit economics.
Intranasal Drug and Vaccine Delivery Market Segmentation
Segmentation in intranasal delivery reveals how device servicing requirements, formulation stability needs, and patient administration settings create divergent margin structures across the value chain. Each dimension carries distinct regulatory pathways and procurement dynamics that shape competitive positioning.
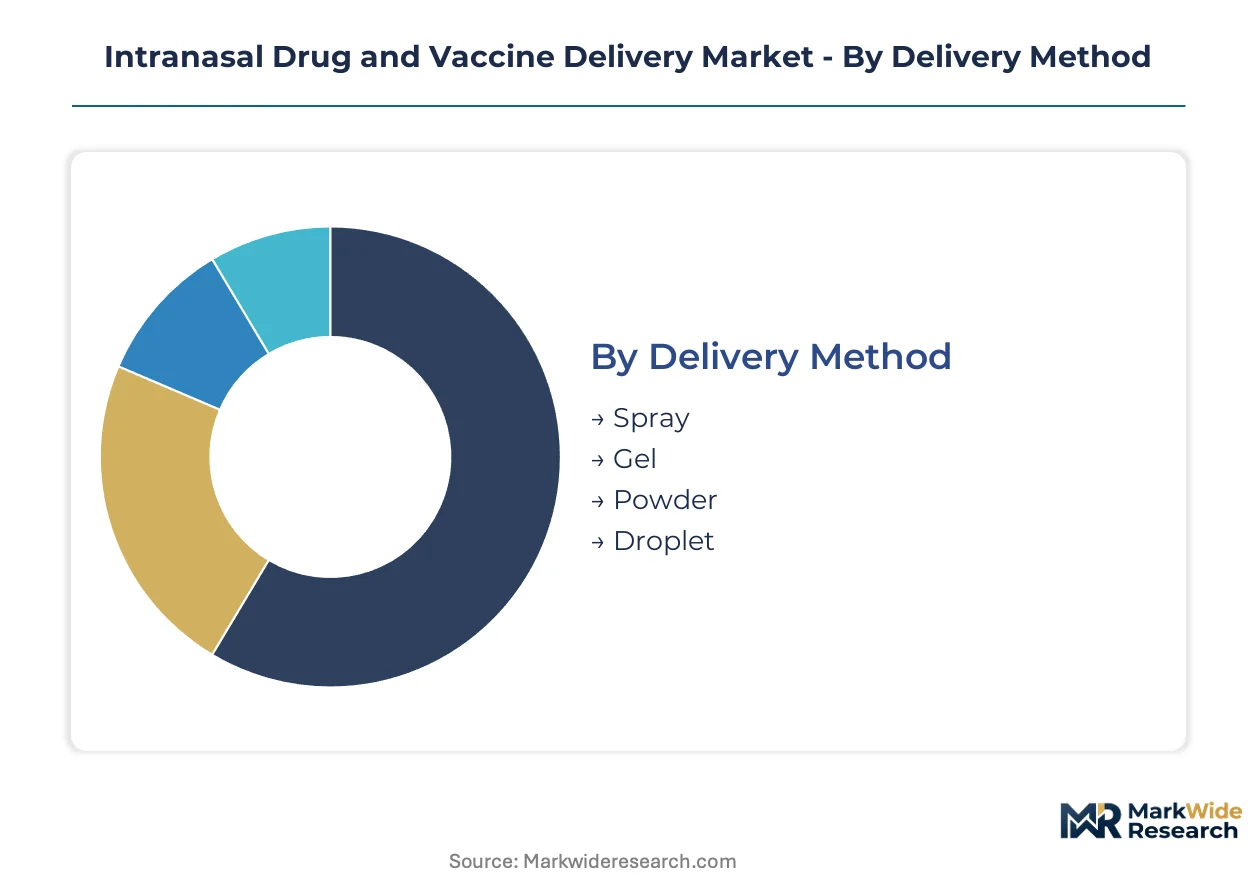
Delivery Method:
After-sales service intensity varies sharply across delivery mechanisms, with electronic metering systems requiring calibration support that mechanical pumps simply do not demand.
- Spray:Mechanical and electronic pump systems generate droplets between 10-100 micrometers for optimized deposition in the olfactory and respiratory epithelium. Hospital systems in the United States now specify dose-verification features for patient-administered therapies, compressing margins for conventional mechanical suppliers while rewarding electronics-integrated partnerships.
- Powder:Dry particle formulations eliminate cold-chain dependency through thermostable engineering, enabling distribution to tropical and resource-limited settings where refrigeration infrastructure is scarce. CDSCO-aligned Indian contract manufacturers are positioning to supply these formulations for Gavi procurement channels.
- Gel:Viscous mucoadhesive preparations extend residence time on nasal mucosa for sustained drug release.
- Droplet:Precision liquid instillation systems target specific anatomical regions within the nasal cavity.
By volume, Spray leads. By growth pace, Powder is ahead.
End User:
Cost tier differentiation separates institutional procurement from retail channels, with hospital formulary committees prioritizing patient safety metrics over unit economics.
- Hospitals:Acute care settings drive adoption of single-use disposable units over multi-dose reservoirs despite higher per-dose cost, reflecting infection control protocols and dosing accuracy concerns. Pharmacy and therapeutics committees in United States health systems now mandate this specification.
- Homecare:Patient self-administration of CNS therapies requires connected spray devices with dose-tracking sensors for adherence monitoring, creating subscription revenue streams through digital health integration.
- Clinics:Outpatient facilities balance device cost against throughput efficiency for routine immunization campaigns.
- Pharmacies:Retail dispensing channels favor multi-dose reservoirs for migraine therapies where patient safety protocols are less stringent.
By patient volume, Hospitals dominate. By expansion trajectory, Homecare is climbing the fastest.
Formulation Type:
Application focus determines development investment allocation, with mucosal immunity targets commanding priority in pipeline portfolios.
- Vaccine:Respiratory pathogen prevention formulations attract the majority of development investment as manufacturers expand intranasal portfolios, with FDA accelerated pathway reviews compressing timelines for needle-free mucosal immunization platforms.
- Analgesics:Acute pain management applications sustain meaningful revenue streams through migraine therapy indications, though conventional oral tablets retain physician familiarity outside this specific use case.
- Antiviral:Direct-acting viral suppression compounds exploit rapid systemic absorption through nasal vascularization.
- Hormones:Endocrine replacement and modulation therapies leverage blood-brain barrier circumvention via olfactory epithelium delivery.
By development pipeline, Vaccine leads. By commercial maturity, Analgesics maintains the strongest position.
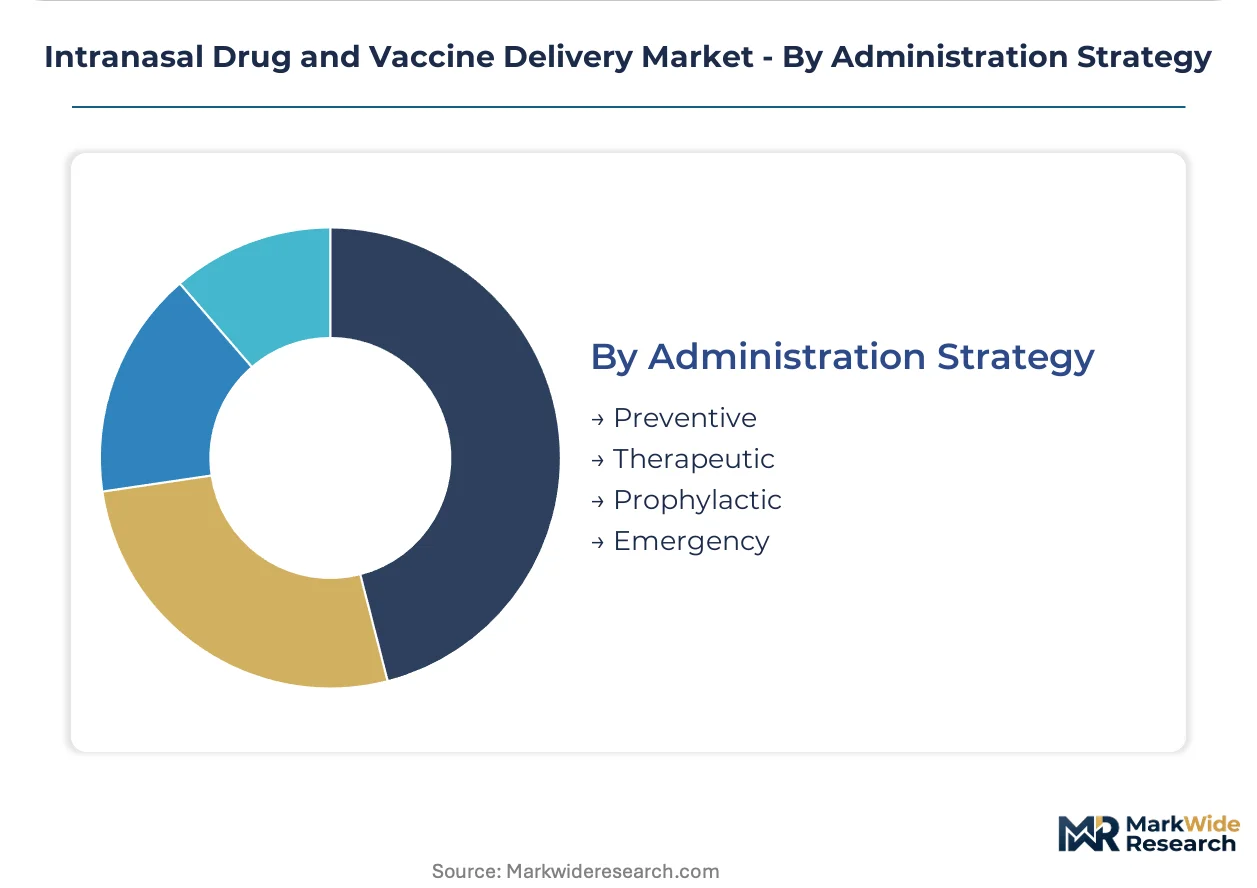
Administration Strategy:
Customer type segmentation separates mass immunization campaigns from individualized therapeutic protocols, with procurement channels diverging accordingly.
- Preventive:Population-scale immunization programs target respiratory pathogens through federal procurement channels, with WHO prequalification pathways shaping access for low-income country distribution.
- Therapeutic:Treatment-resistant depression applications using ketamine and esketamine intranasal delivery represent an emerging category with limited device-optimized competition.
- Prophylactic:Pre-exposure protection protocols for high-risk occupational and travel populations.
- Emergency:Rapid-response deployment for outbreak containment and crisis medical countermeasures.
By procurement scale, Preventive leads. By therapeutic innovation intensity, Therapeutic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems prioritize single-use disposable units for infection control, while Indian manufacturers target thermostable powder formulations for tropical distribution without cold-chain infrastructure.
United States
Federal procurement channels and hospital formulary committees drive spray-based delivery adoption for respiratory vaccines and migraine therapies. FDA accelerated pathway reviews compress development timelines for needle-free mucosal immunization platforms. The Boston-Cambridge biotech cluster anchors CNS drug development exploiting olfactory epithelium vascularization for blood-brain barrier circumvention.
Germany
Precision device engineering capabilities support electronic metering system production for dose-verification features. EMA MDR framework governs combination product classifications, extending certification timelines for integrated spray-device systems. The Baden-Württemberg medical technology corridor concentrates nasal pump and valve component manufacturing for pharmaceutical partnerships.
India
CDSCO regulatory alignment with WHO prequalification standards positions contract manufacturers for Gavi procurement channel supply. PLI scheme incentives attract formulation investment for thermostable intranasal vaccines. The Hyderabad-Visakhapatnam pharmaceutical belt expands sterile spray filling capacity for export markets.
Japan
PMDA guidelines shape bioequivalence requirements for nasal spray generics and device reproducibility standards. METI industrial policy supports connected device development with dose-tracking sensors for adherence monitoring. The Kansai region maintains respiratory vaccine formulation expertise from legacy influenza immunization programs.
Switzerland
Swissmedic oversight ensures stringent quality standards for nasal delivery combination products entering European distribution. Precision manufacturing traditions attract device-integrated digital health partnerships. The Basel-Zürich corridor concentrates formulation science talent for mucoadhesive polymer development.
Intranasal Drug and Vaccine Delivery Market Key Industry Players
Capability concentration sits with formulation specialists possessing respiratory vaccine heritage; scale advantage sits with diversified pharmaceutical conglomerates with established commercial infrastructure. The market structure tiers between legacy respiratory developers with decades of mucosal immunization expertise and device-technology suppliers controlling critical pump and valve components. Three archetypes dominate: vertically integrated pharmaceutical-device hybrids, captive formulation specialists, and independent component manufacturers supplying multiple partners. Competitive moves center on exclusive supply agreement capture and regulatory certification bundling for combination product submissions.
Within the pharmaceutical-device hybrid tier, GSK plc and Teva Pharmaceutical Industries Ltd occupy positions leveraging established therapeutic franchises to anchor spray-based delivery expansion. AptarGroup, Inc. exemplifies the independent component archetype, supplying critical nasal pump and valve technology across multiple pharmaceutical partnerships without formulation ownership. These three entities represent the dominant competitive anchors: one anchored in respiratory vaccine expertise, one in central nervous system therapeutics, and one in precision device engineering.
| Leading Market Players |
|---|
| GSK plc |
| Teva Pharmaceutical Industries Ltd |
| AptarGroup, Inc. |
| UCB S.A. |
| Teleflex Incorporated |
| 3M |
| Bespak Limited |
| Optinose |
| Nemera |
| Others |
Cost & Logistics Intelligence
Single-source dependency for nasal pump and valve technology concentrates pricing power among specialized device manufacturers while forcing pharmaceutical partners into long-term offtake commitments that widen tier spreads between integrated and non-integrated supply configurations.
Pricing Analysis
Long-term offtake agreements dominate contract structures for nasal device components, with pharmaceutical partners locking supply to mitigate AptarGroup concentration risk. Price differentiation hinges on FDA combination product certification tier and after-sales calibration service bundling for electronic metering systems. Cost compression in mechanical pump tiers is intensifying because hospital procurement committees now mandate dose-verification features. Homecare segments show least price sensitivity due to insurance reimbursement coverage, while clinic immunization campaigns remain most cost-constrained.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electronics-integrated metering components. Manufacturing concentrates in Germany for precision device engineering, India for sterile spray filling under PLI incentives, and Switzerland for formulation science talent. Raw material dependencies include medical-grade silicone for valve membranes, lithium-ion cells for connected device power, and specialized polymers for mucoadhesive formulations. Distribution runs through pharmaceutical wholesaler networks with cold-chain requirements for liquid formulations and ambient logistics for thermostable powders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform licensing fragmentation across formulation specialists and device manufacturers creates entry niches as therapeutic applications expand beyond respiratory vaccines into CNS and mental health categories.
For Market Incumbents: Build regulatory certification moats through unified EMA MDR combination product submissions that bundle device and formulation approvals. Secure exclusive supply agreements with CDSCO-aligned Indian contract manufacturers to defend against Gavi procurement channel displacement. Invest in captive device capabilities to reduce AptarGroup dependency exposure.
For New Entrants and Emerging Players: Establish a beachhead in ketamine and esketamine intranasal delivery for treatment-resistant depression, where device-optimized competition remains sparse. Target homecare adherence monitoring through connected spray sensors with subscription revenue models. Partner with precision device engineering specialists in Baden-Württemberg rather than developing mechanical pump capabilities in-house.
For Investors and Strategic Acquirers: The market sits at a platform expansion phase that favors formulation specialists with respiratory vaccine heritage over diversified pharmaceutical conglomerates. Acquisition targets should demonstrate mucoadhesive polymer expertise and existing WHO prequalification pathway engagement. Monitor FDA guidance evolution on mucosal immunity correlates of protection as the signal for accelerated review channel access.
| Strategic Initiative | Industry Significance |
|---|---|
| Device-Integrated Digital Health Partnership | Enables adherence monitoring subscriptions for chronic CNS therapies through METI-supported sensor development. |
| CDSCO-WHO Prequalification Alignment | Positions Indian contract manufacturers for Gavi procurement channel access in tropical distribution markets. |
| EMA MDR Unified Submission Bundling | Compresses certification timelines for spray-device integrated systems through captive regulatory packaging. |
| Thermostable Powder Formulation Investment | Eliminates cold-chain dependency for resource-limited settings where refrigeration infrastructure is scarce. |
| Electronic Metering System Calibration Service | Creates recurring revenue attachment to hospital formulary specifications for dose-verification features. |
Research Approach
Cross-validation between primary interviews with formulation scientists, device engineering directors, hospital pharmacy procurement managers, and regulatory affairs specialists anchors the qualitative findings against secondary sources including FDA 510(k) filings, EMA combination product registration databases, ClinicalTrials.gov mucosal immunity endpoints, and WHO prequalification assessment reports. Bottom-up patient volume modeling by administration setting and top-down pharmaceutical revenue triangulation by therapeutic category were reconciled across the analysis window.
Calibration against historical CAGRs from respiratory vaccine and CNS therapeutic delivery markets informed the projection framework. Segmentation dimensions modeled include delivery method, end-user setting, formulation stability requirements, and regional regulatory cluster. Growth rates derived from patent filing velocity in nasal mucoadhesive polymers and hospital formulary adoption curves for single-use disposable units.
Sensitivities concentrate around FDA guidance finalization on mucosal immunity correlates of protection and EMA MDR enforcement consistency for combination product classifications. Forecasts reflect assumptions on CDSCO regulatory alignment timing and PLI scheme incentive continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Antimycotics Market
Pharmacology
Propranolol Drug Market
Pharmacology
Medication Adherence Market
Pharmacology
Aspirin API Market
Pharmacology
Apixaban Market
Pharmacology
Ibuprofen API Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Influenza Medication Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Cough Remedies Market