
 Assisted Walking Devices Market | 2026-2036
Assisted Walking Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Assisted Walking Devices Market Intelligence
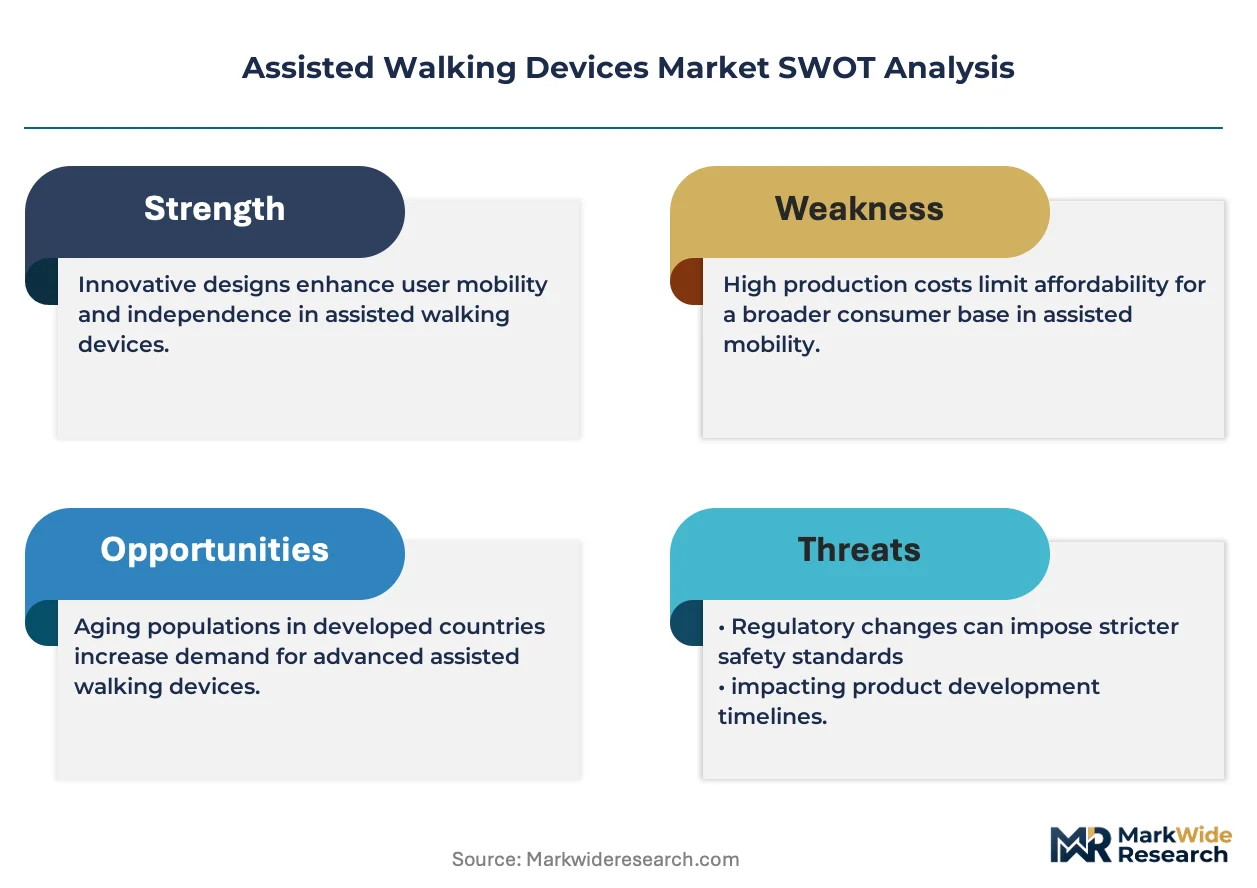
Carbon fiber is displacing conventional aluminum in premium rollator frames and is realigning cost structures across the assisted walking devices category. Ottobock SE & Co. KGaA leverages its German engineering base to dominate European rehabilitation channel supply. Drive DeVilbiss Healthcare, Inc. anchors North American distribution through broad retail and institutional coverage. Permobil AB specializes in powered mobility integration, extending its technology portfolio into smart-assisted walking platforms.
Assisted walking devices encompass canes, walkers, rollators, and crutches engineered with load-bearing capacities ranging from 250 to 500 pounds, fabricated through aluminum extrusion, carbon fiber layup, or polymer injection molding to provide ambulatory support and fall prevention. Rollators equipped with ergonomic hand grips and seated resting platforms command the largest revenue share due to their versatility across senior citizen and rehabilitation center end users. Smart technology segments incorporating sensor-based gait analysis represent the fastest-expanding category, though manual devices sustain the highest unit volumes in emerging markets where price sensitivity shapes procurement patterns.
The FDA classifies powered walkers and smart rollators as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation mandates CE marking with enhanced clinical evidence for active implantable accessories. ISO 11199 establishes international performance and safety benchmarks for walking aids, directly influencing product design cycles and market access timelines. Stakeholders must monitor evolving reimbursement codes from CMS and national health systems, as coverage determinations for smart and powered technologies will reshape competitive positioning and R&D allocation decisions.
Market Dynamics
Carbon fiber substitution in premium rollator frames is compressing aluminum's historical dominance while forcing manufacturers to recalibrate production economics across the assisted walking devices category. This materials transition intersects with tightening EU Medical Device Regulation clinical evidence requirements to reshape competitive positioning.
Growth Catalysts
- EU Medical Device Regulation:Rehabilitation centers in Germany are expanding procurement of powered mobility aids under enhanced clinical evidence mandates, accelerating channel consolidation toward certified suppliers.
- Lightweight aluminum alloys:METI standards in Japan are accelerating material substitution in rollator manufacturing, creating specification premiums for domestic producers.
- Sensor-based gait analysis:Smart technology segments incorporating real-time biomechanical feedback are capturing rehabilitation center procurement budgets previously allocated to manual devices.
Market Restraints
- Carbon fiber input volatility:Aerospace and automotive demand for prepreg composites constrains supply availability for medical device manufacturers, compressing margin structures in premium segments.
- 510(k) notification timelines:FDA Class II classification for powered walkers extends market access cycles, freezing capital deployment for smart rollator developers awaiting clearance.
- Manual device substitution ceiling:Emerging market price sensitivity sustains high-volume aluminum walker demand, limiting smart technology penetration in unit-dense geographies.
Strategic Opportunities
- Reimbursement code expansion:CMS coverage determinations for sensor-integrated mobility aids are creating new payment pathways for smart rollator categories previously excluded from durable medical equipment schedules.
- Rehabilitation channel integration:Post-acute care facilities in Japan are consolidating vendor relationships around full-lifecycle service providers, favoring suppliers with predictive maintenance capabilities.
- Carbon fiber-aluminum hybrid architectures:Layup-extrusion composite frames are opening mid-tier price positioning between economy aluminum and full carbon fiber premium products.
Industry Challenges
- ISO 11199 certification bottlenecks:International performance benchmark testing capacity constraints are extending product design cycles, delaying market entry for iterative frame innovations.
- Biomechanical engineering talent scarcity:Specialized expertise in sensor-orthotic integration is concentrating in German and Japanese industrial clusters, fragmenting R&D capabilities elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assisted Walking Devices Market |
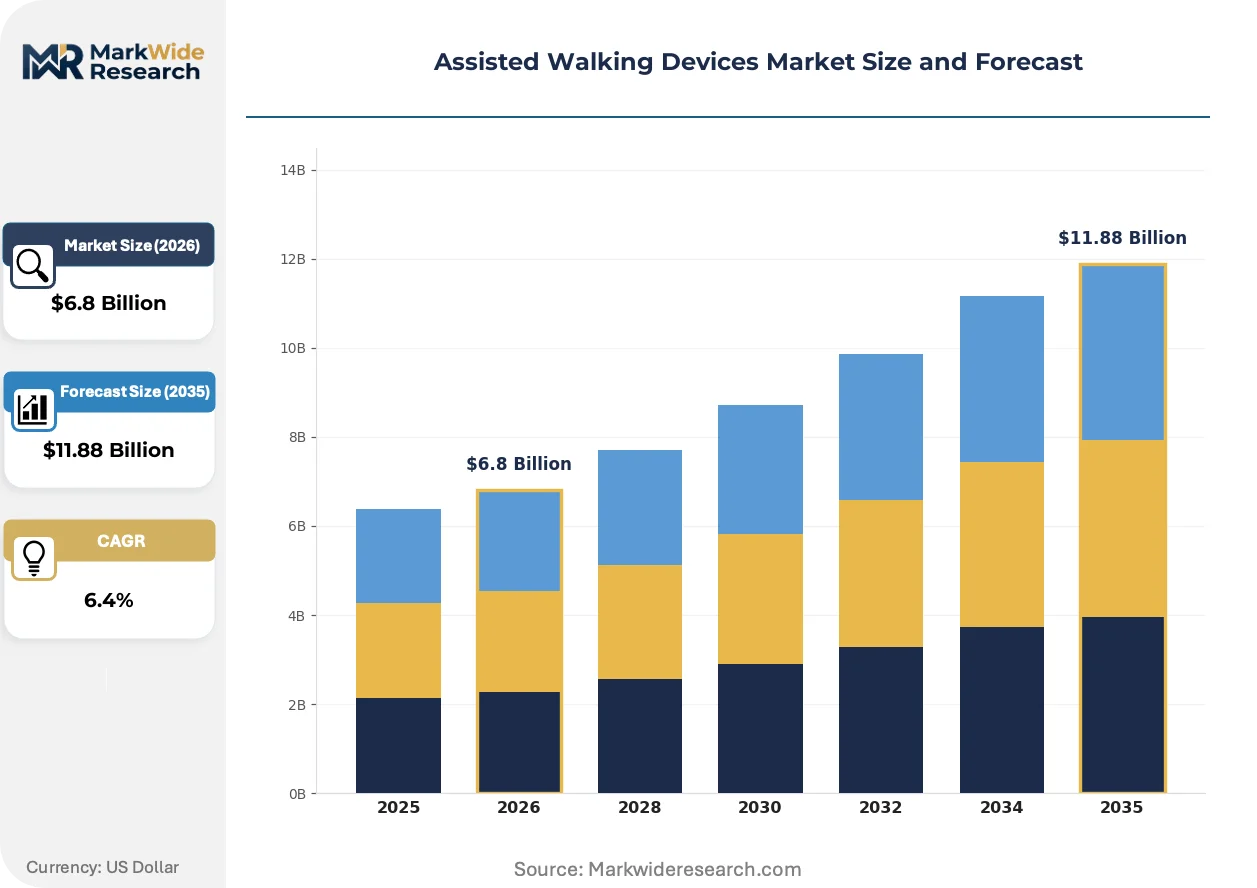
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canes, Walkers, Rollators, Crutches End User: Senior Citizens, Physically Disabled, Patients, Rehabilitation Centers Weight Capacity: Standard, Heavy-Duty, Lightweight, Adjustable Technology: Manual, Powered, Smart, Ergonomic |
| Companies Covered | GF Health Products, Inc., Nova Medical Products, Inc., Invacare Corporation, Ottobock SE & Co. KGaA, Pride Mobility Products Corporation, Drive DeVilbiss Healthcare, Inc., Medline Industries, L.P., Permobil AB, Sunrise Medical LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assisted Walking Devices Market Strategic Shifts & Innovations
Active materials substitution and regulatory recalibration are compressing traditional product lifecycles while opening new value capture mechanisms in assisted mobility. These shifts are redistributing competitive advantage toward vertically integrated manufacturers with captive materials science capabilities.
Carbon fiber layup manufacturing is absorbing premium rollator frame production as rehabilitation centers and high-ambulation seniors prioritize sub-five-kilogram transport weights. German engineering clusters are scaling automated fiber placement for medical device geometries, reducing unit costs that previously confined carbon fiber to elite athletic prosthetics. The structural consequence is absorbing margin from aluminum extruders while creating specification tiers that segment the market by load-bearing capacity rather than brand heritage.
EU Medical Device Regulation enhanced clinical evidence requirements are forcing powered walker developers to conduct prospective usability studies before CE marking, extending premarket timelines by twelve to eighteen months. This regulatory friction is compressing venture-funded startup participation while favoring established rehabilitation equipment manufacturers with captive clinical trial infrastructure. Active implantable accessory classifications are particularly affecting smart rollator segments with integrated electrical stimulation or automated braking functions.
Rehabilitation centers are consolidating procurement around full-service contracts that bundle device provision with predictive maintenance and outcome monitoring, displacing transactional equipment purchasing. This contractual evolution is compressing distributor margins while transferring value to manufacturers with IoT-enabled fleet management platforms. Germany's statutory health insurance system is piloting these bundled payment models in post-acute stroke rehabilitation, creating reference contracts that other European social insurers are evaluating for orthopedic recovery pathways.
Assisted Walking Devices Market Segmentation
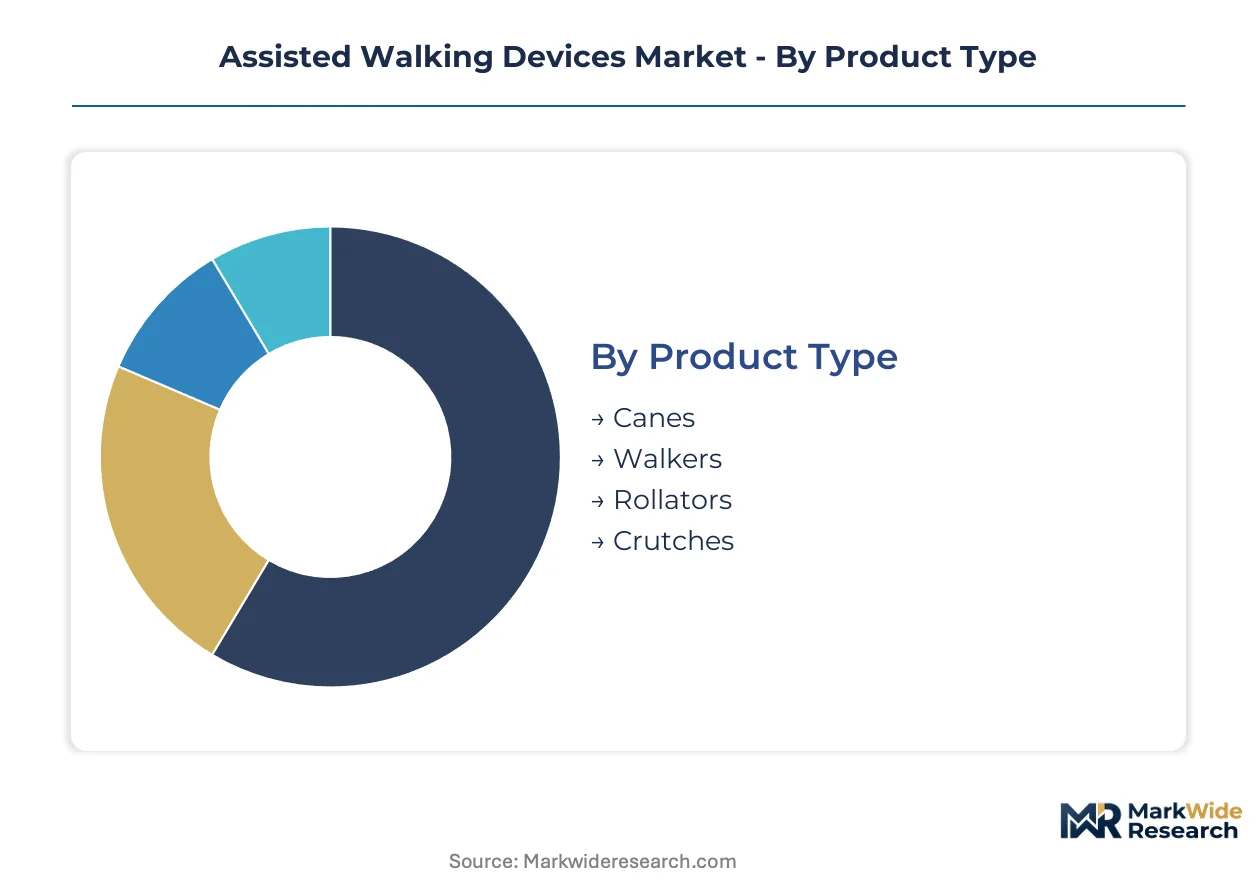
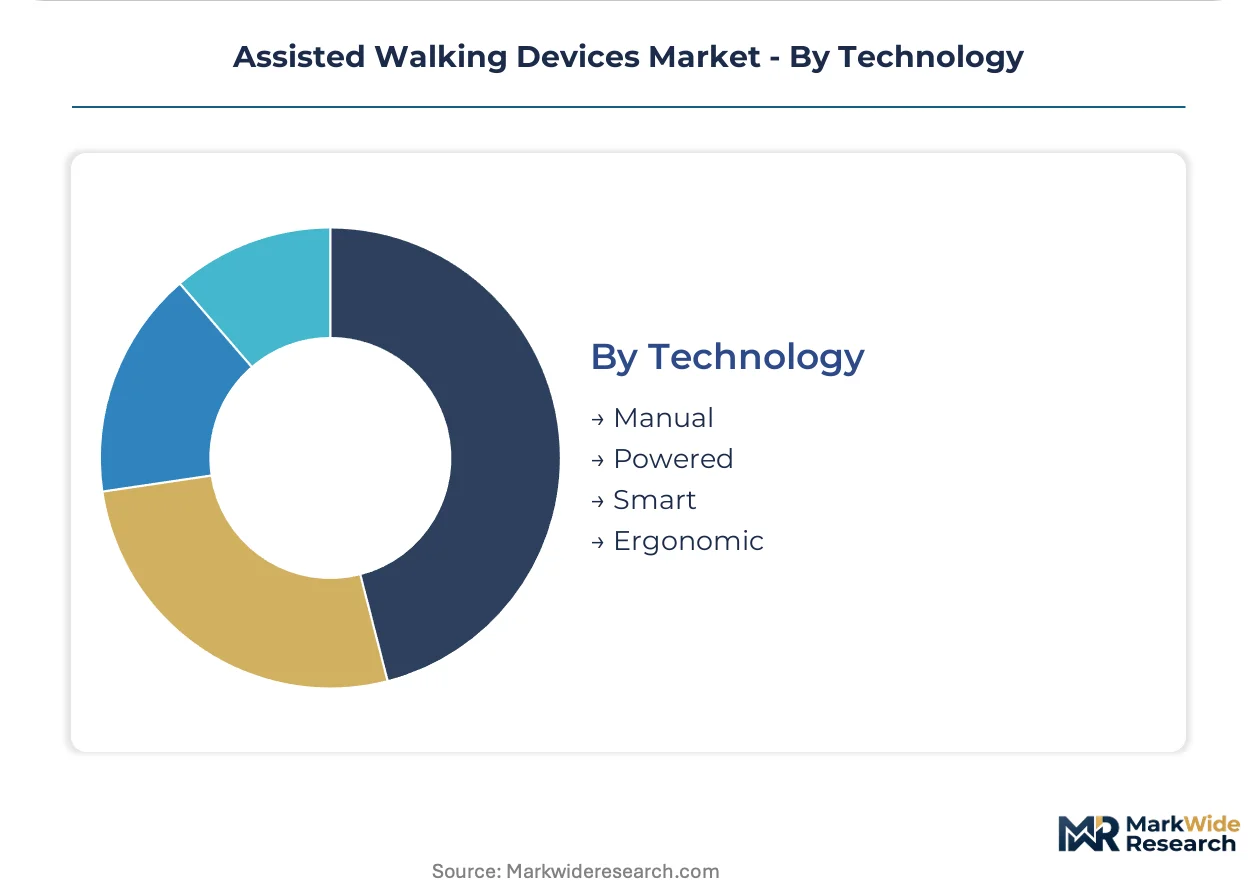
Segmentation in assisted walking devices reveals how procurement priorities diverge across clinical, retail, and institutional channels. Each dimension—product form, patient condition, structural specification, and intelligence level—carries distinct margin profiles and regulatory pathways that reshape supplier strategy.
Product Type:
Replacement cycles vary sharply across ambulatory aid categories, with durability expectations and insurance reimbursement schedules driving differential upgrade timing.
- Rollators:Four-wheeled frames with integrated seating and braking systems dominate rehabilitation center procurement budgets. German statutory health insurance pilots for post-acute stroke recovery are accelerating fleet refresh cycles in European institutional channels.
- Walkers:Standard and wheeled configurations sustain the highest unit volumes in emerging markets where aluminum extrusion economies keep acquisition costs accessible. METI lightweight alloy standards in Japan are compressing demand for conventional steel-frame variants.
- Canes:Single-point and quad-base designs serve transitional mobility needs with minimal reimbursement friction.
- Crutches:Axillary and forearm styles retain niche demand in acute injury recovery segments.
Volume placements concentrate in Walkers; the faster expansion belongs to Rollators.
End User:
Patient acuity and care setting determine specification intensity, with post-acute facilities demanding predictive maintenance capabilities that retail channels rarely require.
- Rehabilitation Centers:Bundled procurement contracts covering device provision, fleet monitoring, and outcome tracking are displacing transactional purchasing. EU Medical Device Regulation clinical evidence mandates favor suppliers with captive trial infrastructure.
- Senior Citizens:Direct-to-consumer demand prioritizes transport weight and aesthetic discretion over clinical functionality. Carbon fiber substitution in premium frames addresses sub-five-kilogram portability expectations.
- Physically Disabled:Long-term users drive customization requirements for seating geometry and grip adaptation.
- Patients:Acute-phase recovery creates episodic demand tied to orthopedic procedure volumes.
Procurement budgets cluster in Rehabilitation Centers; the steepest expansion trajectory is emerging in Senior Citizens.
Weight Capacity:
Load-bearing specification tiers segment manufacturing capabilities, with heavy-duty frames requiring distinct aluminum alloys and structural testing protocols.
- Heavy-Duty:Reinforced frames rated above 350 pounds command specification premiums in bariatric care segments. ISO 11199 testing capacity constraints extend design cycles for iterative frame innovations in this category.
- Lightweight:Sub-five-kilogram targets are absorbing carbon fiber layup manufacturing from aerospace suppliers. German engineering clusters are scaling automated fiber placement for medical device geometries.
- Standard:Conventional 250-300 pound ratings sustain volume production in economy segments.
- Adjustable:Modular capacity systems address variable patient needs across recovery timelines.
Production runs heaviest in Standard configurations; Adjustable specifications are climbing the fastest.
Technology:
Intelligence integration creates new reimbursement complexity, with sensor-embedded devices navigating distinct regulatory classifications from manual counterparts.
- Smart:Real-time gait analysis and automated braking functions trigger FDA Class II 510(k) notification requirements and EU MDR active implantable accessory classifications. CMS coverage determinations for sensor-integrated mobility aids are creating new payment pathways.
- Powered:Motorized propulsion and elevation systems serve high-ambulation-deficit populations. FDA premarket timelines extend market access cycles, freezing capital deployment for developers awaiting clearance.
- Manual:Unpowered mechanical designs sustain highest unit volumes where price sensitivity shapes procurement patterns.
- Ergonomic:Grip and posture optimization addresses repetitive strain prevention without electronic components.
Shipment volumes remain dominated by Manual devices; Smart categories are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates rehabilitation center procurement budgets for lightweight aluminum rollators, while Germany's statutory health insurance pilots reshape post-acute care device purchasing across Europe.
Germany
Rehabilitation centers in Berlin and Munich are expanding fleet procurement of powered mobility aids under EU Medical Device Regulation clinical evidence mandates. The country's national medical device regulator enforces enhanced premarket documentation requirements for active implantable accessories. Engineering clusters around Stuttgart are scaling automated fiber placement for carbon fiber layup manufacturing of premium rollator frames.
Japan
METI standards for lightweight aluminum alloys are accelerating material substitution in domestic rollator manufacturing, with senior citizens prioritizing sub-five-kilogram transport weights. The Pharmaceuticals and Medical Devices Agency classifies sensor-integrated mobility aids under distinct premarket notification pathways. Industrial concentrations in the Nagoya region are developing hybrid carbon fiber-aluminum architectures for mid-tier price positioning.
United States
CMS coverage determinations for smart rollator categories are creating new payment pathways for sensor-integrated mobility aids previously excluded from durable medical equipment schedules. The FDA classifies powered walkers as Class II medical devices requiring 510(k) premarket notification, extending market access cycles. Post-acute care facilities in Florida and Arizona are piloting bundled payment models that combine device provision with predictive maintenance capabilities.
China
Domestic manufacturers are capturing volume demand for standard aluminum walkers across hospital procurement channels and retail pharmacy networks. The National Medical Products Administration harmonizes technical review standards with ISO 11199 performance benchmarks for walking aids. Production clusters in the Yangtze River Delta are scaling polymer injection molding capacity for economy crutch and cane segments.
United Kingdom
NHS England procurement frameworks are consolidating vendor relationships around full-lifecycle service providers for rehabilitation equipment. The Medicines and Healthcare products Regulatory Agency enforces CE marking requirements under retained EU Medical Device Regulation provisions. Medical device engineering concentrations in the Cambridge area are developing IoT-enabled fleet management platforms for institutional channel contracts.
Assisted Walking Devices Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with rehabilitation channel consolidation favoring established suppliers while retail channels sustain fragmented competition. The vendor base organizes around three strategic archetypes: German-engineered rehabilitation equipment specialists, North American diversified healthcare conglomerates, and Asian volume manufacturers. Dominant competitive moves include backward integration into carbon fiber supply and geographic expansion through distributor acquisition.
Among diversified healthcare fabricators, Invacare Corporation and Drive DeVilbiss Healthcare, Inc. occupy positions anchored in North American institutional and retail distribution. Ottobock SE & Co. KGaA exemplifies the rehabilitation-focused engineering archetype with its German manufacturing base. Permobil AB represents the powered mobility specialization vector, extending technology portfolios into smart-assisted walking platforms.
| Leading Market Players |
|---|
| GF Health Products, Inc. |
| Nova Medical Products, Inc. |
| Invacare Corporation |
| Ottobock SE & Co. KGaA |
| Pride Mobility Products Corporation |
| Drive DeVilbiss Healthcare, Inc. |
| Medline Industries, L.P. |
| Permobil AB |
| Sunrise Medical LLC |
| Others |
Cost & Logistics Intelligence
Rehabilitation center procurement consolidation in Germany under EU Medical Device Regulation clinical evidence mandates is forcing suppliers to absorb certification costs while maintaining price accessibility across institutional tiers, compressing margin structures particularly in mid-market aluminum frame segments.
Pricing Analysis
Volume placements concentrate in economy aluminum walkers while margin capture clusters in carbon fiber premium rollators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in mid-tier hybrid architectures is intensifying because aerospace demand constrains carbon fiber prepreg availability. Emerging market institutional buyers exhibit highest price sensitivity; rehabilitation centers in Japan and Germany show lowest sensitivity due to bundled outcome-based contracts.
Supply Chain Analysis
Dual-sourcing qualification requirements from German statutory health insurers and Japanese GPOs mandate multi-supplier validation for critical structural components. Manufacturing concentrates in China for aluminum extrusion, Germany for automated fiber placement, and Japan for precision alloy processing. Raw material flows draw from Taiwanese carbon fiber suppliers, Australian bauxite refiners, and South Korean polymer compounders. Single-source vulnerability in aerospace-grade prepreg constrains medical device allocation. Distribution runs through rehabilitation equipment specialists in Europe, retail pharmacy networks in North America, and hospital procurement consortia in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber layup capacity scarcity in medical-grade specifications props pricing power for qualified suppliers, creating a supply-constrained market structure favoring incumbent consolidation over new capacity entry.
For Market Incumbents: To counter aerospace and automotive demand crowding out medical-grade carbon fiber supply, secure captive prepreg allocation through long-term offtake agreements with Taiwanese and Japanese fiber suppliers. Accelerate backward integration into automated fiber placement equipment to reduce dependency on Stuttgart-area engineering clusters for manufacturing scale-up. For New Entrants and Emerging Players: Direct-to-consumer digital channels for lightweight ergonomic canes offer the most penetrable entry vector, bypassing institutional procurement barriers that favor established rehabilitation equipment suppliers. Target senior citizen segments in North American and European markets through subscription-based mobility aid services with predictive replacement scheduling. For Investors and Strategic Acquirers: The window for entry favors mid-tier manufacturers with ISO 11199 certification infrastructure and existing carbon fiber-aluminum hybrid production capabilities. Monitor CMS coverage determination timelines for sensor-integrated mobility aids as the inflection signal for smart rollator category viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence mandates compress venture-funded startup participation in powered walker segments. |
| Hospital System Partnership | Bundled procurement contracts in German post-acute stroke rehabilitation transfer value to IoT-enabled fleet managers. |
| Backward Integration | Captive carbon fiber supply insulates margin structures from aerospace demand volatility in premium rollator production. |
| Reimbursement Strategy | CMS coverage determinations for sensor-integrated devices reshape competitive positioning in North American institutional channels. |
| Software Companion Development | Predictive maintenance platforms capture rehabilitation center procurement budgets previously allocated to transactional equipment purchasing. |
Research Approach
Multi-period observation of carbon fiber input pricing, FDA 510(k) clearance timelines, and rehabilitation center fleet refresh cycles anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital GPO contracts managers, rehabilitation center procurement directors, and carbon fiber composite suppliers. Secondary validation drew from FDA 510(k) database filings, EU MDR notified body documentation, CMS Medicare durable medical equipment fee schedules, and ISO 11199 certification records. Bottom-up unit shipment modeling triangulated against top-down addressable market sizing across product type and end-user segments.
Input-output matrices mapped carbon fiber layup capacity allocation, aluminum alloy specification premiums, and regulatory clearance pathway durations to volume and value projections across the analysis window. Segmentation dimensions modeled include product form, patient acuity level, structural load-bearing tier, and intelligence integration level. CAGRs were derived from regression analysis of historical procurement patterns against demographic and reimbursement policy trajectories. Forecast inputs incorporated METI lightweight alloy standard adoption curves and EU MDR transition completion timelines.
The model holds under stable carbon fiber supply allocation to medical device applications; deviation in aerospace or automotive demand spikes would shift premium rollator availability and pricing trajectories. A model refresh is warranted upon material change in CMS coverage determination outcomes for sensor-integrated mobility aids.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
Cannula Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
North America Pen Needles Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Transcranial Magnetic Stimulation System Market